
 Coherent Radar Market | 2026-2036
Coherent Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Coherent Radar Market Analysis
The performance gap between premium military-grade coherent radar and commodity commercial sensors is decoupling along signal-processing sophistication and thermal management benchmarks. Raytheon Technologies leverages classified GaN transmitter arrays to sustain margins in next-generation fire-control radars. Lockheed Martin anchors the US Navy's Aegis combat system refresh with digital beamforming upgrades. Northrop Grumman competes through integrated sensor-to-shooter architectures that fuse coherent radar with electronic warfare suites.
Coherent radar employs phase-stable transmit-receive chains to detect Doppler-shifted returns from moving targets against clutter backgrounds, typically operating in X-band through Ku-band with pulse compression ratios exceeding 1000:1 for fine range resolution. Aerospace and maritime applications dominate procurement volume, with synthetic aperture radar variants capturing the fastest expansion as satellite-based Earth observation constellations multiply. Defense end users concentrate spending on fully polarimetric processors that enable automatic target recognition, while civil aviation and environmental monitoring segments gravitate toward cost-optimized frequency modulated continuous wave implementations.
FAA certification requirements for airborne weather radar and ITAR export controls administered by the US State Department constrain technology transfer and shape competitive boundaries. EASA harmonizes with FAA on minimum performance standards for coherent radar altimeters and wind shear detection systems across European airspace. Stakeholders must monitor convergence between military spectrum allocation policies and commercial 5G mid-band expansion, as interference disputes reshape operational frequency availability for coastal and urban radar deployments.
Market Dynamics
Digital beamforming architectures are compressing procurement cycles for next-generation surveillance platforms, forcing incumbent suppliers to reconfigure transmitter-receive chains around software-defined processing cores rather than analog hardware stacks.
Growth Catalysts
- GaN-on-SiC transmitter arrays:Wide-bandgap semiconductors enable higher power density at X-band through Ku-band frequencies, reducing thermal management overhead in compact airborne installations.
- FAA certification mandates:Updated minimum performance standards for airborne weather radar and wind shear detection systems are accelerating fleet retrofit programs across US commercial aviation operators.
- Synthetic aperture radar constellations:Satellite-based Earth observation platforms are expanding procurement volume for lightweight, high-resolution coherent radar payloads in low-Earth orbit deployments.
Market Restraints
- ITAR export controls:US State Department licensing requirements constrain technology transfer to non-allied nations, fragmenting addressable markets for dual-use coherent radar components.
- Gallium supply concentration:China dominates raw gallium refining capacity, creating input cost volatility for GaN transmitter fabrication.
- Legacy analog integration friction:Existing fire-control and air-traffic infrastructure operates on proprietary waveforms, complicating phased upgrade paths.
Strategic Opportunities
- India defense modernization:Indigenous radar production initiatives under the PLI scheme create openings for technology partnerships in coastal surveillance and airborne early warning platforms.
- 5G mid-band convergence:Shared spectrum allocation frameworks between military radar and commercial telecommunications present frequency coexistence engineering contracts.
- Fully polarimetric processors:Automatic target recognition capabilities for defense end users remain underdeployed in maritime patrol and ground-based air defense segments.
Industry Challenges
- Digital signal processing talent scarcity:Phased-array calibration and adaptive beamforming algorithm development requires specialized expertise concentrated in defense contractor ecosystems.
- EASA-FAA harmonization timelines:Divergent certification pathways for coherent radar altimeters create duplicate testing overhead for multinational avionics suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coherent Radar Market |
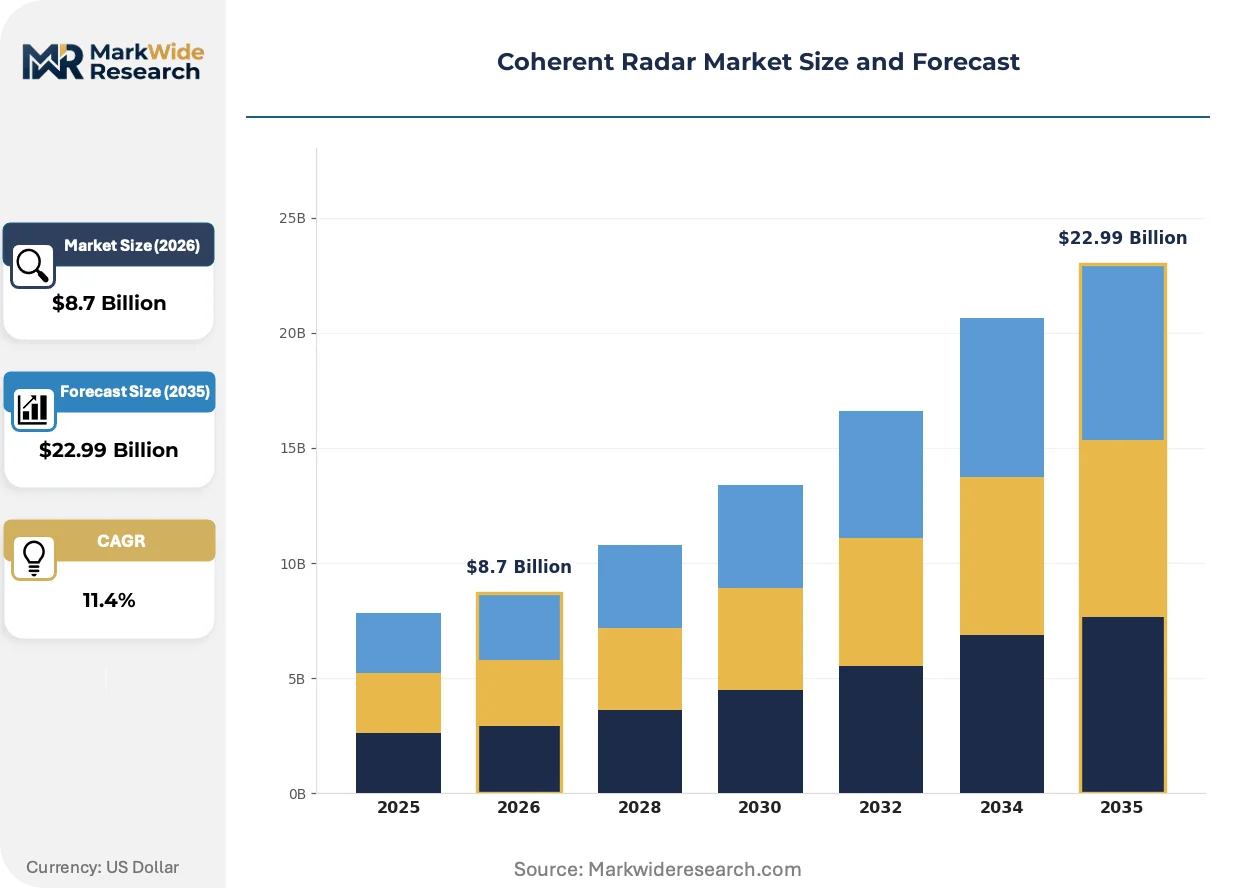
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Maritime, Automotive, Environmental Monitoring Technology: Frequency Modulated Continuous Wave, Pulse-Doppler, Synthetic Aperture Radar, Digital Beamforming End User: Defense, Civil Aviation, Research Institutions, Oil & Gas Component: Sensors, Antennas, Processors, Transmitters |
| Companies Covered | Raytheon Technologies, Lockheed Martin, Northrop Grumman, Thales Group, Leonardo S.p.A., BAE Systems, Hensoldt AG, Saab AB, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coherent Radar Market Emerging Trajectories
Software-defined radio architectures are collapsing the boundary between radar sensing and electronic warfare functions, enabling multifunction apertures that switch between detection, tracking, and jamming modes through firmware updates rather than hardware replacement.
Machine learning-based clutter suppression algorithms are automating target extraction in dense urban and littoral environments, reducing operator workload in ground-based air defense and maritime surveillance installations. Military procurement offices in NATO member states are embedding these capabilities into next-generation fire-control radar specifications. The shift is compressing development timelines for automatic target recognition systems previously reliant on rule-based processing chains.
EASA harmonization with FAA minimum performance standards for coherent radar altimeters is reshaping avionics supplier qualification pathways across European airspace. Dual-certification requirements are elevating compliance costs for mid-tier component manufacturers while consolidating procurement relationships around established defense-electronics houses. Regional airlines operating cross-border routes face compressed retrofit deadlines to maintain operational access.
Defense procurement offices are consolidating sensor contracts under integrated sensor-to-shooter architectures that bundle coherent radar with electronic warfare and communications functions. Prime contractors are responding with platform-agnostic payload designs that reduce per-unit customization overhead. The United States Navy's Aegis combat system refresh exemplifies this pattern, embedding digital beamforming upgrades within broader combat management system modernization programs.
Coherent Radar Market Segmentation
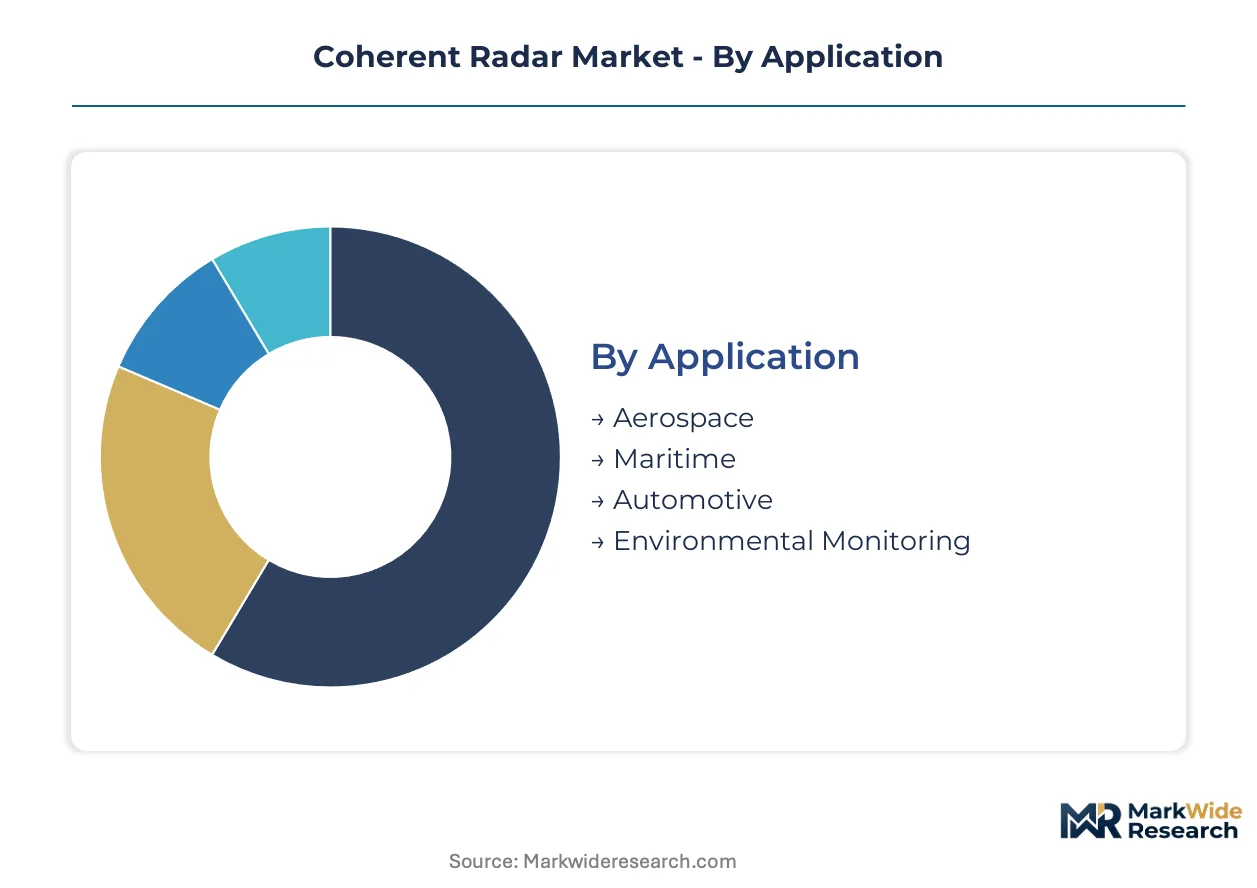
Coherent radar procurement fragments across mission profiles, hardware architectures, and institutional buyers. Each dimension carries distinct margin structures, certification burdens, and technology refresh cycles that reshape supplier positioning.
Application:
Volume concentrates in aerospace and maritime platforms, while environmental monitoring commands premium pricing for satellite-grade payloads.
- Aerospace:Airborne weather radar, fire-control systems, and synthetic aperture reconnaissance pods dominate procurement volume. FAA certification mandates for wind shear detection and terrain avoidance drive fleet retrofit cycles across US commercial carriers and allied military operators.
- Maritime:Naval fire-control radars and coastal surveillance arrays anchor defense procurement in the United States, United Kingdom, and Japan. Surface vessel installations prioritize GaN transmitter density for extended range against low-observable threats.
- Automotive:Frequency modulated continuous wave implementations for adaptive cruise control and automated emergency braking face cost pressure from lidar alternatives. Tier-1 suppliers in Germany and South Korea concentrate R&D on 77-81 GHz compact arrays.
- Environmental Monitoring:Satellite-based synthetic aperture radar constellations for Earth observation capture the steepest expansion trajectory. European Space Agency and commercial operators in Finland and Germany drive demand for lightweight, high-resolution polarimetric payloads.
Today's leader: Aerospace. Tomorrow's challenger: Environmental Monitoring.
Technology:
Digital architectures displace analog stacks fastest where software-defined updates reduce platform obsolescence.
- Digital Beamforming:Software-defined phase control enables multifunction apertures switching between detection, tracking, and electronic attack modes through firmware. US Navy Aegis combat system refresh embeds this architecture within broader combat management modernization.
- Synthetic Aperture Radar:Satellite and unmanned aerial vehicle payloads demand compact, high-resolution implementations with pulse compression ratios exceeding 1000:1. Low-Earth orbit constellation deployment in Finland, Germany, and the United States accelerates procurement volume.
- Pulse-Doppler:Legacy fire-control and air-traffic infrastructure relies on proprietary waveforms, complicating upgrade paths. Defense operators in NATO member states sustain demand for fully polarimetric variants enabling automatic target recognition.
- Frequency Modulated Continuous Wave:Cost-optimized automotive and short-range environmental monitoring implementations sacrifice range resolution for hardware simplicity. Civil aviation weather radar retrofits increasingly adopt hybrid architectures blending FMCW front-ends with digital back-end processing.
Digital Beamforming commands the highest unit margins; Synthetic Aperture Radar expands most quickly.
End User:
Defense procurement anchors premium pricing, while civil aviation certification requirements fragment supplier qualification pathways.
- Defense:Fully polarimetric processors for automatic target recognition and integrated sensor-to-shooter architectures concentrate spending in the United States, United Kingdom, and allied NATO programs. ITAR export controls constrain technology transfer and fragment addressable markets for dual-use components.
- Civil Aviation:FAA and EASA harmonization on minimum performance standards for weather radar, altimeters, and wind shear detection compresses retrofit timelines. Regional airlines operating cross-border routes face compliance cost elevation and procurement consolidation around established avionics houses.
- Research Institutions:Academic and government laboratory procurement prioritizes experimental polarimetric and interferometric capabilities over operational reliability. Funding concentration in Germany, Japan, and the United States supports niche transmitter and processor development.
- Oil & Gas:Offshore platform surveillance and pipeline monitoring deploy compact coherent radar for all-weather perimeter security. North Sea operators and Gulf of Mexico installations drive modest volume with severe cost constraints relative to defense specifications.
Defense sustains margin leadership; Civil Aviation offers volume scaling through fleet standardization mandates.
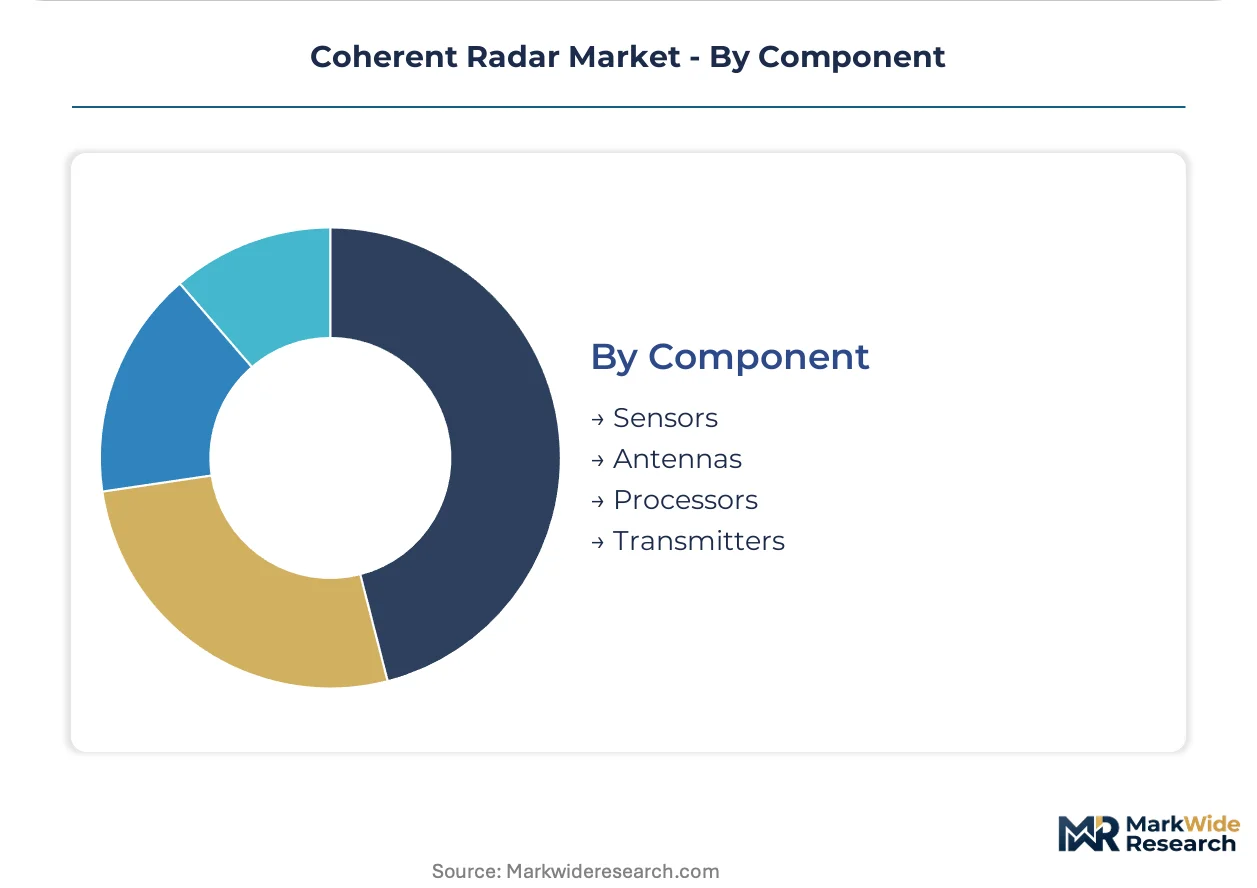
Component:
GaN transmitter arrays and adaptive processors capture value migration from legacy analog hardware.
- Transmitters:Gallium nitride on silicon carbide wide-bandgap semiconductors enable higher power density at X-band through Ku-band frequencies. China's dominance in raw gallium refining creates input cost volatility constraining fabrication economics.
- Processors:Field-programmable gate array and application-specific integrated circuit implementations for adaptive beamforming and machine learning-based clutter suppression concentrate specialized expertise. Talent scarcity in phased-array calibration algorithms limits supplier expansion.
- Antennas:Active electronically scanned array architectures with transmit-receive module integration dominate defense and high-end civil applications. Mechanical steering persists in cost-constrained environmental monitoring and research installations.
- Sensors:Compact coherent receiver chains for unmanned platforms and satellite payloads prioritize SWaP-C optimization. Dual-use sensor exports face ITAR licensing friction fragmenting non-allied market access.
Transmitters and Processors capture value migration; Antennas face commoditization pressure in commercial tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics engineering talent concentrates in Massachusetts, Maryland, and California, anchoring US coherent radar development. European clusters in France and Germany sustain sovereign production capabilities. Asian expansion centers on indigenous programs in China and India.
United States
US Navy Aegis combat system refresh and FAA certification mandates for airborne weather radar drive procurement volume. ITAR export controls administered by the State Department constrain technology transfer to non-allied nations. Massachusetts and Maryland host prime contractor engineering campuses developing digital beamforming architectures.
China
Indigenous military modernization and satellite-based Earth observation constellations expand addressable demand. MIIT spectrum allocation policies and dual carbon goals shape transmitter efficiency requirements. Yangtze River Delta manufacturing bases concentrate GaN fabrication capacity for domestic radar programs.
Germany
EASA harmonization with FAA standards for coherent radar altimeters compresses avionics supplier qualification timelines. Hensoldt AG and regional defense electronics houses anchor sovereign production in Baden-Württemberg. Munich and Ulm clusters specialize in active electronically scanned array module development.
India
Coastal surveillance and airborne early warning platform modernization accelerates under PLI scheme incentives. DGFT import substitution policies favor domestic transmitter and processor assembly. Bengaluru and Hyderabad host DRDO laboratories and private sector partnerships for phased-array calibration.
United Kingdom
Integrated sensor-to-shooter architectures for naval fire-control sustain procurement spending. Ministry of Defence sovereign radar initiatives protect classified waveform development. BAE Systems operations in Lancashire and Bristol anchor maritime surveillance payload production.
Coherent Radar Market Vendor Landscape
Capital-heavy defense primes compete with asset-light subsystem specialists across coherent radar procurement. The vendor base consolidates around vertically integrated platform providers and component-focused technology houses. Three archetypes dominate: full-system integrators with classified clearances, GaN transmitter foundries with wide-bandgap expertise, and software-defined processing specialists. Competitive dynamics center on M&A consolidation of sensor-to-shooter capabilities and strategic partnerships for satellite payload miniaturization.
Within the full-system integrator tier, Raytheon Technologies, Lockheed Martin, and Northrop Grumman exemplify prime contractor positioning. These US-based entities occupy the classified program anchor role through digital beamforming and fire-control system integration. European counterparts Thales Group and Leonardo S.p.A. represent sovereign production alternatives within NATO procurement frameworks.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Lockheed Martin |
| Northrop Grumman |
| Thales Group |
| Leonardo S.p.A. |
| BAE Systems |
| Hensoldt AG |
| Saab AB |
| L3Harris Technologies |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate costs cascade through coherent radar manufacturing tiers, with China's dominance in raw gallium refining concentrating upstream pricing power before downstream differentiation across defense-certified and commercial-grade transmitter arrays.
Pricing Analysis
Bundled platform-integration contracts versus unbundled component supply splits procurement economics across the coherent radar market. Three-tier pricing structure across ITAR-restricted defense systems, dual-use certified platforms, and commodity commercial sensors reflects certification grade and waveform classification levels. Pricing pressure stems from gallium supply volatility as China controls raw material refining capacity. Civil aviation operators exhibit highest price sensitivity due to fleet-wide retrofit mandates, while defense primes absorb premium pricing for classified GaN transmitter arrays.
Supply Chain Analysis
Direct-to-OEM channels handle prime contractor demand for Aegis combat system and satellite payload programs, while distributor networks serve mid-tier avionics retrofit markets. Gallium refining concentrates in China, GaN-on-SiC fabrication clusters in the United States and Germany, and final transmitter assembly anchors in Massachusetts and Maryland facilities. Raw material dependencies span high-purity gallium, silicon carbide substrates, and specialized thermal management ceramics. Single-source vulnerability in Chinese gallium supply creates procurement risk exposure. Distribution runs through defense primes with classified clearances for ITAR-controlled components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coherent radar market functions as a geographic-arbitrage play where ITAR export restrictions in the United States create pricing premiums unavailable to non-allied competitors, while China's gallium refining dominance offers input cost advantages for domestic radar programs.
For Market Incumbents: Anticipate margin compression from software-defined radio architectures collapsing hardware refresh cycles. Defend position by deepening classified program relationships through digital beamforming integration and securing captive gallium supply arrangements outside Chinese refining channels. ITAR compliance infrastructure represents a moat against emerging GaN foundry competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in airborne weather radar retrofits offers white-space entry for FPGA-based adaptive processors targeting regional airline fleets. Target environmental monitoring satellite payloads as the most penetrable segment, where lightweight SAR implementations face fewer certification barriers than defense or civil aviation tiers. Pursue EASA-FAA dual-certification partnerships with established avionics houses as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined processing capabilities fragment across subsystem specialists lacking platform-integration scale. Long-term viability favors vertically integrated primes with classified clearances and sovereign production relationships in NATO procurement frameworks. Monitor gallium supply diversification initiatives as the critical inflection signal for input cost stability.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Transmitter Capacity Expansion | Secures supply independence from Chinese gallium refining concentration for defense-rated arrays. |
| Digital Beamforming Platform Integration | Embeds Raytheon and Lockheed Martin architectures within US Navy Aegis modernization programs. |
| EASA-FAA Dual Certification Investment | Unlocks cross-border avionics procurement for Hensoldt AG and European radar altimeter suppliers. |
| SAR Satellite Payload Partnership | Positions subsystem houses for Finnish and German Earth observation constellation deployments. |
| India PLI Scheme Localization | Channels technology transfer into Bengaluru and Hyderabad coastal surveillance production. |
Methodological Framework
Multiple input streams — defense procurement database tracking, semiconductor supply chain analysis, and regulatory filing review — were reconciled to construct market estimates. Primary interviews with radar systems engineers, defense procurement officers, GaN foundry operations managers, and FAA certification specialists informed demand-side validation. Secondary sources included ITAR licensing records, EASA airworthiness directives, SEC 10-K filings from prime contractors, and customs trade data for gallium and silicon carbide substrate flows. Bottom-up transmitter array shipment analysis and top-down defense budget allocation triangulation anchored volume estimates.
Data-stream reconciliation across component-level bill-of-materials and platform-level contract awards generated consistent value estimates across the analysis window. Segmentation modeling incorporated application dimension (aerospace, maritime, environmental monitoring), technology architecture (digital beamforming, SAR, pulse-Doppler), end-user category (defense, civil aviation, research), and component type (transmitters, processors, antennas). CAGRs derived from defense procurement cycle analysis and satellite constellation deployment schedules. Industry-specific inputs included FAA mandate implementation timelines and ITAR license approval velocity.
Caveats apply where gallium export restrictions, spectrum reallocation disputes, or defense budget reprioritization could materially shift the outlook. Forecasts embed assumptions regarding EASA-FAA harmonization completion and sustained NATO procurement commitments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Spain Satellite Communications Market