
 Manpack Military Antennas Market | 2026-2036
Manpack Military Antennas Market Size, Share, and Industry Trends Forecast 2026-2036
Manpack Military Antennas Market Insights
North American defense primes is consolidating production of manpack antenna systems around software-defined radio compatibility. RTX leverages its embedded communications portfolio to anchor military waveform integration across multiple branch programs. L3Harris Technologies sustains dominance in tactical radio-adjacent antenna architectures through captive RF engineering. BAE Systems differentiates via hardened manufacturing for airborne and ground-mobile crossover applications.
Manpack military antennas are portable, collapsible RF radiators engineered for dismounted soldier use across VHF through C-band spectra, typically employing whip, blade, or mesh-conformal elements with rapid field-deployable mounting. These systems enable tactical voice, data, and position-location networks in contested electromagnetic environments where fixed infrastructure is absent or denied. Foldable and telescopic variants occupy the highest volume tiers due to mechanical simplicity and compatibility with legacy radio mounts. Frequency-band segmentation shows HF and VHF retaining criticality for beyond-line-of-sight propagation in mountainous or urban terrain, while L-band and S-band configurations grow fastest through satellite communications backhaul integration. Application-level demand pools concentrate in tactical communication and signal intelligence, where antenna bandwidth agility directly determines mission set flexibility.
FCC equipment authorization and MIL-STD-810 environmental qualification govern U.S. market access, while NATO STANAG standards harmonize interoperability requirements across allied procurement. The U.S. Army's PM Tactical Network enforces HMS waveform conformance, effectively filtering vendor participation through certified radio platform integration. Stakeholders must monitor software-defined radio roadmap evolution and emerging low-probability-of-intercept waveform requirements to preserve antenna design relevance.
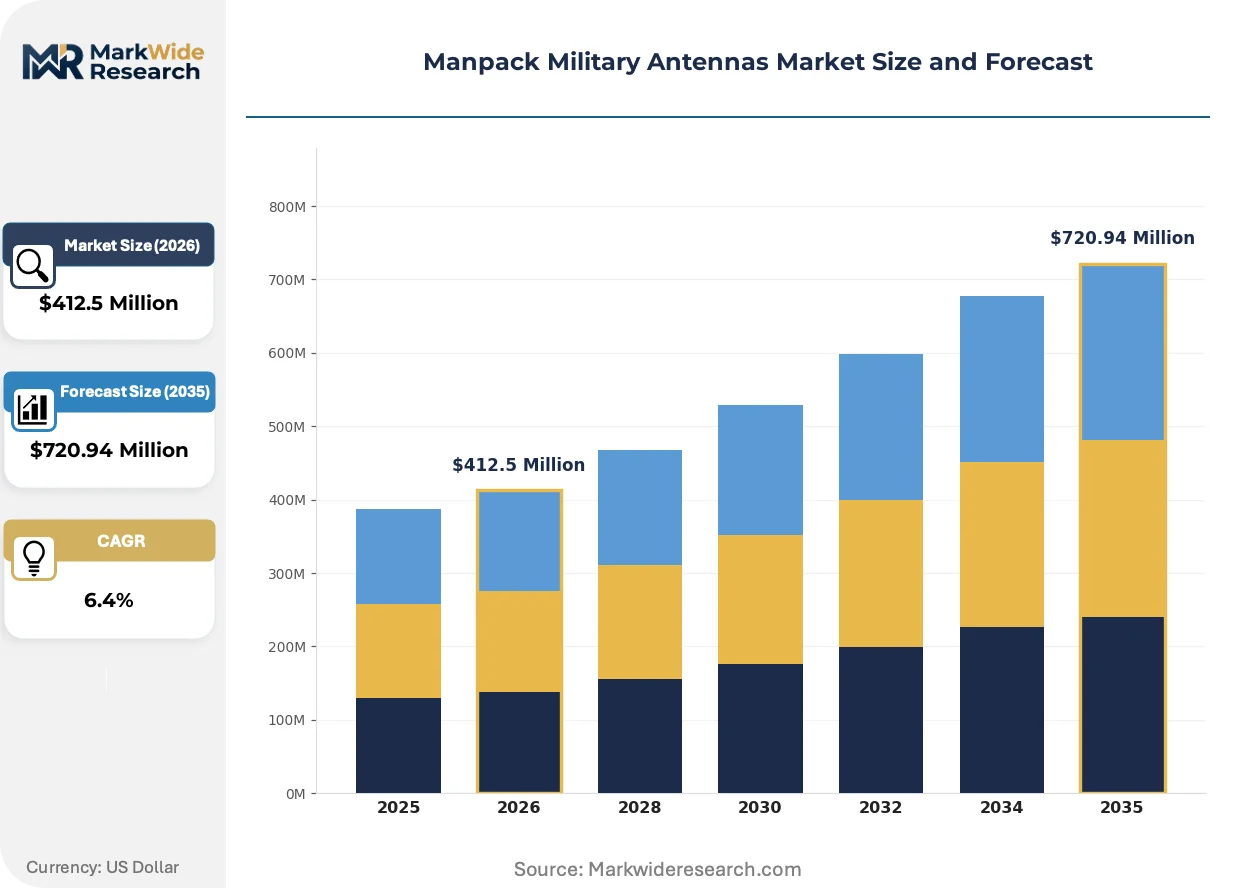
Market Dynamics
Software-defined radio architecture migration is compressing antenna design cycles as defense procurement mandates multi-waveform interoperability across dismounted soldier platforms, forcing vendors to reengineer RF front-ends for programmable spectrum agility rather than fixed-band optimization.
Growth Catalysts
- JTRS Waveform Certification:The U.S. Army's HMS program mandates certified radio platform integration, filtering vendor participation and creating qualified supplier tiers that lock in sustained procurement volumes.
- Satellite Communications Backhaul:L-band and S-band configurations are capturing expanded mission sets through integration with tactical satellite terminals, enabling beyond-line-of-sight data exfiltration in denied environments.
- NATO STANAG Harmonization:Allied procurement alignment across member states is standardizing antenna interface specifications, reducing non-recurring engineering costs for cross-border defense contracts.
Market Restraints
- Raw Material Concentration:High-performance copper-nickel alloys and specialized RF substrates concentrate sourcing among limited specialty metal suppliers, exposing production schedules to geopolitical supply disruptions.
- MIL-STD-810 Qualification Burden:Extended environmental testing timelines for shock, vibration, and temperature extremes stretch product development cycles and defer revenue recognition.
- Fixed Infrastructure Preference:Budget allocation inertia favors established base station and vehicle-mounted systems over dismounted soldier gear in fiscally constrained defense environments.
Strategic Opportunities
- Mesh-Conformal Form Factors:Integration of flexible printed circuit antenna elements with soldier body armor is opening embedded RF channels that eliminate external protrusion signatures.
- Low-Probability-of-Intercept Waveforms:Emerging spread-spectrum and frequency-hopping protocols are demanding ultra-wideband antenna architectures with instantaneous bandwidth switching.
- Indo-Pacific Theater Expansion:Island-chain contingency planning across allied forces is generating demand for lightweight, salt-corrosion-resistant antenna systems optimized for maritime jungle environments.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized electromagnetic simulation and antenna measurement expertise concentrates among aging practitioner cohorts with limited pipeline replenishment through university programs.
- Legacy Radio Backward Compatibility:Fielded inventory of single-band tactical radios requires antenna designs supporting obsolete connector standards and impedance matching, complicating product portfolio rationalization.
- Field Repair Documentation Gaps:Theater-level maintenance units lack detailed antenna fault isolation procedures, driving premature replacement costs and degrading operational availability metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manpack Military Antennas Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable Antennas, Telescopic Antennas, Wire Antennas, Panel Antennas, Loop Antennas Frequency Band: VHF, UHF, HF, L Band, S Band, C Band Application: Tactical Communication, Signal Intelligence, Electronic Warfare, Navigation Support, Field Surveillance End User Segment: Infantry Units, Special Forces, Command Centers, Reconnaissance Teams, Border Security |
| Companies Covered | RTX, Honeywell International, L3Harris Technologies, Leonardo, General Dynamics, BAE Systems, Thales, Southwest Antennas, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manpack Military Antennas Market Trends and Innovations
Active electronically steered elements and additive manufacturing techniques are redefining mechanical antenna construction, collapsing trade-offs between bandwidth coverage and physical durability that historically constrained dismounted soldier equipment design.
Metamaterial-inspired radiating structures is absorbing conventional quarter-wave whip geometries in next-generation manpack configurations. These engineered surfaces enable electrically small antennas with multi-octave bandwidth performance. Special operations units are field-testing folded-mesh conformal variants that maintain gain patterns across VHF through L-band without mechanical redeployment. The technology is absorbing legacy blade antenna market share by eliminating telescoping failure modes in contested insertion scenarios.
EU defense procurement directives under the European Defence Fund are mandating cross-border industrial participation and technology transfer requirements for collaborative capability programs. These rules are fragmenting national supplier preferences that historically favored domestic antenna manufacturers. Medium-tier European defense electronics firms are responding by forming consortium bids that pool RF engineering resources across multiple member states to meet collective contracting thresholds.
Consolidated program office buying is displacing unit-level discretionary procurement across major defense forces. The U.S. Army's PM Tactical Network now centrally manages antenna fielding decisions that previously resided at brigade or battalion echelons. This concentration is compressing vendor sales cycles and elevating importance of sole-source justification documentation. Similar centralization patterns are visible in United Kingdom and Australian tactical communications modernization programs.
Manpack Military Antennas Market Segmentation
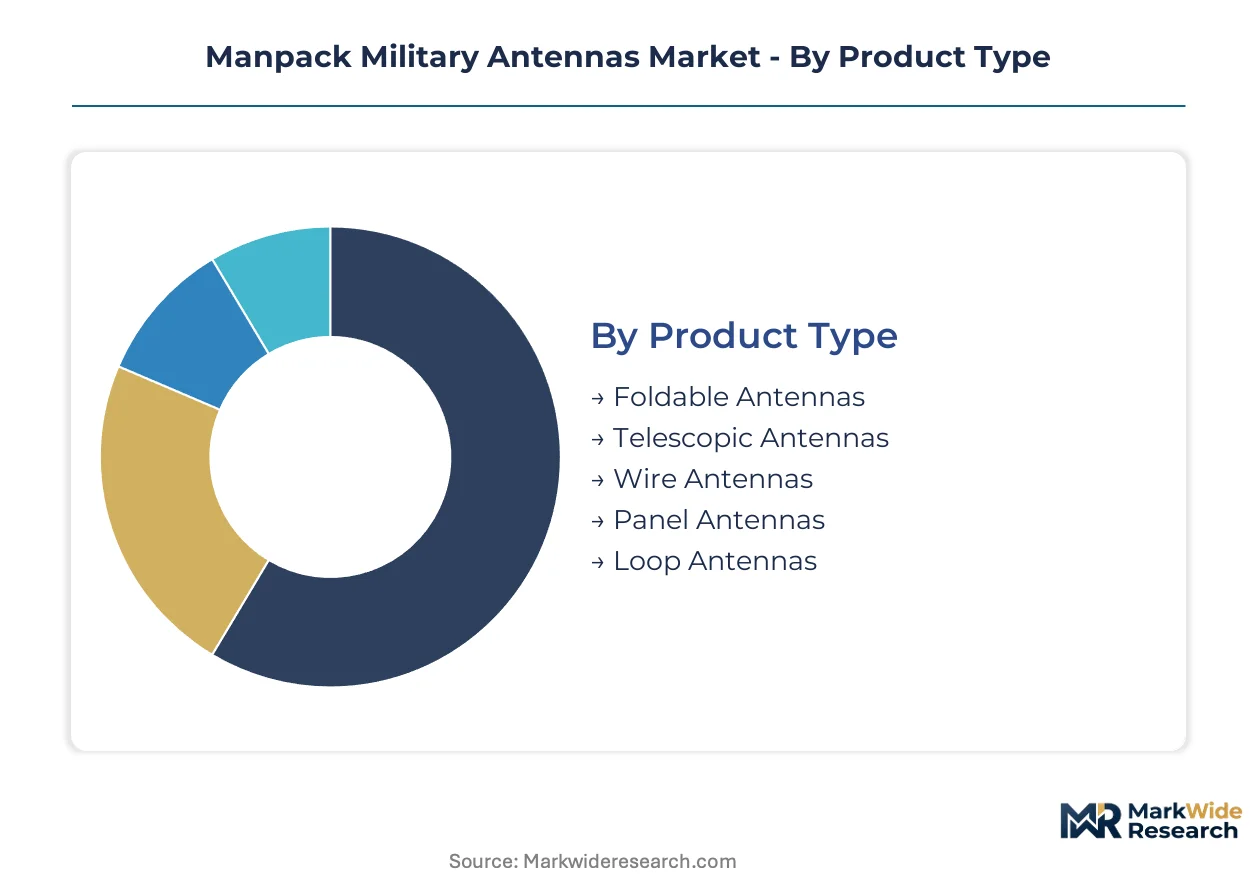
Manpack military antenna procurement divides across four critical dimensions that shape vendor positioning and qualification requirements. Each segmentation axis imposes distinct certification burdens, performance specifications, and customer access pathways that determine competitive viability in defense contracting.
Product Type:
FCC equipment authorization and MIL-STD-810 environmental qualification requirements vary sharply by mechanical construction, with collapsible designs facing accelerated shock-testing protocols versus fixed-form alternatives.
- Foldable Antennas:Mesh-conformal radiating elements employing flexible substrate layers enable rapid stowage against soldier body armor. Infantry units across the United States drive procurement volumes through compatibility with legacy radio mounts and reduced snag hazards in dense terrain.
- Telescopic Antennas:Multi-section whip assemblies extend operating length through friction-lock or threaded collet mechanisms. Special operations forces concentrate demand for these variants due to mechanical simplicity and field-repairability in denied logistics environments.
- Wire Antennas:Deployable dipole configurations using stranded copper-clad steel conductors for improvised elevated installations.
- Panel Antennas:Flat planar radiators with directional gain patterns for point-to-point data links.
- Loop Antennas:Magnetic-field-coupled receiving elements optimized for low-frequency direction-finding applications.
Leading the category by volume: Foldable Antennas. Growing fastest: Telescopic Antennas.
Frequency Band:
Cost tier stratification separates spectrum segments, with HF and VHF commanding premium pricing through specialized propagation engineering while L-band and S-band benefit from commercial satellite component economies.
- VHF:30-300 MHz whip and blade configurations dominate line-of-sight tactical voice networks. Ground-based tactical communication units across NATO-aligned forces anchor procurement volumes through interoperability mandates under STANAG standards.
- L Band:1-2 GHz architectures integrate with tactical satellite terminals for beyond-line-of-sight data exfiltration. Indo-Pacific theater expansion fuels steepest expansion trajectory as island-chain contingency planning prioritizes lightweight satcom backhaul.
- UHF:300 MHz-1 GHz ground-to-air and ground-to-ground links with moderate antenna gain requirements.
- HF:3-30 MHz skywave propagation enabling continental-scale communications without relay infrastructure.
- S Band:2-4 GHz configurations supporting wideband data and drone control link applications.
- C Band:4-8 GHz directional terminals for high-capacity relay and satellite uplink missions.
Highest average selling prices: HF and VHF. Expanding most quickly: L Band.
Application:
Customer type segmentation separates program office procurement from unit-level discretionary acquisition, with signal intelligence and electronic warfare requiring additional security clearance tiers for vendor personnel.
- Tactical Communication:Voice, data, and position-location networks for dismounted squad-level coordination. Command centers across the United Kingdom and Australia centralize procurement decisions under consolidated program office structures.
- Signal Intelligence:Intercept, direction-finding, and emitter geolocation missions demanding ultra-wideband reception. Reconnaissance teams drive specification requirements for instantaneous bandwidth switching across contested electromagnetic environments.
- Electronic Warfare:Jamming, deception, and self-protection countermeasures requiring high-power handling and rapid retuning.
- Navigation Support:GPS and multi-constellation GNSS augmentation for denied-environment positioning.
- Field Surveillance:Unattended ground sensor and remote camera relay links for perimeter monitoring.
Dominating procurement value: Tactical Communication. Gaining share fastest: Signal Intelligence.
End User Segment:
Maturity differentiation separates established infantry modernization programs from emerging special operations requirements, with border security representing a fragmented, price-sensitive procurement channel.
- Infantry Units:Standard dismounted soldier equipment for brigade combat teams and light infantry formations. The U.S. Army's PM Tactical Network enforces HMS waveform conformance, filtering vendor participation through certified radio platform integration.
- Special Forces:Low-observable, multi-mission configurations for direct action and special reconnaissance. Salt-corrosion-resistant variants optimized for maritime jungle environments concentrate demand across allied Indo-Pacific forces.
- Command Centers:Fixed and deployable headquarters elements requiring interoperability with higher-echelon networks.
- Reconnaissance Teams:Long-range surveillance and target acquisition units with extended autonomy requirements.
- Border Security:Paramilitary and coast guard organizations with constrained procurement budgets and simplified technical specifications.
Highest unit volumes: Infantry Units. Steepest technology refresh cycles: Special Forces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper-nickel alloy sourcing concentrates in German and Japanese specialty metal corridors, anchoring antenna component supply chains for defense electronics manufacturing clusters across NATO-aligned territories.
United States
The U.S. Army's PM Tactical Network drives procurement centralization through HMS waveform certification requirements. FCC equipment authorization and MIL-STD-810 environmental qualification govern domestic market access. RTX and L3Harris Technologies anchor production in Arizona and Florida facilities, consolidating software-defined radio integration for dismounted soldier platforms.
Germany
Bundeswehr tactical modernization prioritizes NATO STANAG interoperability for cross-border coalition operations. EU defense procurement directives under the European Defence Fund mandate cross-border industrial participation. Thales Deutschland and Rheinmetall cluster RF engineering capabilities in Bavaria and North Rhine-Westphalia, serving pan-European consortium bids.
United Kingdom
Army Command Field Army restructuring concentrates antenna fielding decisions under consolidated program office structures. Ministry of Defence procurement aligns with NATO standardization agreements for allied interoperability. BAE Systems maintains hardened manufacturing facilities in Hampshire and Lancashire, producing ground-mobile and airborne crossover antenna architectures.
Israel
Special operations requirements for low-observable configurations drive technology refresh cycles faster than standard infantry programs. Israeli Defense Forces procurement emphasizes indigenous electromagnetic simulation capabilities. Rafael Advanced Defense Systems and Elbit Systems cluster antenna development in Tel Aviv and Haifa corridors, exporting battle-tested designs to allied Indo-Pacific forces.
Australia
Project Land 200 tactical communications modernization centralizes procurement under Defence Material Organisation authority. Salt-corrosion-resistant specifications dominate island-chain contingency planning for maritime jungle environments. EOS Defence Systems and CEA Technologies anchor production in Canberra and Adelaide, integrating with Five Eyes intelligence-sharing architectures.
Manpack Military Antennas Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mesh-conformal and metamaterial form factors. The vendor base concentrates around three tiers: defense primes with captive RF engineering, mid-tier specialists in tactical radio-adjacent architectures, and niche providers of salt-corrosion-resistant variants. Dominant competitive moves include sole-source justification documentation for program office qualification and consortium formation for EU collective contracting thresholds.
Within the defense prime tier, RTX and L3Harris Technologies exemplify software-defined radio integration strategies, while BAE Systems occupies a position bridging airborne and ground-mobile applications. RTX leverages embedded communications portfolios across multiple branch programs. L3Harris Technologies sustains tactical radio-adjacent antenna architectures through captive RF engineering resources. BAE Systems differentiates via hardened manufacturing capabilities serving crossover application demands.
| Leading Market Players |
|---|
| RTX |
| Honeywell International |
| L3Harris Technologies |
| Leonardo |
| General Dynamics |
| BAE Systems |
| Thales |
| Southwest Antennas |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
Copper-nickel alloy ingots flow from German and Japanese specialty metal corridors through tiered pricing structures that separate MIL-STD-810 certified suppliers from uncertified alternatives. FCC equipment authorization and NATO STANAG compliance costs concentrate pricing power among qualified vendors serving U.S. Army PM Tactical Network procurement.
Pricing Analysis
Warranty and field service bundling separates premium-tier antenna suppliers from standard-tier competitors in manpack military antenna procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from consolidated program office buying that compresses vendor sales cycles and elevates sole-source justification requirements. Border security organizations exhibit highest price sensitivity due to constrained procurement budgets, while special operations forces demonstrate lowest sensitivity given mission-critical performance demands.
Supply Chain Analysis
High-performance copper-nickel alloys and specialized RF substrates rest on limited specialty metal suppliers concentrated in Germany, Japan, and the United States. Antenna manufacturing draws from copper-clad steel conductors, flexible printed circuit substrates, and metamaterial-engineered surfaces as critical inputs. Single-source vulnerability in copper-nickel alloy sourcing exposes production schedules to geopolitical supply disruptions. Distribution runs through defense prime captive production facilities and authorized military procurement channels with direct program office contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where MIL-STD-810 environmental qualification and JTRS waveform certification create substantial barrier-to-entry moats protecting incumbent positions.
For Market Incumbents: To counter emerging metamaterial antenna specialists, deepen captive RF engineering capabilities through targeted recruitment of electromagnetic simulation talent and accelerate software-defined radio platform integration investments. Consolidate sole-source justification documentation for program office qualification to defend procurement volumes against consortium-based European competitors. For New Entrants and Emerging Players: Begin with salt-corrosion-resistant variants optimized for Indo-Pacific maritime jungle environments as the most penetrable white-space target. Pursue EU defense procurement directive consortium formation to meet collective contracting thresholds. Target special operations forces through low-observable mesh-conformal form factors requiring minimal legacy radio backward compatibility. For Investors and Strategic Acquirers: U.S. Army PM Tactical Network centralized procurement decisions signal that software-defined radio roadmap alignment is the leading indicator of long-term antenna design relevance. Mid-tier tactical radio-adjacent specialists with captive RF engineering and existing NATO STANAG certification represent optimal acquisition targets. Monitor JTRS waveform certification status changes as the critical inflection signal for vendor viability reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| JTRS Waveform Certification Investment | Locks in qualified supplier status for U.S. Army HMS program participation. |
| Metamaterial Manufacturing Scale-Up | Enables multi-octave bandwidth performance without mechanical telescoping failure modes. |
| EU Consortium Formation | Pools RF engineering resources across member states to meet European Defence Fund thresholds. |
| Indo-Pacific Salt-Corrosion Testing | Qualifies lightweight variants for island-chain contingency planning requirements. |
| Software-Defined Radio Platform Integration | Anchors antenna relevance through programmable spectrum agility compatibility. |
Research Methodology
Document review covered defense procurement databases, FCC equipment authorization filings, and NATO standardization agreements, complemented by interviews with program managers at U.S. Army PM Tactical Network, RF engineering directors at defense primes, procurement officers at allied defense ministries, and antenna measurement laboratory technicians. Secondary validation drew from MIL-STD-810 test reports, HMS program documentation, and EU defense procurement directive texts. Bottom-up segment sizing and top-down market reconciliation provided cross-verification.
Segment-level value and volume trajectories across the projection horizon reflect product type, frequency band, application, and end user segment dimensions. CAGRs were derived from regression analysis against defense budget appropriation patterns and software-defined radio platform deployment schedules. Waveform certification timelines and NATO STANAG revision cycles served as industry-specific forecast inputs.
Defense budget reallocation shocks, JTRS waveform specification changes, and copper-nickel supply disruptions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented procurement centralization trends and environmental qualification burden assessments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Displays Market