
 Tactical Data Link Market | 2026-2036
Tactical Data Link Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Data Link Market Analysis
STANAG 5516 and MIL-STD-6016 certification cycles is redrawing competitive access in tactical data link supply. L3Harris Technologies leverages its vertically integrated waveform development to sustain program-of-record positions across U.S. Navy and Air Force platforms. Collins Aerospace anchors European Link 16 retrofit demand through its NATO-compatible MIDS-LVT production line. Thales Group differentiates via national security-cleared manufacturing facilities serving French and export customers.
A tactical data link constitutes a standardized digital communications system enabling real-time exchange of tactical information—surveillance tracks, weapon assignments, and command directives—between mobile military platforms via UHF or L-band radio frequencies with encryption and frequency-hopping protection. The technology dimension shows Link 16 sustaining dominant program share while VMF protocols gain traction in ground-force digitization; application-level demand tilts toward military operations where joint force interoperability requirements command premium pricing, with naval operations representing a concentrated margin pool due to shipborne integration complexity.
FAA coordination with U.S. DoD spectrum policy, NATO STANAG standardization bodies, and national cryptographic authorities including the U.S. National Security Agency shape product roadmaps and foreign market access conditions. The U.S. Federal Communications Commission and equivalent spectrum regulators in Germany, Japan, and South Korea constrain waveform deployment parameters, directly influencing manufacturer R&D allocation. Stakeholders must monitor software certification timelines and host-nation cryptographic approval pathways as determinants of contract viability.
Market Dynamics
Software-defined radio architectures are fragmenting the traditional hardware-locked supplier base by enabling waveform portability across platforms, forcing incumbents to release proprietary IP into interoperable frameworks or lose program-of-record status.
Growth Catalysts
- U.S. DoD Link 16 Modernization Mandate:The Pentagon's directive to upgrade legacy terminals across air and naval platforms sustains multi-year procurement pipelines for certified waveform developers.
- NATO STANAG 5516 Interoperability:Alliance-wide standardization compels member states to harmonize tactical data link equipment, creating cross-border volume for qualified suppliers.
- Joint All-Domain Command-and-Control:U.S., UK, and Australian defense integration initiatives demand real-time data fusion across land, sea, air, space, and cyber domains.
Market Restraints
- Gallium Nitride Component Concentration:Foundry capacity for high-power RF semiconductors clusters in Taiwan and the United States, exposing supply chains to single-source fragility.
- National Cryptographic Approval Pathways:Each host nation requires host-nation certification from agencies like the U.S. NSA or equivalent bodies, stretching sales cycles by 18-36 months.
- Legacy Terminal Sunk Costs:Existing Link 16 hardware investments across NATO fleets slow replacement velocity despite performance gaps with software-defined alternatives.
Strategic Opportunities
- Unmanned Systems Integration:UAV swarms and autonomous surface vessels require lightweight, low-power tactical data links absent mature vendor solutions.
- VMF Protocol Ground-Force Digitization:Variable Message Format adoption in armored vehicle networks opens retrofit demand beyond aviation-centric Link 16 dominance.
- Five Eyes Spectrum Harmonization:Coordinated U.S., UK, Canadian, Australian, and New Zealand frequency allocations reduce customization overhead for multi-national programs.
Industry Challenges
- Software Certification Bottlenecks:Formal verification of waveform code against MIL-STD-6016 and STANAG 5516 absorbs 40% of development resources and delays fielding.
- Cross-Domain Security Architecture Integration:Zero-trust networking principles from U.S. DoD Zero Trust Strategy clash with legacy link-layer encryption assumptions, forcing architecture rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Data Link Market |
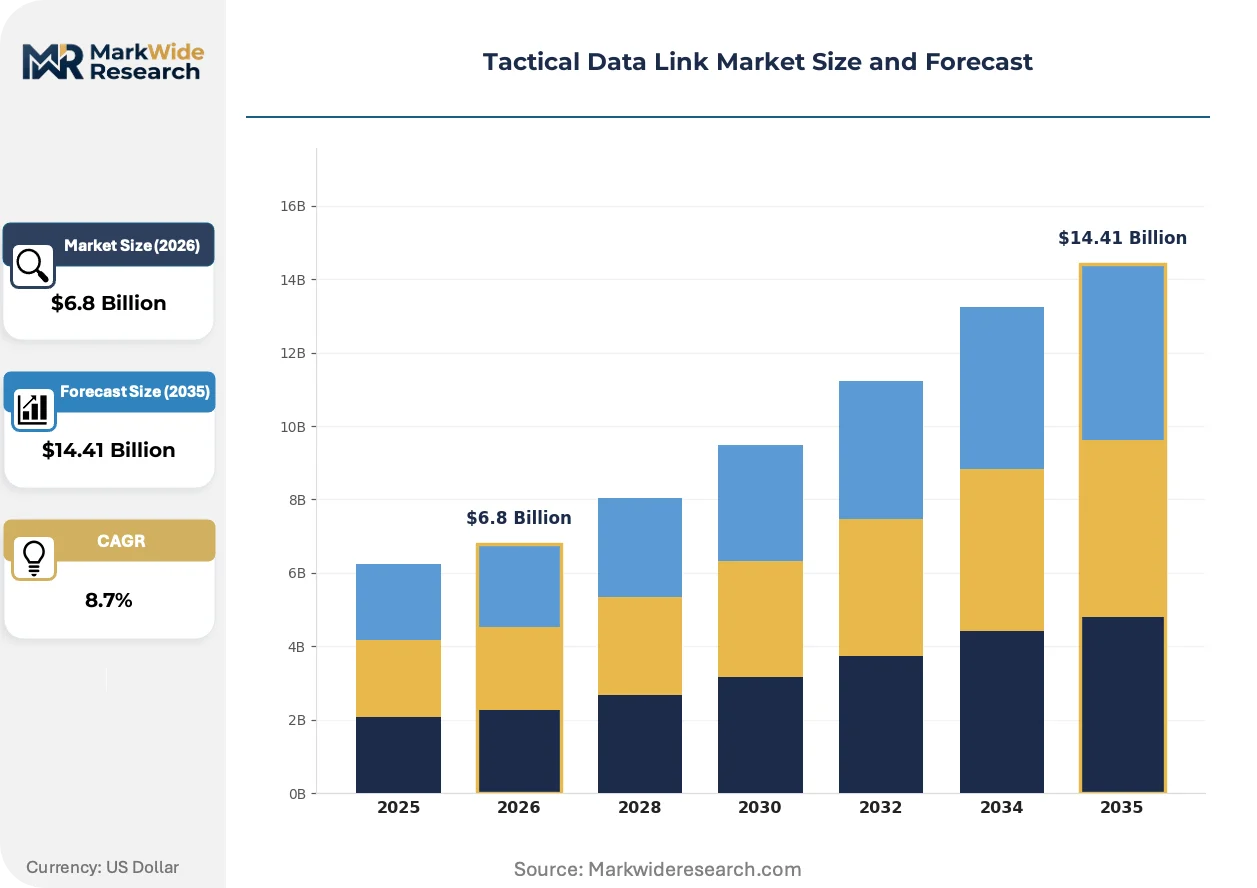
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Link 16, Link 11, ATDL, VMF Application: Military Operations, Air Traffic Control, Naval Operations, Ground Forces End User: Defense Contractors, Government Agencies, Military Forces, Research Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | L3Harris Technologies, Collins Aerospace, General Dynamics Corporation, Northrop Grumman Corporation, BAE Systems, Raytheon Technologies, Thales Group, Lockheed Martin Corporation, Viasat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Data Link Market Emerging Trajectories
Waveform virtualization and modular open systems architectures are collapsing the traditional boundary between radio hardware and software, enabling faster capability insertion without platform recertification.
Software-defined radio is decomposing the rigid hardware-software coupling that historically locked militaries into single-vendor terminal ecosystems. U.S. Navy and Air Force programs are adopting open-architecture middleware at accelerating pace. This decomposition compresses supplier switching costs and enables competitive waveform sourcing across previously captive platform lines.
FCC coordination with U.S. DoD spectrum policy is tightening L-band and UHF allocation rules for commercial-adjacent military operations. Manufacturers must now engineer dynamic spectrum access capabilities into new terminal designs. Naval platforms operating in congested littoral environments face the steepest compliance engineering burden.
Defense procurement offices are consolidating tactical data link requirements into multi-platform enterprise contracts rather than platform-specific buys. This concentrates vendor selection authority with joint program offices and marginalizes platform primes as procurement gatekeepers. The United Kingdom's Defence Digital organization exemplifies this concentration most visibly among European allies.
Tactical Data Link Market Segmentation
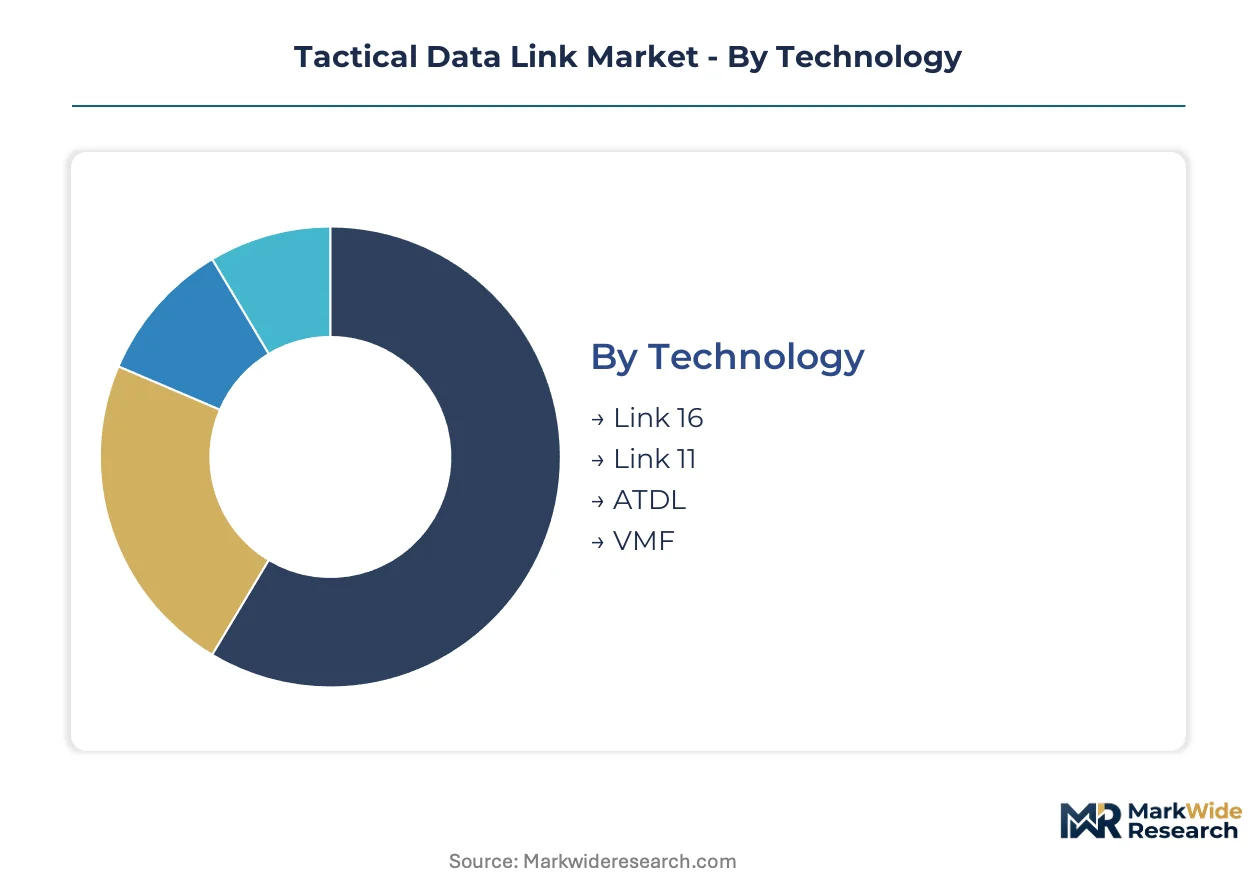
Tactical data link procurement patterns diverge sharply across waveform standards, platform types, and operational domains. Segmentation reveals where certification barriers concentrate vendor margins and which deployment models face the steepest compliance engineering costs.
Technology:
FCC spectrum allocations and NSA cryptographic certification cycles create tiered access barriers across waveform categories, with STANAG 5516 compliance separating program-of-record suppliers from peripheral vendors.
- Link 16:The NATO-standard TADIL-J waveform operates in the 960-1215 MHz L-band with frequency-hopping spread spectrum and time-division multiple access. U.S. Navy and Air Force platform modernization programs sustain dominant procurement volumes, though Gallium Nitride component bottlenecks constrain terminal production timelines.
- VMF:Variable Message Format protocols enable digital information exchange across ground combat platforms via IP-based networking rather than legacy time-slot architectures. U.S. Army and Marine Corps armored vehicle digitization initiatives are accelerating VMF adoption beyond its traditional aviation-centric Link 16 complement.
- Link 11:The legacy TADIL-A/B HF/UHF waveform persists in naval task force coordination despite bandwidth limitations relative to Link 16. Existing shipborne terminal installations across NATO fleets slow displacement velocity.
- ATDL:Army Tactical Data Links encompass specialized ground-force protocols including interim VMF precursors and national variants. Host-nation cryptographic approval requirements fragment procurement standardization.
Link 16 handles the majority of throughput; VMF is climbing the fastest on program share.
Application:
Platform integration complexity and mission-criticality create four distinct demand tiers with diverging margin structures and certification timelines.
- Naval Operations:Shipborne tactical data link integration demands salt-hardened terminals, mast-mounted antenna arrays, and multi-band interoperability across congested littoral electromagnetic environments. The U.S. Navy's distributed maritime operations doctrine and Royal Navy carrier strike group modernization sustain concentrated procurement.
- Military Operations:Joint all-domain command-and-control architectures fuse air, maritime, ground, space, and cyber domain data through interoperable waveforms. U.S. Indo-Pacific Command and NATO Allied Command Operations drive multi-national terminal standardization.
- Air Traffic Control:Military-civil coordination requirements impose FAA interoperability mandates on terminal designs for national airspace system integration. Mode 5 identification friend-or-foe upgrades create adjacent procurement demand.
- Ground Forces:Armored vehicle network digitization requires ruggedized low-power terminals with ad-hoc networking capabilities absent mature vendor solutions. Urban warfare communication range constraints challenge waveform selection.
Naval Operations commands premium pricing per terminal; Ground Forces represent the steepest expansion trajectory as vehicle modernization accelerates.
End User:
Procurement authority concentration and security clearance requirements segment the customer base into distinct contracting pathways with diverging vendor qualification barriers.
- Military Forces:Operational commands within the U.S. Department of Defense, UK Ministry of Defence, and Australian Defence Force execute platform-specific terminal acquisitions through program executive offices. Joint program office consolidation is marginalizing platform prime gatekeeper roles.
- Defense Contractors:System integrators including L3Harris Technologies and Collins Aerospace procure waveform modules and terminal subsystems for platform integration. Vertically integrated suppliers with captive semiconductor fabrication sustain cost advantages.
- Government Agencies:National security establishments and signals intelligence organizations procure specialized tactical data link variants with enhanced encryption tiers. NSA and GCHQ certification pathways extend sales cycles substantially.
- Research Institutions:Defense laboratories and university-affiliated research centers acquire developmental waveform software and software-defined radio testbeds. DARPA and ONR funding supports next-generation protocol experimentation.
Military Forces account for the dominant procurement volume; Defense Contractors are expanding fastest as platform integration responsibilities shift.
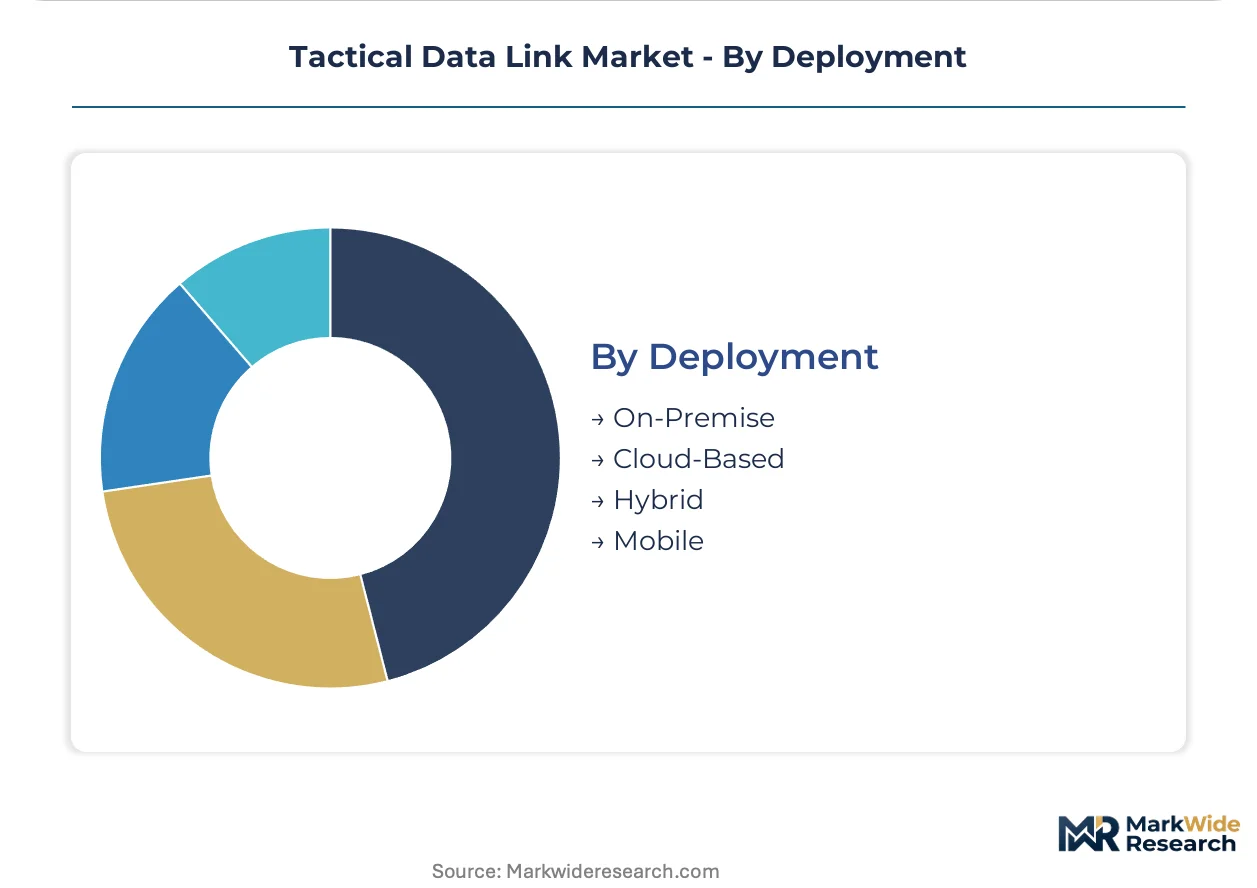
Deployment:
Network architecture choices reflect operational mobility requirements and security classification levels, with cloud-adjacent models facing the steepest U.S. DoD Zero Trust compliance engineering.
- On-Premise:Classified networks and air-gapped operational systems require physically isolated terminal infrastructure with no external connectivity. Fixed command posts and strategic headquarters sustain this deployment model.
- Mobile:Forward-deployed platforms including fighter aircraft, surface vessels, and ground vehicles demand ruggedized terminals with autonomous networking capabilities. SWaP-C constraints dominate procurement specifications.
- Hybrid:Partitioned architectures segregate classified tactical data from unclassified administrative traffic across common physical infrastructure. U.S. Navy afloat network modernization exemplifies this approach.
- Cloud-Based:Software-defined waveform virtualization and tactical edge computing enable dynamic capability insertion without hardware recertification. DISA milCloud and UK Defence Digital cloud programs are piloting classified implementations.
Mobile deployment handles the dominant installed base; Cloud-Based models are gaining share fastest as software-defined architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in NATO-aligned nations concentrate demand for interoperable waveform systems, with national cryptographic approval pathways creating distinct market access conditions across major military spenders.
United States
The U.S. Department of Defense drives dominant procurement volumes through Link 16 modernization mandates across Navy and Air Force platforms. FCC coordination with DoD spectrum policy tightens L-band allocation rules for military operations. Defense contractors cluster around Washington D.C. and Florida, where L3Harris Technologies and Collins Aerospace maintain program-of-record positions.
United Kingdom
UK Ministry of Defence investments in joint all-domain command-and-control architectures sustain cross-domain terminal demand. Defence Digital organization consolidates procurement authority into enterprise contracts rather than platform-specific buys. Industrial activity concentrates in England's aerospace corridor, where BAE Systems anchors European Link 16 retrofit programs.
Australia
Australian Defence Force integration into Five Eyes intelligence-sharing networks drives spectrum harmonization requirements with allied nations. The country's defense procurement follows U.S. NSA cryptographic certification pathways, extending sales cycles substantially. Defense technology development clusters in South Australia and Victoria, where sovereign capability mandates shape vendor selection.
Germany
Bundeswehr platform modernization programs generate demand for NATO STANAG 5516-compliant terminals across naval and aerial assets. German spectrum regulators constrain waveform deployment parameters in congested European electromagnetic environments. Defense industrial activity concentrates in Bavaria and Baden-Württemberg, where Rheinmetall and Airbus Defence maintain integration partnerships.
France
French armed forces procurement prioritizes national security-cleared manufacturing for sovereign data link capabilities. ANSSI and DGA certification requirements create distinct approval pathways separate from NATO standardization. Thales Group anchors domestic supply from facilities in Île-de-France and Provence-Alpes-Côte d'Azur, serving export customers with national-cleared production.
Tactical Data Link Market Vendor Landscape
Player mix skews toward vertically integrated defense primes with captive waveform development capabilities. The supplier base concentrates around certification-holding incumbents who have secured STANAG 5516 and MIL-STD-6016 approvals. Three strategic archetypes dominate: waveform developers with semiconductor fabrication control, platform integrators with program-of-record relationships, and national champions with security-cleared manufacturing. Competitive moves center on software-defined radio architecture releases and multi-platform enterprise contract consolidation.
Among U.S.-based defense primes, L3Harris Technologies and General Dynamics Corporation exemplify the vertically integrated archetype with in-house waveform development. Collins Aerospace and Raytheon Technologies occupy positions as platform integrators leveraging NATO-compatible production lines. Thales Group represents the national champion model with French security-cleared facilities serving sovereign and export demand.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Collins Aerospace |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Raytheon Technologies |
| Thales Group |
| Lockheed Martin Corporation |
| Viasat |
| Others |
Supply Flow & Price Mechanics
Foundry utilization rates above 85 percent at Taiwan Semiconductor Manufacturing Company and GlobalFoundries' U.S. facilities create asymmetric scale advantages for waveform developers with captive semiconductor access, compressing price floors for modular terminal suppliers lacking backward integration into Gallium Nitride fabrication.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics producer price index adjustment clauses dominate U.S. DoD program-of-record awards, embedding raw material pass-throughs that insulate vertically integrated primes from margin erosion while exposing modular assemblers to GaN wafer spot volatility. Pricing stratifies across STANAG 5516-certified program-of-record tiers, host-nation cryptographic approval tiers, and commercial-off-the-shelf economy alternatives. Cost compression in the COTS tier intensifies as software-defined radio portability collapses switching costs. Defense contractors with in-house foundry relationships exhibit lowest price sensitivity; platform integrators dependent on merchant GaN supply face acute margin pressure.
Supply Chain Analysis
Taiwan and the United States anchor Gallium Nitride-on-Silicon-Carbide wafer fabrication, while Germany and Japan concentrate precision RF filter and antenna component manufacturing. Terminal assembly draws from GaN RF power amplifiers, cryptographic modules with NSA Type 1 certification, and ruggedized embedded computing substrates. Single-source vulnerability concentrates in 100-millimeter GaN-on-SiC substrate supply from two merchant foundries. Distribution runs through prime contractor integration partnerships with platform OEMs rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tactical data link demand sits in early-cycle expansion as Joint All-Domain Command-and-Control architectures mandate real-time waveform interoperability across previously siloed platform categories, accelerating replacement of hardware-locked legacy terminals.
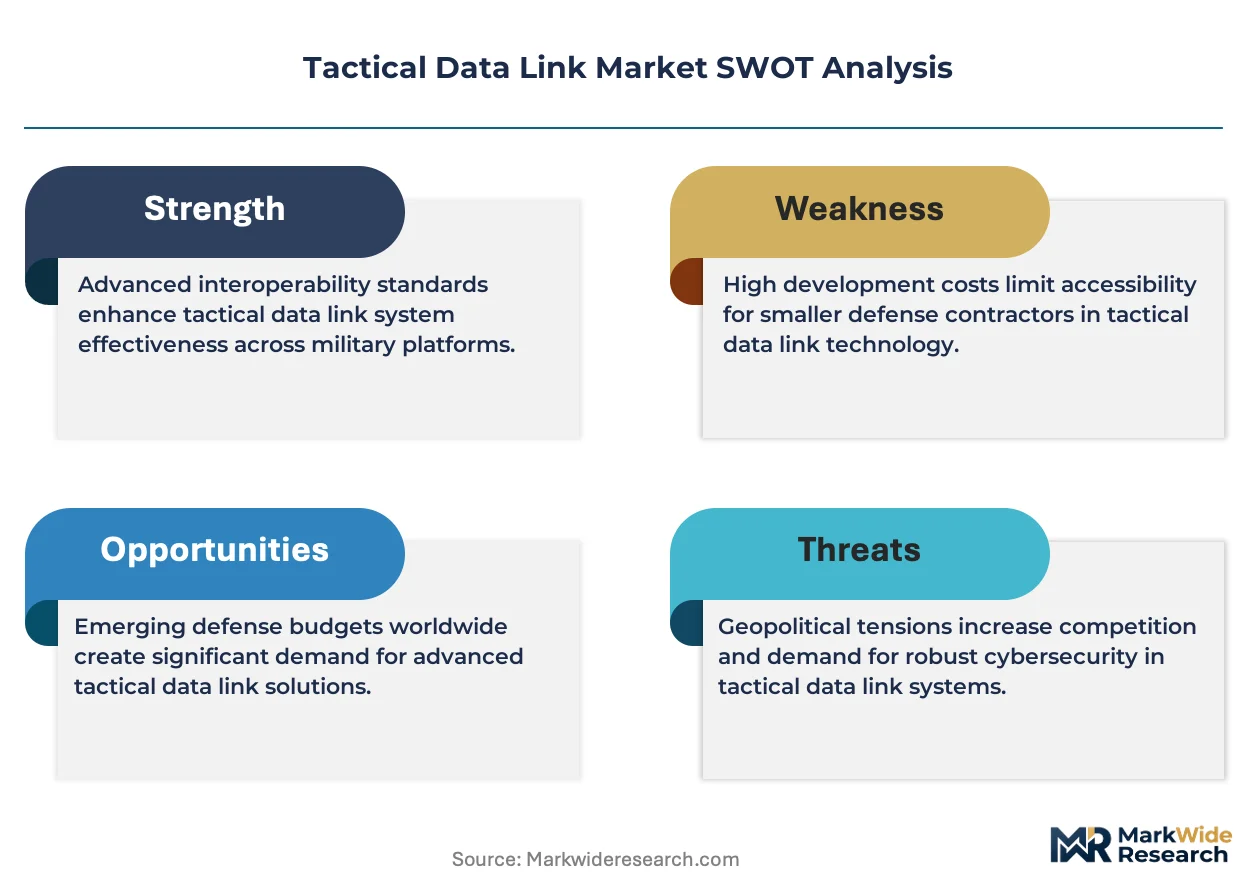
For Market Incumbents: Compound program-of-record positions by accelerating software-defined radio middleware releases that collapse competitor switching-cost advantages, while securing captive GaN foundry allocation through long-term supply agreements with Taiwan-based substrate providers. Threat from modular waveform developers with open-architecture stacks demands preemptive certification investment in NSA Type 1 and NATO STANAG 5516 variants. For New Entrants and Emerging Players: Differentiate on unmanned systems integration where lightweight low-power terminal requirements outpace incumbent product roadmaps, targeting UAV swarm and autonomous surface vessel programs with SWaP-C-optimized form factors. Ground-force VMF protocol digitization represents the most penetrable application tier given absent mature vendor solutions. Go-to-market through defense laboratory R&D partnerships accelerates waveform validation without platform recertification burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among waveform developers with multi-platform enterprise contracts spanning Navy, Air Force, and allied foreign military sales channels. Long-term viability over a decade-plus horizon rests on cryptographic certification moats and foundry integration depth. Acquisition target archetype: mid-scale software-defined radio specialists with STANAG 5516 approvals and strained working capital. Signal to watch: U.S. DoD Zero Trust architecture mandate acceleration forcing legacy encryption rebuilds.| Strategic Initiative | Industry Significance |
|---|---|
| Waveform Virtualization Platform Launch | Enables capability insertion without MIL-STD-6016 recertification, compressing fielding timelines for U.S. Navy programs. |
| GaN Foundry Backward Integration | Captures margin pool from RF semiconductor supply concentration in Taiwan and secures allocation priority during capacity constraints. |
| Multi-Nation Cryptographic Certification | Unlocks NATO STANAG 5516 and French ANSSI pathways, expanding addressable market beyond U.S. NSA Type 1 constraints. |
| Unmanned Systems Terminal Miniaturization | Addresses SWaP-C requirements for UAV swarms where incumbent terminal form factors exceed platform payload limits. |
| Joint Program Office Enterprise Contracting | Aligns procurement authority concentration at U.S. DoD and UK Defence Digital, marginalizing platform prime gatekeeper roles. |
Methodological Framework
Initial hypotheses were tested against primary input from program executive officers at U.S. Navy and Air Force acquisition commands, waveform engineering directors at tier-one defense primes, and national cryptographic authority certification leads, then refined through secondary validation against DoD budget justification documents, NATO STANAG publication records, and SEC 10-K filings from publicly traded defense contractors. Bottom-up terminal shipment estimates by platform type were triangulated against top-down defense procurement budget allocations across the analysis window.
Variance decomposition across technology, application, and deployment segmentation dimensions drove analytical framework construction, with CAGRs derived from logistic adoption curves fitted to software-defined radio penetration assumptions and Joint All-Domain Command-and-Control investment trajectories. Industry-specific forecast inputs included GaN component foundry capacity expansion schedules and host-nation cryptographic approval pipeline backlogs.
Material uncertainties — Gallium Nitride supply disruption, NSA certification timeline delays, and allied defense budget reallocation — sit outside the modeled envelope. Forecasts reflect assumptions about sustained U.S. DoD modernization mandate continuity and NATO interoperability spending cohesion. Recalibration cycles align with material shifts in semiconductor foundry utilization, cryptographic policy directives, and joint program office contracting consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market