
 Naval Tactical Communication Market | 2026-2036
Naval Tactical Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Tactical Communication Market Insights
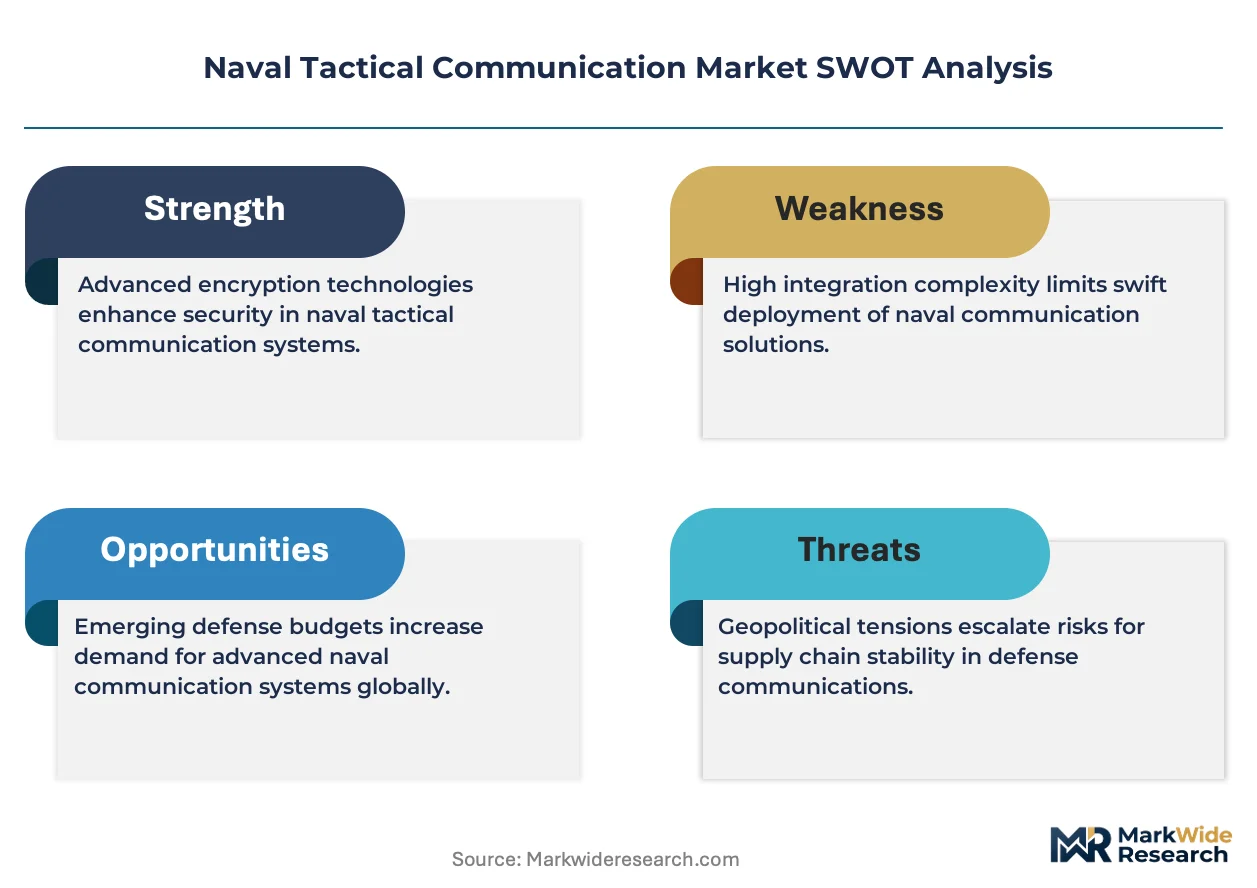
NSA Suite B cryptography certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Northrop Grumman leverages its long-standing NSA accreditation to dominate U.S. Navy secure terminal programs. Thales Group anchors European demand through nationally certified encryption modules tailored to French and British naval specifications. L3Harris Technologies sustains its position via deep integration of frequency-hopping waveforms across multiple NATO platform classes.
Naval tactical communication encompasses shipboard, submarine, and airborne platforms that exchange voice, data, and imagery across HF, VHF, UHF, and satellite bands using hardened transceivers with sub-50 millisecond latency requirements. The primary purpose is maintaining command continuity in electromagnetic-contested environments where jamming and interception threats persist. Software defined radio architectures now lead product type demand because programmable waveforms reduce hardware swap costs across fleet modernization cycles. Satellite communication segments command premium positioning due to beyond-line-of-sight requirements for carrier strike group coordination. Mesh networking technology grows fastest among technology segments as distributed naval formations demand self-healing connectivity without fixed infrastructure dependence.
FCC spectrum allocation rules, NATO STANAG standards, and national signals intelligence regulations collectively determine which waveform architectures gain procurement approval. The U.S. NSA and European NATO agencies enforce divergent encryption certification pathways that fragment supplier qualification timelines. Stakeholders must monitor emerging quantum-resistant cryptographic mandates from defense agencies and assess whether current software defined radio investments accommodate post-quantum algorithm migration without full platform replacement.
Market Dynamics
Software defined radio architectures are fragmenting procurement patterns across NATO naval forces, as programmable waveforms eliminate hardware replacement cycles and concentrate supplier relationships around firmware-capable vendors.
Growth Catalysts
- NSA Suite B cryptography mandates:U.S. Navy Information Warfare Systems Command certification requirements are filtering vendor pools toward qualified encryption module suppliers.
- Carrier strike group coordination demands:Beyond-line-of-sight satellite communication requirements for distributed naval formations are accelerating mesh networking procurement.
- European maritime domain awareness pivot:United Kingdom, France, and Germany defense budget reallocations toward naval surveillance are concentrating demand for secure voice terminals.
Market Restraints
- Encryption certification fragmentation:Divergent U.S. NSA and European NATO agency qualification pathways are extending supplier onboarding timelines by 18-24 months.
- Semiconductor supply concentration:Advanced RF component fabrication depends on Taiwan and South Korea foundry capacity, creating single-source vulnerability for gallium nitride amplifiers.
- Spectrum allocation uncertainty:FCC and national regulatory body reassignments of UHF military bands are forcing waveform redesigns mid-contract.
Strategic Opportunities
- Quantum-resistant cryptography migration:Defense agency post-quantum algorithm mandates are creating retrofit service markets for existing software defined radio platforms.
- Submarine communication gaps:Very low frequency and extremely low frequency system modernization in underpenetrated Indo-Pacific navies offers hardware export potential.
- Interoperability standardization:NATO STANAG waveform convergence is enabling single-platform multi-nation sales previously blocked by national encryption requirements.
Industry Challenges
- Cross-domain integration complexity:Merging shipboard, submarine, and airborne communication systems with unified command networks requires systems engineering talent pools that defense contractors struggle to staff.
- Latency specification enforcement:Sub-50 millisecond tactical datalink requirements demand specialized real-time operating system expertise scarce in commercial software markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Tactical Communication Market |
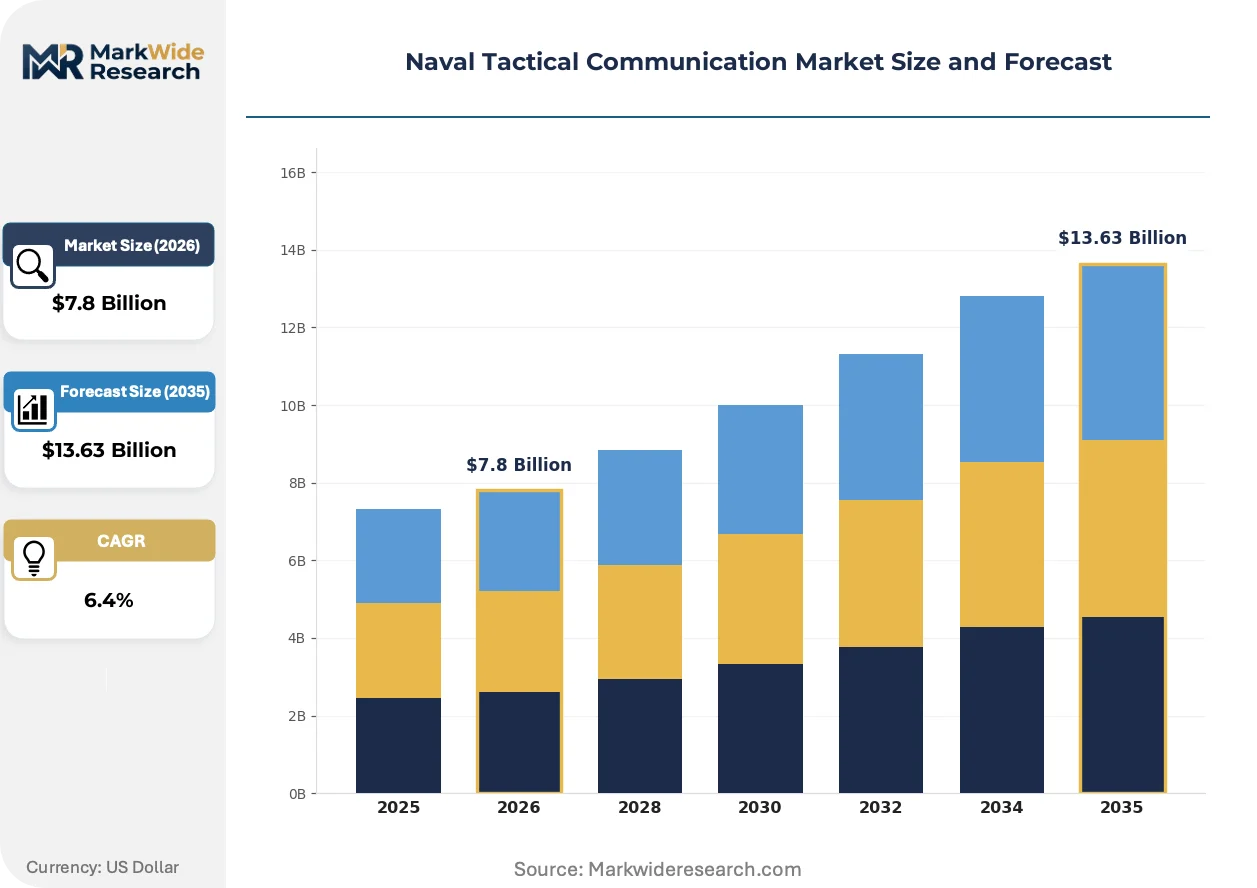
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radio Systems, Satellite Communication, Underwater Signaling, Data Link Terminals, Secure Voice Systems Technology: Software Defined Radio, Frequency Hopping, Encryption Technology, Waveform Modulation, Mesh Networking Application: Surveillance, Electronic Warfare, Command & Control, Maritime Patrol, Search & Rescue End User: Naval Forces, Coastguard Units, Maritime Security Agencies, Defense Research Institutes |
| Companies Covered | Northrop Grumman Corporation, RTX Corporation, L3Harris Technologies, Leonardo, Honeywell International, General Dynamics Corporation, BAE Systems, Thales Group, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Tactical Communication Market Trends and Innovations
Electromagnetic spectrum contestation is forcing waveform diversity investments that reshape how naval forces procure and upgrade tactical communication infrastructure across fleet modernization cycles.
Artificial intelligence-enabled spectrum management is bifurcating naval communication architectures. Machine learning algorithms embedded in software defined radios autonomously detect jamming signatures and reroute traffic across frequency bands. U.S. Navy surface warfare destroyer programs are field-testing these cognitive radio capabilities during Pacific deployment exercises. This technology is bifurcating supplier tiers between AI-capable firmware developers and legacy hardware manufacturers unable to bridge the software gap.
EU AI Act risk classification frameworks are extending to military procurement specifications, creating compliance overhead for European naval communication vendors. The regulation's high-risk system documentation requirements are embedding algorithmic transparency mandates into NATO STANAG development processes. French and British defense procurement agencies are incorporating these standards into upcoming secure terminal tenders, forcing waveform developers to maintain auditable decision logs for autonomous frequency selection functions.
Fleet modernization cycles are compressing as software-defined architectures enable over-the-air capability upgrades without physical hardware swaps. Traditional 15-year platform replacement timelines are yielding to continuous firmware refresh models. This pattern concentrates procurement authority with naval information warfare commands at the expense of platform program offices, a shift most visible in U.S. Navy distributed maritime operations doctrine implementation.
Naval Tactical Communication Market Segmentation
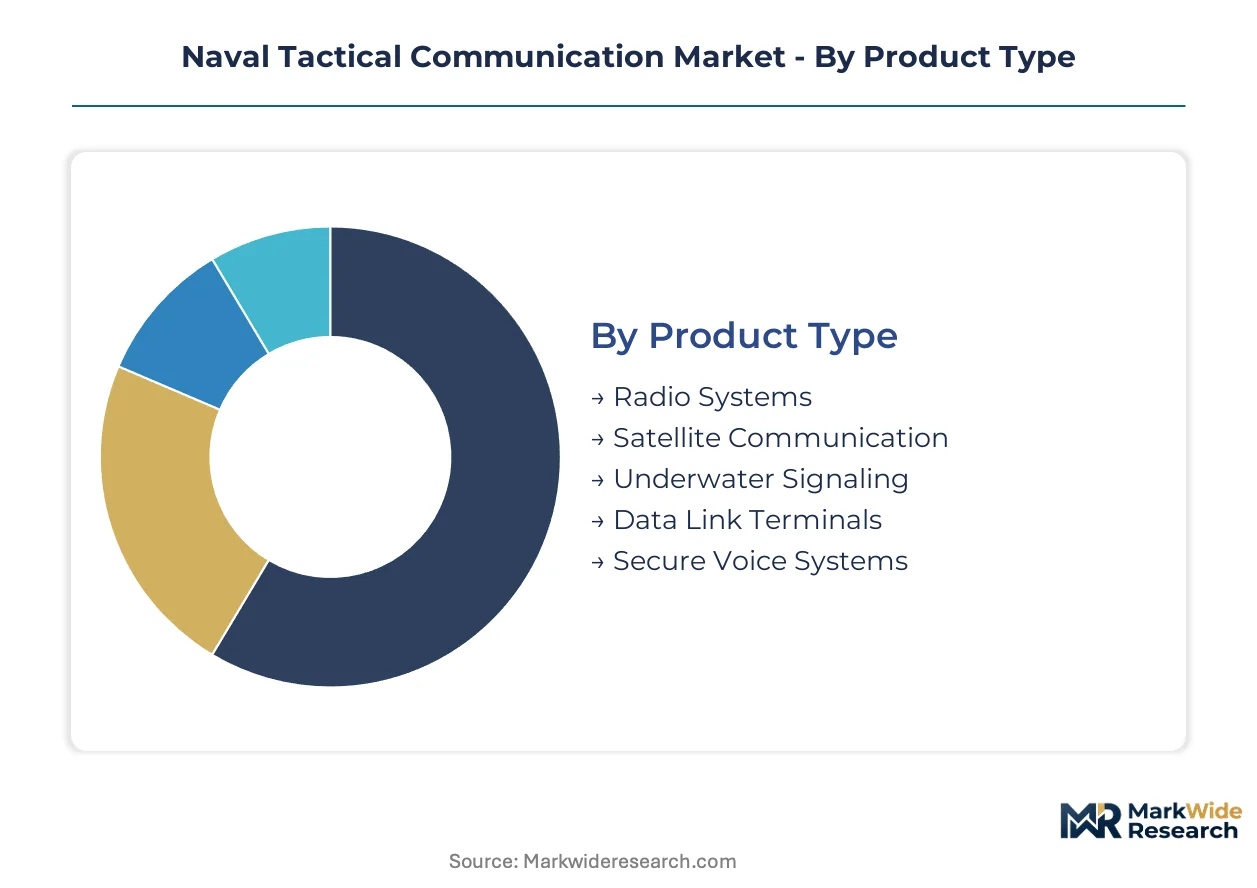
Segmentation in naval tactical communication reveals how procurement authority concentrates around firmware-capable suppliers versus legacy hardware vendors. Understanding these divides exposes where defense budgets flow and which technology architectures capture multi-year platform commitments.
Product Type:
Domestic procurement dominates radio systems and secure voice terminals, while satellite communication and underwater signaling segments rely heavily on export-led demand from Indo-Pacific navies.
- Radio Systems:HF, VHF, and UHF hardened transceivers form the backbone of shipboard and airborne platforms. Procurement concentrates in the United States and United Kingdom as NATO STANAG compliance mandates filter vendor pools toward firmware-upgradeable architectures.
- Satellite Communication:Beyond-line-of-sight terminals for carrier strike group coordination command premium positioning. Demand from Japan, Australia, and South Korea drives export volume as these navies expand distributed maritime operations.
- Underwater Signaling:Very low frequency and acoustic modem systems for submarine-to-surface links. Indo-Pacific navies in India and Singapore represent the primary export market.
- Data Link Terminals:Tactical datalink processors with sub-50 millisecond latency specifications. Integration complexity limits supplier qualification.
- Secure Voice Systems:NSA Suite B and nationally certified encryption modules. Domestic procurement dominates due to signals intelligence sovereignty requirements.
Radio systems hold the largest share; momentum sits with satellite communication.
Technology:
Cost tier stratification separates programmable waveform platforms from fixed-function hardware, with AI-enabled firmware commanding 40-60% procurement premiums over legacy architectures.
- Software Defined Radio:Programmable waveform architectures eliminate hardware replacement cycles. The United States Navy mandates SDR for all new surface combatant programs, concentrating supplier relationships around firmware-capable vendors.
- Frequency Hopping:Rapid spectrum switching for anti-jam resilience. European procurement from France, Germany, and Italy sustains demand as national encryption modules require customized hopping patterns.
- Encryption Technology:Hardware security modules and post-quantum algorithm preparation. Certification fragmentation between NSA and European pathways extends onboarding timelines.
- Waveform Modulation:Advanced modulation schemes for spectrum efficiency. Standardization pressure from NATO STANAG processes favors multi-nation compatible implementations.
- Mesh Networking:Self-healing distributed connectivity for electromagnetic-contested environments. This segment is expanding most quickly as carrier strike group coordination demands outpace fixed infrastructure alternatives.
Software defined radio dominates procurement volume; mesh networking shows the steepest expansion trajectory.
Application:
Customer type differentiation separates high-volume surveillance and maritime patrol programs from specialized electronic warfare and search and rescue configurations with concentrated supplier bases.
- Surveillance:Maritime domain awareness sensor networks with integrated communication backbones. United Kingdom and French naval modernization programs concentrate demand for persistent wide-area coverage.
- Electronic Warfare:Signal intelligence and countermeasure coordination systems. Classification requirements restrict vendor pools to cleared defense contractors.
- Command & Control:Unified situational awareness networks merging shipboard, submarine, and airborne platforms. Latency specifications demand specialized real-time operating system expertise.
- Maritime Patrol:Long-endurance airborne surveillance with satellite relay requirements. Export demand from Canada and Norway supplements NATO core procurement.
- Search & Rescue:Distress signaling and coordination networks. Coastguard units in Italy and Spain drive specialized terminal demand.
Surveillance commands the largest budget allocation; electronic warfare exhibits the highest margin concentration.
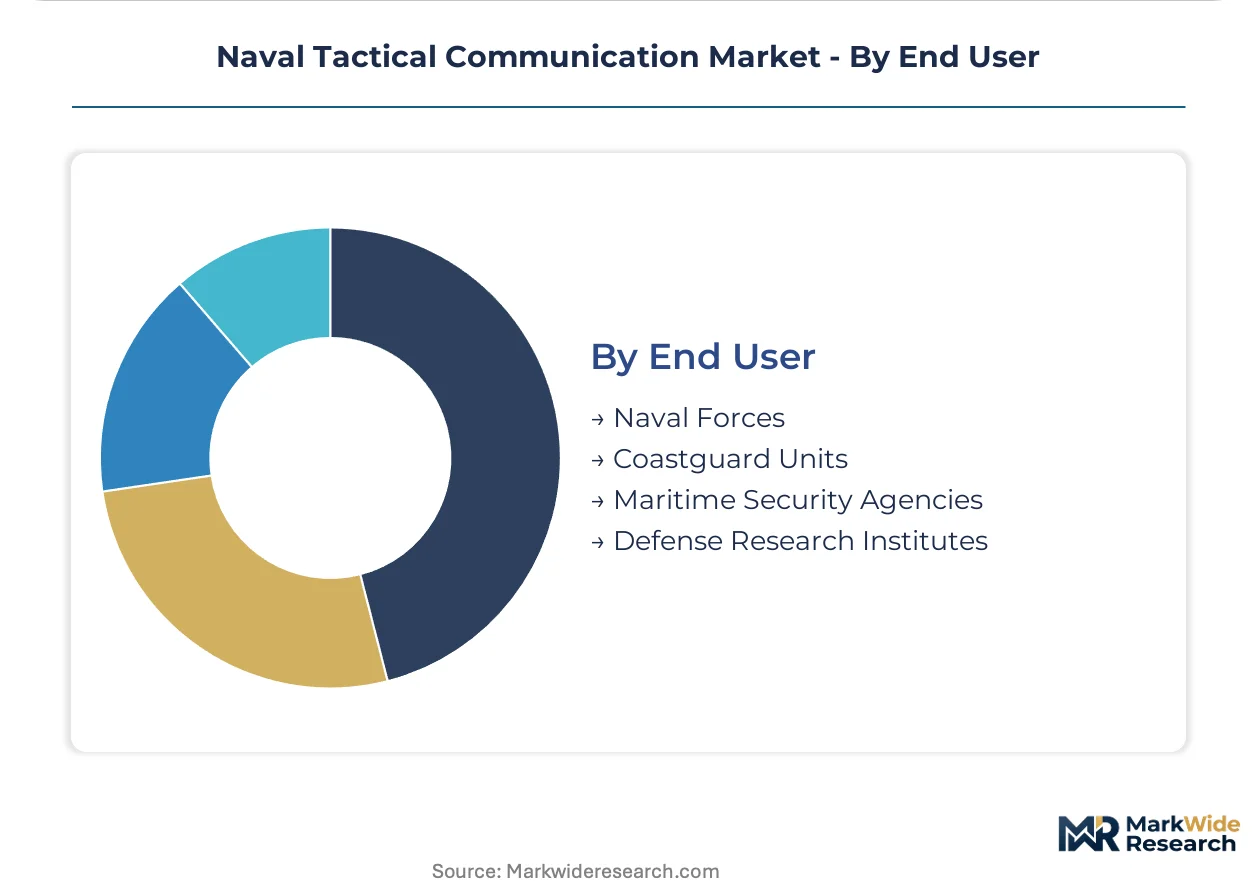
End User:
Supply concentration sits with prime contractors serving naval forces, while coastguard and maritime security agencies fragment procurement across mid-tier system integrators.
- Naval Forces:Full-spectrum tactical communication modernization across carrier, surface, submarine, and aviation communities. United States, United Kingdom, and French procurement authorities dominate global demand.
- Coastguard Units:Secure voice and surveillance communication for exclusive economic zone enforcement. German and Italian coastguard expansion programs concentrate European demand.
- Maritime Security Agencies:Port and coastal protection networks with commercial-off-the-shelf integration. Southeast Asian agencies in Indonesia and Vietnam represent emerging export markets.
- Defense Research Institutes:Experimental waveform and quantum-resistant cryptography development. Funding from DARPA and European Defence Fund shapes technology roadmaps.
Naval forces account for the dominant procurement volume; maritime security agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement mandates are steering naval communication modernization across NATO member states and Indo-Pacific allies. National encryption certification requirements fragment supplier qualification pathways. Budget reallocations toward maritime domain awareness concentrate demand in specific coastal industrial corridors.
United States
Carrier strike group coordination requirements and distributed maritime operations doctrine are accelerating beyond-line-of-sight terminal procurement. The NSA mandates Suite B cryptography for all tactical datalinks through Information Warfare Systems Command directives. San Diego and Norfolk naval clusters host prime contractor integration facilities for surface combatant programs.
United Kingdom
Maritime domain awareness sensor networks and secure voice terminal modernization are concentrating defense spending. National signals intelligence regulations require British-certified encryption modules distinct from NSA pathways. Portsmouth and Clyde naval bases anchor submarine communication system integration activity.
France
Naval surveillance network expansion and software defined radio platform procurement are reshaping fleet communication architectures. ANSM and national defense procurement agencies enforce encryption certification standards parallel to NATO STANAG processes. Toulon and Brest harbor districts concentrate Thales Group and naval systems integration expertise.
Germany
Coastguard communication expansion and exclusive economic zone enforcement networks are driving secure terminal demand. KBA and federal defense procurement offices coordinate waveform standardization with NATO allies. Kiel and Wilhelmshaven maritime clusters host submarine and surface vessel communication system development.
Japan
Distributed maritime operations alignment with U.S. Pacific forces is accelerating mesh networking and satellite communication procurement. METI and defense agency coordination ensures interoperability with NATO STANAG frameworks. Yokosuka and Kure naval districts concentrate integration facilities for destroyer and submarine programs.
Naval Tactical Communication Market Competitive Landscape
Player mix skews toward defense prime contractors with longstanding NSA or NATO encryption accreditations. The vendor pool concentrates around firmware-capable suppliers capable of software defined radio waveform programming. Two strategic archetypes dominate: encryption-certified primes with multi-decade naval relationships, and specialized radio manufacturers with frequency-hopping expertise. Competitive moves center on strategic partnerships for quantum-resistant cryptography development and geographic expansion into Indo-Pacific navies seeking NATO interoperability.
Within the encryption-certified prime tier, Northrop Grumman Corporation and L3Harris Technologies exemplify U.S.-based vendors leveraging NSA accreditation to anchor Navy secure terminal programs. Thales Group occupies a parallel position in European procurement, representing French and British nationally certified encryption pathways. RTX Corporation sits within the frequency-hopping specialist archetype, sustaining positioning through waveform integration across multiple NATO platform classes.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| RTX Corporation |
| L3Harris Technologies |
| Leonardo |
| Honeywell International |
| General Dynamics Corporation |
| BAE Systems |
| Thales Group |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride amplifier substitution for legacy silicon LDMOS devices simultaneously shifts RF component sourcing toward Taiwan and South Korea foundries and compresses hardware cost structures for software defined radio platforms. This materials transition concentrates supplier pricing power with semiconductor fabricators while enabling firmware-upgradeable architectures to command procurement premiums over fixed-function hardware.
Pricing Analysis
Certification level (NSA Suite B versus nationally certified encryption modules) creates the primary spread between premium and standard tiers in naval tactical communication procurement. Three-tier pricing structure separates firmware-capable software defined radio platforms from frequency-hopping hardware systems and basic secure voice terminals. Pricing pressure stems from semiconductor supply concentration as gallium nitride foundry capacity constraints extend lead times for advanced RF components. Coastguard units and maritime security agencies exhibit highest price sensitivity due to commercial-off-the-shelf integration requirements, while naval information warfare commands prioritize latency performance over unit cost.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites strategic risk calculations for advanced RF semiconductor sourcing in naval communication programs. Component fabrication draws from Taiwan, South Korea, and United States foundry capacity for gallium nitride amplifiers and field-programmable gate arrays. Raw material dependencies span rare earth elements for magnetics, high-purity silicon substrates, and specialized ceramic packaging materials. Single-source vulnerability concentrates in Taiwan semiconductor fabrication for software defined radio baseband processors. Distribution runs through prime contractor integration facilities in San Diego, Norfolk, Portsmouth, and Toulon harbor districts before fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encryption certification fragmentation creates structural opportunity for specialized suppliers capable of bridging NSA and European national pathways. Divergent qualification timelines between U.S. and NATO agencies fragment procurement authority and open niches for mid-tier firmware developers.
For Market Incumbents: Secure NSA accreditation renewal timelines ahead of post-quantum cryptography mandate implementation to defend against emerging firmware specialists. Deepen backward integration into gallium nitride foundry partnerships to mitigate Taiwan supply concentration risk. Channel control through long-term service contracts for software defined radio waveform updates protects recurring revenue streams against hardware commoditization. For New Entrants and Emerging Players: Retrofit service capabilities for existing software defined radio platforms represent the most penetrable white-space target as defense agencies mandate quantum-resistant algorithm migration without full platform replacement. Indo-Pacific navies in Singapore and Vietnam seeking NATO STANAG interoperability offer geographic expansion opportunity with lower certification barriers than U.S. or European domestic procurement. Go-to-market positioning should emphasize firmware-only upgrade pathways that eliminate hardware swap costs during fleet modernization cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed radio manufacturers holding frequency-hopping expertise but lacking AI-enabled firmware capabilities. Five-to-ten year viability hinges on successful waveform programming talent acquisition and software defined radio platform transition. Acquisition targets should demonstrate existing NATO STANAG compliance to capture interoperability standardization tailwinds. The signal to watch is defense agency quantum-resistant cryptography procurement timeline acceleration as post-quantum algorithm finalization approaches.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Certification | NSA post-quantum algorithm mandates create retrofit service markets for existing software defined radio platforms. |
| AI-Enabled Spectrum Management Integration | Machine learning firmware development separates competitive tiers between cognitive radio suppliers and legacy hardware vendors. |
| Indo-Pacific Naval Export Expansion | Japan, Australia, and South Korea distributed maritime operations alignment drives mesh networking and satellite communication demand. |
| Backward Integration into RF Semiconductor Sourcing | Gallium nitride foundry partnerships mitigate Taiwan supply concentration vulnerability for advanced amplifier components. |
| NATO STANAG Waveform Convergence | Standardization enables single-platform multi-nation sales previously blocked by national encryption requirements. |
Research Methodology
Desk research of defense procurement databases, NATO standardization documents, and national signals intelligence regulations preceded structured interviews with naval program office directors, software defined radio firmware engineers, encryption module certification specialists, and prime contractor business development executives. Secondary validation drew from U.S. Navy Information Warfare Systems Command directives, European Defence Fund technology roadmaps, FCC spectrum allocation filings, and semiconductor trade flow data. Bottom-up platform deployment estimates across carrier, surface, submarine, and aviation communities were triangulated against top-down defense budget allocation analysis.
Variance decomposition across product type, technology architecture, application mission profile, and end-user procurement authority shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include hardware versus firmware-upgradeable platforms, NSA versus nationally certified encryption pathways, shipboard versus submarine versus airborne platform classes, and naval force versus coastguard versus maritime security agency customer types. CAGRs were derived from fleet modernization cycle timing, software refresh rate assumptions, and Indo-Pacific naval expansion program announcements. Industry-specific forecast inputs incorporated electromagnetic spectrum contestation intensity scenarios and quantum-resistant cryptography mandate implementation pacing.
Forecasts assume regulatory continuity in NSA Suite B certification pathways and European national encryption regimes; material policy shifts toward accelerated post-quantum algorithm mandates or divergent NATO STANAG interpretations would require re-modeling. Semiconductor supply disruption scenarios, particularly Taiwan foundry capacity constraints, represent primary forecast revision triggers. Practitioners should keep alternative scenarios live as defense agency procurement timeline acceleration and Indo-Pacific maritime domain awareness budget reallocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Coherent Radar Market