
 GNSS Smart Antenna Market | 2026-2036
GNSS Smart Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
GNSS Smart Antenna Market Insights
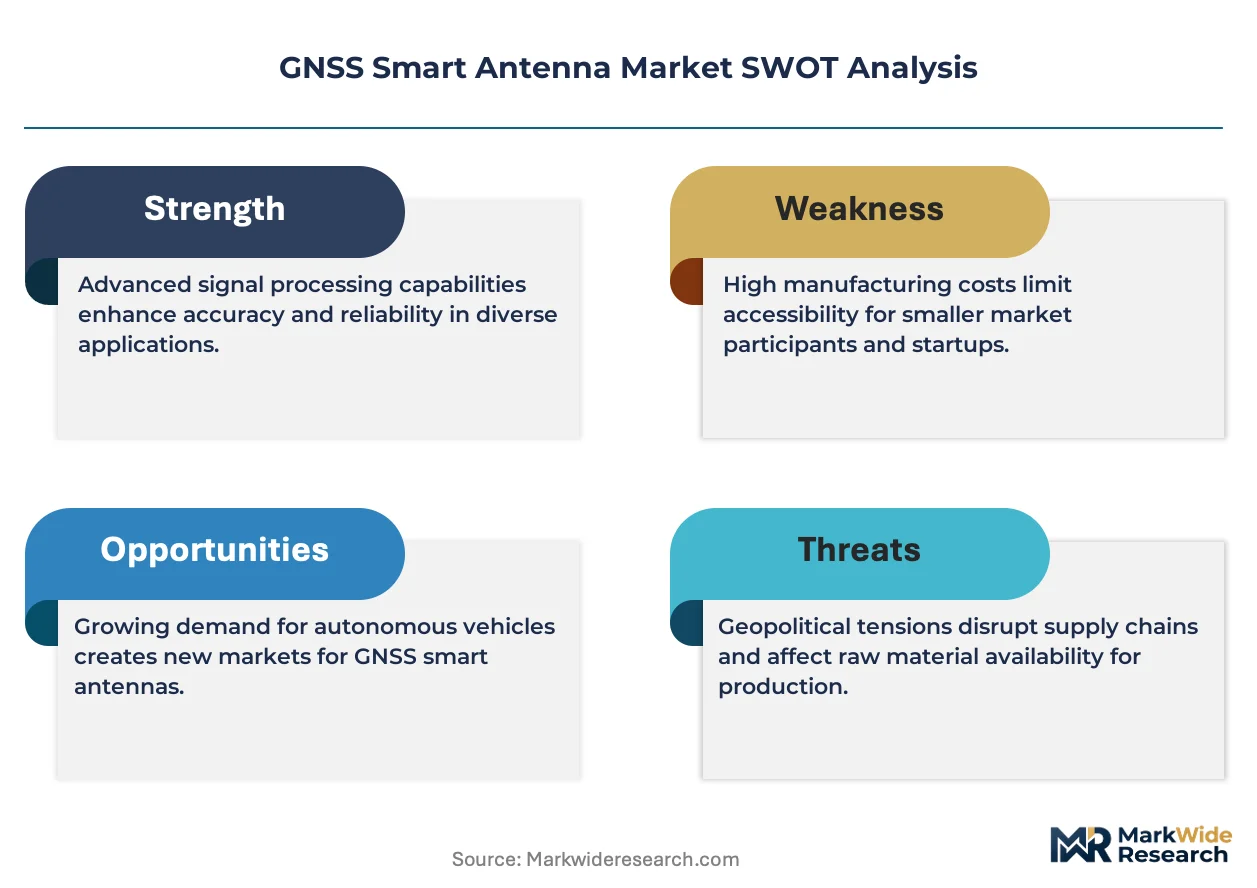
RF engineering talent is collapsing across European defense contractors, forcing antenna manufacturers to restructure hiring pipelines. Trimble Inc. leverages its agricultural channel dominance to bundle smart antennas with precision farming suites. Septentrio anchors its position through in-house ASIC design for multi-frequency signal processing. NovAtel competes on measurement-while-drilling contracts where centimeter-level reliability commands premium positioning.
A GNSS Smart Antenna integrates radiating elements with low-noise amplifiers, filtering stages, and often inertial measurement units into a single enclosure, typically operating across L1/L2/L5 bands with axial ratio below 3 dB to maintain circular polarization for satellite signal reception. Its primary purpose is delivering phase-stable, interference-resistant positioning to mobile platforms where discrete component assemblies fail on shock or space constraints. Dual-frequency antennas lead product-type revenue owing to ionospheric correction requirements in surveying and construction workflows, while integrated antennas capture the fastest expansion as drone OEMs spec compact modules with embedded IMUs. Software-defined technology is displacing fixed-correlator architectures, letting end users reconfigure constellation support through firmware rather than hardware swaps.
The EU Radio Equipment Directive and FCC Part 15 rules in the United States shape electromagnetic compatibility and out-of-band emission limits, directly filtering which antenna designs reach commercialization. EASA airworthiness mandates for commercial UAVs above 25 kg are pushing aerospace end users toward aviation-certified multi-constellation units. Japan's MIC radio certification adds another compliance layer for vendors targeting Asia-Pacific mobility contracts. Stakeholders must monitor spectrum reallocation proceedings at ITU and national regulators, as Ligado-adjacent bands and proposed L-band reassignments threaten interference budgets already strained by dense urban multipath.
Market Dynamics
Software-defined correlator architectures are collapsing the traditional hardware refresh cycle, letting fleet operators reconfigure constellation support through firmware uploads rather than physical antenna swaps. This shift compresses replacement revenue while expanding attach rates for subscription-based correction services.
Growth Catalysts
- EU Radio Equipment Directive tightening:Electromagnetic compatibility thresholds for antenna certifications are forcing design upgrades across precision agriculture and surveying equipment, creating mandatory replacement demand in Germany and France.
- Multi-constellation receiver procurement:Brazilian precision agriculture fleets are accelerating purchases of receivers tracking GPS, GLONASS, Galileo, and BeiDou simultaneously for canopy-penetrating signal resilience.
- Drone OEM specification shifts:Embedded IMU integration is becoming standard in compact modules for commercial UAV platforms above 25 kg, driven by EASA airworthiness mandates requiring aviation-certified positioning.
Market Restraints
- RF engineering talent scarcity:European defense contractors are absorbing available microwave design specialists, forcing antenna manufacturers to restructure university hiring pipelines or relocate R&D to lower-cost engineering clusters.
- L-band spectrum reallocation uncertainty:ITU proceedings on Ligado-adjacent bands and proposed L-band reassignments are freezing procurement decisions among precision agriculture buyers awaiting interference clarity.
- ASIC design capital intensity:In-house multi-frequency signal processing chip development requires sustained R&D commitments that exclude mid-tier vendors from performance leadership tiers.
Strategic Opportunities
- Aviation-certified multi-constellation units:EASA mandates for commercial UAVs above 25 kg are pushing aerospace end users toward certified antennas with dual-frequency ionospheric correction, opening premium positioning segments.
- Measurement-while-drilling contracts:Oilfield services are specifying centimeter-level reliability for downhole navigation, creating demand for shock-hardened antennas with phase-stable performance under vibration.
- Japan MIC radio certification leverage:Vendors obtaining Asia-Pacific mobility certifications can access construction automation and precision agriculture contracts requiring local regulatory compliance.
Industry Challenges
- Electromagnetic compatibility testing backlog:EU Radio Equipment Directive certification queues are extending product launch timelines, compressing revenue recognition windows for seasonal agriculture procurement cycles.
- Urban multipath interference budgets:Dense signal reflection environments in Stuttgart and Munich automotive corridors are demanding adaptive filtering algorithms that increase firmware complexity and validation cycles.
- Legacy discrete component integration:Mobile platforms transitioning from discrete antenna-amplifier-filter assemblies to integrated smart antennas face mechanical redesign costs and supply chain requalification.
Report Scope
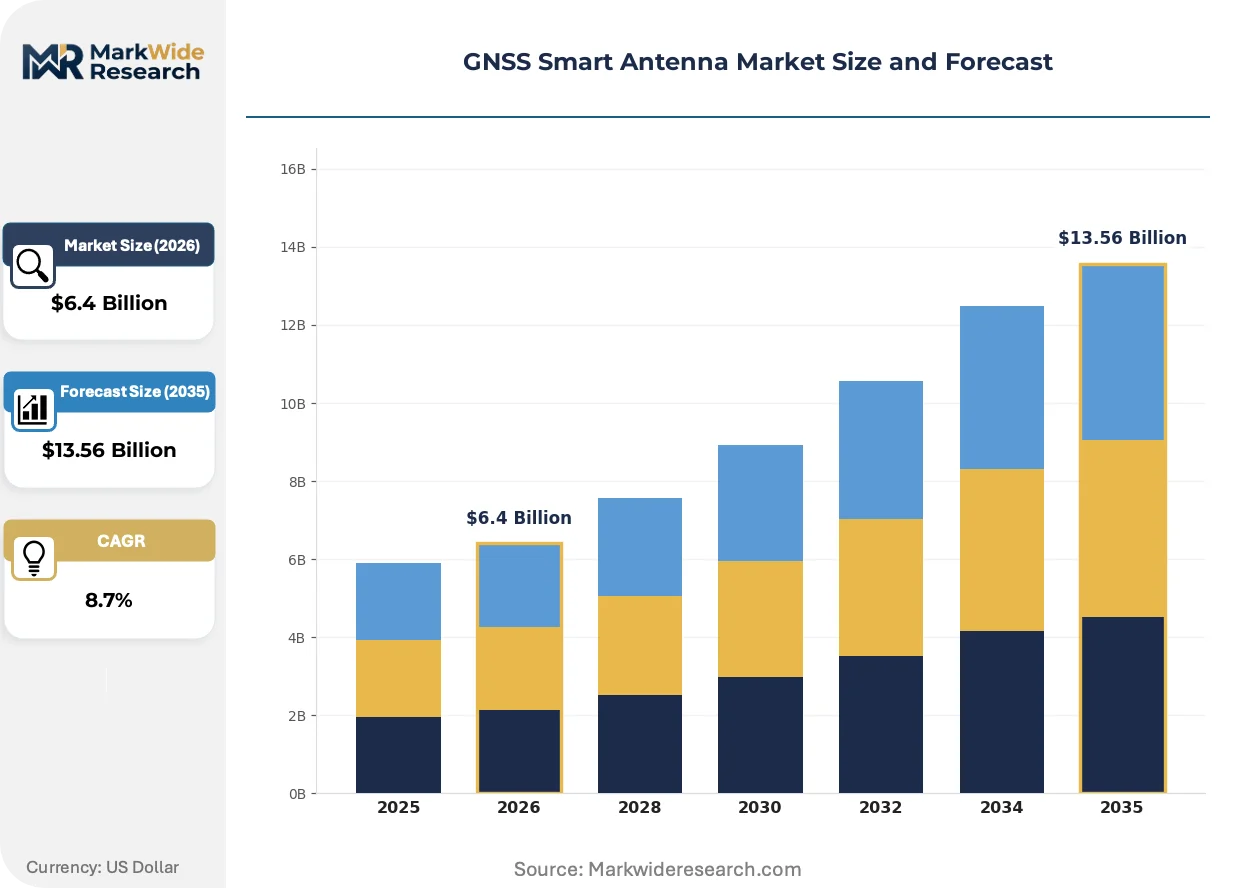
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GNSS Smart Antenna Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Cost Antennas, Geodetic Antennas, Dual-Frequency Antennas, Integrated Antennas End User: Aerospace, Automotive, Marine, Surveying Application: Navigation, Mapping, Geolocation, Timing Technology: Multi-Constellation, Active, Passive, Software-Defined |
| Companies Covered | Septentrio, NovAtel, Trimble Inc., comNav Technology, Southwest Antennas, SatLab Geosolutions, infiniDome, CHC Navigation, VectorNav Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GNSS Smart Antenna Market Trends and Innovations
Firmware-configurable signal processing is dissolving the boundary between hardware and service revenue, enabling antenna vendors to capture recurring value through correction service subscriptions rather than one-time equipment sales.
Software-defined radio architectures in GNSS smart antennas is bifurcating the installed base between fixed-function legacy units and reconfigurable platforms. Precision agriculture fleets in Brazil and Germany are adopting firmware-upgradeable receivers at accelerating pace. This technology is bifurcating vendor business models between hardware margins and recurring correction service revenue.
REACH restrictions on hazardous substances in electronic equipment are extending to antenna substrate materials and solder compositions, forcing redesigns of low-noise amplifier enclosures. Manufacturers serving EU mobility markets are qualifying halogen-free PCB laminates and lead-free assembly processes. Surveying equipment vendors face the steepest compliance costs due to outdoor exposure durability requirements.
Channel consolidation among precision agriculture dealers is concentrating antenna procurement decisions through bundled equipment financing. Trimble's agricultural channel dominance enables smart antenna attachment to precision farming suite sales. This pattern is most visible in Brazil's Mato Grosso soybean belt and Germany's Bavarian dairy automation corridors.
GNSS Smart Antenna Market Segmentation
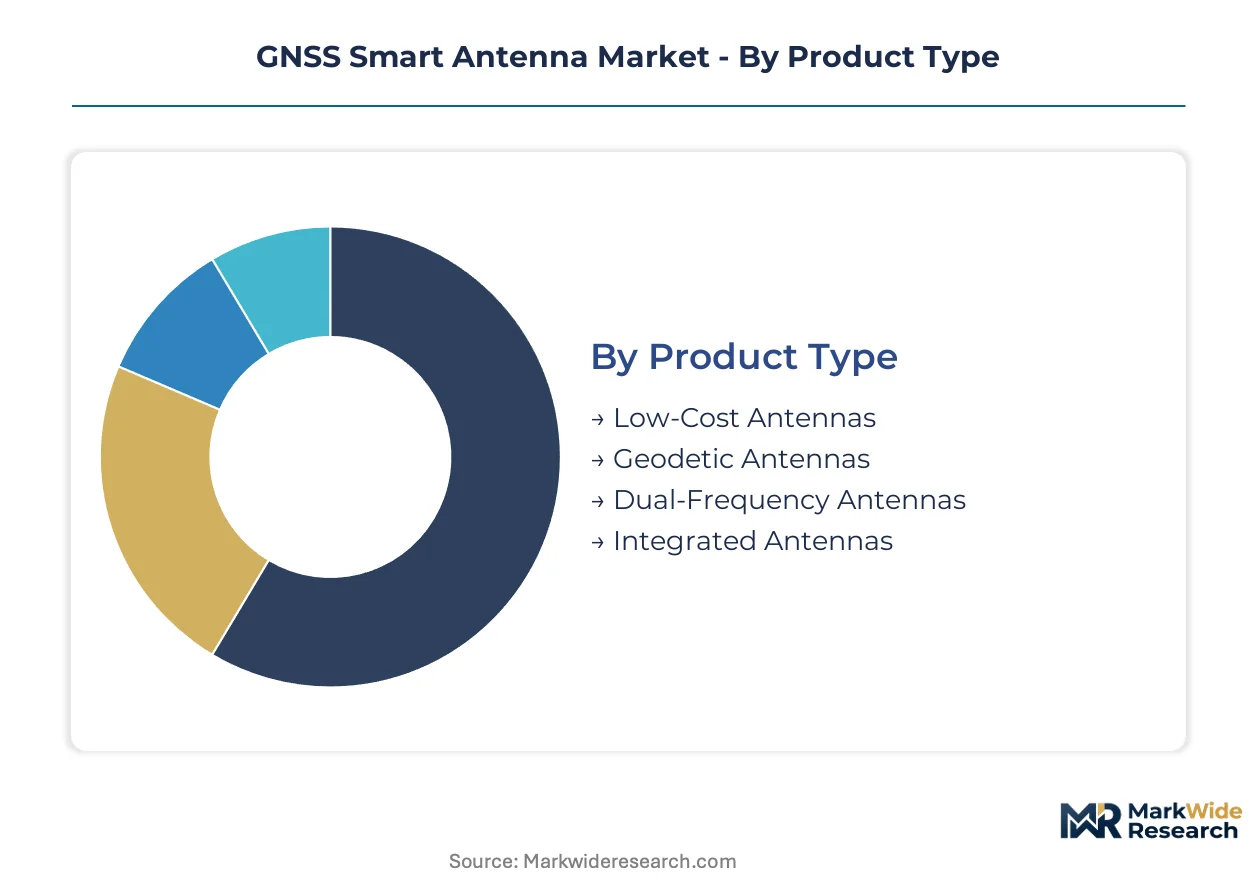
GNSS smart antenna procurement channels diverge sharply across precision agriculture dealerships, automotive tier-1 direct contracts, and aerospace certification pathways. Channel economics determine which antenna configurations achieve volume scale versus premium positioning.
Product Type:
Agricultural equipment dealers push bundled low-cost units to fleet operators, while automotive OEMs source geodetic-grade antennas through direct RFQ processes with stringent EMC validation.
- Dual-Frequency Antennas:These units combine L1/L2 or L1/L5 band reception with ionospheric correction algorithms for centimeter-level accuracy. Demand concentrates in Brazilian soybean belt surveying operations where canopy penetration requires signal redundancy across multiple frequencies.
- Integrated Antennas:Compact modules embed IMUs, filtering stages, and radiating elements in single enclosures. Drone OEMs above Stuttgart and Munich automotive corridors specify these for space-constrained UAV platforms facing EASA airworthiness mandates.
- Low-Cost Antennas:Single-frequency L1 receivers dominate emerging market agricultural mechanization through dealer financing bundles.
- Geodetic Antennas:Choke ring designs with sub-millimeter phase center stability serve reference station networks and scientific applications.
Dual-frequency antennas dominate installed base. Integrated antennas are where expansion concentrates.
End User:
Cost tiers stratify sharply: automotive contracts absorb EMC testing overhead for multi-constellation units, while marine buyers prioritize salt-spray corrosion resistance over signal processing sophistication.
- Automotive:Stuttgart and Munich corridor OEMs specify aviation-certified multi-constellation units with adaptive filtering for urban multipath. EU Radio Equipment Directive compliance costs are embedded in supplier RFQ terms.
- Aerospace:Commercial UAV platforms above 25 kg require EASA-certified antennas with embedded IMUs and dual-frequency ionospheric correction. Japan MIC radio certification adds procurement complexity for Asia-Pacific mobility contracts.
- Surveying:Geodetic-grade phase stability commands premium pricing in construction automation workflows.
- Marine:Salt-spray rated enclosures with multi-constellation tracking serve offshore positioning and fisheries monitoring.
Automotive volumes scale fastest. Aerospace margins sustain premium positioning.
Application:
Navigation deployments concentrate in mobile platforms where shock resistance matters; mapping applications demand post-processed kinematic precision that drives firmware subscription attach rates.
- Navigation:Real-time positioning for autonomous vehicle guidance and precision agriculture auto-steering. Brazilian Mato Grosso fleets deploy multi-constellation receivers for signal resilience under dense canopy.
- Mapping:Post-processed kinematic workflows in surveying and construction require geodetic-grade phase stability. Software-defined correlator architectures enable firmware-configurable constellation support without hardware swaps.
- Geolocation:Asset tracking and fleet management prioritize power efficiency over centimeter accuracy.
- Timing:Financial networks and telecommunications infrastructure demand nanosecond-level synchronization from disciplined oscillators.
Navigation commands unit volumes. Mapping drives service revenue expansion.
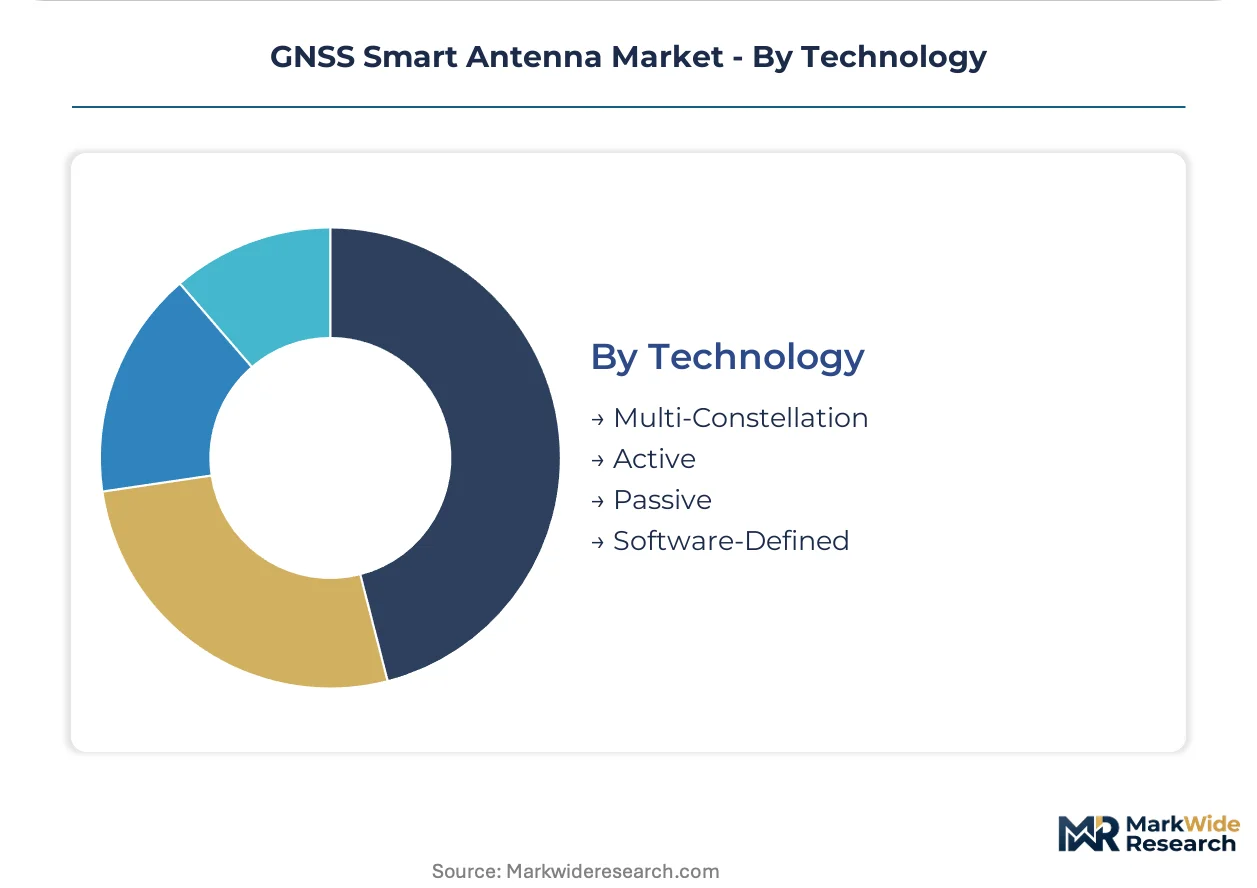
Technology:
Supply concentration favors vendors with in-house ASIC design capabilities; passive antenna architectures face margin compression as active and software-defined platforms capture specification shifts.
- Software-Defined:Reconfigurable correlator architectures collapse hardware refresh cycles through firmware uploads. Precision agriculture fleets in Brazil and Germany adopt these platforms for constellation flexibility without antenna replacement.
- Multi-Constellation:Simultaneous GPS, GLONASS, Galileo, and BeiDou tracking provides signal redundancy for canopy penetration and urban canyon resilience. REACH restrictions on substrate materials force PCB laminate redesigns for EU market access.
- Active:Integrated low-noise amplifiers and filtering stages serve mobile platforms with severe space constraints.
- Passive:Discrete radiating elements without amplification persist in cost-sensitive reference station deployments.
Multi-constellation anchors current procurement. Software-defined platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Radio Equipment Directive anchors European procurement standards, while Brazil's precision agriculture expansion and Japan's MIC certification requirements shape complementary demand poles across three continents.
Germany
Automotive OEMs in the Stuttgart and Munich corridors specify multi-constellation antennas with adaptive filtering for urban multipath resilience. The EU Radio Equipment Directive mandates electromagnetic compatibility thresholds that extend certification timelines for suppliers. Bavaria's dairy automation clusters are accelerating firmware-upgradeable receiver adoption through dealer financing bundles.
Brazil
Mato Grosso soybean belt fleets are procuring receivers tracking GPS, GLONASS, Galileo, and BeiDou simultaneously for canopy-penetrating signal redundancy. ANVISA equipment registration intersects with agriculture ministry mechanization incentives for precision farming adoption. São Paulo-based precision agriculture dealers are consolidating antenna procurement decisions through bundled equipment financing.
United States
FCC Part 15 rules govern out-of-band emission limits for commercial antenna designs reaching the North American market. Oilfield services in Texas and the Permian Basin are specifying shock-hardened antennas for measurement-while-drilling contracts demanding centimeter-level reliability. California's autonomous vehicle testing corridors are driving aviation-certified multi-constellation unit specifications.
Japan
METI industrial automation programs are channeling procurement toward construction automation and precision agriculture contracts requiring local regulatory compliance. MIC radio certification adds a mandatory compliance layer for vendors targeting Asia-Pacific mobility contracts. Kanto region electronics manufacturers are integrating compact modules with embedded IMUs for commercial UAV platforms.
GNSS Smart Antenna Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure bifurcating between ASIC-capable multi-frequency designers and firmware-configurable platform vendors. The upper tier commands premium positioning through in-house signal processing chip development and aviation certification pathways. Three archetypes dominate: integrated technology conglomerates with agricultural channel dominance, RF engineering specialists with defense heritage, and agile firmware-first entrants exploiting software-defined radio shifts. Competitive moves concentrate on strategic partnerships for correction service bundling and selective geographic certification leverage.
Within the integrated technology tier, Trimble Inc. and Septentrio exemplify divergent strategic positions—one leveraging agricultural channel dominance for bundled equipment financing, the other anchoring performance leadership through captive ASIC design. NovAtel occupies a position bridging precision agriculture and oilfield services, representing the specialist archetype with shock-hardened antenna credentials. These three entities collectively illustrate how vendor configuration spans channel control, semiconductor integration, and vertical application depth.
| Leading Market Players |
|---|
| Septentrio |
| NovAtel |
| Trimble Inc. |
| comNav Technology |
| Southwest Antennas |
| SatLab Geosolutions |
| infiniDome |
| CHC Navigation |
| VectorNav Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Brazilian precision agriculture fleets and multi-constellation receiver suppliers lock in both antenna supply access and price visibility across volatile raw material cycles. These arrangements concentrate procurement power with dealer networks in Mato Grosso while insulating manufacturers from spot-market gallium arsenide wafer fluctuations.
Pricing Analysis
Geographic price spreads between Stuttgart automotive corridor contracts and Mato Grosso agricultural bundles reach three-to-one multiples based on certification grade and EMC validation overhead. Three-tier pricing structure across aviation-certified, industrial-grade, and dealer-financed economy levels stratifies by ionospheric correction capability and IMU integration depth. Cost compression in economy tiers intensifies because REACH-compliant substrate materials add manufacturing overhead. Dealer-financed agricultural buyers in Brazil exhibit highest price sensitivity; aerospace OEMs in Germany absorb premium positioning for EASA-certified units.
Supply Chain Analysis
Strategic stockpiling of RF-grade ceramic substrates and gallium arsenide wafers dominates inventory strategy among antenna manufacturers facing extended EU Radio Equipment Directive certification queues. Supply concentrates in Taiwan for GaAs foundry capacity, Japan for high-frequency ceramic substrates, and Germany for precision machining of choke ring enclosures. Component dependencies include low-noise amplifier dies, multi-layer PCB laminates, and inertial measurement unit MEMS sensors. Single-source vulnerability in GaAs foundry capacity threatens production continuity. Distribution runs through precision agriculture dealer networks, automotive tier-1 direct contracts, and aerospace certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware-configurable correction service subscriptions are expanding faster than hardware unit sales, converting one-time antenna purchases into recurring revenue streams across Brazilian and German precision agriculture fleets.
For Market Incumbents: Secure aviation certification pathways for multi-constellation units before EASA mandates tighten for commercial UAVs above 25 kg. Deepen backward integration into GaAs foundry partnerships to insulate against single-source wafer supply disruption. Channel control through dealer financing bundles in Brazil's Mato Grosso belt defends position against firmware-first entrants. For New Entrants and Emerging Players: Firmware-upgradeable subscription gaps in mid-tier surveying equipment present white-space targets where incumbents under-serve construction automation workflows. Japan's MIC radio certification barrier filters competition for Asia-Pacific mobility contracts, creating the most penetrable geography. Partner with precision agriculture software platforms for embedded antenna specification rather than direct OEM sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined platform vendors with correction service attach rates exceeding hardware replacement cycles. Long-term viability favors ASIC-capable designers with in-house multi-frequency signal processing chip development. Target acquisition archetype: RF engineering specialists with defense heritage transitioning to commercial UAV certification. Watch ITU spectrum reallocation proceedings on Ligado-adjacent bands as inflection indicator for precision agriculture procurement freeze-thaw cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Aviation Certification Pathway | EASA compliance unlocks premium positioning for commercial UAV platforms above 25 kg. |
| ASIC Design Investment | In-house multi-frequency signal processing chips exclude mid-tier competitors from performance leadership. |
| Correction Service Bundling | Firmware-configurable subscriptions convert hardware sales into recurring revenue across Brazilian fleets. |
| Geographic Certification Leverage | Japan MIC radio certification opens Asia-Pacific construction automation and mobility contracts. |
| Dealer Channel Consolidation | Precision agriculture financing bundles in Germany and Brazil concentrate procurement decisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC Part 15 rulemakings, EASA airworthiness directives, and ITU spectrum allocation proceedings. Primary interviews engaged RF engineering directors at antenna manufacturers, precision agriculture dealer network managers, automotive OEM procurement leads, and aerospace certification specialists. Secondary validation drew from EU Radio Equipment Directive technical documentation, ANVISA equipment registration databases, and METI industrial automation program disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing across technology and application segments.
Segmentation dimensions modeled include product type, end user, application, and technology architecture across the analysis window. CAGRs derived from regression analysis of historical procurement patterns and projected replacement cycles for software-defined versus fixed-function installed bases. Industry-specific forecast inputs incorporated REACH compliance cost trajectories for halogen-free PCB laminates and firmware subscription attach rate assumptions for precision agriculture fleets.
Underlying assumptions cover sustained Brazilian soybean belt mechanization incentives and stable EU electromagnetic compatibility thresholds, with deviation risk concentrated in ITU L-band reallocation outcomes and GaAs foundry capacity constraints. Revision becomes warranted when spectrum interference proceedings cross regulatory decision thresholds or when single-source substrate supply disruptions exceed six-month continuity buffers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Defense Communication System Market