
 Dual Axis Gyro Stabilized Platform Market | 2026-2036
Dual Axis Gyro Stabilized Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Axis Gyro Stabilized Platform Market Insights
The EU Green Deal is repositioning defense and aerospace procurement criteria across European member states, compelling manufacturers to demonstrate lower energy consumption and reduced thermal signatures in stabilization systems. Safran leverages its integrated avionics portfolio to address these sustainability-linked specifications. Leonardo DRS anchors its competitive stance through deep specialization in electro-mechanical stabilization architectures for naval applications. KONGSBERG dominates Nordic and Baltic defense contracts with platform designs optimized for maritime navigation in extreme climates.
A dual axis gyro stabilized platform employs two orthogonal gimbal rings driven by gyroscopic sensors to isolate payloads from rotational disturbances across pitch and roll axes, typically achieving angular stabilization precision below 0.1 milliradians through closed-loop torque motor control. These systems serve critical functions in maintaining line-of-sight accuracy for surveillance optics, weapon targeting, and inertial reference frames under dynamic motion. Fiber optic gyroscope variants command premium positioning due to their immunity to electromagnetic interference and absence of moving parts, while MEMS gyroscope segments attract volume demand from autonomous vehicle developers seeking cost-scalable inertial units. Defense targeting applications sustain the deepest margin pools, though seismic monitoring represents an emerging structural growth vector as geophysical survey operators adopt portable high-precision platforms.
The U.S. Department of Defense mandates MIL-STD-810 environmental compliance and ITAR-controlled export protocols, which constrain supplier eligibility and shape product qualification timelines for international sales. EASA and FAA airworthiness standards for stabilized payloads aboard manned and unmanned aerial platforms further segment market access between certified and uncertified system tiers. Stakeholders must monitor evolving ITAR reciprocity agreements and emerging EU defense procurement localization requirements to calibrate manufacturing footprint and partnership strategies.
Market Dynamics
The EU Green Deal is compressing procurement timelines for defense and aerospace stabilization systems, compelling manufacturers to requalify existing platforms for energy efficiency and thermal signature reduction. This regulatory pressure is accelerating platform redesign cycles and reshaping supplier qualification criteria across European defense agencies.
Growth Catalysts
- MIL-STD-810 compliance mandates:U.S. Department of Defense environmental testing requirements sustain qualification-driven replacement demand for hardened stabilization platforms in tactical vehicles and maritime vessels.
- Precision agriculture:Autonomous spraying and surveying equipment in North American farming operations is absorbing MEMS-based gyro stabilized units for terrain-following optical systems.
- Fiber optic gyroscope immunity:Electromagnetic interference resilience in FOG variants supports penetration into power transmission monitoring and high-voltage substation inspection applications.
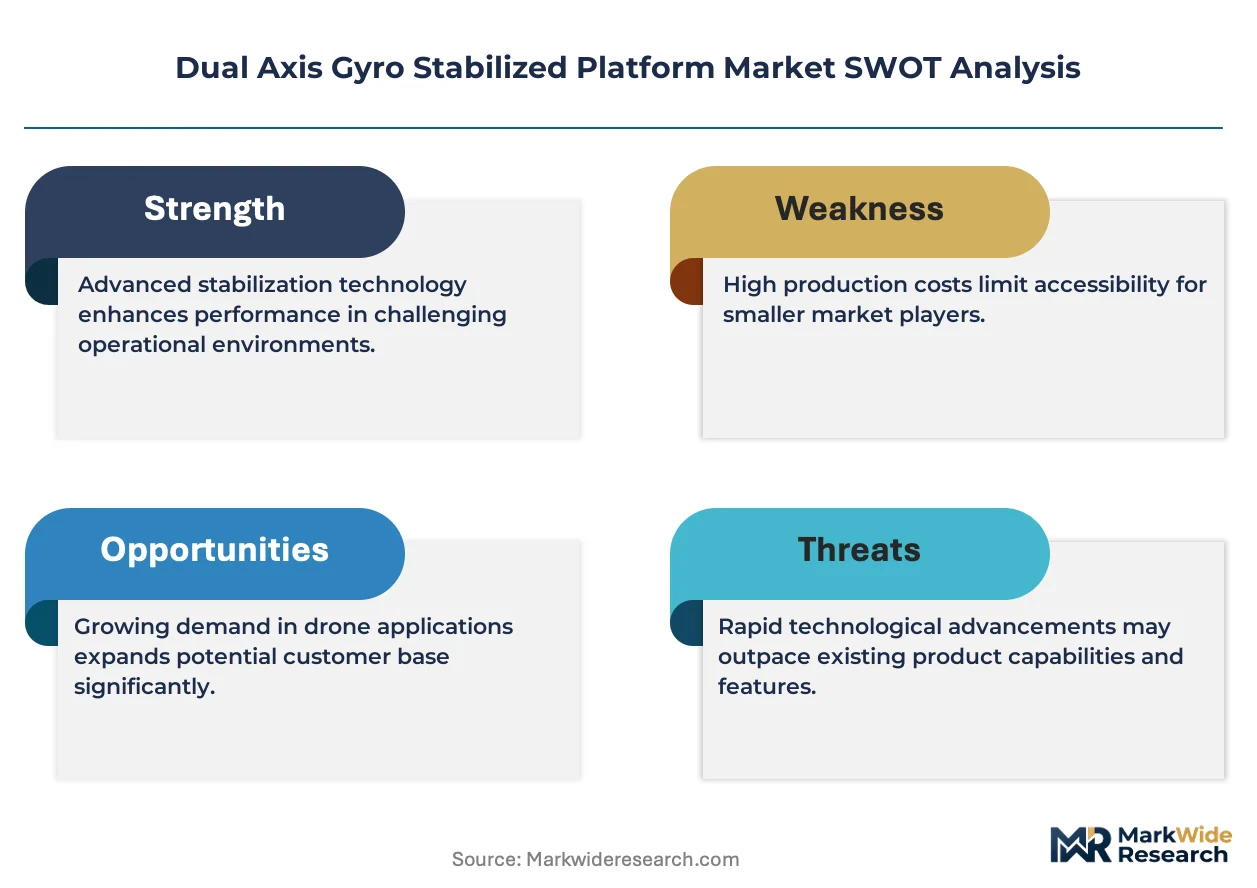
Market Restraints
- ITAR-controlled component sourcing:U.S. export control protocols restrict supplier eligibility for international platform sales, elongating procurement cycles for non-U.S. defense agencies.
- High-purity optical fiber cost volatility:FOG manufacturing depends on specialized fiber coils subject to supply concentration among Japanese and U.S. specialty fiber producers.
- MEMS drift limitations:Micro-electromechanical gyroscopes exhibit cumulative angle random walk that disqualifies them from long-duration maritime navigation without frequent recalibration.
Strategic Opportunities
- Seismic monitoring portability:Geophysical survey operators in remote terrain are adopting battery-powered dual-axis platforms for rapid-deployment subsurface imaging arrays.
- EU defense procurement localization:Emerging European Union requirements for domestic manufacturing content create entry pathways for regional engineering centers in Germany and France.
- Urban air mobility integration:Electric vertical take-off and landing developers are specifying compact stabilized gimbals for passenger monitoring and obstacle detection systems.
Industry Challenges
- Torque motor winding specialization:Precision gimbal manufacturing requires scarce electromagnetic design expertise concentrated among aerospace-tier suppliers.
- EASA airworthiness certification timelines:Stabilized payload approval for unmanned aerial platforms demands 18-36 month validation cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Axis Gyro Stabilized Platform Market |
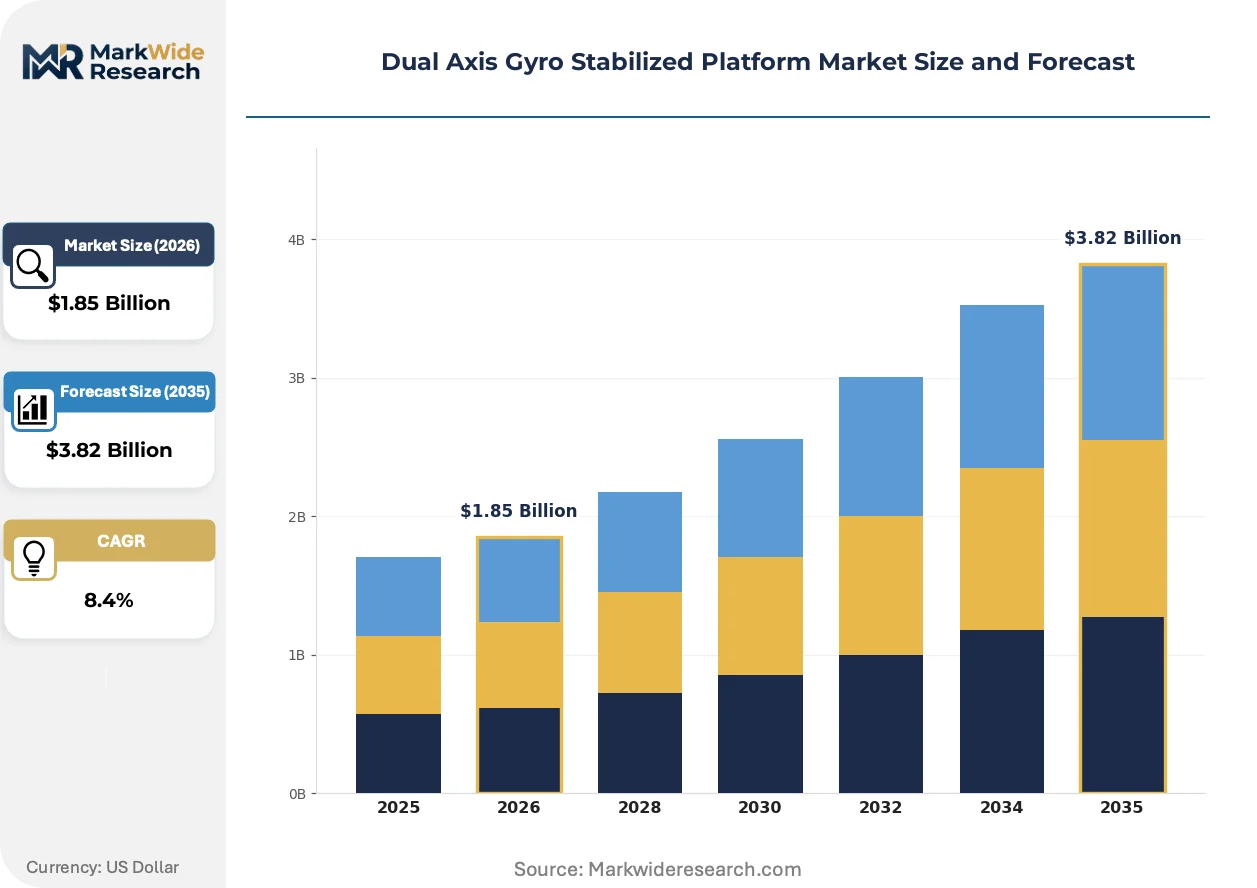
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Gyroscope, Optical Gyroscope, Fiber Optic Gyroscope, MEMS Gyroscope Technology: Inertial Navigation System, Electro-Mechanical Stabilization, Solid-State Stabilization, Piezoelectric Stabilization Application: Maritime Navigation, Aerial Surveillance, Defense Targeting, Seismic Monitoring, Autonomous Vehicles End User: Military Agencies, Aerospace Manufacturers, Research Laboratories, Oil Exploration Companies |
| Companies Covered | Northrop Grumman, Safran, Leonardo DRS, KONGSBERG, L3Harris Technologies, Teledyne FLIR, AeroVironment, Israel Aerospace Industries, ASELSAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Axis Gyro Stabilized Platform Market Trends and Innovations
Stabilization architecture is converging around solid-state sensing modalities while procurement patterns favor modular platform configurations. These shifts are compressing traditional electromechanical supply chains and elevating software-defined control strategies.
Fiber optic gyroscope technology is consolidating its position in high-reliability defense and aerospace applications through closed-loop digital signal processing architectures. Naval targeting system integrators are standardizing on FOG-based platforms for above-deck weapon stations exposed to electromagnetic pulse environments. This technology is consolidating vendor tiers by eliminating mechanical bearing maintenance requirements and compressing total cost-of-ownership calculations for 20-year service life programs.
EU Green Deal procurement amendments are mandating lifecycle carbon disclosure for defense platform subsystems including stabilization electronics. EASA technical specifications for electric aircraft are incorporating thermal efficiency metrics that disadvantage legacy brushed motor gimbal designs. German defense procurement offices are prioritizing platform suppliers demonstrating renewable energy sourcing for manufacturing operations.
Defense agencies are unbundling stabilization hardware from integrated weapon system contracts, creating direct procurement relationships with gimbal specialists. This channel disintermediation is displacing prime contractor markup structures in NATO member states and compressing delivery timelines for platform upgrades. The United Kingdom Ministry of Defence exemplifies this pattern through its Land Industrial Strategy sourcing frameworks.
Dual Axis Gyro Stabilized Platform Market Segmentation
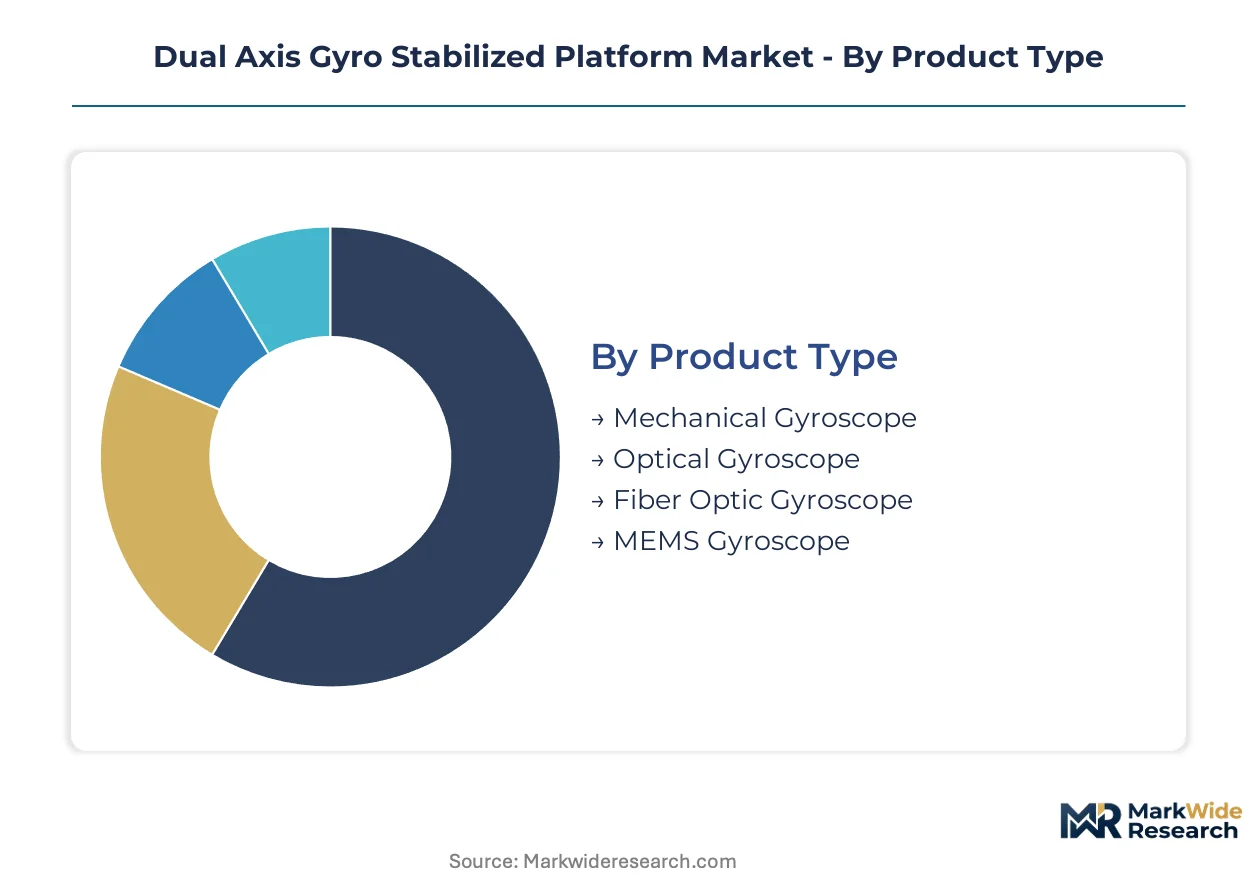
Dual axis gyro stabilized platforms serve divergent performance requirements across defense, commercial, and scientific end-uses. Segmentation reveals how procurement budgets, environmental tolerances, and accuracy specifications reshape supplier positioning and technology investment priorities.
Product Type:
Buyers in this category differentiate primarily by immunity to electromagnetic interference and tolerance for mechanical wear in extended deployments.
- Fiber Optic Gyroscope:Solid-state sensing coils eliminate moving parts while delivering sub-0.01 degree-per-hour bias stability. Naval weapon stations above deck specify FOG platforms for electromagnetic pulse resilience, with NATO maritime procurement driving qualification volumes. Japanese and U.S. specialty fiber producers constrain coil supply availability.
- MEMS Gyroscope:Silicon micromachined structures enable batch fabrication at unit costs an order of magnitude below optical alternatives. Autonomous vehicle developers in precision agriculture absorb volume shipments for terrain-following optical systems, though angle random walk accumulates error over extended maritime missions.
- Mechanical Gyroscope:Spinning mass architectures persist in legacy naval inertial reference systems requiring 20-year service life certification.
- Optical Gyroscope:Ring laser variants command aerospace tier positioning for strapdown navigation in manned aircraft platforms.
Fiber optic gyroscope platforms lead volumes today; MEMS gyroscope segments are gaining share fastest.
Technology:
Technology selection tracks the trade-off between software-defined control flexibility and proven electromechanical reliability in shock environments.
- Inertial Navigation System:Tight integration of gyroscopes, accelerometers, and Kalman-filtered position estimation enables standalone navigation without external references. Submarine and long-endurance unmanned underwater vehicle programs specify INS-integrated platforms for denied-GPS environments, with ITAR-controlled component sourcing elongating non-U.S. procurement cycles.
- Electro-Mechanical Stabilization:Torque motor-driven gimbal rings achieve sub-0.1 milliradian precision through closed-loop position feedback. Leonardo DRS anchors naval market positioning through deep specialization in these architectures for above-deck weapon stations.
- Solid-State Stabilization:Elimination of bearing assemblies compresses maintenance intervals and total cost-of-ownership calculations for 20-year programs.
- Piezoelectric Stabilization:Ceramic actuator responsiveness supports micro-radian precision for laboratory-grade optical bench applications.
Electro-mechanical stabilization dominates current procurement; solid-state stabilization is climbing the fastest.
Application:
Application segmentation reflects divergent motion profiles—from continuous wave-induced disturbance to transient shock—and corresponding accuracy thresholds.
- Defense Targeting:Line-of-sight maintenance under vehicle traverse and weapon recoil demands the tightest stabilization loops. U.S. Department of Defense MIL-STD-810 environmental compliance mandates sustain qualification-driven replacement demand for hardened platforms in tactical vehicles and maritime vessels.
- Maritime Navigation:Pitch and roll isolation in sea states up to severe conditions requires gyrocompass-grade heading reference. KONGSBERG dominates Nordic and Baltic defense contracts with platform designs optimized for extreme climate navigation.
- Aerial Surveillance:EASA and FAA airworthiness standards segment market access between certified and uncertified system tiers for manned and unmanned platforms.
- Seismic Monitoring:Portable battery-powered platforms enable rapid-deployment subsurface imaging arrays in remote terrain.
- Autonomous Vehicles:Cost-scalable inertial units support obstacle detection and passenger monitoring in electric vertical take-off and landing developments.
Defense targeting leads revenue concentration today; seismic monitoring shows the steepest expansion trajectory.
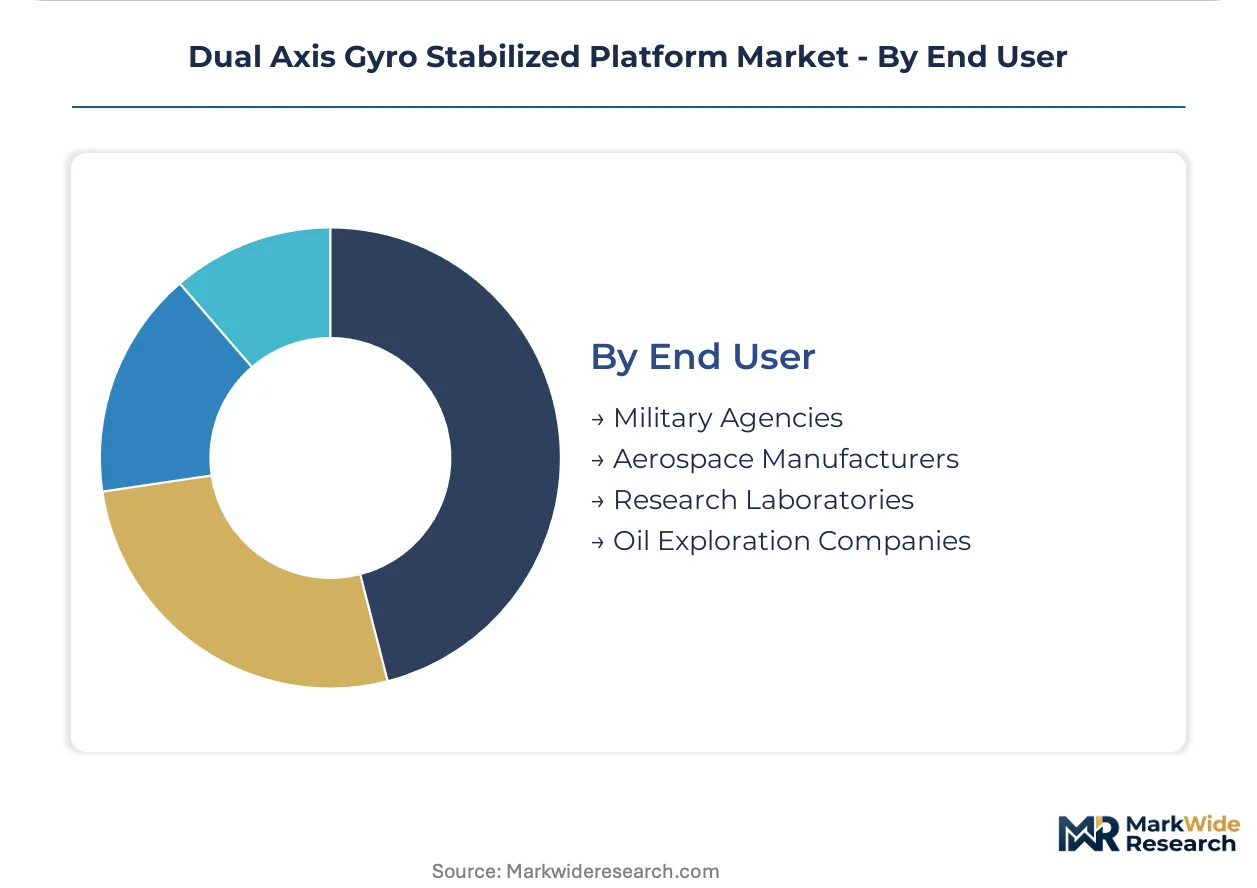
End User:
End user categories separate by procurement authority structures—centralized defense agency frameworks versus distributed commercial purchasing—and qualification burden tolerance.
- Military Agencies:Centralized procurement through NATO and national defense ministries concentrates volume in qualified supplier tiers. EU Green Deal amendments now mandate lifecycle carbon disclosure for stabilization subsystem procurement, compressing redesign cycles.
- Aerospace Manufacturers:Tier-1 integrators specify stabilized payloads for original equipment and retrofit programs, with EASA certification timelines demanding 18-36 month validation cycles.
- Research Laboratories:Small-batch procurement of laboratory-grade platforms prioritizes angular precision over environmental hardening.
- Oil Exploration Companies:Geophysical survey operators adopt portable platforms for subsurface imaging, with battery-powered configurations enabling remote deployment.
Military agencies anchor current demand; aerospace manufacturers are expanding share most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-axis gyro stabilized platforms trace their industrial lineage to post-war aerospace clusters in the United States and Western Europe, where precision gimbal manufacturing coalesced around defense procurement corridors. Contemporary demand distributes across specialized national programs with divergent certification regimes and climate specifications.
United States
Defense modernization programs and urban air mobility startups drive platform absorption across military and commercial channels. The FAA mandates airworthiness certification for stabilized payloads aboard electric vertical take-off and landing aircraft, compressing product validation timelines. Southern California and Greater Boston host dense concentrations of gimbal engineering talent serving both defense primes and autonomous vehicle developers.
Germany
Naval fleet upgrades and renewable energy inspection drones sustain procurement volumes for precision stabilization systems. The EU Green Deal compels lifecycle carbon disclosure for defense subsystem sourcing, reshaping supplier qualification criteria. Bavaria and Baden-Württemberg anchor manufacturing operations where engineering centers optimize platform designs for extreme climate resilience.
Japan
Seismic monitoring networks and power transmission infrastructure inspection create dual-use demand for electromagnetic-immune stabilization. METI technical standards for industrial drones specify gyroscopic payload performance thresholds that favor fiber optic variants. Tokyo-Osaka industrial corridors concentrate specialty optical fiber coil production essential for high-precision FOG manufacturing.
Israel
Border surveillance programs and export-oriented defense electronics sustain niche platform development for harsh desert environments. The national defense procurement office prioritizes ITAR-compatible supply chains for NATO-aligned sales. Tel Aviv and Haifa metropolitan areas host compact engineering clusters specializing in miniaturized gimbal architectures for unmanned aerial platforms.
South Korea
Maritime patrol modernization and autonomous surface vessel trials generate demand for naval-grade stabilization systems. MFDS-equivalent defense acquisition frameworks mandate domestic content thresholds that incentivize local assembly partnerships. Seoul Capital Area and Busan-Ulsan industrial zones concentrate system integration capabilities for regional export markets.
Dual Axis Gyro Stabilized Platform Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models in the dual-axis gyro stabilized platform sector. Integrated defense primes maintain captive foundry operations for torque motor windings and precision bearing assemblies, while specialized gimbal houses outsource component fabrication to concentrate on control algorithm development. The vendor base stratifies into three archetypes: vertically integrated aerospace conglomerates, electro-mechanical stabilization specialists, and solid-state sensing technology purveyors. Dominant competitive moves include strategic partnerships for ITAR-compliant international sales channels and geographic expansion into EU defense procurement localization zones.
Within the integrated defense tier, Northrop Grumman and L3Harris Technologies exemplify capital-intensive positioning through comprehensive platform-to-system integration capabilities. Safran occupies a distinctive position bridging European aerospace certification requirements with avionics portfolio synergies. Among electro-mechanical specialists, Leonardo DRS and KONGSBERG represent contrasting geographic anchors serving NATO maritime and Nordic extreme-climate specifications respectively. Israel Aerospace Industries and ASELSAN illustrate regional defense-industrial base models optimized for export-oriented production under national procurement frameworks.
| Leading Market Players |
|---|
| Northrop Grumman |
| Safran |
| Leonardo DRS |
| KONGSBERG |
| L3Harris Technologies |
| Teledyne FLIR |
| AeroVironment |
| Israel Aerospace Industries |
| ASELSAN |
| Others |
Pricing and Supply Chain Analysis
Specialty optical fiber coil pricing indices cascade through fiber optic gyroscope platform manufacturing, compressing margins at mid-tier suppliers while concentrating pricing power among Japanese and U.S. producers who captive-source precision winding operations. This raw-material cost structure stratifies the market into certification-grade premiums for defense procurement and volume-discounted MEMS alternatives for commercial autonomy developers.
Pricing Analysis
Project-based contract pricing with multi-year service bundles dominates defense procurement, separating ITAR-qualified platforms with MIL-STD-810 certification premiums from uncertified commercial tiers. Price differentiation hinges on electromagnetic interference immunity ratings and torque motor precision grades. Cost compression in MEMS-based units is intensifying as precision agriculture equipment manufacturers consolidate purchase volumes. Autonomous vehicle developers exhibit highest price sensitivity; naval weapon system integrators accept premium positioning for 20-year lifecycle guarantees.
Supply Chain Analysis
MIL-STD-810 and EASA airworthiness certification gates constrain supplier eligibility to a qualified tier with proven environmental testing records. Manufacturing concentrates in the United States, Germany, and Japan, with specialized optical fiber coil production anchored in Tokyo-Osaka industrial corridors. Torque motor winding expertise and high-purity fiber supplies constitute critical input dependencies. Single-source vulnerability in Japanese specialty fiber producers elevates supply risk. Distribution runs through prime contractor channels for defense applications and direct OEM relationships for commercial autonomy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dual axis gyro stabilized platform market functions as a regulatory compounder where EU Green Deal lifecycle carbon disclosure mandates are accelerating platform redesign cycles and requalification demand across European defense agencies.
For Market Incumbents: Deploy captive torque motor winding capacity to defend margin position against emerging solid-state stabilization substitutes. Deepen certification investment in EASA airworthiness pathways for urban air mobility integration. Consolidate ITAR-compliant international sales channels before EU defense procurement localization requirements harden.
For New Entrants and Emerging Players: Direct-to-defense-agency platform sales are disintermediating prime contractor markups in NATO member states. Target seismic monitoring portability applications where battery-powered rapid-deployment configurations face limited incumbent specialization. Pursue German engineering center partnerships to satisfy emerging domestic manufacturing content thresholds.
For Investors and Strategic Acquirers: Asymmetric upside sits with electro-mechanical stabilization specialists possessing proven naval above-deck weapon station qualifications. Long-term viability over the next decade rests on solid-state sensing technology transition readiness. Watch ITAR reciprocity agreement negotiations as the inflection signal for international sales channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Compliant International Channel Partnership | Unlocks NATO defense agency procurement beyond U.S. domestic programs. |
| Solid-State Stabilization R&D Investment | Eliminates bearing maintenance requirements for 20-year naval service life contracts. |
| EU Green Deal Carbon Disclosure Certification | Qualifies platforms for German and French defense procurement amendments. |
| Seismic Monitoring Product Line Extension | Captures geophysical survey operator demand for portable battery-powered arrays. |
| Torque Motor Winding Capacity Expansion | Secures scarce electromagnetic design expertise concentrated among aerospace-tier suppliers. |
Research Methodology
Multiple input streams — primary interviews with defense procurement officers, platform engineering directors, and naval system integrators; secondary validation through MIL-STD-810 qualification databases, EASA certification registries, and EU defense procurement frameworks; plus customs trade data for specialty optical fiber imports — were reconciled through bottom-up shipment analysis and top-down defense budget allocation triangulation.
Historical qualification volumes were cross-referenced against expert panel inputs on redesign cycle compression. The analytical framework models platform absorption across product type, technology architecture, application severity, and end-user procurement authority over the projection horizon. CAGRs were derived from segment-level qualification pipelines and replacement demand curves. Forecast inputs incorporate fiber optic gyroscope coil supply constraints and MEMS angle random walk limitations.
The model assumes a particular technology adoption path; alternative pathways for solid-state stabilization architectures would alter the outlook if electromagnetic interference resilience thresholds shift. Forecasts reflect assumptions on ITAR reciprocity progression and EU localization requirement implementation. Deviation in specialty optical fiber supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market