
 Airborne SATCOM Market | 2026-2036
Airborne SATCOM Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne SATCOM Market Analysis
Aftermarket service revenue is tilting toward integrated managed-network offerings as operators seek guaranteed uptime over hardware ownership. Viasat, Inc. leverages its vertically integrated satellite fleet to capture recurring service margins. L3Harris Technologies, Inc. anchors its position through classified military modem portfolios. Thales Group competes across both commercial aviation and defense channels with dual-use terminal architectures.
Airborne SATCOM denotes satellite communication systems installed on aerial platforms, typically operating across Ku, Ka, and X-band frequencies with phased-array or parabolic antennas to maintain links during dynamic flight profiles. These systems enable real-time broadband connectivity for cockpit data, passenger internet, and mission-critical military transmissions beyond terrestrial network reach. Terminal systems command the deepest integration complexity as platform-specific certification requirements extend development cycles. Military Use applications outpace commercial segments in R&D intensity due to anti-jam and low-probability-of-intercept specifications. Fixed Wing deployments dominate unit economics through higher passenger and payload densities that amortize terminal costs.
The FAA mandates SATCOM equipage for oceanic and remote airspace operations under NextGen performance standards, while EASA's connectivity regulations for commercial fleets accelerate retrofit timelines. The International Telecommunication Union coordinates spectrum allocation that directly constrains Ka-band expansion and terminal manufacturer roadmaps. Stakeholders must weigh proprietary constellation bets against interoperable open-architecture standards as the supplier landscape reconfigures around low-Earth-orbit and geostationary hybrid networks.
Market Dynamics
The Airborne SATCOM market is compressing around hybrid network architectures as low-Earth-orbit constellations force incumbent geostationary operators to restructure service models and terminal compatibility layers.
Growth Catalysts
- FAA NextGen Mandates:Oceanic and remote airspace equipage requirements under US performance-based navigation standards compel commercial fleet retrofits, expanding addressable terminal demand.
- Military ISR Modernization:Defense agencies prioritize beyond-line-of-sight connectivity for intelligence, surveillance, and reconnaissance platforms, driving Ka-band and X-band terminal procurement cycles.
- EASA Connectivity Regulations:European commercial aviation connectivity requirements accelerate retrofit timelines for narrow-body and wide-body fleets operating transcontinental routes.
Market Restraints
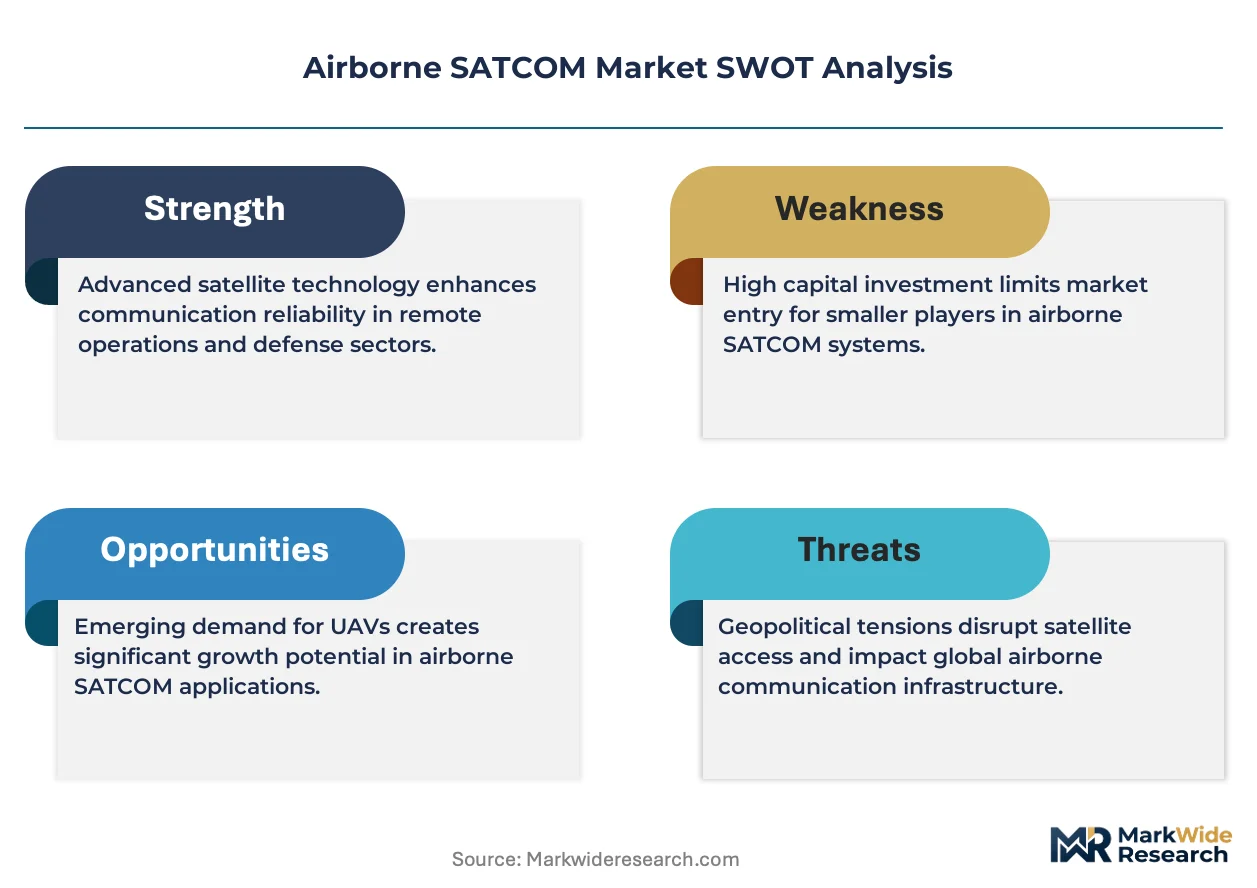
- Spectrum Allocation Friction:ITU coordination delays on Ka-band expansion constrain terminal manufacturer roadmaps and constellation deployment schedules.
- Platform-Specific Certification Burden:FAA and EASA airworthiness validation extends development cycles 18-36 months, freezing capital in non-recurring engineering.
- Input Concentration Risk:Gallium nitride power amplifier supply concentrates among specialized semiconductor foundries, creating single-source vulnerability for phased-array antenna production.
Strategic Opportunities
- Unmanned Aerial Systems Expansion:Beyond-visual-line-of-sight drone regulations in Germany and France open new terminal volume for tactical data-link applications.
- Dual-Use Terminal Architectures:Convergence of commercial aviation and defense specifications enables suppliers to amortize R&D across dual customer bases.
- Managed Network Services:Airlines and defense operators increasingly prefer guaranteed uptime contracts over capital-intensive hardware ownership, shifting revenue to recurring service models.
Industry Challenges
- Phased-Array Thermal Management:Active electronically scanned antenna integration demands specialized aerospace thermal engineering talent that remains scarce across US and European defense industrial bases.
- Interoperability Certification Complexity:Multi-constellation terminals must validate seamless handover between geostationary and low-Earth-orbit networks, multiplying test matrices and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne SATCOM Market |
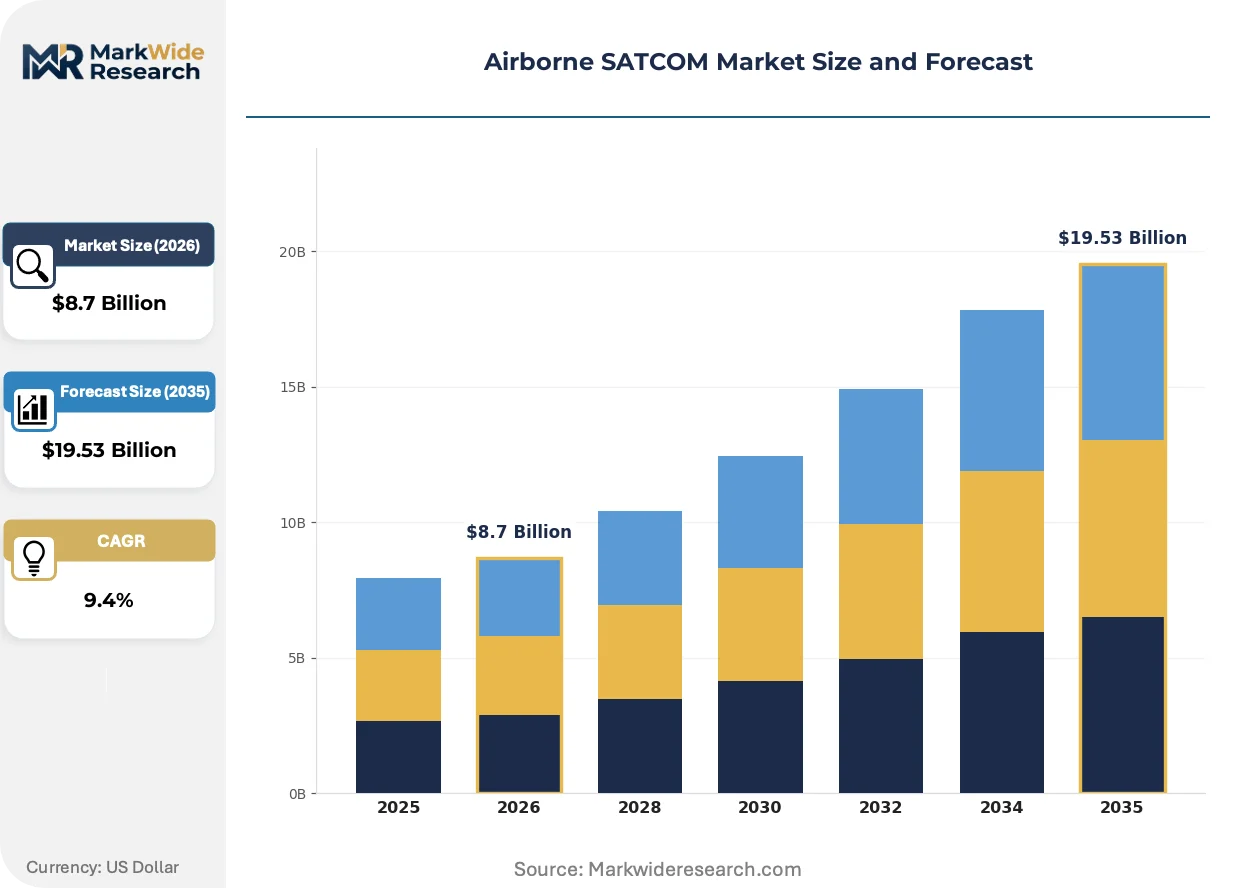
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Electronically Scanned Array, Phased Array, Parabolic Antenna, Terminal Systems Application: Commercial Aviation, Military Use, Emergency Services, Business Jets End User: Aerospace Manufacturers, Airline Operators, Defense Contractors, Private Aviation Firms Deployment: Fixed Wing, Rotorcraft, UAV, Others |
| Companies Covered | L3Harris Technologies, Inc., Thales Group, Viasat, Inc., General Dynamics Corporation, Honeywell International Inc., RTX Corporation, Northrop Grumman, Cobham Limited, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne SATCOM Market Emerging Trajectories
Software-defined payload architectures are displacing hardware-centric terminal designs, compressing upgrade cycles and enabling over-the-air capability insertion without physical retrofit.
Virtualized modem implementations are virtualizing baseband processing functions previously locked in proprietary ASICs, allowing military and commercial operators to field waveform updates via firmware rather than line-replaceable unit swaps. Defense procurement offices in the US and UK are piloting these architectures for rapid threat-response reconfiguration. The structural consequence is virtualizing supplier lock-in, as open-architecture interfaces commoditize hardware layers and shift value toward software stacks and security certification.
EU CSRD sustainability disclosure requirements are mandating lifecycle carbon accounting for satellite terminal manufacturing, compelling suppliers to document supply chain emissions from rare-earth extraction through end-of-life disposal. Aerospace OEMs in France and Germany now embed these specifications in supplier qualification criteria. Fixed-wing commercial aviation programs face the steepest compliance burden due to high production volumes and extended fleet service lives.
Consolidated procurement by ultra-low-cost carriers is compressing vendor management overhead into single-source managed connectivity contracts that bundle hardware, bandwidth, and maintenance. European and Southeast Asian budget airlines pioneered this model, displacing fragmented multi-vendor arrangements. The shift is most visible in narrow-body fleet deployments where passenger connectivity has transitioned from premium amenity to baseline operational expectation.
Airborne SATCOM Market Segmentation
Airborne SATCOM segmentation reveals divergent procurement rhythms across defense and commercial channels. Terminal refresh cycles stretch 7-10 years in military platforms versus 3-5 years for commercial fleet retrofits. Understanding these temporal patterns enables suppliers to align R&D pipelines with predictable replacement windows.
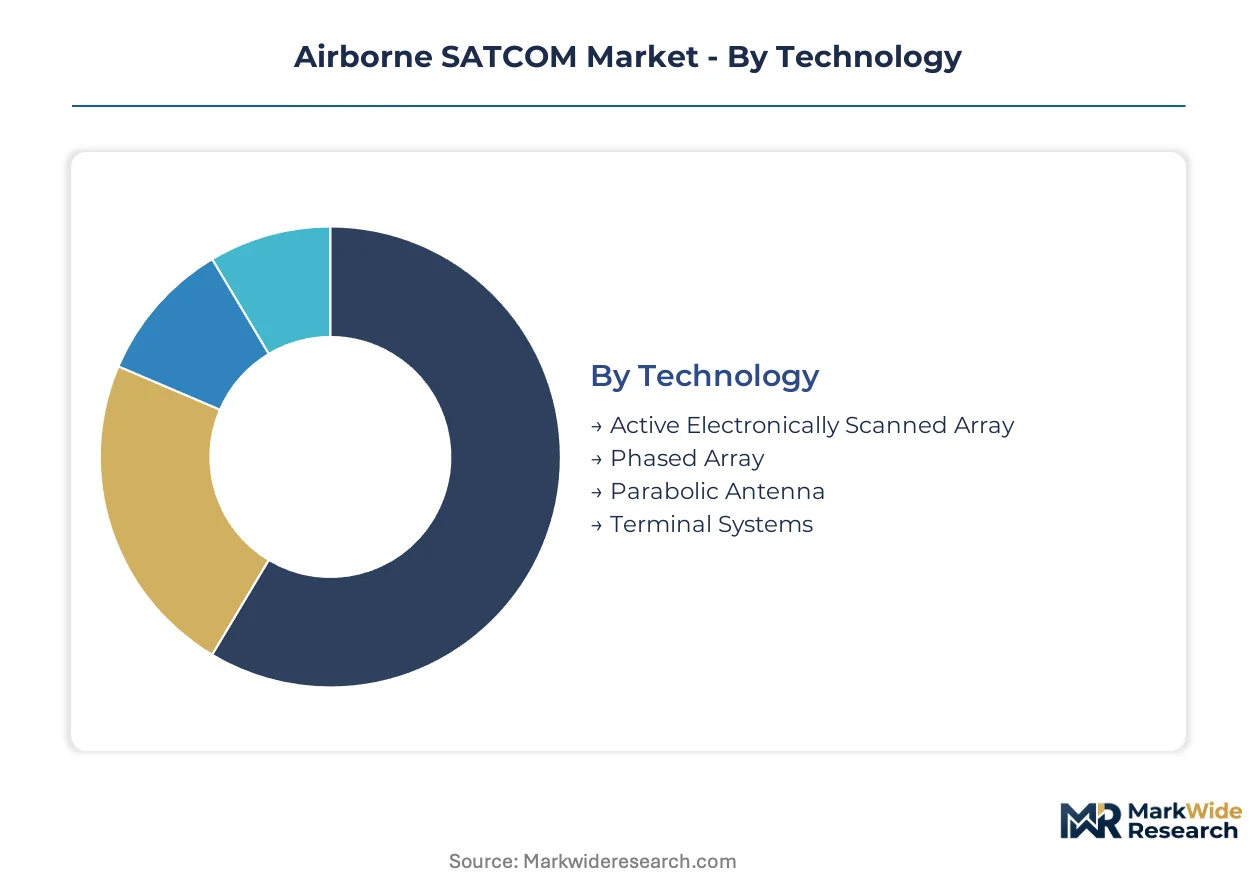
Technology:
Development velocity separates antenna architectures by certification burden and thermal engineering complexity.
- Active Electronically Scanned Array:Solid-state beam steering eliminates mechanical gimbals, enabling rapid frequency hopping for low-probability-of-intercept military waveforms. Demand concentrates in US and UK defense procurement for ISR platforms where anti-jam resilience justifies premium unit economics.
- Phased Array:Constrained electronic scanning trades field-of-regard for reduced power consumption and simpler thermal management. Commercial aviation retrofits in Germany and France favor this architecture for narrow-body installations where weight and cooling capacity are limited.
- Parabolic Antenna:Mechanical tracking systems dominate legacy military platforms and cost-sensitive regional airline configurations.
- Terminal Systems:Integrated modem-antenna packages command the longest non-recurring engineering cycles due to multi-constellation interoperability requirements.
Terminal Systems anchors the volume base while Active Electronically Scanned Array gains share at the steepest rate.
Application:
Procurement authority structures create distinct margin profiles across customer types with varying technical specification authority.
- Commercial Aviation:Passenger connectivity mandates from FAA NextGen and EASA regulations drive fleet-wide equipage decisions. Ultra-low-cost carriers in Southeast Asia consolidate procurement through managed service contracts that bundle hardware, bandwidth, and maintenance.
- Military Use:Classified modem portfolios and anti-jam specifications sustain specialized supplier relationships. US defense procurement prioritizes beyond-line-of-sight connectivity for intelligence, surveillance, and reconnaissance platforms.
- Emergency Services:Search-and-rescue helicopter fleets require hardened terminals for disaster-response coordination.
- Business Jets:Owner-operators prioritize cabin internet experience over cockpit data-link redundancy.
Commercial Aviation generates the largest addressable terminal population while Military Use commands the highest unit margins.
End User:
Supply chain position determines whether procurement emphasizes design collaboration or aftermarket service reliability.
- Aerospace Manufacturers:Boeing and Airbus line-fit programs require 18-36 month advance terminal qualification cycles.
- Airline Operators:Retrofit decisions respond to passenger connectivity satisfaction metrics and fuel-burn tradeoffs.
- Defense Contractors:Lockheed Martin and Northrop Grumman integrate terminals into platform-specific mission systems with classified interface requirements.
- Private Aviation Firms:Fractional ownership fleets standardize on single-source connectivity providers to simplify logistics.
Airline Operators drive the highest annual terminal volume while Defense Contractors sustain the most durable supplier relationships.
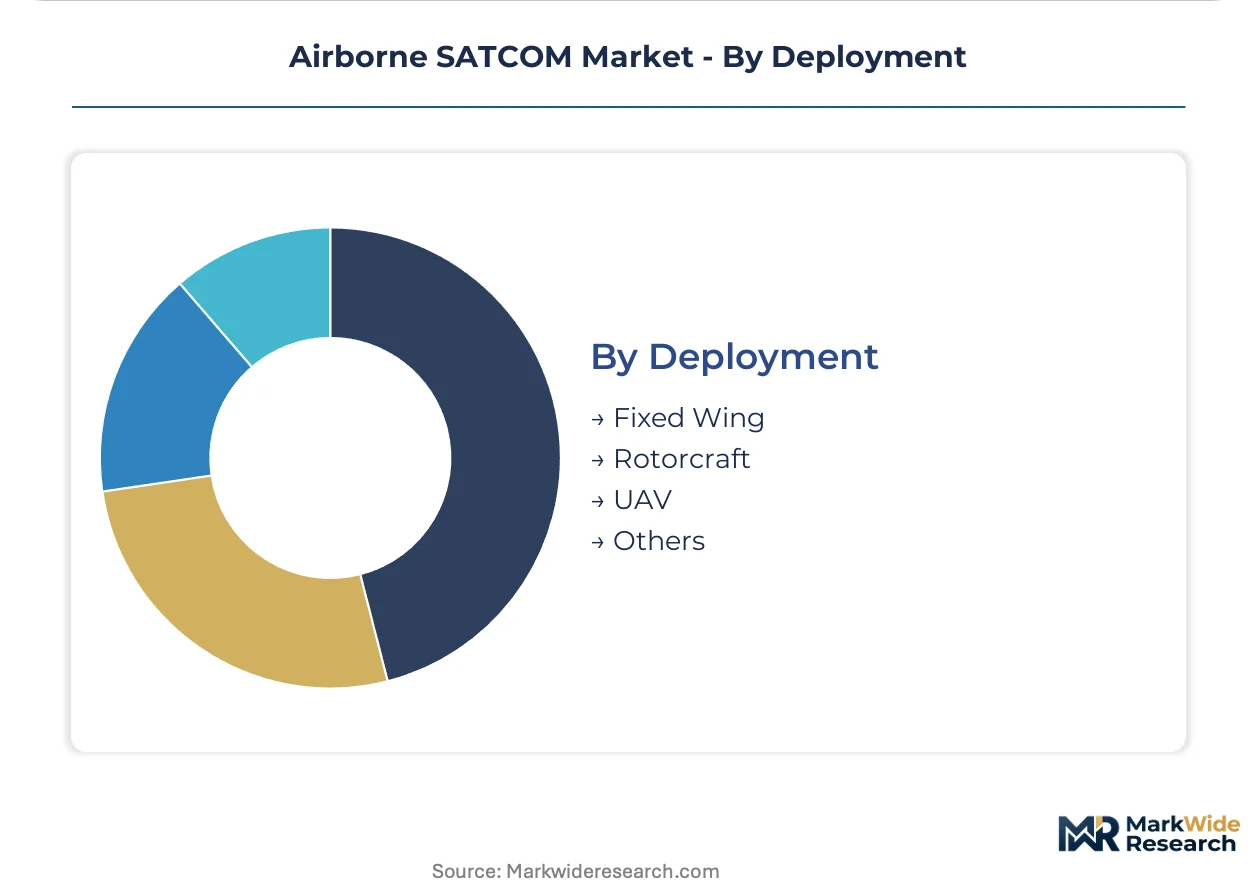
Deployment:
Platform kinematics dictate antenna tracking performance requirements and installation envelope constraints.
- Fixed Wing:Higher passenger and payload densities amortize terminal costs across greater seat-mile volumes. Wide-body deployments in US and European flag carriers justify Ka-band broadband investments with predictable utilization rates.
- Rotorcraft:Blade modulation and hover dynamics demand specialized stabilization algorithms. Emergency medical services in Germany and France represent concentrated demand for reliable beyond-line-of-sight coordination.
- UAV:Beyond-visual-line-of-sight regulations in Germany and France open tactical data-link terminal volume.
- Others:Stratospheric platforms and aerostats occupy nascent regulatory territory with undefined certification pathways.
Fixed Wing anchors the volume base while UAV gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement intensity distinguishes national consumption patterns. The United States prioritizes classified military modem portfolios with anti-jam specifications. Germany and France emphasize dual-use terminal architectures serving both commercial aviation retrofit mandates and tactical unmanned systems. Japan concentrates on line-fit qualification cycles for aerospace OEM integration.
United States
The Pentagon's ISR modernization programs drive Ka-band and X-band terminal procurement for intelligence platforms. FAA NextGen mandates compel oceanic equipage across commercial fleets, expanding addressable hardware demand. Defense contractors in the Baltimore-Washington corridor integrate classified modems into mission-specific airborne platforms.
Germany
Beyond-visual-line-of-sight drone regulations open tactical data-link terminal volume for unmanned systems operators. EASA connectivity requirements accelerate narrow-body fleet retrofits at Lufthansa Group and budget carriers. Aerospace suppliers in Bavaria specialize in phased-array thermal engineering for weight-constrained installations.
France
Thales Group anchors dual-use development serving both commercial aviation and defense channels. ANSM and military procurement offices coordinate spectrum allocation for emergency services helicopter fleets. Toulouse's aerospace cluster hosts terminal qualification programs for Airbus line-fit integration cycles.
United Kingdom
The Ministry of Defence pilots software-defined payload architectures for rapid threat-response reconfiguration. CSRD sustainability disclosures mandate lifecycle carbon accounting for terminal manufacturing supply chains. Defense procurement in Bristol and Stevenage concentrates on low-probability-of-intercept waveform specifications.
Japan
METI coordinates domestic satellite constellation participation to reduce dependence on foreign bandwidth providers. Commercial aviation operators retrofit narrow-body fleets for passenger connectivity on transoceanic routes. Aerospace manufacturers in Nagoya advance terminal qualification for Boeing and Airbus subcontractor integration.
Airborne SATCOM Market Vendor Landscape
Capability concentration sits with defense-specialized tier suppliers possessing classified modem portfolios and anti-jam certifications; scale advantage sits with vertically integrated satellite operators controlling captive bandwidth supply. The market structures around three archetypes: satellite fleet owners capturing recurring service margins, defense primes anchoring classified military programs, and dual-use terminal architects amortizing R&D across commercial and government customers. Consolidation pressures intensify as low-Earth-orbit constellations force incumbent geostationary operators to restructure compatibility layers and service models.
Among US-based defense contractors, L3Harris Technologies, Inc. and RTX Corporation occupy positions within the classified military modem tier, exemplifying suppliers whose customer relationships extend through platform-specific mission system integration. Thales Group represents the dual-use architecture archetype, with its French corporate structure supporting concurrent commercial aviation and defense channel access. These three companies anchor the competitive landscape's capability-intensive segment, where security certification and proprietary waveform libraries create durable supplier positioning.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Thales Group |
| Viasat, Inc. |
| General Dynamics Corporation |
| Honeywell International Inc. |
| RTX Corporation |
| Northrop Grumman |
| Cobham Limited |
| Collins Aerospace |
| Others |
Supply Flow & Price Mechanics
Overcapacity in gallium nitride power amplifier foundries across Taiwan and the United States compresses supplier margins while extending procurement leverage to terminal manufacturers seeking multi-source qualification. This utilization slack feeds directly into pricing posture, as phased-array antenna producers negotiate volume commitments against guaranteed capacity reservation.
Pricing Analysis
Long-term managed service contracts dominate procurement structures, with airlines and defense agencies favoring guaranteed uptime subscriptions over capital-intensive hardware purchases. Price differentiation rests on certification tier—FAA and EASA airworthiness validation commands substantial premiums—and on bandwidth reservation scale, with constellation owners capturing recurring margins through committed information rate tiers. Pricing pressure stems from low-Earth-orbit constellation entrants forcing incumbent geostationary operators to restructure service models. Ultra-low-cost carriers exhibit the highest price sensitivity, prioritizing bundled connectivity over performance specifications, while military procurement offices accept premium positioning for anti-jam and low-probability-of-intercept waveform libraries.
Supply Chain Analysis
Upstream feedstock concentration in compound semiconductor substrates draws from Japan, Germany, and the United States for gallium arsenide and gallium nitride wafer supply. Raw material dependencies center on rare-earth elements for magnet components, specialized ceramics for thermal management substrates, and aerospace-grade aluminum alloys for antenna housings. Single-source vulnerability pervades active electronically scanned array module production, where qualified foundry capacity concentrates among defense-cleared suppliers. Distribution runs through aerospace OEM line-fit programs and aftermarket retrofit channels, with terminal qualification cycles extending 18-36 months for platform-specific integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Airborne SATCOM market exhibits cyclical recovery characteristics as defense ISR modernization programs and commercial fleet retrofit mandates converge, with FAA NextGen compliance deadlines and EASA connectivity regulations synchronizing procurement waves across customer segments.
For Market Incumbents: Harden classified modem portfolio positions through accelerated software-defined payload certification, countering emerging open-architecture entrants seeking to commoditize hardware layers. Prioritize backward integration into gallium nitride power amplifier supply through captive foundry investment or long-term capacity reservation agreements, mitigating single-source concentration risk that threatens production continuity.
For New Entrants and Emerging Players: Tactical unmanned systems terminals for beyond-visual-line-of-sight operations in Germany and France represent the most penetrable entry point, as regulatory clarity opens procurement volume absent entrenched supplier relationships. Dual-use terminal architectures amortizing R&D across commercial aviation and defense channels offer the strongest go-to-market angle, leveraging EASA retrofit mandates to establish reference accounts for subsequent military qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated satellite operators controlling captive bandwidth supply, where managed service contracts generate durable cash flows insulated from terminal hardware commoditization. Long-term viability across the projection horizon favors suppliers with software-defined payload architectures and security certification moats. The signal to watch is ITU Ka-band allocation rulings, as spectrum expansion decisions will reconstitute addressable terminal demand and constellation deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Certification | FAA and EASA validation accelerates threat-response reconfiguration for defense procurement offices. |
| Managed Network Service Expansion | Guaranteed uptime contracts shift revenue from hardware sales to recurring service margins with airlines. |
| Dual-Use Terminal Architecture Development | Thales Group exemplifies amortizing R&D across commercial aviation and military ISR platforms. |
| Gallium Nitride Foundry Integration | Captive power amplifier supply mitigates single-source vulnerability in phased-array production. |
| Open-Architecture Modem Partnership | Virtualized baseband processing commoditizes hardware layers and shifts value toward security certification. |
Methodological Framework
Desk research of satellite operator capacity disclosures, defense procurement databases, and aviation regulatory filings preceded structured interviews with terminal engineering directors, airline connectivity procurement managers, military program office leads, and phased-array thermal engineering specialists. Primary intelligence combined with secondary validation against FAA NextGen implementation schedules, EASA certification bulletins, and ITU spectrum coordination records. Bottom-up terminal deployment estimates triangulated against top-down constellation bandwidth demand projections.
Assumptions held fixed include ITU Ka-band allocation timelines and existing defense procurement authority structures, while variables spanned low-Earth-orbit constellation deployment velocity and commercial aviation retrofit penetration rates. Segmentation modeling incorporated antenna architecture, application channel, end-user procurement position, and platform deployment type. CAGRs derived from replacement cycle analysis across military and commercial refresh windows, with inputs including platform-specific certification duration and gallium nitride foundry capacity expansion announcements.
Practitioners should monitor ITU spectrum rulings, defense budget authorization cycles, and gallium nitride foundry utilization rates for early signals requiring forecast revision. Cross-checking against satellite operator bandwidth pricing disclosures and aerospace OEM delivery schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market