
 Global Natural Gas Fired Electricity Generation Market | 2026-2036
Global Natural Gas Fired Electricity Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Gas Fired Electricity Generation Market Intelligence
The European Union's Green Deal, which classifies certain natural gas projects as transitional activities, is expanding the investment framework for new generation capacity. GE Vernova leads in high-efficiency gas turbine technology, particularly for large-scale combined cycle plants. Siemens Energy AG competes with a comprehensive portfolio of generation equipment and services. Meanwhile, Shell plc leverages its extensive natural gas supply chain to develop integrated power projects.
Natural gas fired electricity generation is a process that combusts natural gas to power a turbine connected to an electric generator. The most efficient configurations use a combined cycle gas turbine (CCGT) system, which captures waste heat to produce additional steam-driven power. Combined Cycle technology dominates new installations for base load power applications due to its superior thermal efficiency. In contrast, open cycle plants serve critical peaking power roles, offering rapid start-up capabilities.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) dictate stringent emissions standards. In Europe, the EU's Industrial Emissions Directive further shapes operational permits and technology requirements for large combustion plants. Utilities and independent power producers must now weigh investments in new gas assets against future hydrogen-blending mandates and carbon capture feasibility.
Market Dynamics
The central structural force shaping the market is the dual role of natural gas as both a bridge fuel displacing coal and a target for long-term decarbonization. This tension creates investment uncertainty, as regulatory frameworks from the US EPA and China's MEE demand cleaner operations while policies like the EU Green Deal signal a finite lifespan for unabated fossil fuels.
Growth Catalysts
- Policy Frameworks:The European Union's classification of certain natural gas projects as transitional activities under its Green Deal unlocks new financing streams for CCGT plant development, supporting grid stability during the energy transition.
- Regulatory Pressure:Stringent emissions standards for coal-fired power plants, enforced by the US Environmental Protection Agency, accelerate the retirement of coal assets and their replacement with more efficient, lower-emitting natural gas generation.
- Industrial Demand:Manufacturing sectors in China are driving investment in on-site gas-fired generation to ensure power reliability and meet air quality targets under the national 'dual carbon goals' policy.
Market Restraints
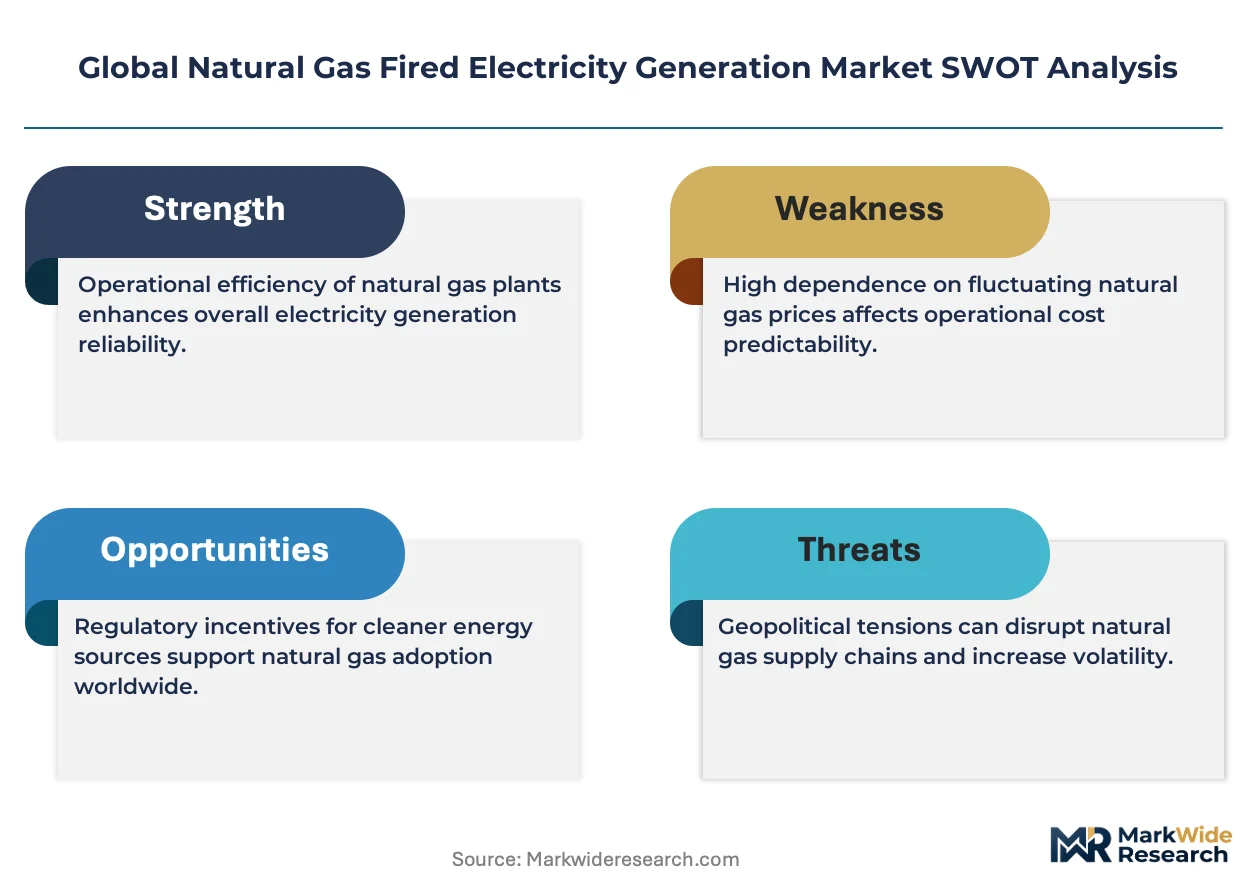
- Input Cost Volatility:Fluctuations in global natural gas prices create significant operational cost uncertainty for power producers, impacting electricity tariffs and the profitability of gas-fired assets compared to sources with stable fuel costs.
- Substitution Threat:The falling costs of utility-scale solar and wind generation, increasingly paired with battery energy storage systems, directly compete with natural gas plants for both baseload and critical peaking power roles.
- Regulatory Risk:Future mandates for hydrogen blending or the retrofitting of carbon capture technology introduce substantial long-term investment risk, potentially stranding assets built without such capabilities.
Strategic Opportunities
- Technology Convergence:Integrating new CCGT plants with carbon capture, utilization, and storage (CCUS) technologies provides a pathway to develop low-carbon, dispatchable power generation that can comply with future emissions regulations.
- Asset Repurposing:Retrofitting existing natural gas turbines for hydrogen co-firing presents a significant opportunity to decarbonize the existing generation fleet, extending asset life and leveraging current infrastructure.
- Geographic Expansion:Developing nations in Southeast Asia and parts of Africa require new, reliable power sources to support economic growth, creating demand for efficient gas-fired plants to replace aging fossil fuel infrastructure.
Industry Challenges
- Capital Expenditure Intensity:The high upfront capital investment required for constructing new, high-efficiency combined cycle gas turbine plants, particularly those designed to be CCUS-ready, remains a significant barrier for developers.
- Grid Integration Complexity:Integrating flexible gas generation to balance the intermittency of renewables requires sophisticated grid management systems and upgrades to transmission infrastructure, adding cost and complexity to projects.
- Compliance Timelines:Meeting evolving emissions standards from regulators like China's Ministry of Ecology and Environment necessitates continuous investment in monitoring systems and abatement technologies throughout a plant's operational life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Gas Fired Electricity Generation Market |
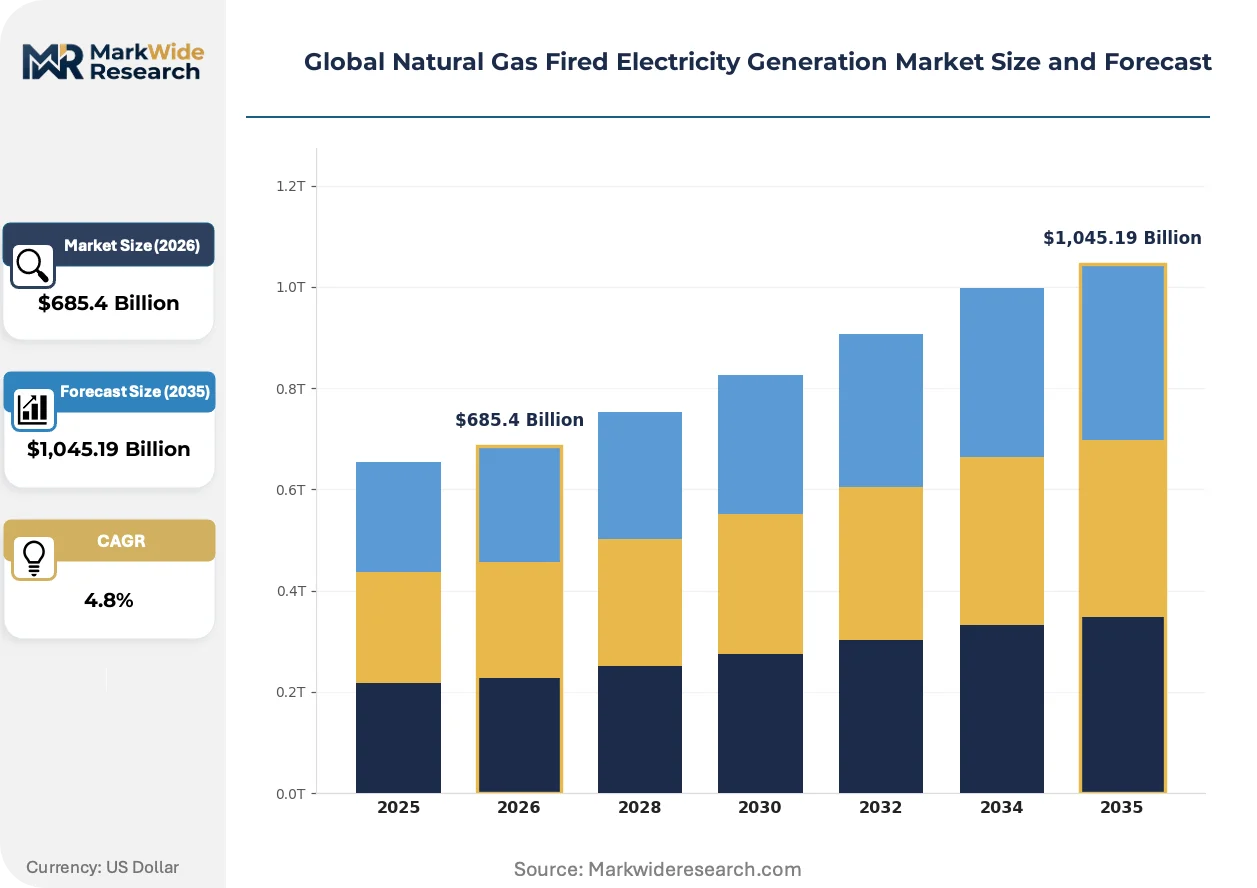
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,045.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Combined Cycle, Open Cycle, Gas Turbine, Reciprocating Engine Application: Peaking Power, Base Load Power, Intermediate Load, Distributed Generation End User: Utilities, Independent Power Producers, Industrial Users, Commercial Users Installation: Greenfield Projects, Brownfield Projects, Repowering, Retrofits |
| Companies Covered | TotalEnergies SE, Dominion Energy Inc, Duke Energy Corp, Siemens Energy AG, GE Vernova, NextEra Energy Inc, NRG Energy Inc, Shell plc, Exelon Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Gas Fired Electricity Generation Market Strategic Shifts & Innovations
The competitive landscape is reshaping around the twin objectives of maximizing thermal efficiency and future-proofing assets against decarbonization policies. This drives innovation in turbine technology and creates new strategies for navigating complex regulatory environments for power producers.
Hydrogen-capable gas turbines are engineered to co-fire a blend of natural gas and hydrogen, enabling a gradual reduction in carbon intensity. Major utilities and independent power producers are specifying this feature for new plant orders to preserve asset value. This hardware evolution is converging with emerging green hydrogen production infrastructure, positioning gas assets for a longer operational life in a decarbonized energy system.
New regulations from the US Environmental Protection Agency (EPA) mandate significant reductions in greenhouse gas emissions from gas-fired plants. This action compels operators to evaluate investments in high-efficiency combined cycle technology or post-combustion carbon capture to remain compliant. The rules most directly affect utilities with large fleets of older, less efficient simple cycle gas peaker plants.
A shift toward integrated power projects is altering procurement models for large-scale generation. Developers are increasingly seeking single-point responsibility from consortia that bundle gas supply, generation equipment, and long-term service agreements. This turnkey approach is most visible in emerging economies in Africa and Southeast Asia, where it helps de-risk complex project financing and streamlines development timelines.
Global Natural Gas Fired Electricity Generation Market Segmentation
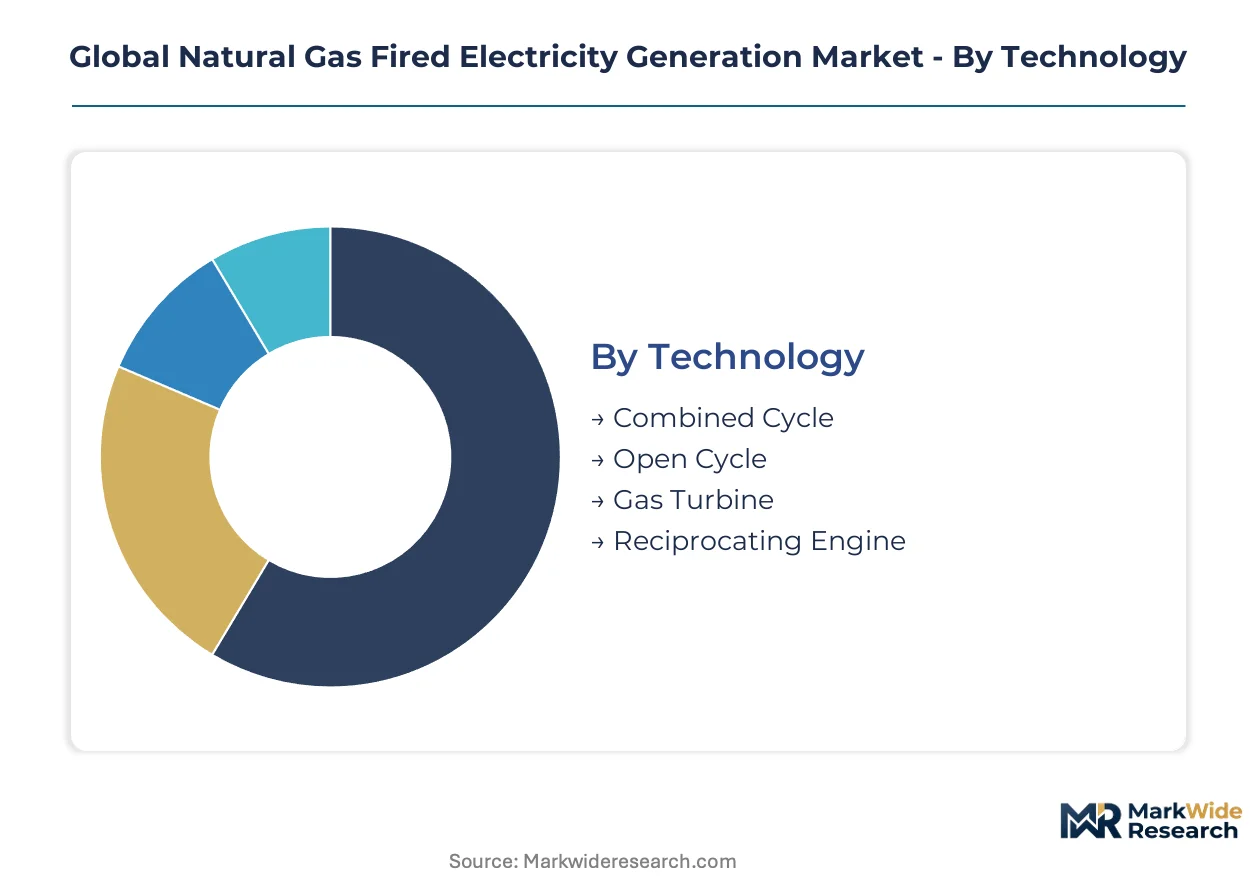
Understanding the varied technical configurations and operational roles of natural gas-fired generation clarifies market dynamics. This segmentation illuminates how different technologies and applications serve distinct power needs, from continuous supply to rapid response. It also highlights the diverse end-users and project types driving investment across the energy transition.
Technology:
The technology segment delineates the balance between high-volume, efficient power production and specialized, responsive generation solutions.
- Combined Cycle:This system integrates a gas turbine with a steam turbine, utilizing exhaust heat to generate additional electricity without burning more fuel. Demand concentrates in China for new base load capacity, driven by 'dual carbon goals' and grid stability requirements.
- Open Cycle:Open cycle plants use only a gas turbine, exhausting hot gases directly to the atmosphere, primarily for peaking power or emergency generation.
- Gas Turbine:Gas turbines convert natural gas combustion energy into mechanical energy, directly driving an electric generator for power production. These systems are foundational for both combined and open cycle plants, with major manufacturers like GE Vernova and Siemens Energy AG supplying advanced units globally.
- Reciprocating Engine:Reciprocating engines, similar to internal combustion engines, offer high flexibility and are suitable for smaller-scale, distributed power applications.
Today's leader: Combined Cycle. Tomorrow's challenger: Gas Turbine.
Application:
The application segment illustrates how natural gas generation addresses varied grid requirements, from continuous power supply to rapid demand response.
- Peaking Power:These plants operate intermittently, typically for short durations during periods of high electricity demand, offering rapid start-up and shutdown capabilities. Utility operators in the US rely on peaking plants to balance grid fluctuations introduced by intermittent renewable energy sources.
- Base Load Power:Base load plants provide a consistent, continuous supply of electricity to the grid, operating for extended periods at high capacity factors. New combined cycle installations in Southeast Asia are increasingly specified for base load roles to support industrial expansion.
- Intermediate Load:Intermediate load generation bridges the gap between base load and peaking, operating for several hours daily to meet fluctuating demand.
- Distributed Generation:Distributed generation involves smaller power sources located near consumption points, enhancing reliability and reducing transmission losses for industrial users.
Base Load Power applications are currently driving the largest investments, while Distributed Generation is gaining share fastest as grid architectures evolve.
End User:
The end-user classification reveals the primary customers for natural gas-fired electricity, distinguishing between large-scale grid operators and specific industrial or commercial needs.
- Utilities:Publicly or privately owned entities responsible for generating, transmitting, and distributing electricity to residential, commercial, and industrial customers. Utilities in Europe are investing in gas-fired plants to maintain grid stability during the transition away from coal and nuclear power.
- Independent Power Producers:Non-utility entities that own and operate power generation facilities, selling electricity to utilities or directly to large consumers. These producers often leverage project financing models to develop large-scale combined cycle plants in emerging markets.
- Industrial Users:Manufacturing facilities and other industrial operations that require reliable, on-site power generation for process continuity and energy security.
- Commercial Users:Businesses and institutions, such as data centers or large retail complexes, that may utilize natural gas-fired generation for backup power or co-generation.
Utilities remain the foundational demand segment, with Industrial Users showing increased strategic investment for on-site reliability.
Installation:
This segment categorizes projects by their development approach, distinguishing between entirely new builds and the modification or replacement of existing infrastructure.
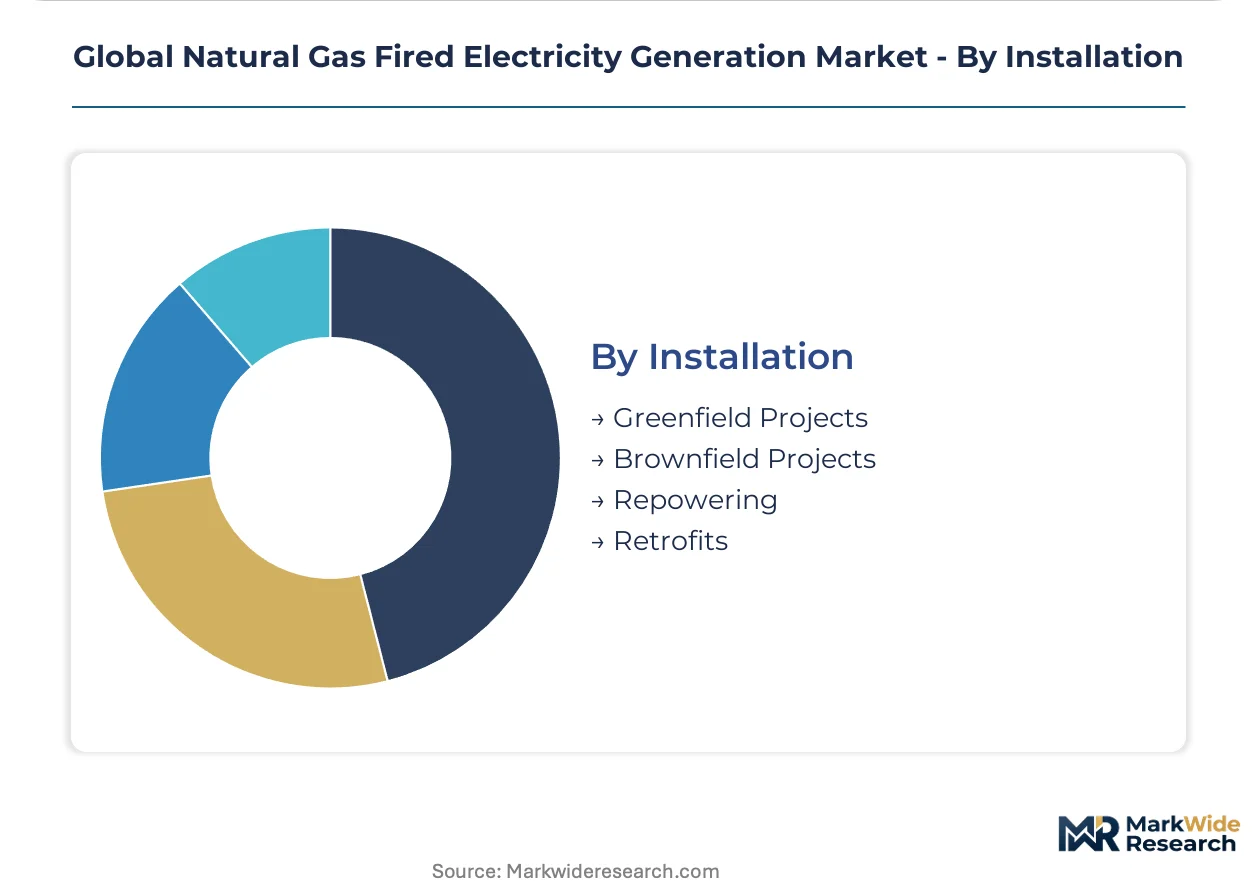
- Greenfield Projects:New power generation facilities constructed on undeveloped sites, often involving significant capital expenditure and extensive permitting processes. Many new combined cycle plants in Southeast Asia are greenfield developments, designed for long-term base load operation.
- Brownfield Projects:Projects developed on previously used industrial or commercial land, often reusing existing infrastructure or permits.
- Repowering:Replacing major components of an existing power plant, such as gas turbines, with newer, more efficient technology to increase capacity or reduce emissions. This approach extends the economic life of older assets, particularly in regulated markets like the US under EPA guidelines.
- Retrofits:Modifications or upgrades to existing plant equipment to improve performance, enhance environmental compliance, or enable new capabilities like hydrogen co-firing.
Greenfield Projects represent significant upfront investment, while Repowering initiatives demonstrate a strategic focus on asset longevity and efficiency upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas fired electricity generation scaled significantly in industrialized nations, providing reliable power for growing urban centers and manufacturing. This foundational role established natural gas as a critical energy source globally. Market dynamics now reflect diverse regional priorities, from decarbonization in Europe to industrial growth in Asia.
United States
United States demand for natural gas fired generation stems from coal plant retirements and grid balancing needs. The US EPA mandates significant greenhouse gas emission reductions from gas-fired plants. Texas's ERCOT grid increasingly utilizes flexible gas generation to manage renewable energy intermittency. Independent power producers actively invest in new CCGT facilities across the Gulf Coast.
China
China's industrial users are driving demand for reliable on-site power and cleaner fossil fuels. The Ministry of Ecology and Environment (MEE) enforces stringent emissions standards under its 'dual carbon goals'. Manufacturing hubs in the Yangtze River Delta are seeing significant investment in new combined cycle capacity. This supports economic growth while meeting environmental targets.
Germany
Germany requires natural gas generation to maintain grid stability during its ambitious energy transition away from coal and nuclear. The EU Green Deal provides an investment framework for new gas-fired capacity as a transitional activity. Utilities in the industrial Ruhr region are developing new CCGT plants to back up intermittent renewables. This ensures a reliable power supply for manufacturing.
Indonesia
Developing nations like Indonesia require new, reliable power sources to support rapid economic growth. The national energy policy prioritizes efficient gas-fired plants to replace aging, less efficient fossil fuel infrastructure. Major urban centers such as Jakarta are seeing new combined cycle installations for base load power. These projects attract integrated power developers.
Global Natural Gas Fired Electricity Generation Market Key Industry Players
Capital-heavy equipment manufacturers compete with asset-light independent power producers in the natural gas fired electricity generation market. This creates a tiered structure, with a few large integrated energy companies also participating across the value chain. Strategic archetypes include advanced turbine technology providers, large-scale project developers, and integrated utility operators. Companies are pursuing strategic partnerships and geographic expansion into emerging economies to secure market share and diversify portfolios.
Within the technology provider archetype, GE Vernova represents a leader in high-efficiency gas turbine technology, particularly for large-scale combined cycle plants. Siemens Energy AG exemplifies a comprehensive portfolio of generation equipment and services, competing across various plant configurations and geographic markets. Shell plc occupies a distinct position as an integrated energy company, leveraging its extensive natural gas supply chain to develop integrated power projects globally. These firms anchor innovation and project development, showcasing diverse approaches to market participation.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Dominion Energy Inc |
| Duke Energy Corp |
| Siemens Energy AG |
| GE Vernova |
| NextEra Energy Inc |
| NRG Energy Inc |
| Shell plc |
| Exelon Corp |
| Others |
Cost & Logistics Intelligence
The performance gap between advanced combined cycle technology and older open cycle plants dictates premium pricing for efficiency and long-term supply contracts. This divergence manifests in both equipment and fuel procurement, with advanced systems commanding higher capital expenditure but lower operational costs over their lifespan.
Pricing Analysis
Contract-based long-term offtake dominates base load power procurement, while commodity spot markets serve peaking power. Price differentiation stems from thermal efficiency, rapid dispatch capability, and hydrogen-readiness of gas turbines. Pricing pressure stems from input cost volatility for natural gas and increasing competition from renewable energy sources. Utilities seeking consistent base load power are less price-sensitive for reliability, while peaking power buyers are highly sensitive to short-term dispatch costs.
Supply Chain Analysis
Asset repurposing strategies, including retrofits for hydrogen co-firing, extend the operational life of gas turbines. This reduces the need for new equipment disposal. Turbine manufacturing concentrates in Germany and the United States, while natural gas supply centers on the United States, Russia, and Qatar. Advanced gas turbines rely on specialized alloys and high-temperature resistant materials. Geopolitical instability impacting natural gas flows presents a significant structural risk. Equipment distribution runs through direct sales channels from manufacturers to utilities and independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural gas fired electricity generation market is evolving into a late-cycle quality story. Utilities and industrial users prioritize premium specifications like hydrogen-ready turbines for long-term asset value.
For Market Incumbents: Hedge against future decarbonization mandates by investing in CCUS-ready plant designs. Pursue strategic partnerships with green hydrogen producers to secure future fuel supply. This mitigates the regulatory shift towards cleaner energy sources. GE Vernova and Siemens Energy AG should prioritize R&D in advanced turbine materials.
For New Entrants and Emerging Players: Enter via integrated power projects in developing nations across Southeast Asia. Focus on base load power applications to support industrial expansion. Offer turnkey solutions bundling gas supply, generation equipment, and long-term service agreements. This approach addresses project financing complexities in emerging markets.
For Investors and Strategic Acquirers: Asymmetric upside sits with developers of flexible, CCUS-ready combined cycle plants. These assets offer long-term viability within a 5-10 year window. Target acquisition archetypes include independent power producers with diversified portfolios in high-growth regions. Practitioners should monitor policy shifts on hydrogen blending mandates for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expanding high-efficiency combined cycle capacity supports grid stability and industrial growth. |
| Power Purchase Agreement | Securing long-term electricity sales contracts ensures revenue stability for new projects. |
| Technology Licensing | Accessing advanced turbine designs accelerates decarbonization efforts and performance upgrades. |
| Vertical Integration into Storage | Combining gas generation with battery storage enhances grid flexibility and reliability. |
| Green Certification Program | Demonstrating environmental compliance attracts ESG-focused investment and reduces regulatory risk. |
Research Approach
Multiple input streams — primary interviews, regulatory filings, and industry reports — were reconciled to construct this analysis. Primary research involved discussions with utility planning officers, independent power producers, EPC contractors, and gas turbine manufacturers. Secondary validation utilized EIA data, IEA reports, and corporate financial disclosures. This approach integrated bottom-up market insights with top-down industry trends.
Historical market data was cross-referenced against expert panel input to establish the forecast framework. The analytical framework modeled segmentation dimensions including technology type, application, end-user, and installation approach. CAGRs were derived using a compound growth model applied across the analysis window. Key forecast inputs included natural gas price projections and renewable energy penetration rates.
Inputs from public regulatory documents and corporate reports were available through the study window; gaps in long-term project financing details introduce uncertainty bands. Forecasts reflect assumptions regarding future policy stability and technological advancements. Practitioners should monitor evolving hydrogen blending mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Japan Combined Heat and Power Market
Power Generation
India Thermal Power Plant Market
Power Generation
Iraq Power EPC Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Power Plant EPC Market
Power Generation
Shore Power Market
Power Generation
Venezuela Power Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Malaysia Power Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
South America Thermal Power Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Global Black Start Generator Market
Power Generation
India Gensets Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Residential Solar Generator Market