
 United Kingdom Combined Heat and Power (CHP) Market | 2026-2036
United Kingdom Combined Heat and Power (CHP) Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Combined Heat and Power (CHP) Market Analytics
ISO 50001 energy management certification is rotating the competitive landscape by filtering out operators lacking systematic efficiency governance. Centrica PLC leverages its nationwide service infrastructure to dominate residential and small commercial installations. Siemens Energy AG anchors the industrial segment through advanced gas turbine CHP packages. Mitsubishi Power Ltd specializes in large-scale integrated solutions for district heating networks.
Combined Heat and Power refers to the simultaneous generation of usable heat and electricity from a single fuel source, typically achieving total system efficiencies of 75-90% compared to separate production methods. The technology captures thermal energy that conventional power plants discard, redirecting it to space heating, industrial processes, or domestic hot water applications. Industrial CHP occupies the largest value share due to continuous baseload demand from manufacturing and chemical processing sites. Fuel cell technology represents the fastest-expanding segment, driven by zero-emission profiles and modular scalability for healthcare and educational institutions. Reciprocating engine systems sustain mature market positions across retrofit installations where capital constraints limit technology switching.
Ofgem administers grid connection standards and capacity market rules that determine CHP project economics, while the Environment Agency enforces emissions limits under the Environmental Permitting Regulations. BEIS policy frameworks including the Industrial Decarbonisation Strategy and future hydrogen blending mandates will reshape fuel choices and equipment specifications. Stakeholders must monitor regulatory timing on hydrogen-ready equipment standards to align capital deployment with evolving compliance pathways.
Market Dynamics
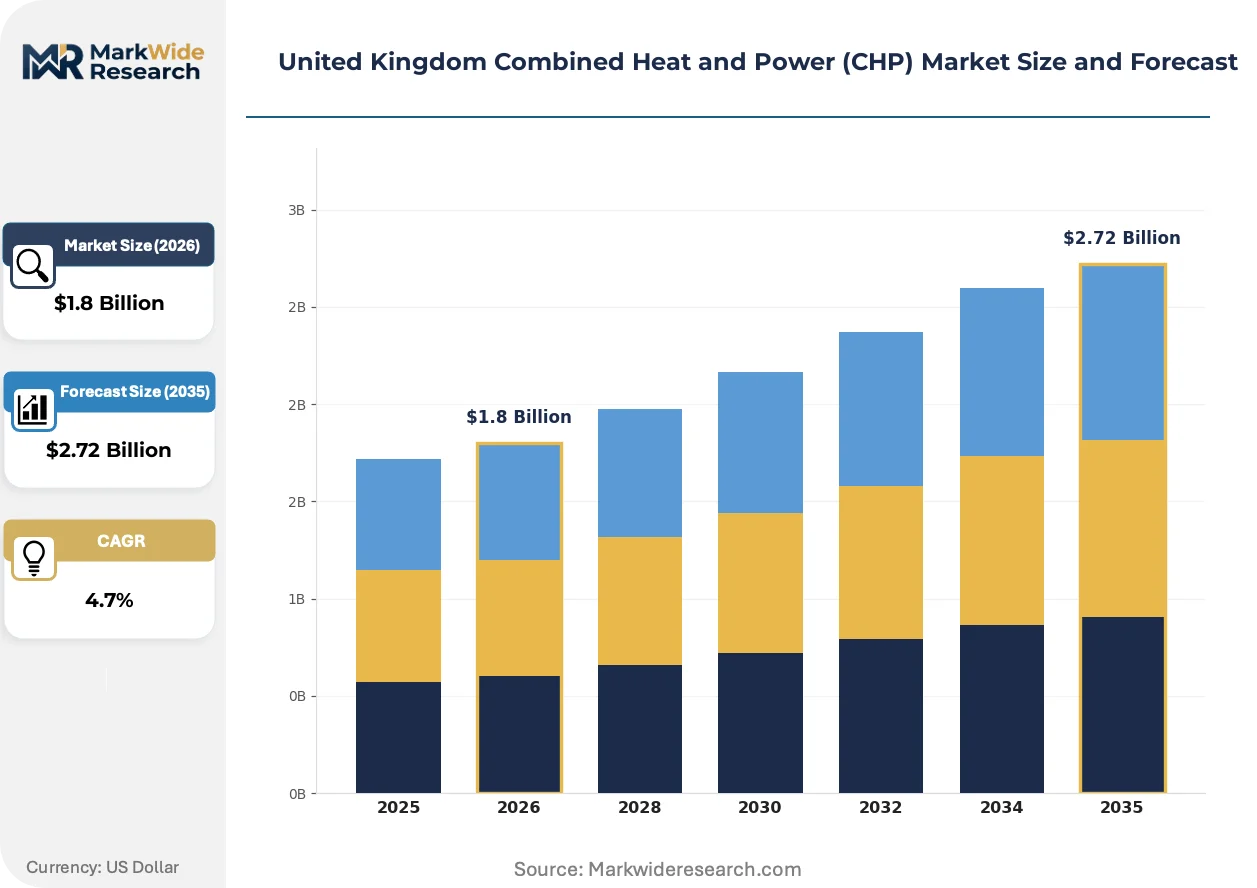
The UK's Contracts for Difference scheme and carbon pricing mechanisms are compressing project timelines as developers race to secure strike prices before subsidy windows narrow. Equipment suppliers face simultaneous pressure to certify hydrogen-ready turbines while maintaining cost competitiveness against standalone heat pumps.
Growth Catalysts
- Industrial Decarbonisation Strategy:The BEIS framework mandates emissions reductions across manufacturing clusters, forcing chemical processors and food manufacturers to retrofit existing facilities with high-efficiency CHP rather than grid-dependent electrification.
- Healthcare resilience requirements:NHS trusts in England are prioritizing baseload power independence after grid instability events, directing capital toward gas turbine and fuel cell installations with islanding capability.
- Humber region cluster development:Carbon capture and storage infrastructure deployment around Immingham and Grimsby is attracting CHP developers seeking to future-proof assets against hydrogen blending mandates.
Market Restraints
- Natural gas price volatility:Wholesale gas futures traded through ICE UK create margin uncertainty for operators of gas engine and turbine systems, eroding payback period predictability for 15-20 year asset lifecycles.
- Grid connection queue congestion:Ofgem's connection application backlog extends project commissioning timelines by 18-36 months in England's industrial corridors, freezing capital deployment.
- Air source heat pump substitution:Residential and light commercial building operators are bypassing CHP entirely for electrification routes supported by Boiler Upgrade Scheme grants.
Strategic Opportunities
- Scotland's district heating acceleration:Heat Network Regulations and the Scottish Government's heat decarbonisation fund are unlocking municipal-scale projects in Glasgow and Edinburgh previously uneconomic under English subsidy structures.
- Green hydrogen co-location:Electrolyzer-integrated CHP configurations allow industrial off-takers to arbitrage between grid electricity, natural gas, and self-produced hydrogen based on real-time price signals.
- Capacity market participation:Ofgem's redesigned capacity auction rules favor dispatchable low-carbon generation, creating revenue stacking opportunities for CHP operators able to demonstrate emissions below 450g CO2/kWh.
Industry Challenges
- Hydrogen-ready certification timelines:Equipment manufacturers face ambiguous BEIS standards on hydrogen blending percentages and testing protocols, delaying product launches and freezing procurement decisions.
- Specialized technician scarcity:The UK's pipeline of gas turbine and fuel cell service engineers remains insufficient to support projected installation rates across Manchester, Teesside, and South Wales industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Combined Heat and Power (CHP) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro CHP, Industrial CHP, Commercial CHP, Biomass CHP Technology: Gas Turbine, Steam Turbine, Reciprocating Engine, Fuel Cell End User: Residential, Educational Institutions, Healthcare Facilities, Industrial Facilities Installation: On-Site, Off-Site, District Heating, Retrofit |
| Companies Covered | Caterpillar Inc., Ramboll Group, Centrica PLC, Tedom AS, Helec Limited, Siemens Energy AG, Mitsubishi Power Ltd, E.ON, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Combined Heat and Power (CHP) Market Evolving Landscape
Technology convergence between power generation and thermal storage is compressing traditional equipment procurement cycles. Developers are resequencing project phases to align with evolving hydrogen infrastructure timelines rather than locking in fuel commitments prematurely.
Solid oxide fuel cell technology is decomposing the historical separation between baseload electricity and high-grade heat supply in healthcare and university campuses. NHS Foundation Trusts in Birmingham and Manchester are deploying 1-5 MW units to replace aging boiler infrastructure while securing carbon-free power. The technology is decomposing conventional gas engine vendor relationships as fuel cell OEMs capture service contracts previously held by reciprocating engine specialists.
BEIS consultations on hydrogen-ready equipment standards are forcing manufacturers to redesign combustion systems for 20-100% hydrogen blends before commercial fuel availability is guaranteed. Industrial CHP operators in the Humber and Teesside clusters face premature obsolescence risk if purchased equipment cannot achieve future compliance thresholds. Equipment finance providers are responding with residual value clauses tied to hydrogen compatibility certification.
Energy-as-a-service contracting is displacing traditional equipment ownership models among cash-constrained public sector buyers. Scottish universities and English hospital trusts are transferring operational risk to third-party developers through 15-20 year heat and power purchase agreements. This shift is most visible in Wales and Northern England where municipal procurement frameworks favor operational expenditure treatment over capital budget allocation.
United Kingdom Combined Heat and Power (CHP) Market Segmentation
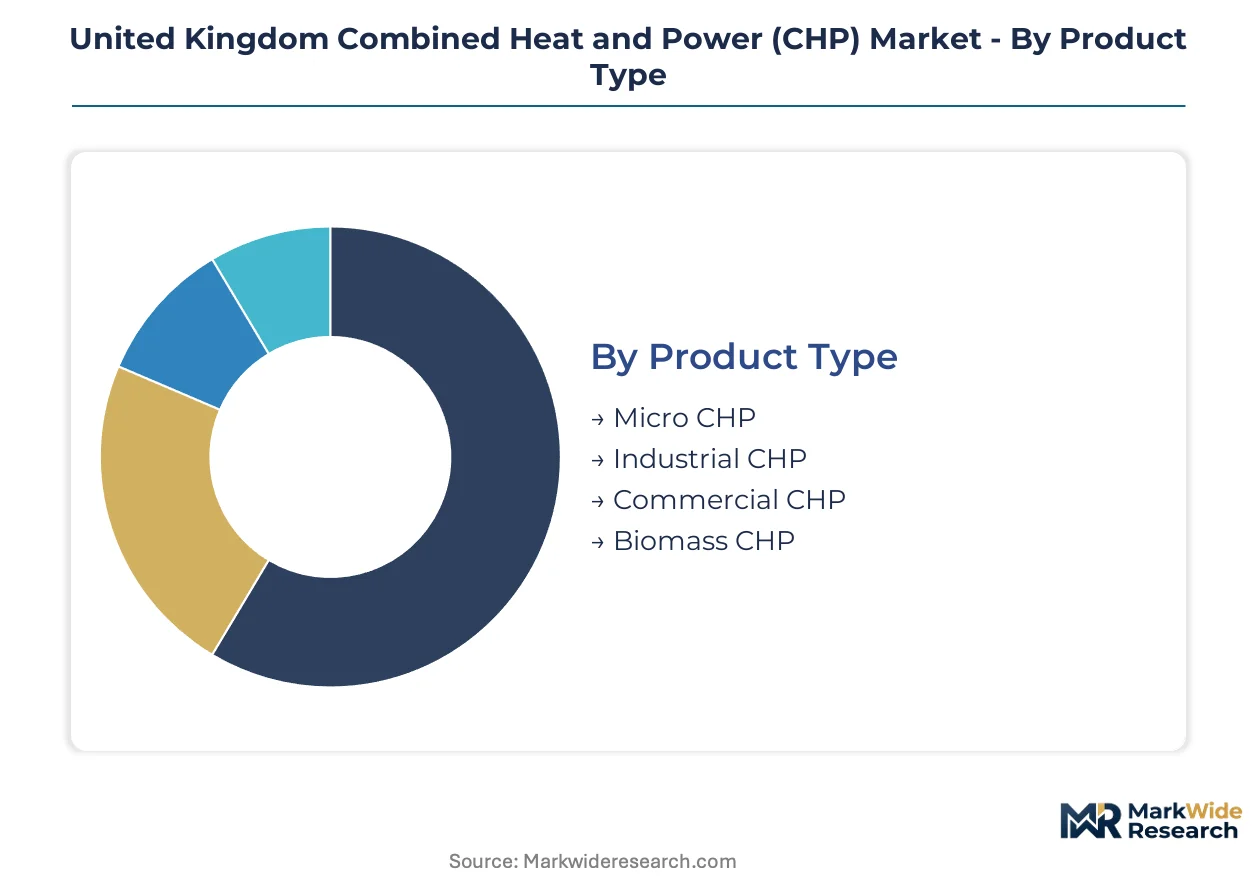
Segmentation in the UK CHP market reveals how technology maturity, fuel access, and regulatory pressure fragment procurement patterns across power ratings and thermal applications. Understanding these divisions exposes where electrification substitutes threaten incumbent equipment categories.
Product Type:
Substitution pressure from air-source heat pumps and grid electrification varies sharply by system scale, with smaller units facing the most severe displacement risk.
- Micro CHP:Residential-scale systems under 50kWe integrate Stirling engines or fuel cells for single-dwelling heat and power. Boiler Upgrade Scheme grants in England are diverting housing associations toward standalone heat pumps, collapsing addressable demand in the sub-5kWe band.
- Industrial CHP:Systems exceeding 1MWe serve continuous process heat loads in chemical and food manufacturing. Manchester and Teesside clusters favor these units for steam-raising integration and carbon capture co-location potential.
- Commercial CHP:Mid-scale 50kWe-1MWe installations target hotels, leisure centres, and office campuses. Scottish municipal procurement frameworks are sustaining deployment despite English market contraction.
- Biomass CHP:Organic fuel systems exploit forestry residues and agricultural waste for net-zero thermal output. Rural installations in Wales and Northern Scotland leverage localized feedstock supply chains.
Industrial CHP retains volume leadership; Micro CHP holds the steepest contraction curve as electrification accelerates.
Technology:
Capital intensity and hydrogen readiness stratify technology selection, with premium systems commanding longer payback periods but stronger regulatory compliance hedges.
- Gas Turbine:Aeroderivative and heavy-frame turbines deliver 1-50MWe output with exhaust heat recovery for industrial steam. Humber region developers prioritize these for future hydrogen blending retrofit compatibility.
- Steam Turbine:Back-pressure and extraction configurations serve combined-cycle and waste heat recovery applications. Legacy installations in paper and pulp mills around Grangemouth anchor residual demand.
- Reciprocating Engine:Spark-ignition and dual-fuel engines dominate 200kWe-10MWe commercial installations. NHS trusts in Birmingham specify these for islanding capability during grid instability events.
- Fuel Cell:Solid oxide and proton exchange membrane systems achieve 40-60% electrical efficiency with near-zero emissions. University campuses in Edinburgh and Manchester are deploying 1-5MWe units to replace aging boiler infrastructure.
Reciprocating Engine retains volume leadership; Fuel Cell holds the steepest expansion trajectory as zero-emission mandates tighten.
End User:
Operational criticality and thermal load profiles determine CHP viability, with baseload-dependent sectors resisting electrification more stubbornly than intermittent users.
- Residential:Single and multi-family dwellings deploy micro-CHP for decentralized heat and power. English housing stock retrofits are stalling as heat pump subsidies absorb available capital.
- Educational Institutions:Universities and colleges require district heating integration for campus-scale thermal networks. Scottish institutions lead procurement through heat decarbonisation fund access.
- Healthcare Facilities:Hospitals demand 24/7 power resilience for life-critical systems. NHS England trusts are prioritizing fuel cell and gas turbine installations with black-start capability post-grid failure incidents.
- Industrial Facilities:Chemical, pharmaceutical, and food processors exploit continuous thermal demand for maximum capacity factor. Teesside and South Wales manufacturing clusters anchor equipment shipments.
Industrial Facilities retain volume leadership; Healthcare Facilities hold the steepest expansion curve as resilience mandates harden.
Installation:
Site constraints and heat network density shape deployment economics, with urban regeneration projects unlocking district heating configurations unavailable to dispersed industrial estates.
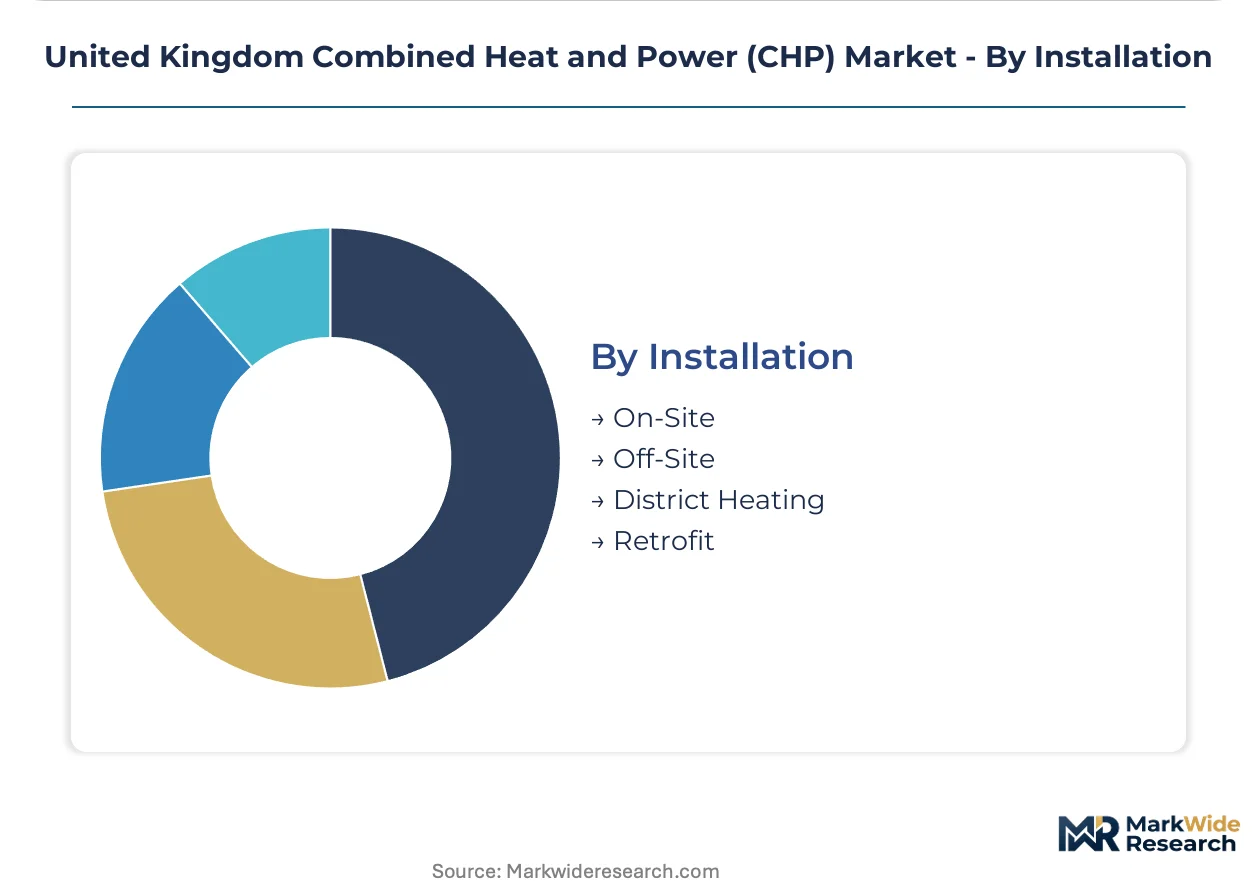
- On-Site:Dedicated plantroom installations serve single-owner facilities with predictable thermal demand. Pharmaceutical manufacturers in Cambridge and Oxford prefer captive generation for power quality control.
- Off-Site:Remote generation with private wire distribution serves campus or industrial park configurations. Energy-as-a-service developers are structuring 15-20 year heat and power purchase agreements around this model.
- District Heating:Centralized CHP feeds municipal heat networks serving multiple buildings. Glasgow and Edinburgh are accelerating deployment through Scottish Government heat network regulations.
- Retrofit:Equipment replacement within existing plantrooms preserves civil infrastructure while upgrading prime movers. Aging gas engine sites in Manchester face hydrogen-ready turbine substitution decisions.
On-Site retains volume leadership; District Heating holds the steepest expansion curve as urban densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BEIS policy frameworks and Ofgem grid standards are directing CHP deployment toward England's industrial corridors while Scotland's heat network regulations unlock municipal-scale opportunities previously uneconomic under English subsidy structures.
North England
Manchester and Teesside manufacturing clusters drive continuous thermal demand from chemical processors and food manufacturers. The Industrial Decarbonisation Strategy mandates emissions reductions across these sites, accelerating retrofit decisions for hydrogen-ready turbine installations. Humber region carbon capture infrastructure around Immingham and Grimsby is attracting developers seeking future-proof assets against blending mandates.
Scotland
Glasgow and Edinburgh universities are deploying campus-scale fuel cell systems through Scottish Government heat decarbonisation fund access. Heat Network Regulations enable municipal procurement frameworks that favor operational expenditure treatment over capital budget allocation. District heating acceleration in Scottish cities contrasts with English market contraction for equivalent building segments.
Midlands
Birmingham NHS trusts specify reciprocating engine installations with islanding capability following grid instability events. Pharmaceutical manufacturers in Cambridge and Oxford prefer captive on-site generation for power quality control. The region's automotive supply chain residual demand anchors mid-scale commercial CHP despite residential electrification pressure.
Wales
South Wales industrial zones anchor equipment shipments for steel and manufacturing revival projects. Rural biomass CHP installations exploit localized forestry residue supply chains in Northern Wales. Welsh municipal procurement frameworks are sustaining energy-as-a-service contracting models that transfer operational risk to third-party developers.
London and Southeast
Grid connection queue congestion extends project commissioning timelines by 18-36 months, freezing capital deployment across England's densest demand center. Healthcare resilience requirements from NHS England trusts are redirecting limited available capacity toward fuel cell and gas turbine installations with black-start capability. Air source heat pump substitution supported by Boiler Upgrade Scheme grants is collapsing residential-scale addressable demand.
United Kingdom Combined Heat and Power (CHP) Market Competitive Landscape
Player mix skews toward diversified energy conglomerates with nationwide service infrastructure and specialized industrial equipment manufacturers with hydrogen-ready certification capabilities. The competitive structure consolidates around three strategic archetypes: utility-affiliated developers leveraging balance sheet capacity for long-term energy-as-a-service contracts, turbine OEMs anchoring large-scale industrial installations, and fuel cell specialists capturing healthcare and educational institutional demand. Dominant competitive moves include strategic partnerships for hydrogen blending co-location and portfolio diversification into electrolyzer-integrated configurations.
Among UK-based energy service providers, Centrica PLC exemplifies the utility-affiliated archetype with nationwide infrastructure reach. Siemens Energy AG and Mitsubishi Power Ltd represent the industrial equipment tier, with the German multinational anchoring gas turbine packages and the Japanese specialist occupying large-scale integrated solutions for district heating networks. These three companies illustrate how geographic origin and corporate structure map to distinct positioning within the technology stratification.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Ramboll Group |
| Centrica PLC |
| Tedom AS |
| Helec Limited |
| Siemens Energy AG |
| Mitsubishi Power Ltd |
| E.ON |
| General Electric Company |
| Others |
Value Network & Pricing Analysis
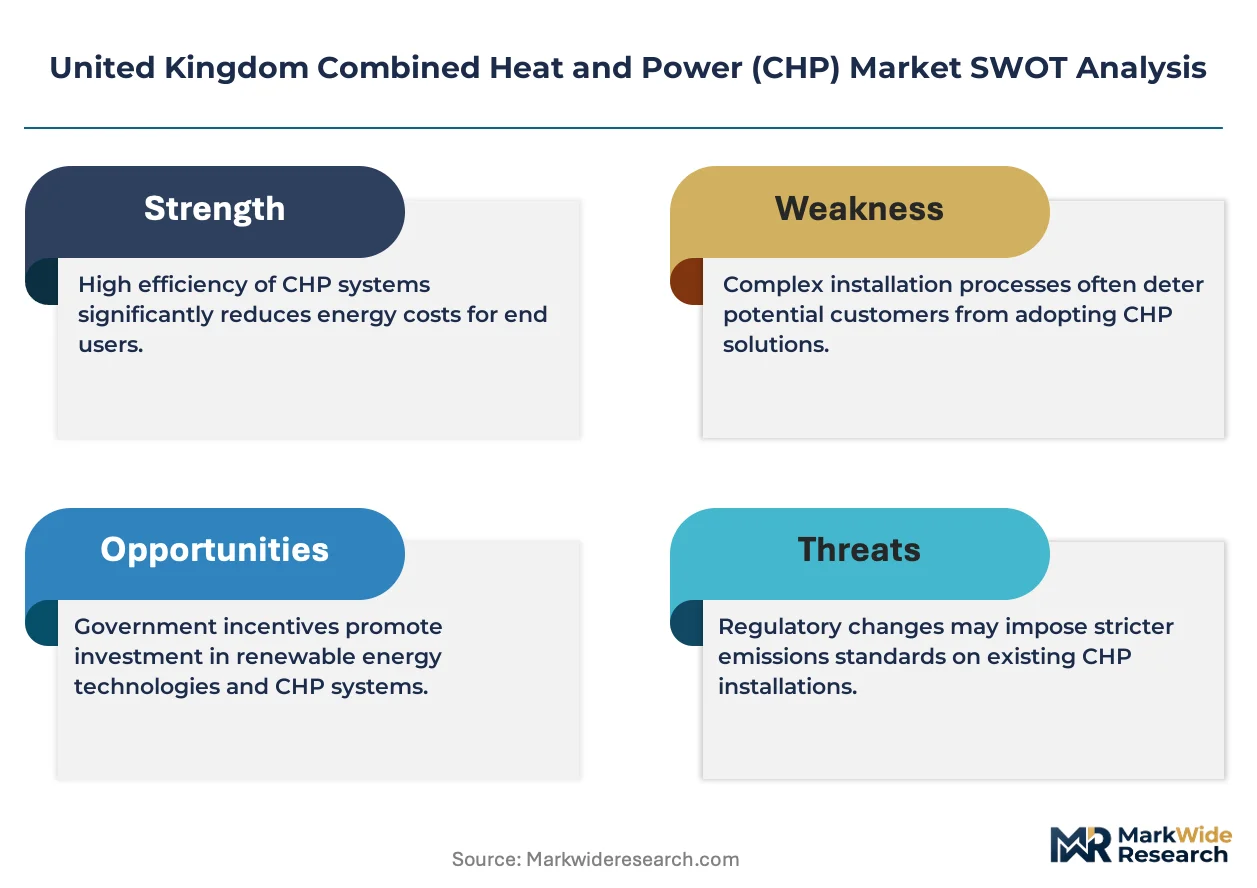
Long-term heat and power purchase agreements lock in supply access and price visibility for NHS trusts and Scottish universities transferring operational risk to third-party developers. These 15-20 year contracts insulate public sector buyers from natural gas volatility while securing dedicated maintenance coverage across England's industrial corridors.
Pricing Analysis
Certification level creates the primary spread between hydrogen-ready turbine packages and standard gas engine configurations. Project-based contracting dominates large industrial installations, while energy-as-a-service models proliferate among cash-constrained municipal buyers. Price differentiation stems from equipment scale and hydrogen blending retrofit compatibility, with premium tiers commanding longer payback periods but stronger regulatory compliance hedges. Cost compression in mid-scale commercial segments is intensifying because air-source heat pump subsidies absorb retrofit capital. Housing associations exhibit highest price sensitivity, whereas pharmaceutical manufacturers in Cambridge and Oxford prioritize power quality over unit economics.
Supply Chain Analysis
Germany and Japan anchor gas turbine and fuel cell manufacturing for UK-bound equipment shipments. Prime mover assembly draws from precision casting foundries in Italy and specialized electronics from South Korea. Single-source vulnerability concentrates in aeroderivative turbine blade supply, where limited OEM certification creates procurement bottlenecks for Humber region developers. Distribution runs through EPC contractors with established relationships to Ofgem grid connection teams, compressing commissioning timelines where queue positions are secured early.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward NHS trusts and Scottish municipalities consolidating procurement through energy-as-a-service frameworks, fragmenting traditional equipment vendor relationships.
For Market Incumbents: Compound service infrastructure density around Manchester and Teesside industrial clusters to capture hydrogen-ready turbine retrofit cycles. Deepen backward integration into electrolyzer-integrated CHP configurations before BEIS blending mandates crystallize. Defend against fuel cell OEMs capturing NHS service contracts by embedding residual value clauses tied to hydrogen compatibility certification. For New Entrants and Emerging Players: Lead with district heating specialization in Glasgow and Edinburgh, where Scottish Government heat decarbonisation fund access sustains deployment despite English market contraction. Target Welsh municipal procurement frameworks favoring operational expenditure treatment. White-space exists in biomass CHP for rural Northern Wales forestry residue supply chains. Go-to-market through 15-20 year heat and power purchase agreements transferring operational risk from public sector capital budgets. For Investors and Strategic Acquirers: Equipment finance providers with hydrogen-ready certification capabilities represent the most defensible acquisition profile across the projection horizon. Long-term viability hinges on residual value modeling for assets facing premature obsolescence risk from ambiguous BEIS blending standards. Watch BEIS consultations on hydrogen-ready equipment standards as the critical inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Equipment Certification | BEIS blending mandates will reshape fuel choices and equipment specifications across Teesside clusters. |
| Energy-as-a-Service Contracting | NHS trusts transfer operational risk to third-party developers through 15-20 year heat and power purchase agreements. |
| District Heating Network Expansion | Scottish Government heat decarbonisation fund unlocks municipal-scale projects in Glasgow and Edinburgh. |
| Capacity Market Participation | Ofgem's redesigned auction rules favor dispatchable low-carbon generation below 450g CO2/kWh. |
| Electrolyzer-Integrated CHP Configuration | Industrial off-takers arbitrage between grid electricity, natural gas, and self-produced hydrogen. |
Research Methodology
Cross-validation between Ofgem grid connection databases and BEIS policy consultation records anchors the qualitative findings on regulatory timing. Primary interviews with CHP project developers, NHS estates directors, Scottish municipal procurement officers, and gas turbine service engineers combined with secondary validation from EIA data, IEA reports, and FERC filings. Bottom-up equipment shipment tracking and top-down capacity market auction analysis triangulate market sizing across the analysis window.
Sensitivity analysis on natural gas price trajectories and hydrogen infrastructure deployment timelines shapes the analytical framework. Segmentation dimensions modeled include fuel source, generation capacity tier, end-use sector, and regional regulatory framework. CAGRs derive from installed base evolution and replacement cycle timing. Forecast inputs incorporate BEIS Industrial Decarbonisation Strategy compliance pathways and Ofgem capacity market rule redesigns.
Forecasts assume regulatory continuity in UK carbon pricing and Contracts for Difference regimes; material policy shifts on hydrogen blending percentages would require re-modeling. Specific risks include grid connection queue congestion extending beyond 36 months and air-source heat pump substitution accelerating faster than projected. Recalibration cycles align with material shifts in BEIS equipment standards and Ofgem auction rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Gas Turbines Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Micro CHP Market
Power Generation
Third Generation Energy Sources Market
Power Generation
South East Asia Power Market
Power Generation
Captive Power Generation Market
Power Generation
Iraq Power EPC Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Global Power Generation Market
Power Generation
LAMEA Microturbine Market
Power Generation
Microturbine Market
Power Generation
Japan Thermal Power Plant Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Global Turbines Market
Power Generation
Oman Power Market
Power Generation
Hydrogenerators Market