
 India Diesel Generator Market | 2026-2036
India Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
India Diesel Generator Market Outlook
After-sales service contracts and remote monitoring subscriptions are restructuring revenue models for genset suppliers in India. Cummins India leverages its nationwide service network to sustain long-term client relationships across industrial zones. Kirloskar Oil Engines anchors its position through deep aftermarket penetration in western India. Mahindra Powerol competes aggressively in the sub-500 kVA segment with standardized maintenance bundles.
A diesel generator converts mechanical energy from an internal combustion engine into electrical output through an alternator, typically operating at 1,500 RPM for 50 Hz grid synchronization in India. Prime power generators rated for continuous duty cycles dominate installed base volumes across Maharashtra and Gujarat factory clusters. The standby generator segment captures premium margins from healthcare and data center buyers who prioritize sub-ten-second start reliability over fuel efficiency. Portable generators remain a fragmented, price-sensitive category serving construction contractors and event operators.
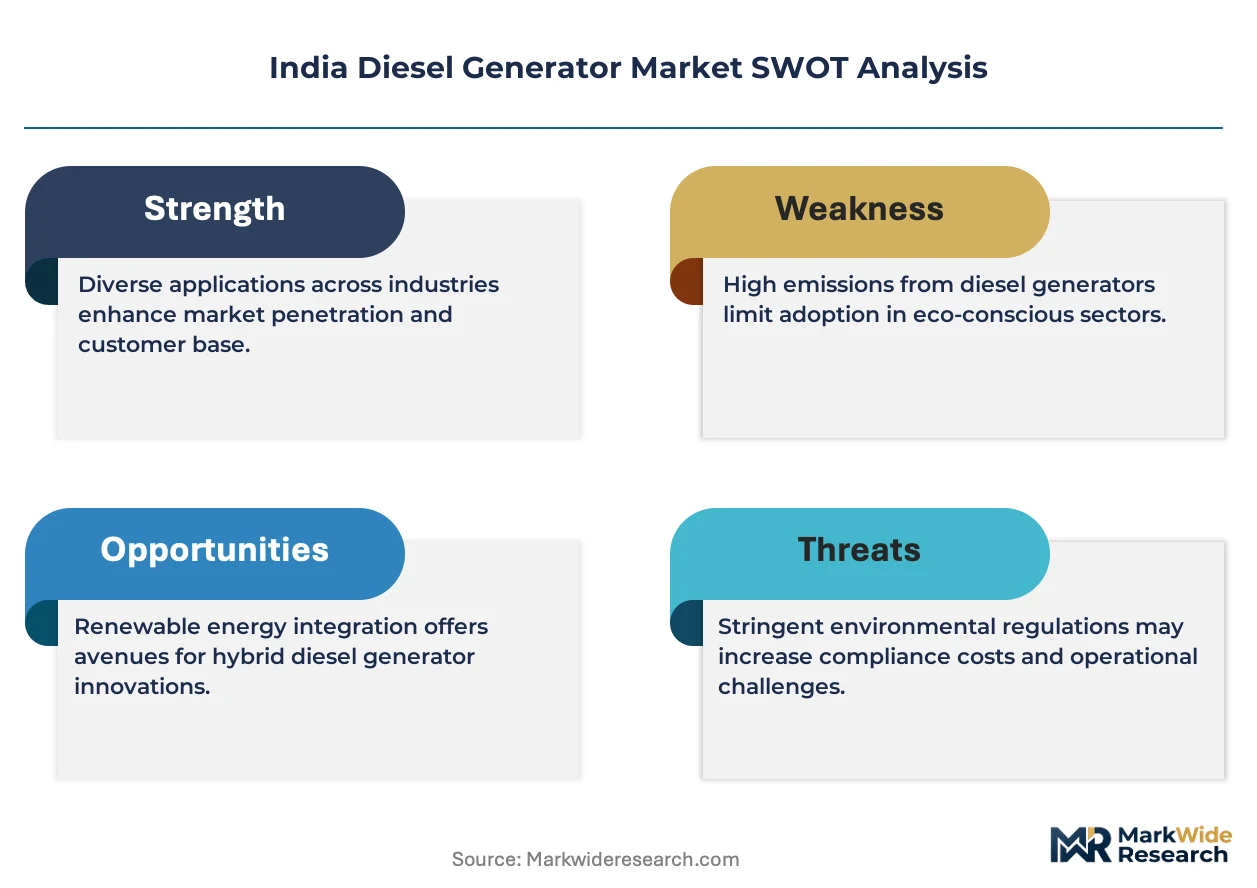
The Central Pollution Control Board enforces emission standards for gensets up to 800 kW under the Environment Protection Act, while BIS certification mandates noise and exhaust compliance for commercial sales. The Bureau of Energy Efficiency's star labeling program for diesel generators is tightening efficiency thresholds and reshaping product development priorities. Stakeholders must monitor state-level renewable integration mandates that could redefine backup power procurement rules for large commercial consumers.
Market Dynamics
The India diesel generator market is absorbing intensifying regulatory pressure from BIS emission norms that compress particulate matter thresholds, forcing manufacturers to re-engineer combustion systems and exhaust after-treatment architectures ahead of enforcement deadlines.
Growth Catalysts
- Data Center Expansion:Hyperscale facilities in Noida and Hyderabad are extending backup power contracts to multi-year service agreements, embedding genset suppliers into critical infrastructure planning cycles.
- CEA Grid Reliability Mandates:The Central Electricity Authority's standards for uninterrupted power supply to essential services are compelling healthcare and telecom operators to upgrade standby generator capacity.
- Hybrid Integration:Diesel-solar hybrid configurations are penetrating manufacturing corridors in Maharashtra and Gujarat as factory operators seek fuel arbitrage during daylight hours.
Market Restraints
- Battery Storage Substitution:Lithium-ion battery costs are declining, enabling data centers to evaluate 4-hour backup alternatives that displace gensets for non-critical load segments.
- Import Dependency:High-pressure common rail fuel injection systems and electronic control modules concentrate sourcing from European and East Asian suppliers, exposing assemblers to currency volatility and lead time extension.
- Emission Compliance Capital Burden:Selective catalytic reduction and diesel particulate filter integration add 15-25% to engine package costs, compressing margins in price-sensitive sub-200 kVA segments.
Strategic Opportunities
- Rural Electrification Gaps:Unreliable grid supply in Bihar, Uttar Pradesh, and Madhya Pradesh agricultural belts sustains demand for prime power gensets in cold storage and irrigation pump clusters.
- Remote Monitoring Monetization:IoT-enabled predictive maintenance platforms allow OEMs to convert one-time equipment sales into recurring revenue streams through subscription-based uptime guarantees.
- PLI Scheme Alignment:The Production Linked Incentive scheme for advanced automotive technology creates pathways for genset engine manufacturers to access capital subsidies for domestic component localization.
Industry Challenges
- Emission Calibration Expertise Scarcity:The shift to electronic engine management and after-treatment systems demands software engineers and combustion specialists that domestic technical institutes have not yet scaled to produce.
- Legacy Fleet Retrofit Complexity:Existing installed base units predating CPCB IV+ norms face technical and economic barriers to upgrade, creating a stranded asset problem for industrial captive power operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Diesel Generator Market |
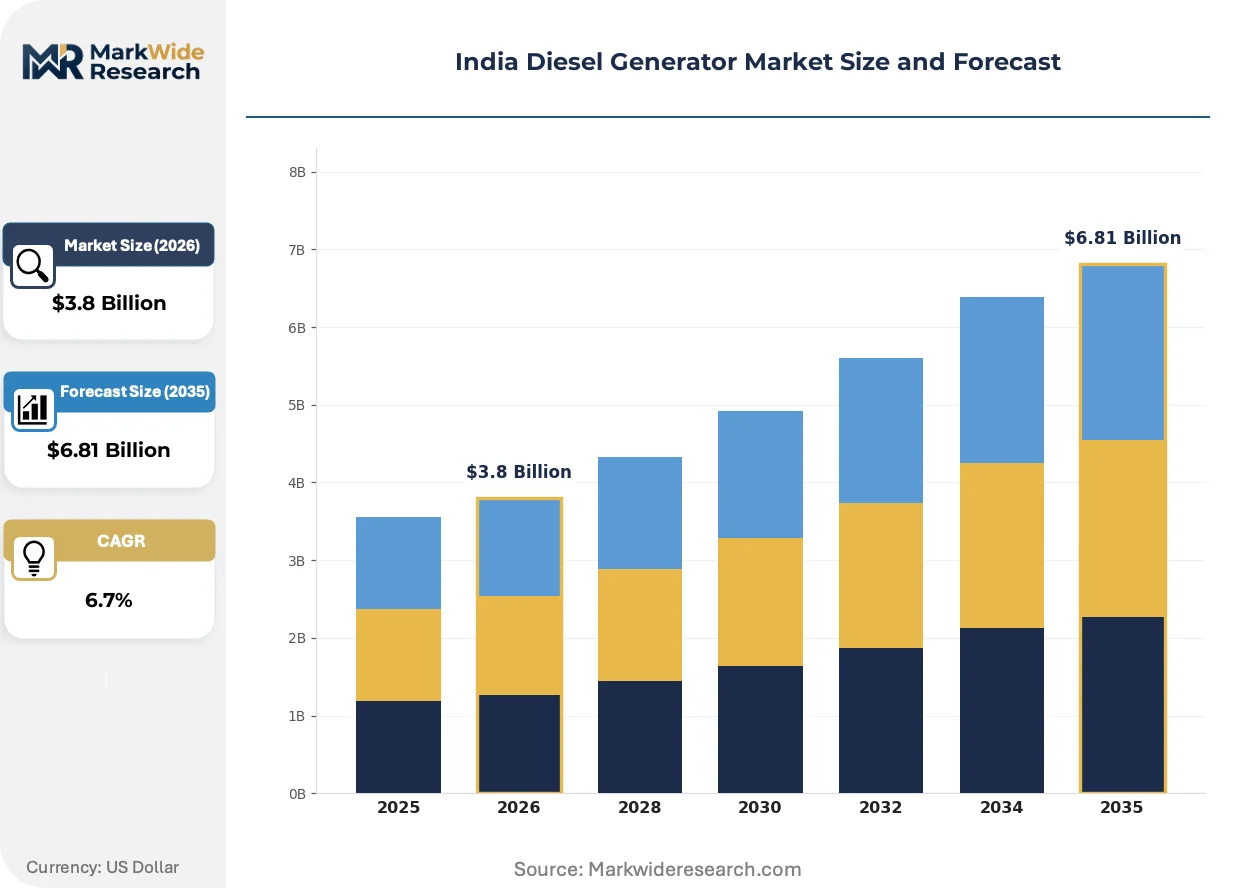
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Prime Power Generators, Industrial Generators End User: Manufacturing, Construction, Healthcare, Commercial Facilities Application: Emergency Backup, Continuous Power Supply, Recreational Use, Remote Locations Fuel Type: Ultra-Low Sulfur Diesel, Biodiesel, Conventional Diesel, Others |
| Companies Covered | Caterpillar, Ashok Leyland, Cummins India, Perkins Engines Company, Mitsubishi Heavy Industries, Kirloskar Oil Engines, Mahindra Powerol, Honda Siel Power Products, Greaves Cotton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Diesel Generator Market Strategic Shifts
Product architecture and commercial models are diverging as emission compliance costs force segmentation between premium certified systems and cost-optimized alternatives for price-sensitive buyers.
Dual-fuel retrofit kits enabling diesel-natural gas blending are absorbing attention from cement and steel producers seeking fuel cost flexibility without full engine replacement. These systems allow 30-70% gas substitution depending on load profile. Large industrial consumers in Gujarat and Rajasthan are piloting conversions to hedge against diesel price volatility, with engineering firms reporting 18-month payback periods at current fuel spreads.
BIS certification timelines for CPCB IV+ compliant gensets are compressing product development cycles, forcing engine manufacturers to parallel-track hardware validation and software calibration. The Bureau of Indian Standards has tightened documentation requirements for emission test reports and durability demonstrations. Suppliers serving the healthcare and banking segments are prioritizing early certification to secure preferred vendor status ahead of tender deadlines.
After-sales service contracts are unbundling from equipment sales, with buyers in Maharashtra's manufacturing belt negotiating standalone maintenance agreements and rejecting bundled pricing. Third-party service aggregators are capturing mid-market accounts by offering multi-brand support networks. This disintermediation pressures OEM margins on initial equipment transactions while expanding addressable revenue in the installed base.
India Diesel Generator Market Segmentation
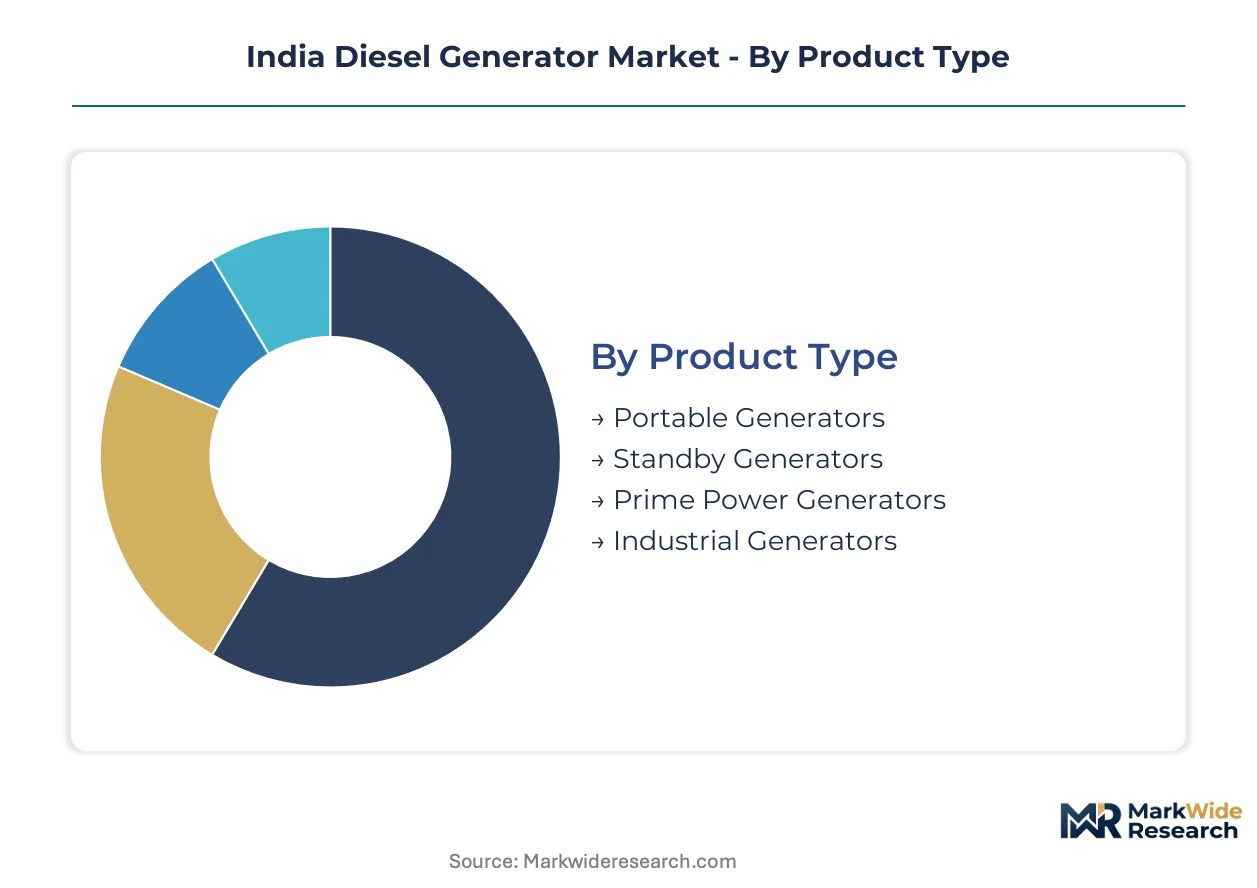
Segmentation in India's diesel generator market reveals how regulatory pressure and end-use reliability requirements are fragmenting product architectures. Suppliers must align combustion system investments with the diverging cost sensitivities across manufacturing clusters versus critical infrastructure operators.
Product Type:
Supply concentration for electronic fuel injection systems and after-treatment hardware favors larger OEMs with capital to absorb CPCB IV+ compliance costs.
- Prime Power Generators:Engineered for continuous duty cycles with load factors exceeding 70%, these units integrate heavy-duty cooling and lubrication systems. Maharashtra and Gujarat factory clusters absorb the majority of prime power installations as captive power operators seek alternatives to grid instability.
- Standby Generators:Optimized for rapid start capability with sub-ten-second synchronization to critical loads. Healthcare facilities in Delhi and data centers in Hyderabad prioritize standby units for life-safety and uptime certification requirements over fuel efficiency metrics.
- Portable Generators:Compact single-cylinder units serving construction contractors and event operators with intermittent runtime needs.
- Industrial Generators:High-capacity synchronized systems for large manufacturing complexes and process industries.
Prime Power Generators absorb the bulk of installed capacity; Standby Generators are expanding most quickly.
End User:
Procurement authority concentrates with engineering heads in manufacturing, while healthcare and commercial facilities delegate to facilities management contractors.
- Manufacturing:Automotive and textile producers in Tamil Nadu and Karnataka operate gensets as primary power sources during scheduled load shedding. These buyers negotiate multi-year fuel supply contracts alongside equipment procurement.
- Healthcare:Multi-specialty hospitals and diagnostic chains require N+1 redundancy configurations with automatic transfer switches. The CEA's reliability mandates for essential services are accelerating replacement cycles in tier-2 cities.
- Construction:Project-based rental demand from infrastructure contractors with seasonal equipment needs.
- Commercial Facilities:Shopping malls and IT parks seeking backup for HVAC and elevator loads.
Manufacturing dominates current installed base volume; Healthcare is climbing the fastest as accreditation standards tighten.
Application:
Margin structures diverge sharply between emergency-rated systems with premium pricing and continuous-duty units optimized for fuel consumption.
- Emergency Backup:Automatic-start systems with battery-backed control panels and remote monitoring capability. Banking and telecom infrastructure operators in Mumbai and Bengaluru specify these for regulatory compliance and SLA adherence.
- Continuous Power Supply:Prime-rated engines with extended maintenance intervals and bulk fuel storage integration. Cold storage operators in Uttar Pradesh agricultural belts rely on continuous gensets for post-harvest preservation.
- Recreational Use:Low-capacity units for camping and outdoor events with minimal emissions controls.
- Remote Locations:Off-grid installations for mining exploration and border infrastructure with limited service access.
Emergency Backup commands premium pricing tiers; Continuous Power Supply is gaining share fastest in rural industrialization corridors.
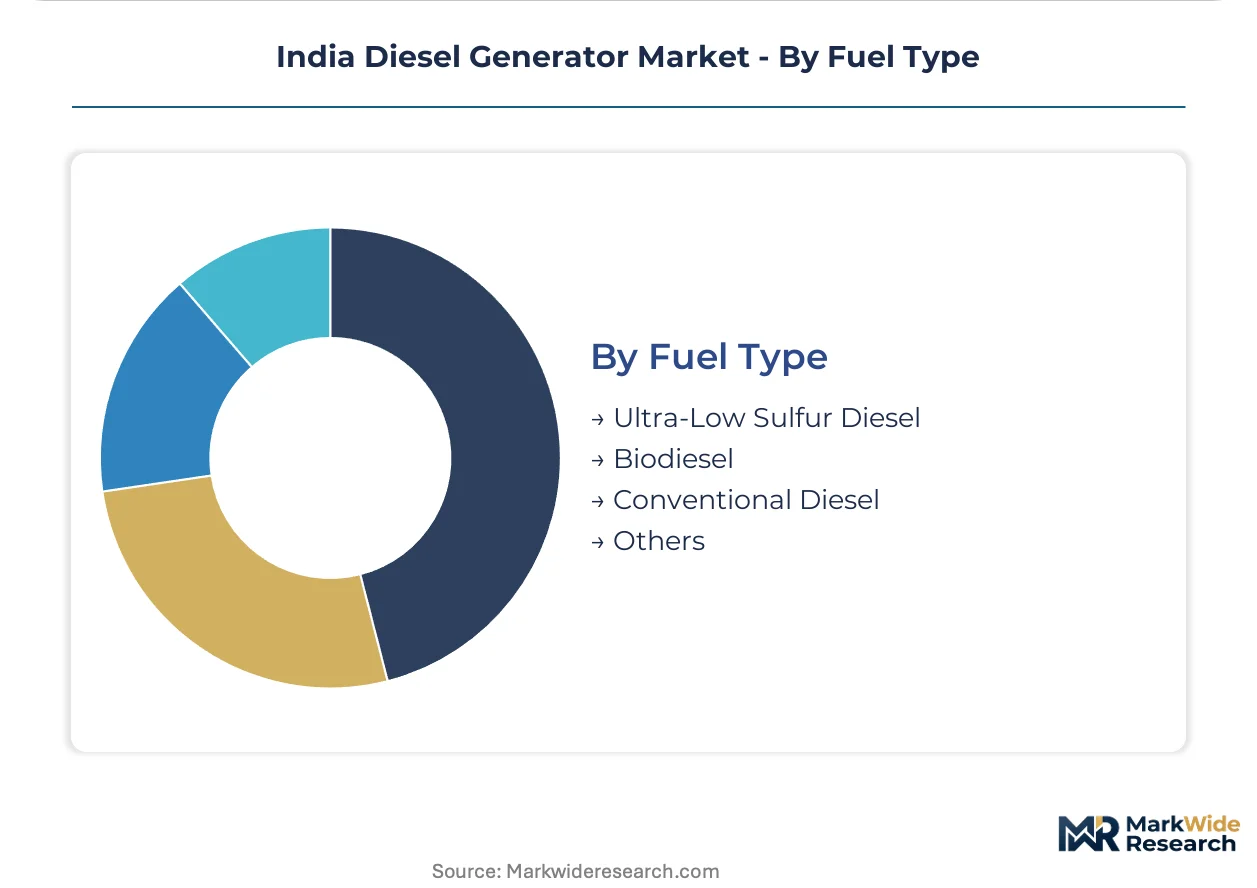
Fuel Type:
Refinery output specifications and state-level biodiesel blending mandates are reshaping fuel procurement strategies across user segments.
- Ultra-Low Sulfur Diesel:Maximum 10 ppm sulfur content enabling compatibility with advanced after-treatment systems. CPCB IV+ compliant gensets in Delhi-NCR and Mumbai metropolitan regions require ULSD to prevent catalyst poisoning and particulate filter clogging.
- Biodiesel:B20 and B100 blends produced from non-edible oilseeds and waste cooking oil. The Ministry of Petroleum and Natural Gas blending roadmap is creating procurement obligations for government and PSU facilities.
- Conventional Diesel:Higher-sulfur legacy fuel still prevalent in unregulated rural installations and pre-2020 genset fleets.
- Others:Dual-fuel diesel-natural gas configurations and synthetic diesel trials in cement sector pilot programs.
Ultra-Low Sulfur Diesel underpins new equipment sales; Biodiesel is expanding most quickly as oil marketing companies extend retail infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's manufacturing corridor anchors India's diesel generator demand, with Mumbai-Pune industrial belt absorbing prime power installations as captive operators seek insulation from grid instability.
Maharashtra
Automotive and textile clusters in Pune and Nashik operate gensets as primary power sources during scheduled load shedding. The state's industrial policy incentivizes captive power investments. Aurangabad's automotive component manufacturers negotiate multi-year fuel supply contracts alongside equipment procurement.
Gujarat
Chemical and pharmaceutical processors in Vadodara and Ankleshwar deploy continuous-duty gensets for process-critical operations. The Gujarat Pollution Control Board enforces CPCB IV+ norms ahead of national deadlines. Mundra port's special economic zone attracts hyperscale data centers extending backup power contracts.
Telangana
Hyderabad's data center operators prioritize sub-ten-second start reliability for uptime certification requirements. The state's IT policy mandates uninterrupted power infrastructure for SEZ status. Cyberabad's cloud facilities embed genset suppliers into multi-year service agreements.
Tamil Nadu
Automotive and electronics manufacturers in Chennai and Coimbatore face frequent grid fluctuations during peak summer demand. The Tamil Nadu Generation and Distribution Corporation's load shedding schedules drive prime power genset adoption. Sriperumbudur's EV component cluster expands captive generation capacity.
Delhi-NCR
Healthcare facilities and banking infrastructure in Delhi, Noida, and Gurugram require N+1 redundancy configurations with automatic transfer switches. The Environment Pollution Control Authority mandates ULSD compatibility for new installations. Noida's hyperscale data centers extend backup power contracts to secure preferred vendor status.
India Diesel Generator Market Competitive Environment
Capital-heavy engine manufacturers compete with asset-light system integrators across India's diesel generator market. The vendor base fragments across three tiers: multinational OEMs with full technology ownership, domestic assemblers sourcing critical subsystems, and regional fabricators serving price-sensitive segments. Strategic archetypes include emission-compliant premium specialists, cost-optimized volume players, and aftermarket service aggregators. Capacity expansion and certification acceleration dominate competitive moves as BIS timelines compress.
Among multinational OEMs, Caterpillar and Cummins India anchor the premium tier with nationwide service networks. Domestic specialists Kirloskar Oil Engines and Mahindra Powerol occupy positions across mid-market segments. These four exemplify divergent approaches to emission compliance investment and aftermarket penetration strategies.
| Leading Market Players |
|---|
| Caterpillar |
| Ashok Leyland |
| Cummins India |
| Perkins Engines Company |
| Mitsubishi Heavy Industries |
| Kirloskar Oil Engines |
| Mahindra Powerol |
| Honda Siel Power Products |
| Greaves Cotton |
| Others |
Value Chain & Pricing Dynamics
Combustion calibration specialists concentrated in Pune and Manesar command wage premiums that widen spreads between CPCB IV+ certified premium tiers and uncertified economy alternatives. Labor-cost differentials across these engineering clusters directly feed into manufacturer pricing architectures, with Tier 1 OEMs absorbing talent premiums while regional assemblers compete on stripped-down configurations.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for data center and healthcare buyers who prioritize sub-ten-second start reliability over capital expenditure minimization. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified systems with full after-treatment from basic mechanical-governed units. Cost compression in sub-200 kVA segments is intensifying because selective catalytic reduction and diesel particulate filter integration adds 15-25% to engine package costs. Construction contractors exhibit highest price sensitivity, while banking infrastructure operators accept premium positioning for regulatory compliance.
Supply Chain Analysis
BIS certification timelines for CPCB IV+ compliant gensets gate supplier qualification, compressing vendor pools to manufacturers with parallel-track hardware validation capabilities. High-pressure common rail fuel injection systems and electronic control modules draw from Germany, Japan, and South Korea, exposing assemblers to currency volatility and lead time extension. Single-source vulnerability concentrates in precision fuel injection hardware where European suppliers dominate technical specifications. Distribution runs through authorized dealer networks for premium tiers and regional fabricator channels for price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CPCB IV+ emission norms erect a cost-of-compliance barrier that consolidates competitive position around capitalized incumbents with certification acceleration capabilities, freezing out under-resourced regional assemblers.
For Market Incumbents: Deploy nationwide service network densification to capture recurring revenue from remote monitoring subscriptions and predictive maintenance platforms. Battery storage substitution threatens standby generator margins in data center segments; counter by embedding genset suppliers into multi-year critical infrastructure planning cycles with uptime guarantees. Certification investment in early BIS approval secures preferred vendor status ahead of tender deadlines for healthcare and banking segments. For New Entrants and Emerging Players: Dual-fuel retrofit kits enabling diesel-natural gas blending offer technology-first wedge into cement and steel producer segments seeking fuel arbitrage without full engine replacement. White-space targets concentrate in Bihar, Uttar Pradesh, and Madhya Pradesh agricultural belts where unreliable grid supply sustains prime power demand for cold storage and irrigation pump clusters. Go-to-market through third-party service aggregators captures mid-market accounts disintermediating from OEM bundled pricing. For Investors and Strategic Acquirers: Re-rating potential sits with aftermarket service aggregators given unbundling of maintenance agreements from equipment sales across Maharashtra's manufacturing belt. Long-term viability frames around installed base monetization rather than new equipment volume capture. Acquisition target archetype: IoT-enabled predictive maintenance platforms with multi-brand support networks. Signal to watch: state-level renewable integration mandates that could redefine backup power procurement rules for large commercial consumers.| Strategic Initiative | Industry Significance |
|---|---|
| CPCB IV+ Certification Acceleration | Early BIS approval secures preferred vendor status for healthcare and data center tenders. |
| Remote Monitoring Platform Deployment | IoT-enabled predictive maintenance converts equipment sales into recurring subscription revenue. |
| Dual-Fuel Retrofit Kit Development | Diesel-natural gas blending captures cement and steel producers hedging fuel price volatility. |
| Service Network Densification | Aftermarket penetration in western India anchors long-term client relationships for Kirloskar Oil Engines. |
| Rural Electrification Gap Targeting | Cold storage and irrigation pump clusters in Bihar and Uttar Pradesh sustain prime power demand. |
Study Parameters
Multi-period observation of BIS certification timelines, fuel injection system lead times, and state-level renewable integration mandates anchored the trend analysis, supplemented by interviews with plant engineers at Maharashtra and Gujarat manufacturing clusters, aftermarket service heads at domestic OEMs, procurement teams at hyperscale data center operators, and fuel supply specialists at oil marketing companies. Secondary validation drew from Central Electricity Authority reliability standards, Bureau of Indian Standards emission test reports, Bureau of Energy Efficiency star labeling databases, and customs records for high-pressure common rail import volumes. Bottom-up installation tracking across state industrial clusters triangulated against top-down revenue estimates from equipment manufacturers.
Segment-weighting approach distributed value and volume across prime power, standby, portable, and industrial generator categories, with further stratification by end-use manufacturing, healthcare, construction, and commercial facilities. Power rating tiers, duty cycle specifications, and after-treatment compliance levels provided additional modeling dimensions throughout the forecast period. CAGRs derived from regression analysis of historical installation data against industrial production indices, grid reliability metrics, and regulatory enforcement schedules. Forecast inputs incorporated diesel-solar hybrid penetration rates and lithium-ion battery cost decline curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery storage substitution or sudden BIS enforcement deadline advancement. Projections reflect assumptions regarding continued grid instability in manufacturing corridors and steady CPCB IV+ compliance phase-in without retroactive legacy fleet mandates. A model refresh is warranted upon material change in state-level renewable integration mandates or lithium-ion battery cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Power Generator Rental Market
Generators
North America Generator Sets Market
Generators
Generator [Up to 100 Kva] Market
Generators
Gasoline Generator Market
Generators
Military Generator Market
Generators
Marine Gensets Market
Generators
Tanzania Diesel Generator Market
Generators
United States Diesel Generator Market
Generators
Industrial Generator Market
Generators
Europe Turbo Generator Market
Generators
Generator Sets Market
Generators
Portable Inverter Generators Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Commercial Generator Market
Generators
Europe Gas Generator Market
Generators
Global Portable Generator Market