
 South America Thermal Power Market | 2026-2036
South America Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
South America Thermal Power Market Analytics
Supercritical and ultra-supercritical steam parameters are rotating the South America thermal power market toward higher efficiency tiers. Petrobras leverages its integrated natural gas supply chain to anchor fuel security for coastal power plants. Enel S.p.A competes through advanced combined-cycle technology leadership across Chile and Peru. Centrais Eletricas Brasileiras SA dominates baseload capacity allocation within Brazil's national interconnected grid.
Thermal power denotes electricity generation from combustion or heat-driven prime movers, typically employing steam turbines with operating pressures exceeding 22 megapascals in supercritical configurations to maximize thermal efficiency above 40 percent. The technology serves baseload and dispatchable intermediate power requirements where renewable intermittency demands firm backup capacity. Combined cycle gas turbine installations represent the fastest-expanding technology segment as LNG infrastructure proliferates along Atlantic coastlines. Coal-fired steam turbine capacity constitutes a mature, declining margin pool concentrated in southern Brazil and Colombia. Utilities command the largest end-user value share due to long-term power purchase agreement structures and regulated return frameworks.
ANEEL enforces grid reliability standards and environmental licensing protocols that shape thermal plant dispatch hierarchies and emissions compliance timelines across Brazil. Chile's Ministry of Energy and SEC electrical standards mandate progressive decarbonization benchmarks that constrain new coal permits while permitting efficient gas-fired replacements. Argentina's ENRE regulatory framework governs wholesale electricity market pricing and thermal generator participation requirements. Stakeholders must monitor LNG import terminal expansions, carbon border adjustment developments, and hydroelectric reservoir variability to calibrate thermal asset dispatch and retirement schedules.
Market Dynamics
ANEEL's grid reliability mandates are compressing dispatch hierarchies across Brazil's national interconnected system, forcing asset owners to prioritize efficiency retrofits over greenfield coal development while LNG infrastructure expansion along Atlantic coastlines reconfigures fuel security calculations.
Growth Catalysts
- Combined-cycle retrofits:Brazil's southeastern industrial corridor spanning São Paulo and Minas Gerais states drives baseload demand for higher-efficiency gas turbine installations.
- Mining baseload requirements:Copper and lithium extraction operations across Chile and Peru anchor firm power demand that intermittent renewables cannot satisfy.
- ANEEL reliability standards:Grid codes mandating spinning reserve capacity preserve thermal plant dispatch priority during hydroelectric reservoir drawdowns.
Market Restraints
- LNG price volatility:Atlantic basin spot market fluctuations transmit directly to coastal combined-cycle plant operating margins.
- Colombian coal supply concentration:Thermal coal imports for southern Brazilian plants depend on single-source rail corridors vulnerable to weather disruptions.
- Chilean decarbonization mandates:Ministry of Energy progressive benchmarks block new coal permits and accelerate existing asset retirement timelines.
Strategic Opportunities
- Argentine Vaca Muerta gas:Domestic shale production expansion offers captive fuel supply for thermal generators serving Buenos Aires industrial load.
- Peruvian LNG import terminals:New regasification infrastructure at Pampa Melchorita enables coastal combined-cycle development without pipeline dependency.
- Brazilian biomethane co-firing:ANEEL renewable gas incentives allow existing turbine assets to capture carbon credit premiums.
Industry Challenges
- Supercritical welding certification:Specialized pressure vessel fabrication skills concentrate in European and East Asian supplier bases, extending procurement lead times.
- Grid code compliance testing:Frequency response validation for retrofitted units requires extended commissioning windows that compress merchant revenue windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Thermal Power Market |
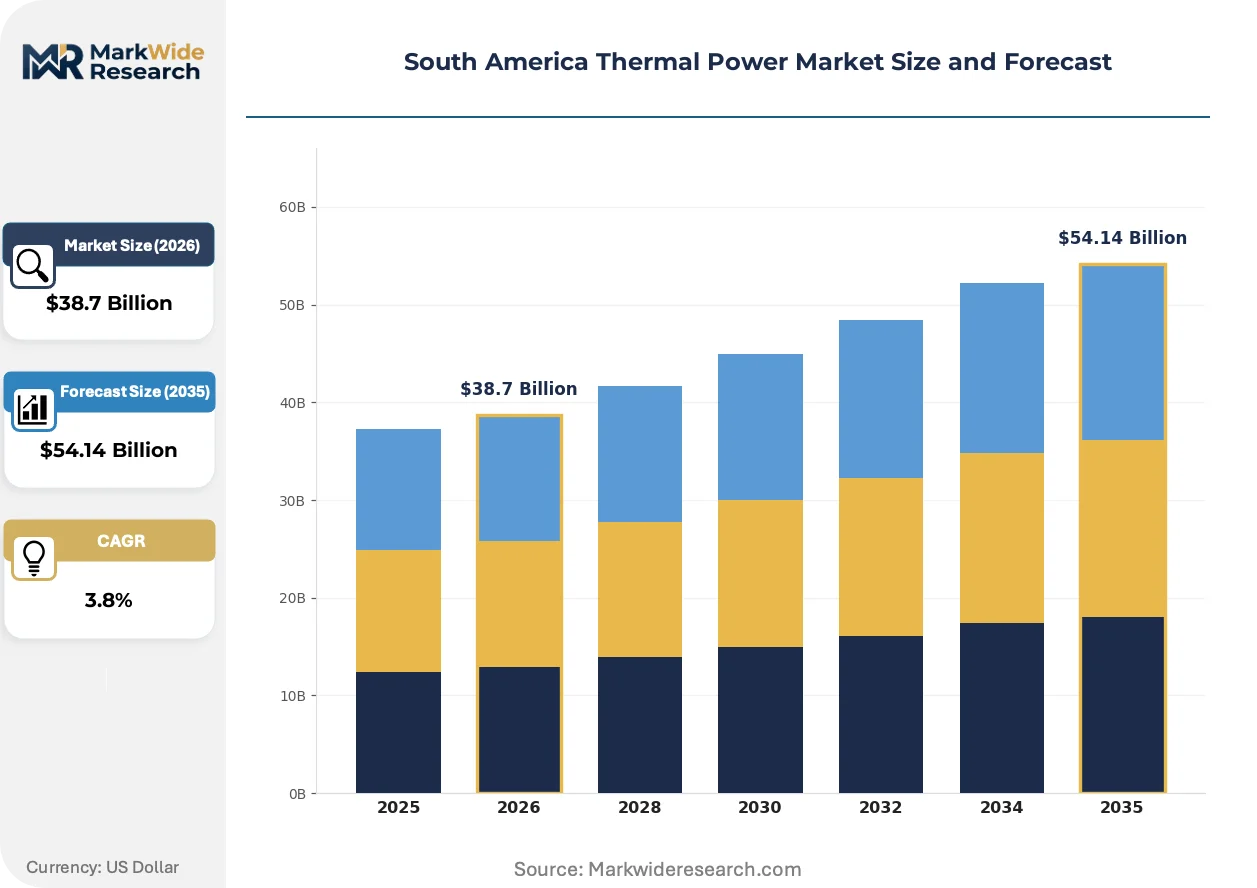
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coal, Natural Gas, Oil, Biomass Technology: Steam Turbine, Combined Cycle, Heat Recovery Steam Generator, Geothermal End User: Industrial, Residential, Commercial, Utilities Application: Base Load, Peak Load, Co-Generation, District Heating |
| Companies Covered | Centrais Eletricas Brasileiras SA, AES Corporation, Pampa Energía SA, Enel S.p.A, Colbún S.A, Petrobras, Engie Energia, AES Gener, Neoenergia SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Thermal Power Market Evolving Landscape
Digital twin deployment and hydrogen blending trials are fragmenting traditional thermal asset operating models, while regulatory pressure on emissions intensity accelerates technology substitution cycles across the region's plant fleet.
Advanced class gas turbines with dry low-NOx combustors are fragmenting the market for mid-merit capacity. Brazilian utilities serving São Paulo's industrial corridor are adopting these units for rapid cycling duty. The technology is fragmenting dispatch hierarchies by enabling sub-30-minute start times that compete with reservoir hydroelectric flexibility.
Chile's SEC electrical standards now mandate progressive emissions intensity benchmarks for new thermal capacity. The regulation compresses planning horizons for gas-fired replacements of retiring coal units. Southern Chilean industrial offtakers are responding by embedding carbon intensity clauses into long-term power purchase agreements.
Merchant offtakers in Brazil's free contracting environment are unbundling energy and capacity payments in procurement structures. Industrial buyers in Minas Gerais are separating firm capacity contracts from energy dispatch decisions. This shift is most visible among mining operations seeking price exposure to spot markets while preserving supply security through separate reliability payments.
South America Thermal Power Market Segmentation
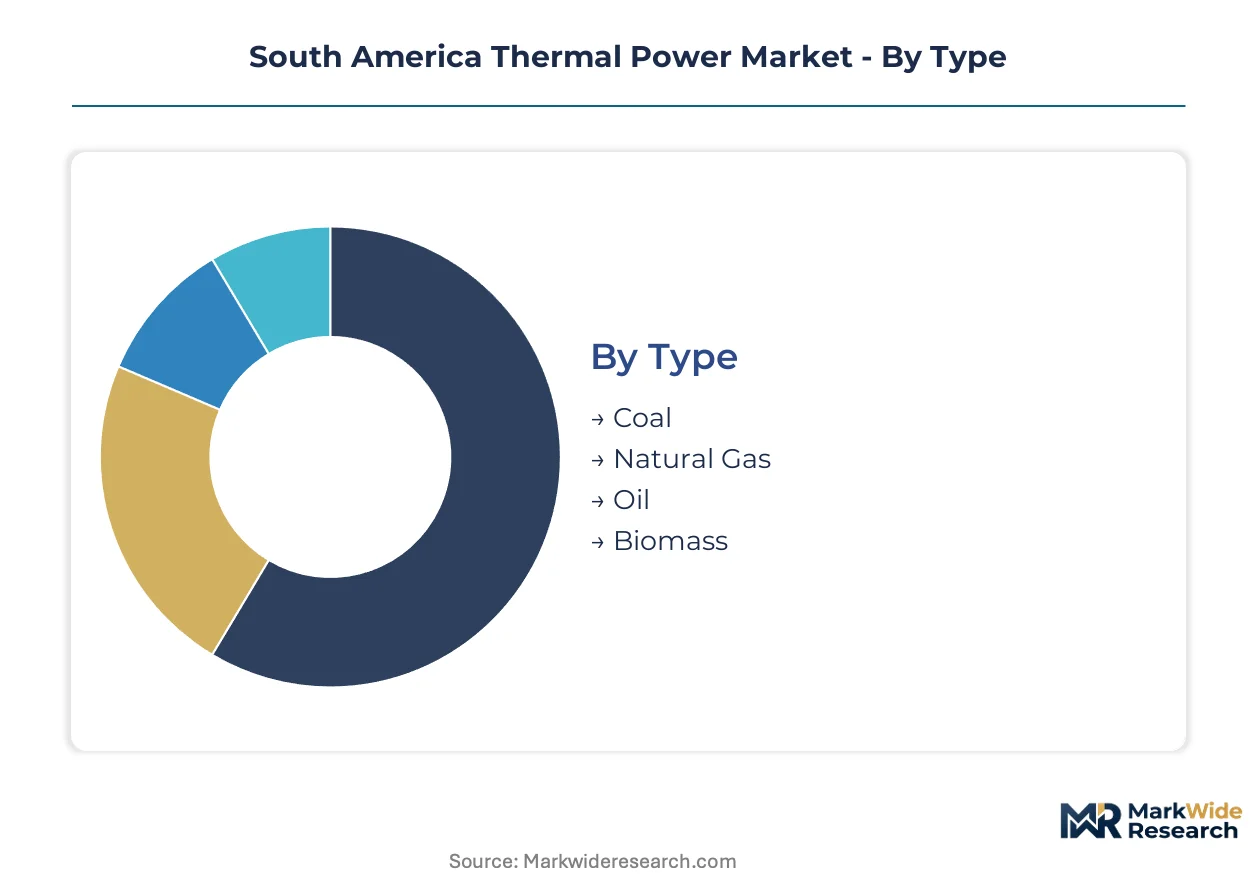
Thermal power assets across South America fragment across fuel types, prime mover technologies, and dispatch applications that determine revenue stability and regulatory exposure. Understanding these segment boundaries reveals where capital deployment concentrates and where stranded asset risk accumulates.
Type:
Channel flows diverge sharply by fuel type, with pipeline-connected natural gas plants integrating into utility procurement while biomass and oil-fired units serve captive industrial offtakers outside regulated frameworks.
- Natural Gas:Combined-cycle configurations dominate new capacity additions along Brazil's Atlantic coastline and Chile's central grid zone. ANEEL reliability mandates and Chilean SEC emissions benchmarks channel utility investment toward this fuel type for mid-merit and baseload duty cycles.
- Coal:Existing subcritical steam turbine capacity concentrates in southern Brazil's Rio Grande do Sul state and Colombia's northern mining corridors. Chilean Ministry of Energy decarbonization protocols block new permits and accelerate retirement timelines for these assets.
- Oil:Distillate-fired peaking units persist in remote Amazonian load centers and Argentine Patagonia where pipeline infrastructure remains absent.
- Biomass:Bagasse cogeneration facilities anchor sugar-ethanol processing clusters in São Paulo state and Brazil's Center-West region.
By volume, natural gas leads installed capacity additions. By growth pace, biomass is climbing the fastest on ANEEL renewable gas incentive structures.
Technology:
Cost tier stratification separates mature steam turbine retrofits from premium combined-cycle installations, with technology choice determining fuel efficiency bands and carbon intensity profiles that shape regulatory compliance costs.
- Combined Cycle:Advanced class gas turbines with dry low-NOx combustors achieve thermal efficiency above 60 percent in Brazilian utility fleets. São Paulo's industrial corridor and Chile's mining regions drive demand for rapid-cycling units that compete with hydroelectric reservoir flexibility.
- Steam Turbine:Supercritical and ultra-supercritical pressure configurations exceeding 22 megapascals maximize efficiency in baseload coal and geothermal applications. Southern Brazilian plants and Colombian Caribbean coast installations concentrate this mature technology base.
- Heat Recovery Steam Generator:HRSG components enable waste heat capture in industrial process applications across Minas Gerais steel and cement complexes.
- Geothermal:Limited volcanic resource development in Chile's Andean spine supports small-scale binary cycle installations for remote mining camps.
By installed base, steam turbines dominate. By expansion trajectory, combined cycle assets are gaining share fastest on LNG infrastructure buildout.
End User:
Customer type determines contract structure and dispatch priority, with utilities commanding regulated return frameworks while industrial offtakers negotiate merchant exposure and capacity separation.
- Utilities:Centrais Eletricas Brasileiras SA and Chilean transmission-distribution companies anchor long-term power purchase agreement volumes. ANEEL and SEC reliability standards preserve thermal dispatch priority during renewable intermittency events.
- Industrial:Copper and lithium mining operations across Chile's Atacama Desert and Peru's Andean slopes require firm capacity that intermittent renewables cannot satisfy. Brazilian steel and petrochemical complexes in Minas Gerais and Rio de Janeiro states drive captive cogeneration demand.
- Commercial:Shopping centers and data centers in São Paulo and Buenos Aires metro zones procure backup thermal capacity for grid outage protection.
- Residential:Limited direct thermal procurement concentrates in remote off-grid communities served by diesel microgrids in Amazonas state and Argentine Patagonia.
By revenue concentration, utilities lead. By contract innovation pace, industrial offtakers are ahead on unbundled energy-capacity procurement structures.
Application:
Dispatch duty cycle determines technology specification and fuel choice, with baseload applications favoring high-efficiency combined cycles while peaking requirements sustain oil-fired turbine flexibility.
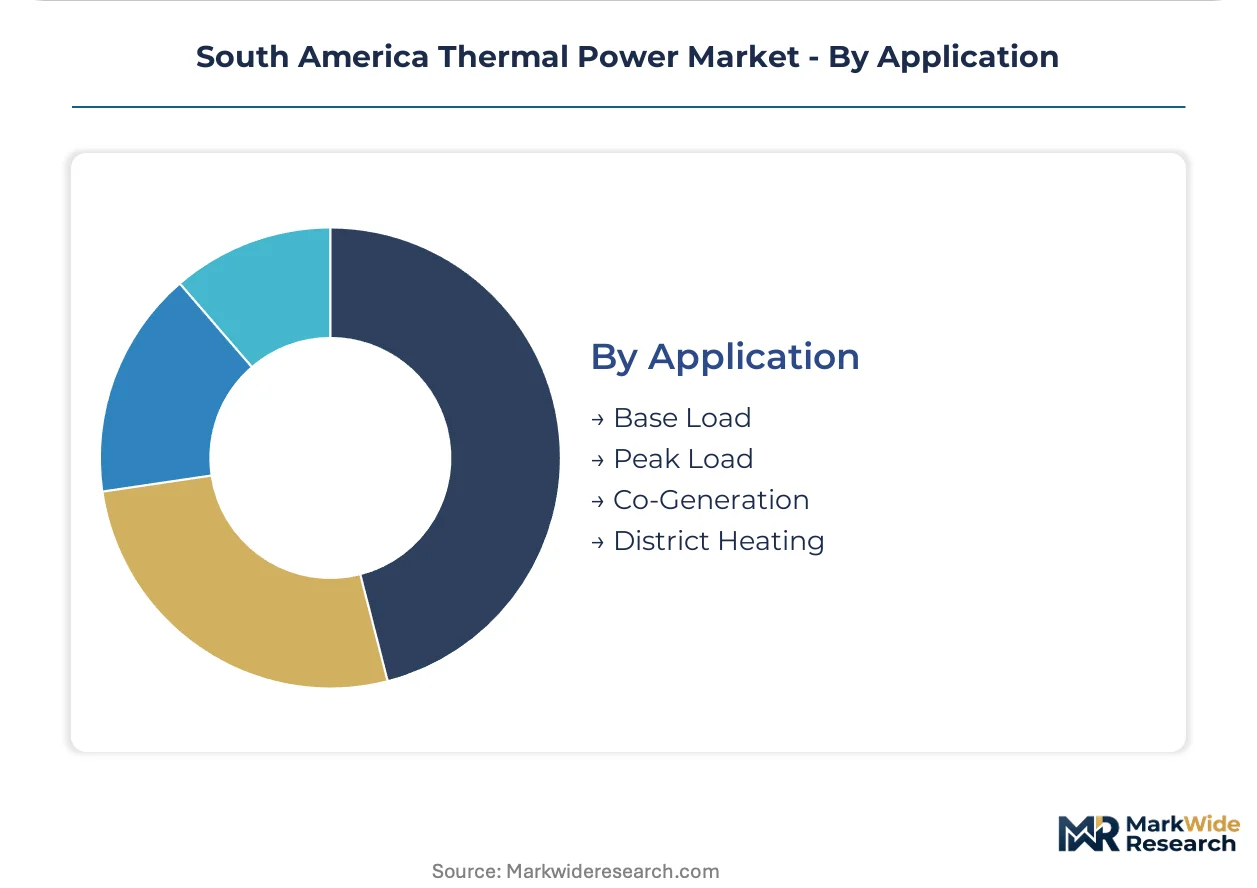
- Base Load:Continuous operation duty favors combined-cycle natural gas units in Brazil's southeastern industrial corridor and Chilean central grid. Mining and smelting operations demand 24/7 thermal backup for process continuity.
- Peak Load:Rapid-start combustion turbines and diesel engines serve Argentine summer demand spikes and Brazilian dry-season hydroelectric shortfalls. ANEEL grid codes mandate spinning reserve capacity that preserves thermal plant dispatch priority.
- Co-Generation:Simultaneous heat and power production integrates with sugar-ethanol processing, pulp and paper mills, and petrochemical complexes across São Paulo and Paraná states.
- District Heating:Limited application in southern Chilean cities and high-altitude Andean population centers where geothermal or biomass thermal integration supports municipal heating networks.
By capacity share, baseload applications dominate. By technology refresh rate, peak load configurations are expanding most quickly on grid flexibility mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for LNG and thermal coal are reshaping generation economics across South America. Pipeline gas deficits in Brazil and Argentina drive coastal import terminal construction. Chilean copper concentrate exports finance power import substitution through domestic gas-fired capacity.
Brazil
São Paulo and Minas Gerais industrial corridors anchor baseload demand for combined-cycle gas turbines. ANEEL reliability mandates preserve thermal dispatch priority during hydroelectric reservoir variability. Petrobras integrates coastal LNG regasification with utility procurement in Rio de Janeiro state.
Chile
Atacama Desert mining operations require firm capacity that solar and wind cannot supply. SEC electrical standards mandate emissions intensity benchmarks that block new coal permits. Antofagasta and Calama industrial clusters drive gas-fired replacement of retiring coal assets.
Argentina
Vaca Muerta shale production expansion offers captive fuel supply for Buenos Aires industrial load. ENRE wholesale market pricing governs thermal generator participation requirements. Neuquén basin gas processing infrastructure feeds combined-cycle development in the Pampas region.
Peru
Pampa Melchorita LNG terminal enables coastal combined-cycle development without pipeline dependency. Copper and lithium extraction across Andean slopes anchors firm power demand. Lima-Callao industrial corridor concentrates procurement for mining sector electricity supply.
Colombia
Northern mining corridors sustain subcritical steam turbine operations for domestic coal consumption. Ministry of Energy transition timelines accelerate retirement of inefficient thermal assets. Caribbean coast installations face carbon intensity pressure from export market access requirements.
South America Thermal Power Market Competitive Landscape
Listed leaders compete with private specialists across fuel security and grid reliability contracting. Centrais Eletricas Brasileiras SA anchors state-backed generation capacity while international utilities capture merchant opportunities. The market fragments across three archetypes: integrated national champions, regional LNG-dependent operators, and mining-captive generators. Dominant competitive moves include combined-cycle retrofits of aging steam assets and strategic partnerships for LNG terminal access.
Among Brazil-based integrated champions, Centrais Eletricas Brasileiras SA and Petrobras exemplify state-linked fuel security models. Italian-headquartered Enel S.p.A occupies a position representing European utility technology transfer into Chilean and Peruvian markets. These three anchors demonstrate how geographic fuel access and regulatory relationships determine competitive positioning across the region's fragmented procurement landscape.
| Leading Market Players |
|---|
| Centrais Eletricas Brasileiras SA |
| AES Corporation |
| Pampa Energía SA |
| Enel S.p.A |
| Colbún S.A |
| Petrobras |
| Engie Energia |
| AES Gener |
| Neoenergia SA |
| Others |
Value Network & Pricing Analysis
Combined-cycle gas turbine retrofits displacing subcritical coal capacity are simultaneously relocating procurement gravity toward Atlantic LNG terminals and compressing long-term power purchase agreement premiums across Brazil's southeastern industrial corridor.
Pricing Analysis
Industrial mining offtakers anchor contract-based long-term offtake structures across Chile's Atacama Desert and Peru's Andean slopes. Price differentiation hinges on fuel security guarantees and ANEEL reliability certification tiers, with coastal LNG-linked plants commanding premiums over pipeline-dependent alternatives. Cost compression in baseload tiers is intensifying because Argentine Vaca Muerta supply expansion erodes import dependency premiums. Merchant industrial buyers exhibit highest price sensitivity, while utility procurement under regulated return frameworks shows lowest elasticity.
Supply Chain Analysis
Strategic stockpiling of critical rotating equipment dominates procurement behavior as supercritical pressure vessel fabrication skills concentrate in German and South Korean supplier bases. Component sourcing draws from Japan for advanced gas turbine blades, Italy for HRSG systems, and the USA for control systems. Single-source vulnerability in specialized welding certification creates procurement chokepoints. Distribution runs through EPC contractors with established ANEEL licensing relationships rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America thermal power market operates as a regulatory entrenchment story where ANEEL reliability mandates and Chilean SEC emissions benchmarks create switching costs that cement incumbent positions.
For Market Incumbents: Shield dispatch priority through accelerated combined-cycle retrofits in São Paulo and Minas Gerais corridors before greenfield LNG terminals saturate coastal capacity. Secure backward integration into biomethane supply chains to capture ANEEL renewable gas incentives. Cement regulatory relationships through proactive grid code compliance investments that extend commissioning timelines for merchant competitors.
For New Entrants and Emerging Players: Remote mining camp power gaps where incumbent utilities under-serve present the most penetrable white space across Chilean and Peruvian Andean slopes. Target captive cogeneration partnerships with lithium extraction operations seeking price exposure to spot markets. Enter through modular turbine leasing structures that bypass long-term PPA negotiation barriers.
For Investors and Strategic Acquirers: Chilean Ministry of Energy decarbonization milestones reshapes the acquisition landscape by accelerating coal asset retirement timelines and compressing gas-fired replacement windows. Long-term viability centers on LNG terminal access rights and ANEEL dispatch priority rankings. Target acquisition archetype: coastal combined-cycle assets with secured regasification capacity. Revision becomes warranted when hydroelectric reservoir variability crosses thresholds that trigger emergency thermal dispatch overrides.
| Strategic Initiative | Industry Significance |
|---|---|
| Combined-Cycle Retrofit | ANEEL reliability mandates preserve dispatch priority for upgraded assets during hydroelectric shortfalls. |
| LNG Terminal Access Partnership | Petrobras coastal regasification integration secures fuel security for utility procurement in Rio de Janeiro. |
| Biomethane Co-Firing Certification | ANEEL renewable gas incentives allow existing turbine assets to capture carbon credit premiums. |
| Mining Captive Generation Development | Copper and lithium extraction operations in Atacama Desert require firm capacity beyond grid supply. |
| Supercritical Welding Capability Investment | European and East Asian supplier concentration extends procurement lead times for pressure vessel fabrication. |
Research Methodology
Desk research of EIA international energy statistics, ANEEL regulatory filings, and IEA power generation databases preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Primary fieldwork across São Paulo, Santiago, and Lima validated secondary projections through bottom-up capacity tracking and top-down demand reconciliation. Triangulation between project development databases and interconnected grid dispatch records anchored segmentation integrity.
Variance decomposition across fuel type, generation capacity tier, and regional grid type shaped the analytical framework over the projection horizon. CAGRs were derived through capacity-weighted averaging of segment-specific expansion trajectories. Modeled inputs incorporated LNG import terminal construction timelines, mining sector electricity intensity coefficients, and hydroelectric reservoir variability indices.
Forecasts assume regulatory continuity in ANEEL reliability standards and Chilean SEC emissions benchmarks; material policy shifts would require re-modeling. Specific risk factors include carbon border adjustment implementation, Argentine export pipeline regulatory reversals, and supercritical equipment procurement delays. Revision becomes warranted when Atlantic basin LNG spot price volatility crosses thresholds that compress combined-cycle operating margins below regulated return floors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Industrial Solar Generator Market
Power Generation
Stirling Engine Market
Power Generation
Global Power to Gas Market
Power Generation
Japan Combined Heat and Power Market
Power Generation
Thermal Power Market
Power Generation
Hydrogenerators Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
India Gas Generator Market
Power Generation
Wind Power EPC Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
East Africa Power Market
Power Generation
Venezuela Power Market
Power Generation
Captive Power Plant Market
Power Generation
Coal Fired Power Generation Market