
 Global Black Start Generator Market | 2026-2036
Global Black Start Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Black Start Generator Market Foresight
Utility providers is rotating toward black start generator procurement as grid resilience mandates tighten across deregulated power markets. Caterpillar Inc. leverages its integrated engine-generator manufacturing footprint to anchor utility-scale diesel deployments. Cummins Inc. competes through modular power system architectures that sustain rapid deployment timelines for independent system operators. Mitsubishi Heavy Industries Ltd specializes in gas turbine black start configurations that dominate combined-cycle plant retrofits in East Asian markets.
A black start generator is a self-starting power unit capable of energizing a grid without external electricity, typically featuring dedicated starting motors, battery banks, or compressed air systems rated for cold-start torque demands. Its primary purpose is restoring grid voltage and frequency after a system-wide blackout by sequentially restarting generation assets and transmission infrastructure. Diesel generators retain the largest installed base among product types due to fuel availability and mechanical simplicity, while battery energy storage systems represent the fastest-growing technology segment as lithium-ion costs decline and response times compress. Power plants command the dominant application share, though data centers are emerging as a concentrated margin pool where uptime guarantees justify premium black start redundancy.
FERC Order 693 and NERC PRC-027-1 in the United States establish mandatory black start capability criteria for bulk power system entities, directly shaping generator specification and testing protocols. EMA grid codes and EU Green Deal resilience frameworks in Europe are extending similar requirements to cross-border transmission operators, tightening product certification pathways. Stakeholders must monitor synchronous condenser technology maturation and flywheel energy storage integration as utilities evaluate hybrid black start architectures against pure diesel baselines.
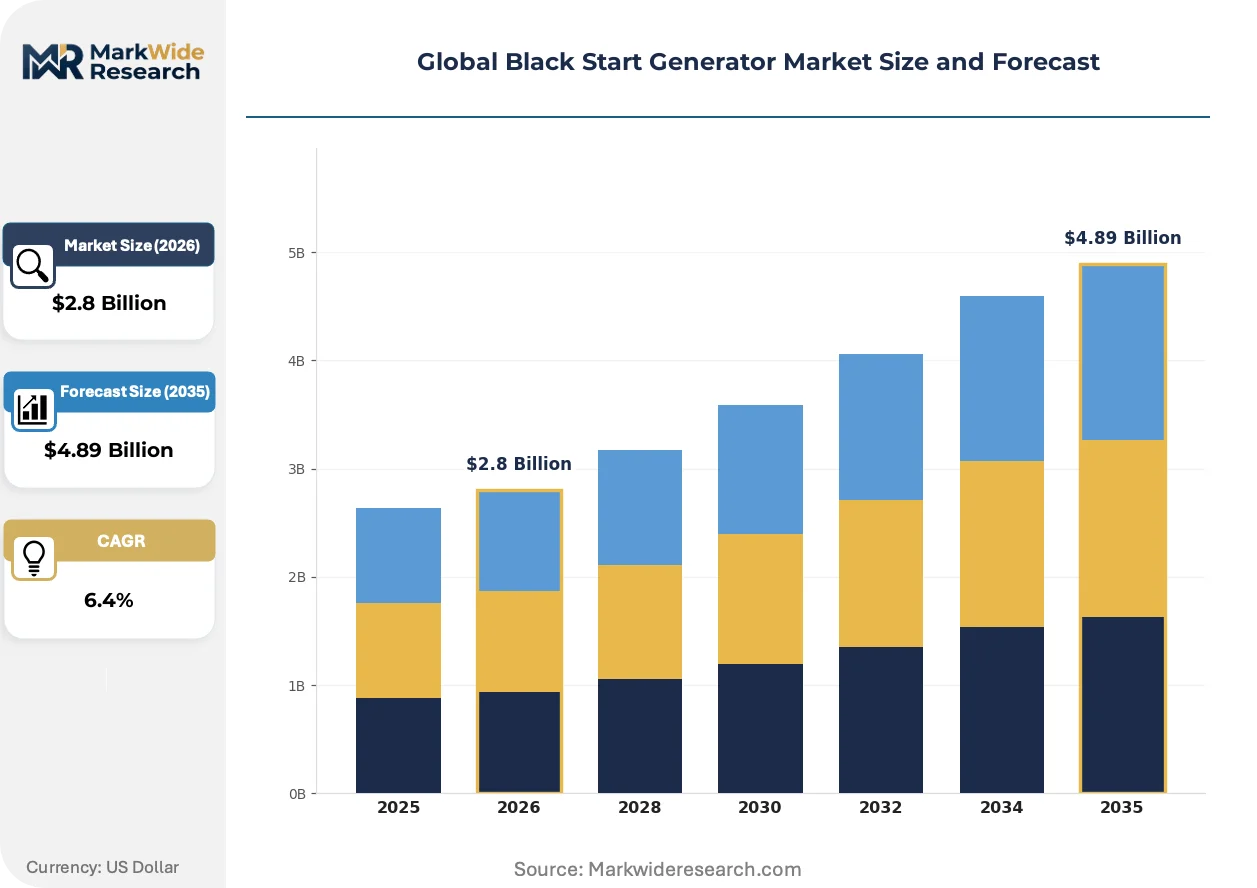
Market Dynamics
Utility procurement cycles are compressing as FERC and NERC mandates force synchronous generator retrofits across deregulated grids, while battery-lithium hybrid architectures challenge diesel incumbents on response-time specifications.
Growth Catalysts
- FERC Order 693:Mandatory black start capability criteria for bulk power system entities in the United States directly expand specification volumes for engine-generator sets.
- Combined-cycle plant retrofits:Gas turbine black start configurations dominate East Asian utility procurement as aging coal baseload retires.
- Data center uptime guarantees:Hyperscale operators in Germany and Japan now require dedicated black start redundancy in colocation contracts.
Market Restraints
- Lithium carbonate price volatility:Battery energy storage system deployments face margin compression from raw material supply concentration in South American brine operations.
- Diesel engine supply consolidation:Foundry capacity for large-bore engine blocks concentrates among a handful of European and Japanese manufacturers.
- NERC PRC-027-1 testing protocols:Compliance timelines extend procurement cycles by 18-24 months for utilities seeking certification.
Strategic Opportunities
- India grid modernization:Central Electricity Authority directives create first-mover advantage for hybrid diesel-battery architectures in state utility tenders.
- EU Green Deal resilience frameworks:Cross-border transmission operators face new product certification pathways that favor low-carbon black start technologies.
- Flywheel-battery convergence:Short-duration mechanical storage paired with lithium-ion compresses frequency restoration timelines for independent system operators.
Industry Challenges
- Synchronous condenser integration:Utilities struggle to retrofit existing turbine halls with rotating inertia equipment without extended outage windows.
- Specialized commissioning engineer scarcity:Grid restoration protocol expertise concentrates among aging utility workforces in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Black Start Generator Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generator, Gas Turbine, Steam Turbine, Hydro Turbine Technology: Battery Energy Storage, Flywheel Energy Storage, Capacitor Banks, Synchronous Condenser Application: Power Plants, Renewable Energy Facilities, Industrial Complexes, Data Centers End User: Utility Providers, Manufacturing Units, Telecom Operators, Oil and Gas Refineries |
| Companies Covered | Caterpillar Inc., Cummins Inc., Mitsubishi Heavy Industries Ltd, Aggreko plc, MTU Onsite Energy, Generac Holdings Inc., General Electric, Man Diesel & Turbo SE, Himoinsa S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Black Start Generator Market Shifts & Advancements
Black start architectures are bifurcating between legacy diesel baselines and electrochemical alternatives, with procurement criteria shifting from fuel availability to frequency response precision.
Lithium-ion battery energy storage systems with integrated inverters are displacing mechanical governor-controlled diesels for sub-50 MW restoration nodes. Independent system operators in Texas and California now specify 4-millisecond response thresholds that chemical storage satisfies. This displacement is compressing diesel generator procurement into megawatt-scale units above battery economic limits.
EU Green Deal resilience frameworks extend black start mandates to cross-border transmission operators previously exempt under national carve-outs. The industrial consequence tightens product certification pathways for synchronous machine manufacturers. German TSOs respond by accelerating flywheel pilot programs to satisfy rotating mass requirements without diesel runtime.
Long-term service agreements now unbundle hardware from commissioning and testing obligations. Utility procurement teams in Japan negotiate separate contracts for equipment supply versus grid restoration protocol validation. This unbundling is most visible in Tokyo and Osaka metropolitan load centers where urban siting restrictions complicate vendor accountability.
Global Black Start Generator Market Segmentation
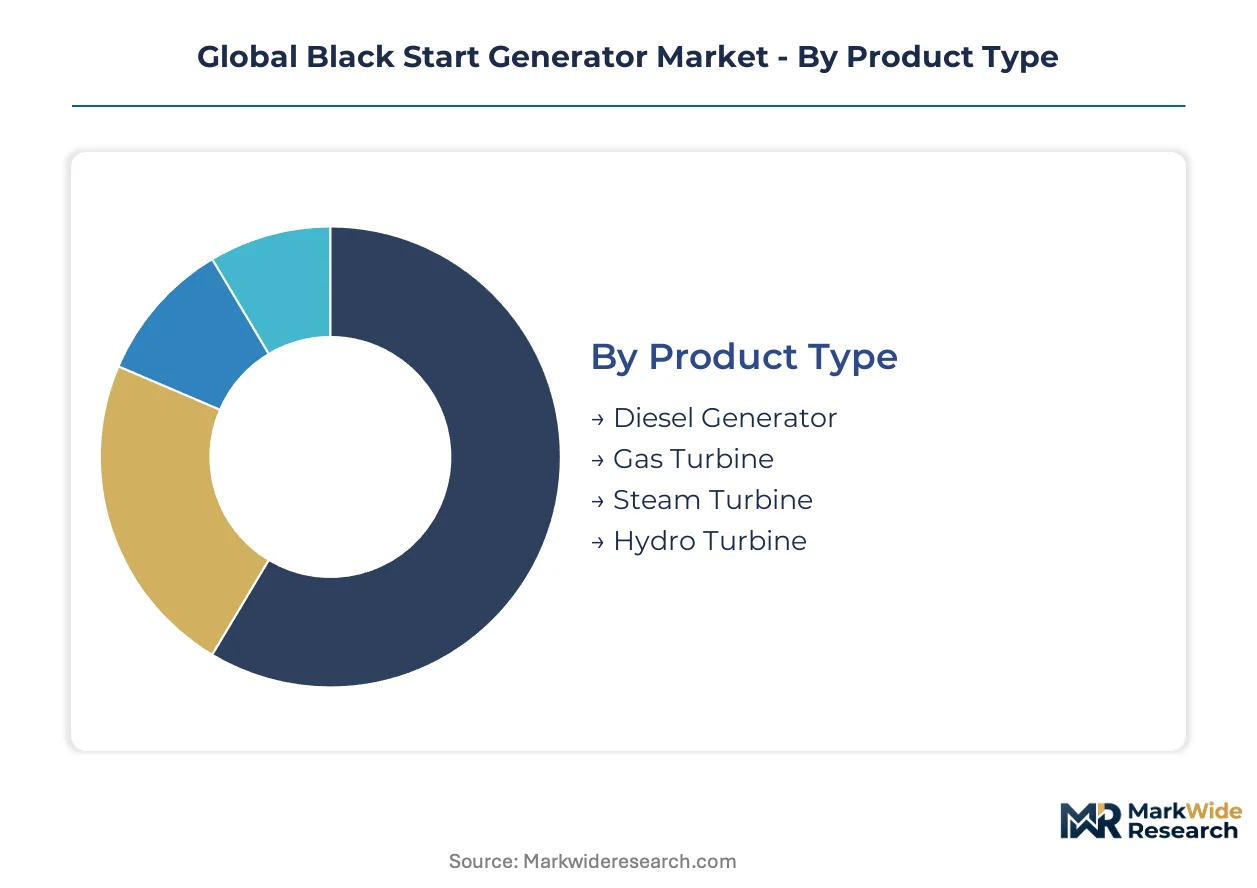
Black start generator procurement splits across four intersecting dimensions that determine specification complexity and vendor selection criteria. Product type and technology choices dictate capital intensity and response-time performance, while application context and end-user identity shape contracting structures and compliance obligations.
Product Type:
Margins concentrate in configurations that balance mechanical simplicity with rapid-start reliability under cold conditions.
- Diesel Generator:Compression-ignition engines with dedicated starting motors and battery banks deliver cold-start torque without external grid dependency. Demand clusters in United States utility retrofits where FERC Order 693 mandates bulk power system compliance and fuel availability concerns dominate procurement.
- Gas Turbine:Aero-derivative and heavy-frame configurations integrate compressed air starting systems for combined-cycle plant black start sequences. Procurement accelerates in Japan and South Korea as aging coal baseload retires and utilities require gas-fired restart redundancy.
- Steam Turbine:Auxiliary boiler and small gas turbine starting arrangements suit nuclear plant emergency diesel replacements.
- Hydro Turbine:Pelton and Francis unit black start capability leverages reservoir head pressure for self-excitation in mountainous geographies.
Diesel Generator holds installed capacity. Gas Turbine is rotating up the share rankings.
Technology:
Technology selection pivots on response-time thresholds that independent system operators now specify in procurement documents.
- Battery Energy Storage:Lithium-ion arrays with integrated inverters achieve sub-100 millisecond frequency response, compressing restoration timelines below mechanical governor limits. Deployment concentrates in Texas and California where ERCOT and CAISO specify 4-millisecond thresholds for grid-forming inverters.
- Flywheel Energy Storage:Rotating mass systems deliver short-duration power without chemical degradation, satisfying rotating inertia requirements in German TSO pilot programs under EU Green Deal resilience frameworks.
- Capacitor Banks:Static VAR compensation supports voltage restoration during initial energization sequences.
- Synchronous Condenser:Rotating machines provide reactive power and short-circuit capacity for weak grid sections.
Battery Energy Storage is climbing the fastest. Flywheel Energy Storage holds niche positioning for rotating mass compliance.
Application:
Application context determines whether black start capability serves regulatory mandate or commercial uptime guarantee.
- Power Plants:Nuclear, coal, and combined-cycle facilities require black start generators for NERC PRC-027-1 compliance and grid restoration protocol participation. Procurement volumes concentrate in United States deregulated markets where independent system operators enforce mandatory capability.
- Data Centers:Hyperscale and colocation facilities in Frankfurt and Tokyo metropolitan areas now contract dedicated black start redundancy to satisfy uptime tier certifications and urban siting restrictions.
- Renewable Energy Facilities:Wind and solar plus storage configurations integrate grid-forming inverters for islanded restart capability.
- Industrial Complexes:Petrochemical and steel installations maintain captive generation for process safety during grid disturbances.
Power Plants anchor procurement volume. Data Centers are expanding most quickly.
End User:
End-user identity shapes whether procurement follows regulated rate-base treatment or competitive tender processes.
- Utility Providers:Investor-owned and public power utilities in Germany, Japan, and the United States execute multi-year capital programs for black start capability expansion, with procurement cycles extending 18-24 months for NERC certification compliance.
- Telecom Operators:Mobile network infrastructure in India requires backup power with black start capability under Central Electricity Authority directives for critical load protection.
- Manufacturing Units:Automotive and semiconductor fabs in Bavaria and Texas negotiate dedicated restart contracts with local distribution utilities.
- Oil and Gas Refineries:Downstream processing facilities in Rotterdam and Singapore maintain gas turbine black start for flare system integrity.
Utility Providers command specification authority. Telecom Operators are gaining procurement momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export black start generator sets to Japanese utilities facing combined-cycle plant retrofits, while United States independent system operators import European synchronous condenser technology for grid hardening mandates.
United States
Independent system operators in Texas and California drive procurement for sub-50 MW battery-lithium hybrid architectures. FERC Order 693 and NERC PRC-027-1 establish mandatory black start capability criteria with 18-24 month certification timelines. ERCOT territory around Houston concentrates diesel generator deployments for bulk power system compliance.
Germany
Transmission system operators accelerate flywheel pilot programs to satisfy rotating mass requirements without diesel runtime. EU Green Deal resilience frameworks tighten product certification pathways for cross-border operators. Frankfurt metropolitan load centers unbundle hardware procurement from grid restoration protocol validation due to urban siting restrictions.
Japan
Utilities require gas turbine black start configurations as aging coal baseload retires across the archipelago. METI directives shape emergency power mandates for nuclear facility restart redundancy. Tokyo and Osaka metropolitan areas negotiate separate contracts for equipment supply versus commissioning expertise.
India
State electricity boards issue tenders for hybrid diesel-battery architectures under Central Electricity Authority grid modernization directives. Telecom operators face backup power mandates for critical load protection in mobile network infrastructure. Maharashtra and Gujarat industrial corridors anchor first-mover procurement for captive generation at process facilities.
South Korea
Combined-cycle plant operators procure aero-derivative gas turbine starting systems for grid restoration sequences. National grid codes extend black start mandates to renewable energy integration zones. Busan-Ulsan petrochemical complex maintains gas turbine black start for flare system integrity during disturbances.
Global Black Start Generator Market Competitive Landscape
Listed leaders compete with private specialists across engine-generator manufacturing and energy storage integration. The vendor base stratifies into three tiers: integrated engine manufacturers with captive foundry capacity, modular power system architects, and rental fleet operators with rapid deployment capabilities. Strategic moves concentrate on backward integration into large-bore engine block production and hybrid technology licensing agreements.
Within the integrated manufacturing tier, Caterpillar Inc. and Cummins Inc. represent archetypal positions. Caterpillar anchors utility-scale diesel deployments through captive engine-generator production. Cummins exemplifies modular architecture specialization for compressed procurement timelines. Mitsubishi Heavy Industries Ltd occupies a distinct position in gas turbine black start configurations for East Asian combined-cycle retrofits.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Mitsubishi Heavy Industries Ltd |
| Aggreko plc |
| MTU Onsite Energy |
| Generac Holdings Inc. |
| General Electric |
| Man Diesel & Turbo SE |
| Himoinsa S.L. |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above 85% at European and Japanese large-bore engine manufacturers compress diesel generator lead times and sustain price floors for utility-scale deployments. This capacity tightness concentrates bargaining power among Caterpillar, Cummins, and MTU Onsite Energy while forcing procurement teams toward longer-term offtake structures.
Pricing Analysis
Diesel-battery hybrid configurations command 15-25% premiums over pure mechanical baselines due to grid-forming inverter integration and dual-certification testing. Pricing stratifies across premium, standard, and economy tiers based on NERC PRC-027-1 certification status and bundled commissioning scope. Cost compression in standard-tier diesel units is intensifying because foundry capacity constraints limit supply elasticity. Independent system operators in Texas exhibit lowest price sensitivity due to ERCOT-mandated response-time specifications, while Indian state electricity boards face acute budget constraints in hybrid architecture tenders.
Supply Chain Analysis
Strait of Malacca transit underwrites 60% of global lithium carbonate flows from South American brine operations to East Asian battery cell manufacturers. Large-bore engine block casting concentrates in Germany, Japan, and the United States, while lithium-ion cell production draws from South Korea, China, and Japan. Single-source vulnerability in South American lithium brine concentration exposes battery energy storage system margins to raw material volatility. Distribution runs through utility capital procurement offices and independent power producer engineering-procurement-construction contractors with 18-24 month certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service agreements for grid restoration protocol validation are expanding faster than hardware shipments as Japanese and German utilities unbundle commissioning from equipment supply. This service-attach dynamic restructures vendor economics toward recurring revenue streams.
For Market Incumbents: Secure captive foundry capacity for large-bore engine blocks through backward integration or exclusive tolling arrangements to defend against lithium-ion substitution in sub-50 MW nodes. Reinforce NERC certification expertise as a moat against modular power system specialists compressing procurement timelines. Prioritize flywheel-battery hybrid R&D to capture EU Green Deal resilience framework mandates without diesel runtime exposure. For New Entrants and Emerging Players: Anchor in Indian state utility tenders for hybrid diesel-battery architectures where Central Electricity Authority directives create first-mover windows without incumbent certification legacy. Target telecom operator backup power mandates as the most penetrable segment given greenfield infrastructure deployment and limited vendor lock-in. Pursue technology licensing partnerships with established inverter manufacturers to bypass engine-generator manufacturing capital intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular power system architects with software-defined grid-forming capabilities over pure hardware manufacturers. Five-to-ten-year viability hinges on hybrid technology portfolios spanning mechanical and electrochemical storage. Acquisition targets should demonstrate integrated inverter control systems and established utility relationships. Watch synchronous condenser retrofit backlog as the inflection signal for rotating mass compliance demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing | Enables battery-diesel convergence for ERCOT and CAISO response-time mandates without captive foundry investment. |
| Long-term Service Agreement Expansion | Captures recurring revenue from grid restoration protocol validation as Japanese utilities unbundle commissioning obligations. |
| Backward Integration into Foundry Capacity | Secures large-bore engine block supply against European and Japanese capacity constraints tightening procurement cycles. |
| Flywheel Pilot Program Partnerships | Positions vendors for German TSO rotating mass requirements under EU Green Deal resilience frameworks without diesel runtime. |
| NERC Certification Compliance Investment | Creates 18-24 month competitive moats against emerging modular specialists in United States deregulated markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators across the United States, Germany, Japan, and India; and secondary validation through FERC filings, NERC reliability standards documentation, EIA generator databases, and IEA grid resilience reports. Bottom-up unit deployment tallies triangulated against top-down addressable market sizing derived from regulatory mandate expansion trajectories.
Across the analysis window, the forecast framework modeled product type, technology, application, and end-user segmentation dimensions with regional regulatory cluster overlays. CAGRs were derived from utility capital expenditure trajectories, independent system operator procurement disclosures, and grid hardening directive implementation timelines. Key inputs included NERC PRC-027-1 certification adoption curves, lithium-ion cost decline trajectories, and combined-cycle plant retrofit pipelines in East Asian markets.
Material uncertainties — lithium carbonate price volatility, foundry capacity expansion decisions, and synchronous condenser technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory mandate enforcement intensity and utility procurement cycle compression. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and Indian grid modernization funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Power Generation Technologies Market
Power Generation
India Thermal Power Plant Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
Peaking Power Plant Market
Power Generation
Oman Power Market
Power Generation
Venezuela Power Market
Power Generation
Asia-Pacific Thermal Power Plant Market
Power Generation
Canada Power EPC Market
Power Generation
East Africa Power Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Marine Power Plant Market
Power Generation
Micro CHP Market
Power Generation
Cogeneration System Market
Power Generation
Oilfield Power Generation Market