
 Nuclear Spent Fuel Market | 2026-2036
Nuclear Spent Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Spent Fuel Market Outlook
The gap between premium engineered storage systems and commodity dry cask commodities is repositioning procurement priorities for utility buyers. Orano leverages its integrated reprocessing-to-storage chain to capture value across multiple fuel cycle stages. Holtec International anchors North American interim storage deployments with its HI-STORM cask systems. EnergySolutions competes on decommissioning bundling, combining spent fuel removal with site remediation contracts.
Nuclear spent fuel comprises irradiated fuel assemblies removed from commercial reactors, typically containing uranium dioxide pellets with burnup levels exceeding 45,000 MWd/MTU and generating decay heat requiring passive cooling for decades. Its primary purpose is secure isolation from the biosphere pending final disposal or reprocessing recovery. Deep geological repositories in granite and clay formations command the longest development timelines but offer the highest regulatory confidence for high-level waste permanence. Interim storage dominates current industry vertical spending as nuclear power operators defer permanent solutions, while reprocessing retains concentrated margin pools in France and Russia through plutonium-uranium recovery.
The U.S. Nuclear Regulatory Commission licenses dry cask storage designs under 10 CFR 72, while Finland's Radiation and Nuclear Safety Authority oversees Posiva's operating permit for the Onkalo spent fuel repository at Olkiluoto. The European Union's Waste Directive imposes national program accountability with defined milestones for geological disposal facility siting. Stakeholders must weigh interim storage extension against repository investment timelines as political and technical uncertainties persist across multiple jurisdictions.
Market Dynamics
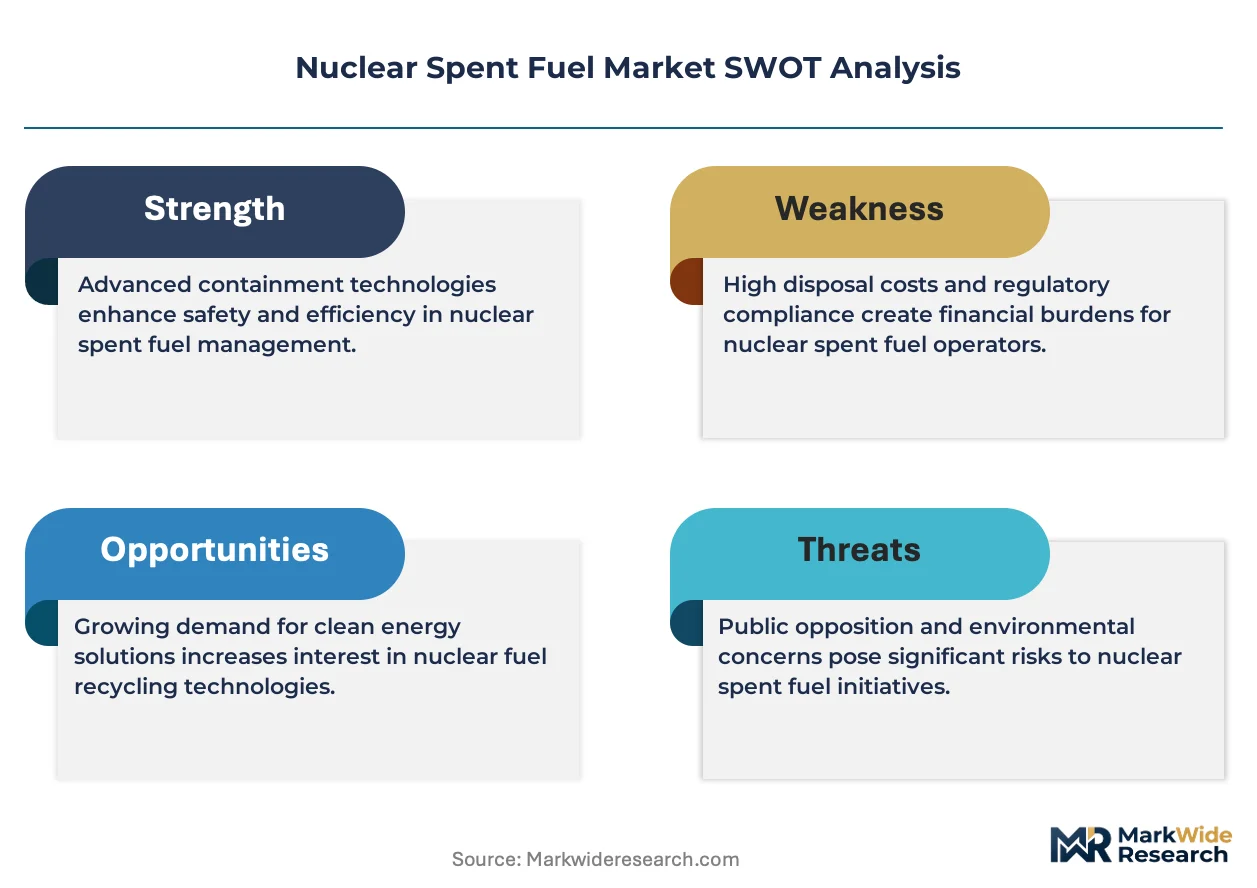
Reactor fleet aging across OECD nations is forcing utilities to commit capital to extended interim storage rather than permanent disposal, compressing investment timelines and reshaping vendor relationships around decades-long service contracts.
Growth Catalysts
- 10 CFR 72 Licensing:The U.S. Nuclear Regulatory Commission's streamlined renewal pathways for dry cask storage systems accelerate deployment timelines for utilities facing pool capacity constraints.
- Finnish Repository Progress:Posiva's operating permit for the Onkalo geological facility validates deep disposal engineering, creating regulatory precedent for similar projects in Sweden and Switzerland.
- Reprocessing Margins:Plutonium-uranium recovery operations in France sustain demand for transport and storage cask fabrication, anchoring specialized manufacturing capacity.
Market Restraints
- Copper Corrosion Uncertainty:Technical debates over canister integrity in sulfide-rich groundwater environments delay licensing decisions for Scandinavian geological repositories.
- Zirconium Alloy Supply:Concentrated production of cladding-grade zirconium in Kazakhstan and Russia creates geopolitical exposure for cask manufacturers dependent on domestic fuel assembly specifications.
- Intergenerational Equity Litigation:Constitutional challenges to long-term liability transfer in Germany and the United States stall centralized storage facility siting.
Strategic Opportunities
- Small Modular Reactor Integration:Advanced reactor developers in Canada and the United Kingdom require standardized spent fuel management protocols, opening design contracts for integrated storage-transport systems.
- EU Waste Directive Milestones:National program accountability requirements create consulting and engineering service demand for member states lagging geological disposal facility development.
- Consolidated Interim Storage:Private fuel storage licensing in Texas and New Mexico offers revenue diversification for utilities willing to accept spent fuel from multiple reactor operators.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section III qualification requirements for thick-walled cask fabrication limit qualified supplier pools, extending procurement lead times to 36-48 months.
- Site-Specific Licensing:Individual NRC certificates of compliance for each dry cask installation prevent manufacturing scale economies despite design standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Spent Fuel Market |
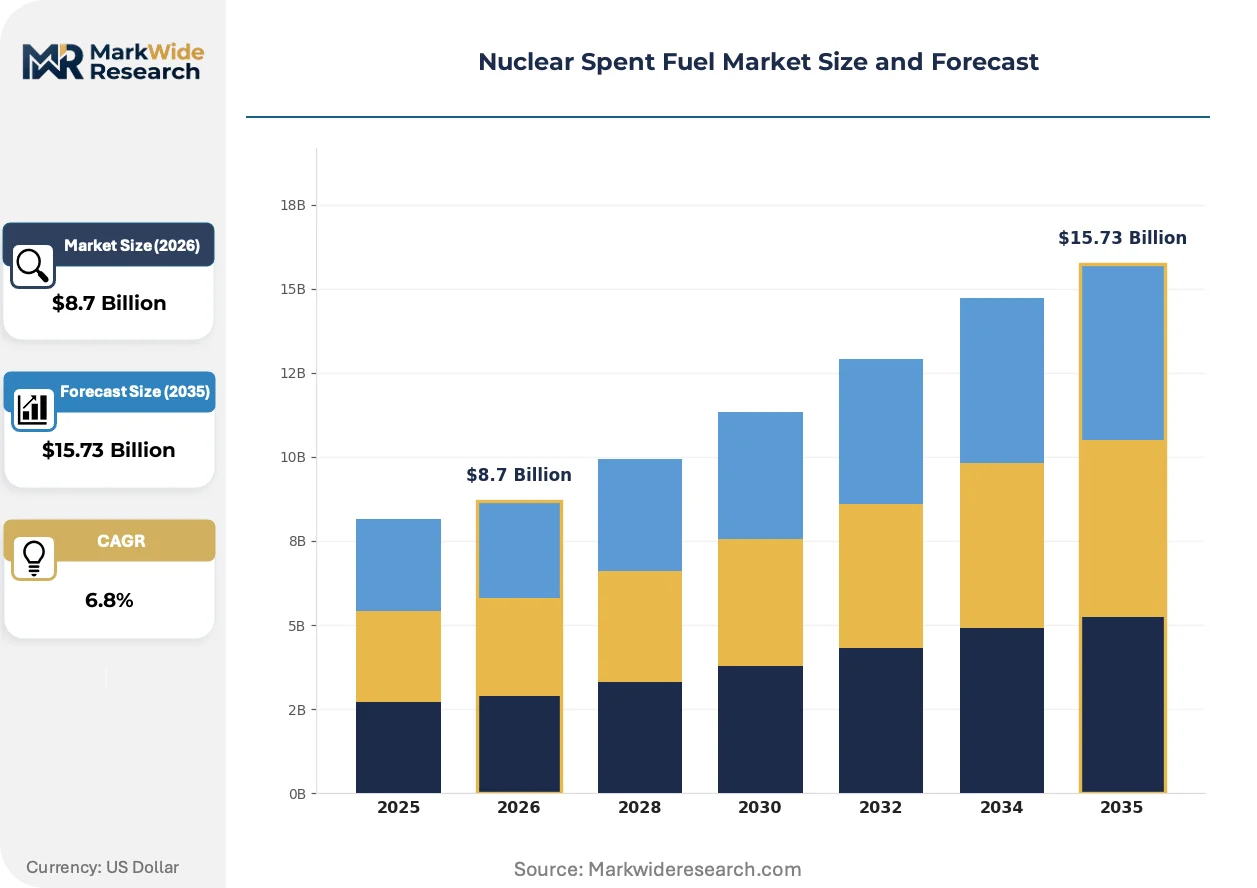
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: High-Level Waste, Intermediate-Level Waste, Low-Level Waste, Transuranic Waste Industry Vertical: Nuclear Power, Research Reactor, Medical Applications, Industrial Applications Management Method: Deep Geological Repositories, Reprocessing, Interim Storage, Near-Surface Disposal Geological Form: Granite, Clay, Salt, Volcanic Rock |
| Companies Covered | Orano, Rosatom, Holtec International, Westinghouse Electric Company, GE Hitachi Nuclear Energy, EnergySolutions, NAC International, Posiva, SKB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Spent Fuel Market Strategic Shifts
Passive cooling system advances and digital monitoring integration are redefining operational requirements for extended storage, while repository program delays force innovation in surface facility design life.
Concrete-steel composite cask technology is decentralizing spent fuel management economics by enabling longer initial storage periods without repackaging. U.S. utilities facing pooled fuel inventory backlogs are adopting these systems at accelerated procurement cycles. The technology is decentralizing vendor market power by reducing dependency on centralized pool-to-cask transfer services and enabling in-house fuel handling capabilities.
The European Union's revised Waste Directive imposes binding national program milestones for geological disposal facility siting with 2050 operational targets. Member states must demonstrate concrete repository progress or face infringement proceedings, accelerating environmental impact assessment contracting. Finland, Sweden, and France hold advanced licensing positions, while Eastern European operators are consolidating interim storage investments to bridge timeline gaps.
Utility procurement departments are unbundling spent fuel removal from comprehensive decommissioning contracts, creating discrete competitive bidding for storage cask supply and transport logistics. Engineering-procurement-construction firms previously capturing bundled site remediation work now face specialized cask vendors competing for standalone fuel management scope. This pattern is most visible in the United States, where reactor operators prioritize capital efficiency through segmented contract structures.
Nuclear Spent Fuel Market Segmentation
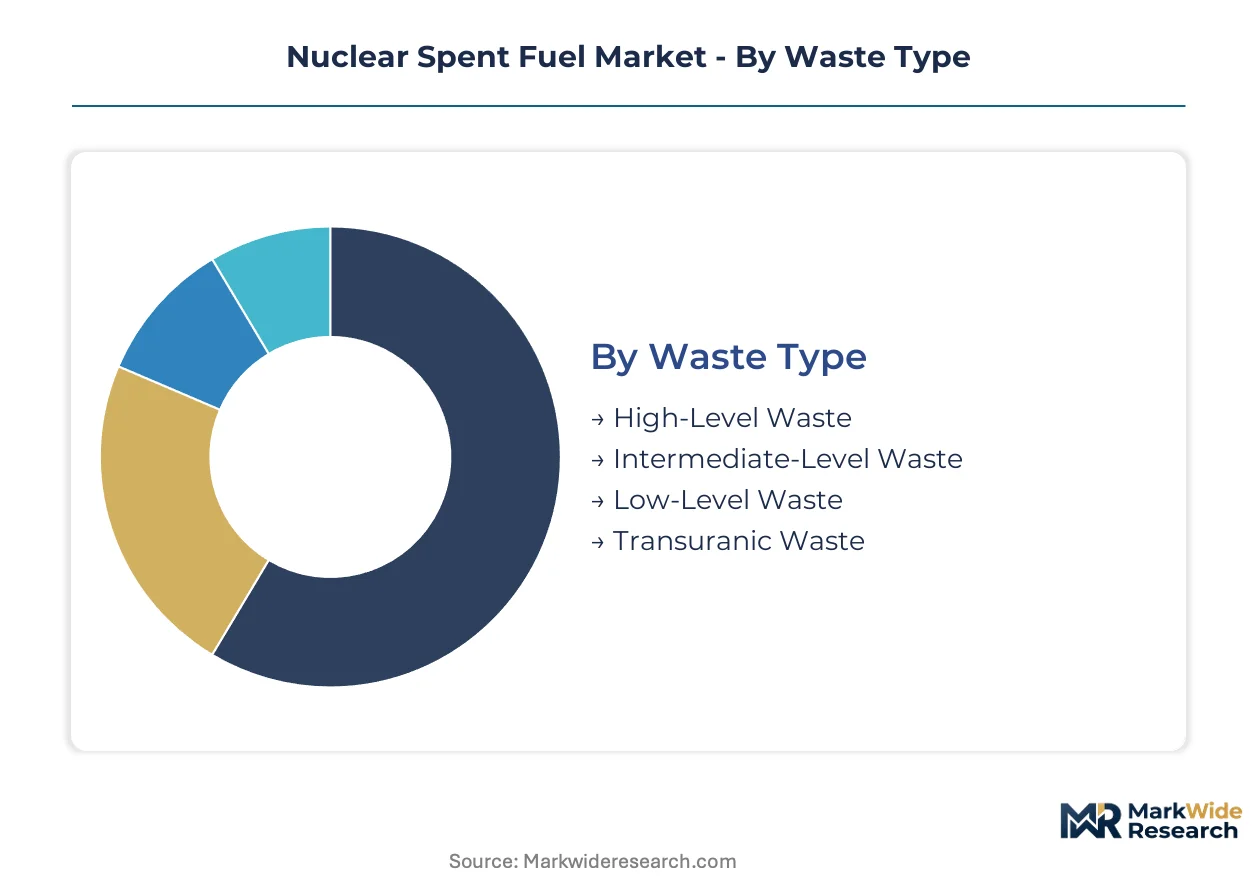
Nuclear spent fuel procurement decisions hinge on decay heat profiles, regulatory jurisdiction, and disposal pathway timelines. Segmentation reveals how utilities allocate capital across interim storage extensions versus permanent repository commitments.
Waste Type:
Decay heat intensity and radiotoxicity duration determine handling protocols and storage duration requirements for utility buyers.
- High-Level Waste:Spent fuel assemblies with burnup exceeding 45,000 MWd/MTU generate substantial decay heat requiring passive cooling for decades. Finnish utilities at Olkiluoto and Swedish operators in Forsmark concentrate procurement of copper-cast iron canisters for deep geological isolation.
- Intermediate-Level Waste:Resins, filters, and reactor components with moderate activity levels demand cementitious encapsulation. French reprocessing facilities at La Hague anchor demand for this segment through plutonium-uranium separation operations.
- Low-Level Waste:Contaminated protective clothing and tools with minimal radiotoxicity suit near-surface disposal. U.S. EnergySolutions dominates volume through its Clive, Utah disposal facility serving western reactor operators.
- Transuranic Waste:Alpha-emitting isotopes from fuel fabrication and reprocessing require remote handling. The U.S. Department of Energy's Waste Isolation Pilot Plant in New Mexico accepts defense-origin material under specific radionuclide limits.
Volume sits with Low-Level Waste; growth tilts toward High-Level Waste.
Industry Vertical:
Reactor scale and operational continuity shape contract structures and vendor relationships across fuel cycle services.
- Nuclear Power:Commercial reactors generate spent fuel volumes measured in thousands of metric tons annually. U.S. operators facing pool capacity constraints drive dry cask procurement through 10 CFR 72 licensing pathways.
- Research Reactor:University and test reactors produce smaller fuel quantities with higher enrichment residues. European operators concentrate demand through centralized services at CERN and IAEA-coordinated return programs.
- Medical Applications:Molybdenum-99 production and isotope irradiation create compact spent fuel streams. Canadian NRU reactor decommissioning shifted this segment toward interim storage reliance.
- Industrial Applications:Gamma irradiation for sterilization and materials testing generates cobalt-60 contaminated hardware. Limited volumes restrict dedicated infrastructure investment.
Procurement concentrates in Nuclear Power; Research Reactor services are expanding most quickly through international fuel return initiatives.
Management Method:
Regulatory certainty and capital recovery mechanisms determine whether utilities pursue permanent disposal or extend interim storage.
- Deep Geological Repositories:Engineered barriers in stable rock formations provide isolation timescales exceeding 100,000 years. Posiva's Onkalo facility in Finland validates this approach through operating license achievement.
- Reprocessing:Plutonium and uranium recovery reduces waste volumes and creates mixed-oxide fuel feedstock. Orano's La Hague complex in France sustains this segment through closed-fuel-cycle contracts with Japanese and European utilities.
- Interim Storage:Dry cask systems enable decades-long surface storage pending permanent solutions. U.S. utilities dominate procurement through Holtec HI-STORM and NAC International Magnastor deployments.
- Near-Surface Disposal:Engineered trenches accommodate low-activity waste with institutional control periods. French Centre de l'Aube and Swedish SFR facility anchor European capacity.
Capital deployment favors Interim Storage; regulatory momentum builds behind Deep Geological Repositories.
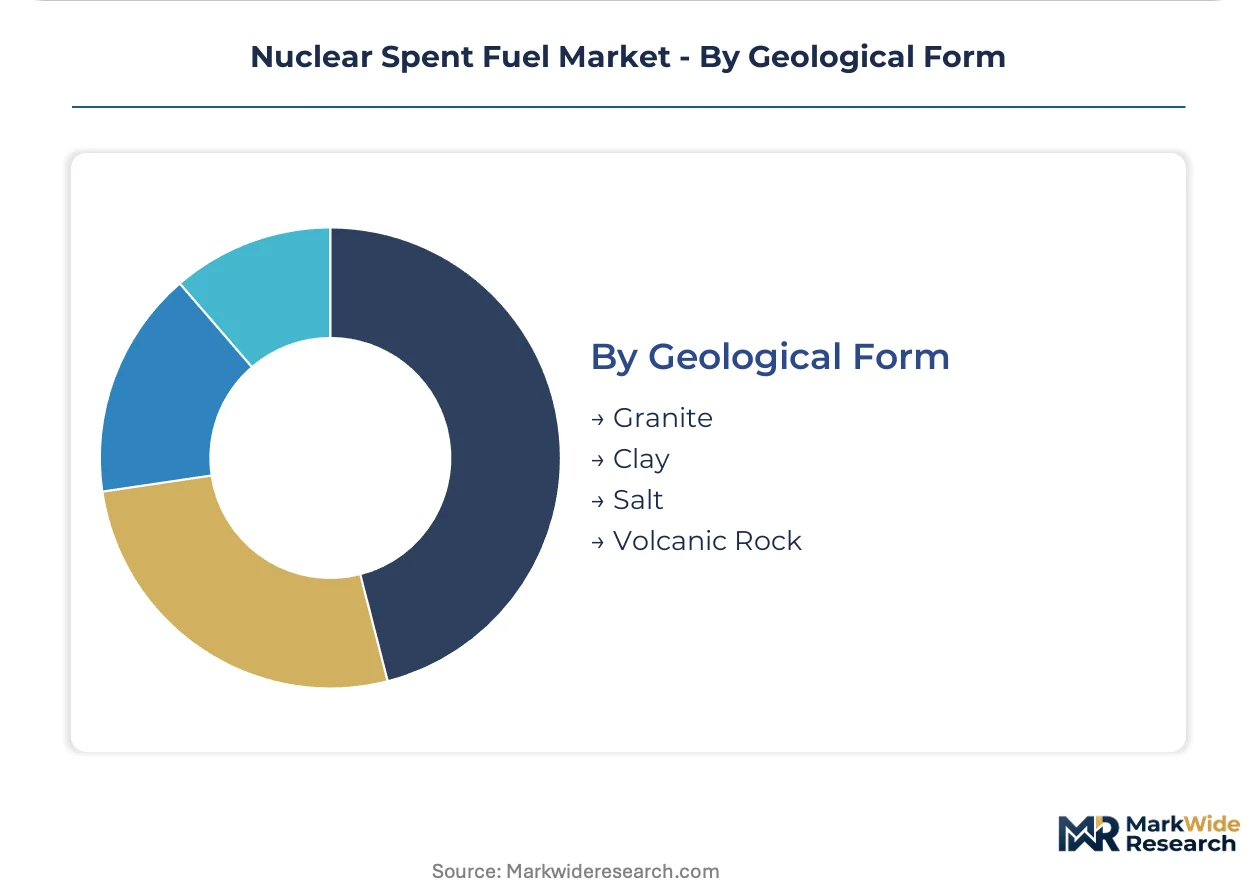
Geological Form:
Site-specific hydrogeology and rock mechanics dictate repository design and licensing timelines across candidate formations.
- Granite:Crystalline basement rocks offer low permeability and tectonic stability for canister emplacement. Swedish SKB targets Forsmark granite for its Spent Fuel Repository through KBS-3 method licensing.
- Clay:Plastic, self-sealing formations retard radionuclide migration through diffusion-dominated transport. France's Cigeo project in Meuse/Haute-Marne clay faces delayed commissioning through technical and political review.
- Salt:Creep closure and thermal conductivity suit high-heat waste emplacement. Germany's Asse and Morsleben pilot facilities encountered flooding challenges that complicated public acceptance.
- Volcanic Rock:Tuff formations at Yucca Mountain, Nevada underwent extensive characterization before program suspension. Alternative volcanic sites in Japan and Taiwan remain under preliminary investigation.
Technical validation concentrates in Granite; Clay formations show steepest expansion trajectory through French and Swiss program advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Olkiluoto anchors European geological repository development through Posiva's licensed Onkalo facility, while interim storage investments concentrate across North American and Asian reactor fleets confronting deferred permanent disposal timelines.
United States
Pool capacity constraints at aging pressurized water reactors drive accelerated dry cask procurement under 10 CFR 72 licensing pathways. The Nuclear Regulatory Commission's streamlined renewal protocols compress deployment timelines for utilities facing spent fuel inventory backlogs. Texas and New Mexico host consolidated interim storage licensing activity for private fuel management facilities.
Finland
Posiva's operating permit for the Onkalo deep geological repository validates copper-cast iron canister emplacement in Olkiluoto granite. The Radiation and Nuclear Safety Authority oversees the only licensed spent fuel disposal facility worldwide. Finnish utilities concentrate procurement of engineered barrier systems for high-burnup fuel assemblies exceeding 45,000 MWd/MTU.
Sweden
SKB advances licensing for the Forsmark spent fuel repository using the KBS-3 method in crystalline basement rock. Sulfide-rich groundwater chemistry debates delay final canister integrity certification. The Oskarshamn interim storage facility anchors national fuel consolidation pending geological disposal commissioning.
France
Orano's La Hague reprocessing complex sustains plutonium-uranium recovery operations for domestic and Japanese utility contracts. The Cigeo deep geological repository project in Meuse/Haute-Marne clay faces delayed commissioning through technical and political review cycles. French regulators enforce national program milestones under revised EU Waste Directive accountability frameworks.
Japan
Tokyo Electric Power and other operators extend interim storage at reactor sites following Fukushima Daiichi decommissioning complications. The Nuclear Regulation Authority reviews geological disposal facility siting in coastal sedimentary formations. Rokkasho reprocessing plant commissioning delays reinforce dry cask dependency for commercial reactor fleets.
Nuclear Spent Fuel Market Competitive Environment
Premium-margin players sit above commodity-margin players across licensing complexity and service integration depth. The vendor base organizes around three archetypes: integrated fuel cycle operators capturing value across reprocessing-to-storage chains, specialized cask fabricators dominating interim storage hardware procurement, and site remediation bundlers combining fuel removal with decommissioning scope. Consolidation pressures favor multi-decade service contracts over discrete equipment sales, while welding certification bottlenecks limit qualified supplier pools for thick-walled containment fabrication.
Within the integrated operator tier, Orano exemplifies closed-fuel-cycle positioning through its La Hague reprocessing complex and associated transport logistics. Holtec International anchors North American interim storage deployments with standardized cask system designs licensed under 10 CFR 72. EnergySolutions occupies the site remediation bundler position, combining spent fuel removal with comprehensive decommissioning contracts for utilities pursuing capital efficiency through segmented procurement structures.
| Leading Market Players |
|---|
| Orano |
| Rosatom |
| Holtec International |
| Westinghouse Electric Company |
| GE Hitachi Nuclear Energy |
| EnergySolutions |
| NAC International |
| Posiva |
| SKB |
| Others |
Value Chain & Pricing Dynamics
Copper-cast iron canister fabrication for deep geological repositories is reshaping procurement economics and concentrating supplier power among ASME Section III-qualified welders. This shift toward thick-walled containment systems simultaneously elevates certification premiums and compresses the qualified vendor pool, creating pricing asymmetry between utilities with long-term cask service contracts and those reliant on spot procurement.
Pricing Analysis
Outcome-based pricing tied to decades-long storage performance anchors contract structures for dry cask systems. Three-tier pricing structure across premium, standard, and economy levels separates NRC-certified designs from commodity alternatives, with price differentiation driven by burnup compatibility and passive cooling duration. Cost compression in standard-tier cask fabrication is intensifying because welding certification bottlenecks limit supplier competition. Research reactor operators exhibit highest price sensitivity due to fragmented fuel volumes, while Finnish and Swedish utilities pursuing geological disposal show lowest sensitivity given repository timeline pressures.
Supply Chain Analysis
Zirconium alloy supply rests on concentrated production in Kazakhstan and Russia, creating geopolitical exposure for cladding-grade material specifications. The supply chain draws from specialized steel foundries in the United States, France, and Japan for thick-walled cask forgings, with neutron shielding resin formulations sourced from German and Japanese chemical producers. Single-source vulnerability in ASME-qualified welding certification extends procurement lead times substantially. Distribution runs through utility-direct contracting for reactor-site installations, with consolidated interim storage facilities in Texas and New Mexico emerging as secondary offtake nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over cask fabrication and transport logistics determines margin capture. Players are pursuing backward integration into qualified welding capacity and neutron shielding material production to defend pricing power.
For Market Incumbents: Deploy multi-decade service contracts bundling cask supply with pool-to-cask transfer operations to lock out specialized competitors. Incumbents must secure ASME Section III welding certification capacity before supplier pools tighten further, while investing in digital monitoring integration to extend design life claims against repository delays. For New Entrants and Emerging Players: Launch via modular cask system designs targeting small modular reactor developers in Canada and the United Kingdom. White-space concentration sits in standardized transport-storage systems for advanced reactor fuel forms, with EU Waste Directive consulting services offering the most penetrable entry point for engineering-procurement-construction firms lacking nuclear licensing heritage. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated fuel cycle operators seeking cask fabrication capability. Long-term viability favors vendors with NRC 10 CFR 72 design certification and established utility relationships over commodity fabricators. The signal to watch is copper corrosion resolution in Scandinavian sulfide-rich groundwater, which would accelerate geological repository procurement and displace interim storage demand.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Section III Certification Investment | Expands addressable contract scope for thick-walled containment fabrication beyond current supplier constraints. |
| Consolidated Interim Storage Licensing | Creates private fuel management revenue streams in Texas and New Mexico independent of utility ownership. |
| Digital Monitoring System Integration | Extends dry cask design life claims through real-time thermal and radiation monitoring for NRC renewal pathways. |
| Copper-Cast Iron Canister Supply Agreement | Locks geological repository procurement for Posiva and SKB deep disposal programs in Finnish and Swedish granite. |
| Small Modular Reactor Protocol Development | Captures design standardization contracts for advanced reactor spent fuel management in Canada and the United Kingdom. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility fuel cycle managers, NRC licensing specialists, cask fabrication procurement leads, and geological repository program directors combined with bottom-up and top-down triangulation. Secondary sources encompassed U.S. Nuclear Regulatory Commission 10 CFR 72 licensing databases, Finnish Radiation and Nuclear Safety Authority permit records, European Union Waste Directive national progress reports, and International Atomic Energy Agency spent fuel management databases.
Data-stream reconciliation across reactor fleet age profiles, pool capacity utilization rates, and cask deployment schedules informed the analytical framework. Segmentation dimensions modeled encompassed waste type decay heat intensity, management method regulatory certainty, geological formation hydrogeology, and industry vertical reactor scale. CAGRs were derived through installed base projection and replacement cycle analysis, with nuclear power plant retirement timelines and repository commissioning milestones serving as key forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for concrete-steel composite cask systems would alter the outlook if passive cooling duration claims extend beyond current regulatory baselines. Forecasts reflect assumptions regarding NRC licensing efficiency, copper corrosion resolution timelines, and EU Waste Directive enforcement intensity. Repository program delays, zirconium supply disruptions, and intergenerational equity litigation outcomes constitute specific revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Thorium Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Global Power Plant Uranium Market