
 Europe LFP Battery Pack Market | 2026-2036
Europe LFP Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Europe LFP Battery Pack Market Insights
Iron phosphate chemistry is recalibrating cell economics across European passenger and commercial vehicle programs. CATL leverages its Erfurt gigafactory to supply localized LFP cells directly to German OEM platforms. Northvolt anchors its competitive stance through integrated cathode active material production at its Skellefteå complex, then extends battery system assembly via its planned Salzgitter joint venture. Samsung SDI competes by specializing in high-nickel alternatives but maintains LFP development lines for cost-sensitive commercial vehicle contracts.
Lithium iron phosphate battery packs use lithium iron phosphate as the cathode material paired with a graphite anode, delivering nominal voltages near 3.2 volts per cell with thermal runaway thresholds above 270°C, making them suitable for high-cycle applications where safety margins outweigh energy density priorities. Standard packs dominate current automotive volumes due to established form factors and simpler thermal management requirements, while modular packs represent the fastest-growing architecture as fleet operators demand field-replaceable units for commercial electric vehicles. Smart battery management systems command disproportionate margin pools because software-defined state-of-charge algorithms differentiate warranty terms and insurance classifications across European markets.
REACH compliance and the EU Battery Regulation's carbon footprint declaration requirements are reshaping import dynamics for Chinese-origin LFP cells, while CE marking and the EU Green Deal's critical raw materials benchmarks dictate local content thresholds for subsidy eligibility. ECHA's evolving substance restrictions on fluorinated compounds may alter electrolyte formulations within the forecast horizon. Stakeholders must monitor how the EU AI Act's risk classification rules apply to predictive battery management algorithms before committing to software architectures.
Market Dynamics
The EU Battery Regulation's carbon footprint declaration requirements and due diligence mandates are forcing cell-to-pack localization across European automotive supply chains. OEMs must now prove supply chain transparency and embodied carbon thresholds to qualify for Green Deal subsidies.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint declarations and recycled content quotas are accelerating domestic LFP cell production investments.
- Commercial vehicle electrification:Fleet operators in Germany and France are specifying LFP chemistry for high-cycle bus and delivery van applications where safety margins outweigh range requirements.
- Cell-to-pack architecture:Elimination of module housings reduces pack weight and assembly cost, enabling OEMs to offset LFP's energy density gap against nickel-based alternatives.
Market Restraints
- Graphite anode supply concentration:Synthetic and natural graphite processing capacity concentrates in China, exposing European pack assemblers to supply disruption and ECHA substance scrutiny.
- Lithium carbonate price volatility:Raw material cost swings compress margin predictability for cathode active material producers serving the LFP value chain.
- Energy density ceiling:Iron phosphate chemistry's theoretical specific energy limit constrains pack-level range performance in premium passenger vehicle segments.
Strategic Opportunities
- Spain's emerging automotive corridor:Underdeveloped cell manufacturing capacity in the Basque and Catalonia regions creates first-mover positioning for integrated cathode-to-pack facilities.
- Second-life stationary storage:Retired automotive LFP packs are repurposing for grid-scale buffering, opening circular economy revenue streams.
- EU Critical Raw Materials Act:Domestic lithium refining and phosphate rock processing incentives reduce import dependency for cathode precursors.
Industry Challenges
- Battery management system firmware certification:CE marking timelines for predictive state-of-health algorithms lag behind hardware validation cycles, delaying platform launches.
- Electrolyte formulation requalification:ECHA's evolving fluorinated compound restrictions force iterative testing of non-PFAS electrolyte salts without guaranteed performance parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe LFP Battery Pack Market |
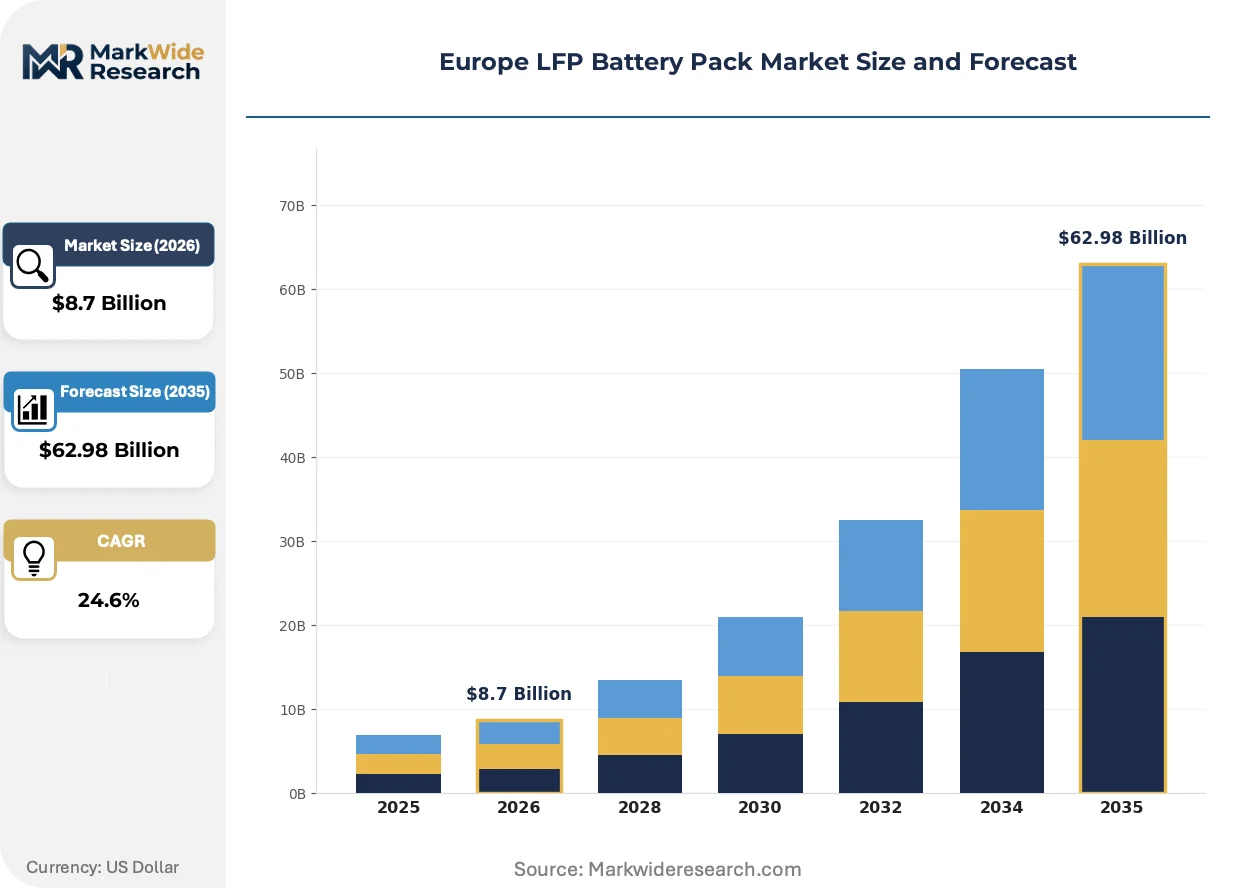
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Packs, Modular Packs, High-Performance Packs, Industrial Packs End User: Electric Vehicles, Renewable Energy Systems, Consumer Electronics, Industrial Equipment Application: Energy Storage, Automotive, Portable Power, Grid Management Technology: LFP Chemistry, Smart Battery Management, Thermal Management, Fast Charging |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), BYD Company Ltd., LG Energy Solution, Ltd., Samsung SDI Co., Ltd., Northvolt, CALB Group Co., Ltd., ACC, Prime Planet Energy & Solutions Inc., BASF, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe LFP Battery Pack Market Trends and Innovations
Iron phosphate chemistry is converging with structural battery pack designs that eliminate traditional module housings. This architectural shift compresses manufacturing steps and reduces embodied carbon, aligning with EU industrial policy objectives.
Cell-to-pack technology is converging with thermal runaway propagation suppression systems. OEMs in Germany and France are adopting this combination for commercial vehicle platforms where field-replaceable units must maintain safety across 500,000+ kilometer lifecycles. The integration is compressing pack assembly labor content while elevating software-defined thermal management to core competitive differentiation.
REACH compliance enforcement is tightening substance disclosure requirements for imported LFP cells. The European Chemicals Agency's expanded candidate list obligations are forcing Chinese cell suppliers to reconfigure material declarations or establish European toll manufacturing arrangements. Pack assemblers in Poland and Hungary are absorbing the compliance burden through enhanced incoming inspection protocols.
Fleet procurement is consolidating around total-cost-of-ownership models that weight cycle life and residual value above upfront pack price. Logistics operators in the Netherlands and Belgium are specifying 10-year warranty terms and guaranteed buyback clauses, displacing transactional spot purchasing. This behavioral shift concentrates contract volumes with pack integrators offering integrated financing and end-of-life takeback services.
Europe LFP Battery Pack Market Segmentation
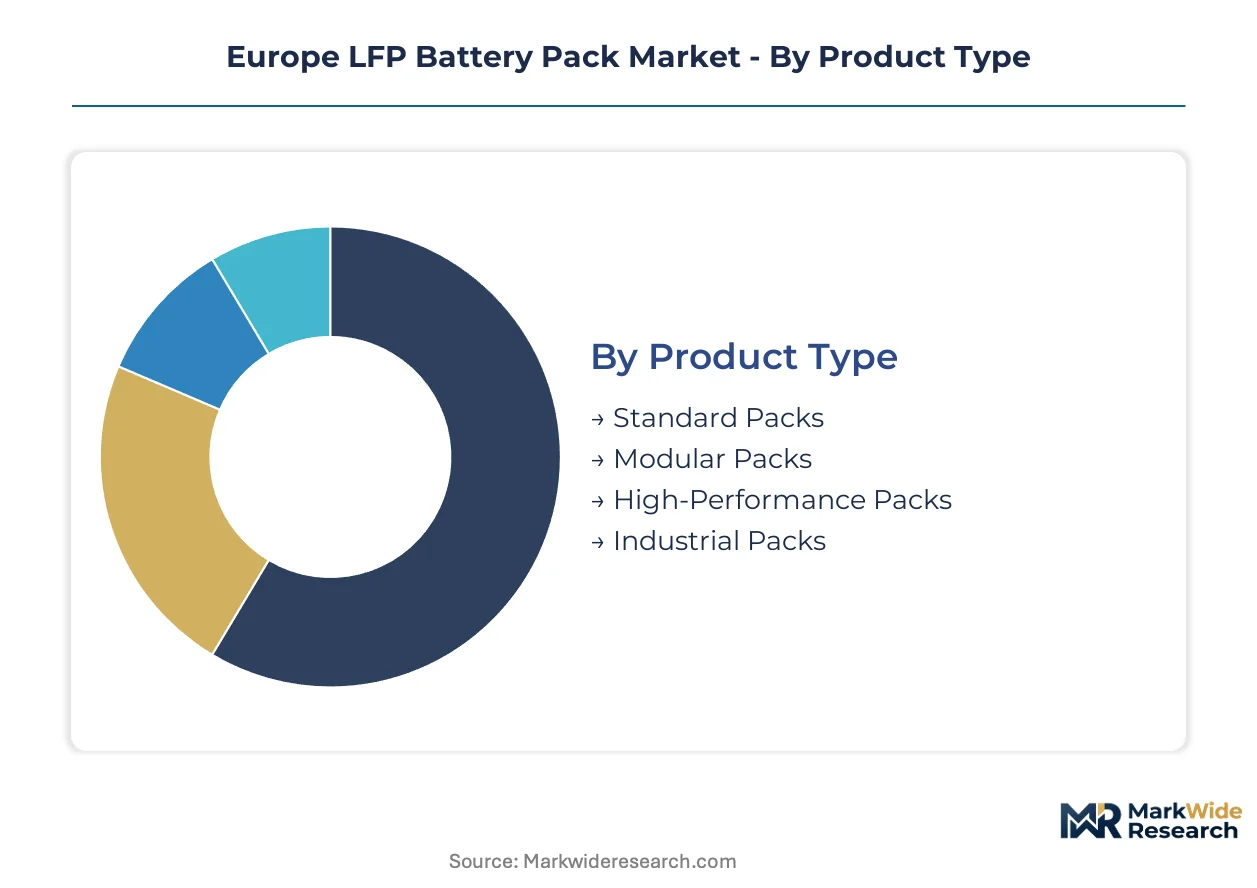
Segmentation in the Europe LFP Battery Pack Market reveals how iron phosphate chemistry adapts across divergent performance requirements and regulatory contexts. Understanding these divisions exposes where pack assemblers concentrate R&D investment and which customer categories drive margin expansion.
Product Type:
Cell architecture and integration density define how LFP packs compete against nickel-based alternatives in European applications.
- Standard Packs:Established form factors with simpler thermal management requirements dominate current automotive volumes. German OEM platforms specify these units for entry-level passenger vehicles where cost predictability outweighs customization needs.
- Modular Packs:Field-replaceable architectures with standardized interfaces enable rapid swap-out in commercial fleets. Logistics operators in the Netherlands and Belgium specify these units for 24/7 delivery van operations where downtime minimization drives procurement decisions.
- High-Performance Packs:Optimized power density configurations serve premium passenger segments with demanding acceleration profiles.
- Industrial Packs:Ruggedized enclosures with extended cycle life ratings anchor material handling and port electrification programs.
Standard packs lead on scale; modular packs lead on momentum.
End User:
Customer categories impose distinct certification burdens and lifecycle service expectations on European pack suppliers.
- Electric Vehicles:Passenger and commercial platforms require CE-marked systems with EU Battery Regulation carbon footprint declarations. Volkswagen Group and BMW procurement teams specify localized cell-to-pack assembly to qualify for Green Deal subsidies.
- Renewable Energy Systems:Stationary storage integrators prioritize cycle life and degradation predictability over energy density. Spanish solar developers are specifying LFP buffers for grid-scale projects in the Basque region.
- Consumer Electronics:Compact form factors with integrated battery management serve portable power tool and e-bike manufacturers.
- Industrial Equipment:Heavy-duty cycle ratings and IP-rated enclosures support forklift and automated guided vehicle fleets.
Electric vehicles command volume concentration; renewable energy systems are expanding most quickly.
Application:
Use-case environments determine thermal management complexity and safety system redundancy in pack design.
- Energy Storage:Containerized systems with passive cooling architectures serve behind-the-meter and front-of-meter installations. French utility procurement frameworks specify these units for frequency regulation services.
- Automotive:Crash-resistant enclosures with propagation-resistant cell spacing meet ECE R100 and UN 38.3 transport requirements.
- Portable Power:Lightweight enclosures with integrated inverters target construction and outdoor recreation segments.
- Grid Management:Utility-scale installations with megawatt-hour stacking capability support network stabilization contracts.
Automotive applications anchor revenue concentration; energy storage claims the steepest expansion trajectory.
Technology:
Subsystem differentiation determines warranty terms and insurance classifications across European markets.
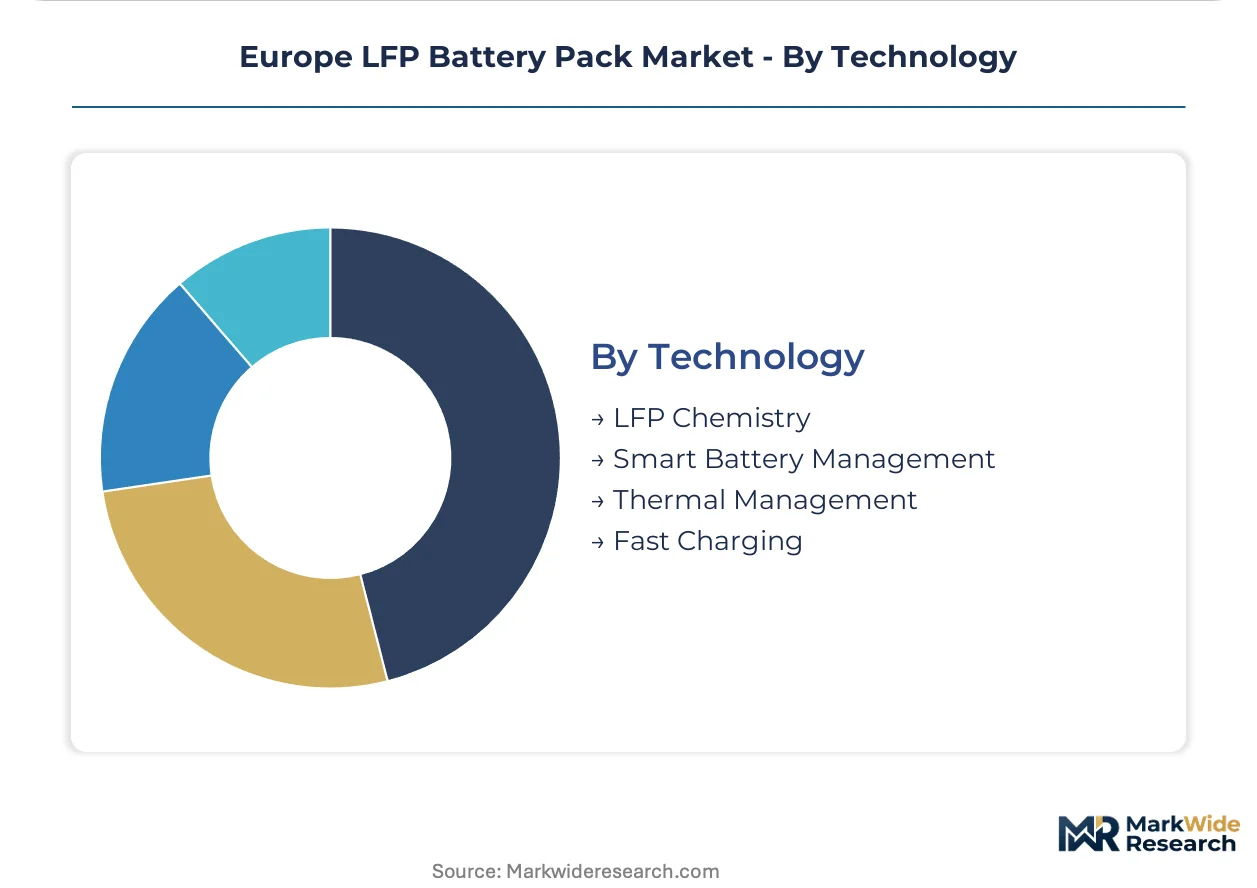
- LFP Chemistry:Lithium iron phosphate cathode material with graphite anode delivers nominal 3.2V per cell and thermal runaway thresholds above 270°C. CATL's Erfurt facility supplies localized cells to German OEM platforms.
- Smart Battery Management:Software-defined state-of-charge algorithms with predictive state-of-health monitoring command disproportionate margin pools. CE marking timelines for these firmware systems lag hardware validation cycles.
- Thermal Management:Liquid cooling circuits and phase-change materials maintain cell temperature uniformity across extreme ambient conditions.
- Fast Charging:High-rate capable cell formulations with reinforced current collectors enable 10-80% charge windows under 30 minutes.
LFP chemistry provides the foundational cost structure; smart battery management delivers margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor concentrates cell-to-pack manufacturing investments as OEMs localize LFP supply chains to satisfy EU Battery Regulation compliance thresholds.
Germany
Volkswagen Group and BMW procurement teams are mandating localized LFP cell sourcing for entry-level EV platforms. The EU Battery Regulation's carbon footprint declaration requirements are accelerating domestic cathode active material investments. Erfurt hosts CATL's gigafactory supplying cells directly to German OEM assembly lines, while Salzgitter anchors Northvolt's planned joint venture for battery system production.
France
Renault and Stellantis are specifying LFP chemistry for commercial van fleets operating high-cycle delivery routes. The EU Green Deal's critical raw materials benchmarks are shaping subsidy eligibility for domestic pack assembly. The Hauts-de-France region clusters ACC's Douai gigafactory, which is ramping LFP-compatible cell lines for automotive contracts.
Spain
Solar developers in the Basque region are procuring containerized LFP buffers for grid-scale storage projects tied to renewable generation. REACH compliance enforcement is tightening substance disclosure requirements for imported cells. Catalonia's emerging automotive corridor attracts cathode-to-pack facility investments as regional governments compete for EU Just Transition Fund allocations.
Poland
Pack assemblers near the German border are absorbing REACH compliance burdens through enhanced incoming inspection protocols for Chinese-origin cells. The EU AI Act's risk classification rules are delaying firmware certification timelines for predictive battery management systems. Lower Silesia hosts manufacturing operations serving Volkswagen Group's Bratislava assembly plant with localized pack integration.
Sweden
Northvolt anchors integrated cathode production at Skellefteå, extending downstream into battery system assembly for European OEM customers. The EU Critical Raw Materials Act is incentivizing domestic lithium refining investments to reduce import dependency. Västerbotten County concentrates Europe's most advanced LFP cell manufacturing complex, with expansion plans targeting commercial vehicle and stationary storage segments.
Europe LFP Battery Pack Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers race to establish localized cell-to-pack production ahead of EU Battery Regulation enforcement deadlines. The market structure consolidates around three tiers: integrated cell-to-pack specialists, cathode material suppliers extending downstream, and pack assemblers dependent on imported cells. Strategic archetypes include scale-driven volume producers, chemistry-focused innovators, and system integrators leveraging software differentiation. Competitive moves center on backward integration into cathode active materials and geographic expansion into underpenetrated European corridors.
Within the integrated manufacturing tier, Contemporary Amperex Technology Co., Limited exemplifies scale-driven localization through its Erfurt facility serving German OEM platforms directly. BYD Company Ltd. and Northvolt occupy distinct positions as chemistry specialists with divergent geographic origins—Chinese and European respectively—yet both are converging on cell-to-pack architectures that eliminate module housings. These three entities anchor the competitive structure through contrasting approaches to supply chain control and regulatory compliance positioning.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Ltd. |
| LG Energy Solution, Ltd. |
| Samsung SDI Co., Ltd. |
| Northvolt |
| CALB Group Co., Ltd. |
| ACC |
| Prime Planet Energy & Solutions Inc. |
| BASF |
| Others |
Pricing and Supply Chain Analysis
Cell-to-pack architecture elimination of module housings compresses assembly labor content while simultaneously redistributing cost concentration toward cathode active material inputs and software-defined battery management systems across European LFP supply chains.
Pricing Analysis
Input-cost pass-through from lithium carbonate and synthetic graphite anode suppliers governs pack-level pricing dynamics. Contract-based long-term offtake agreements dominate procurement between German OEMs and cell producers, with price differentiation anchored in volume scale and CE marking tier. Cost compression in standard pack configurations is intensifying because Chinese-origin cell suppliers absorb REACH compliance burdens to maintain market access. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while premium passenger OEMs prioritize cycle-life guarantees over upfront unit economics.
Supply Chain Analysis
EU Battery Regulation carbon footprint declarations and recycled content quotas are forcing pack assemblers to reconfigure sourcing away from Chinese cell imports toward localized production. Cathode active material supply concentrates in China, South Korea, and emerging European facilities at Skellefteå and Salzgitter. Raw material dependencies rest on lithium carbonate from South American brine operations, phosphate rock processing capacity, and synthetic graphite anode supply. Single-source vulnerability in graphite purification exposes European pack integrators to ECHA substance scrutiny and potential supply disruption. Distribution runs through just-in-sequence delivery to OEM assembly plants and containerized shipment to stationary storage integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe LFP Battery Pack Market operates as a stable compounder where regulatory-driven localization mandates ensure sustained capacity absorption across the forecast horizon.
For Market Incumbents: Extend cathode-to-pack integration depth to defend margin position against emerging Chinese suppliers establishing toll manufacturing in Poland and Hungary. Prioritize backward integration into lithium refining and phosphate processing under EU Critical Raw Materials Act incentive frameworks. Accelerate firmware certification timelines to close the gap between hardware validation and CE marking for predictive battery management systems. For New Entrants and Emerging Players: EU Battery Regulation in Europe opens a window for specialized pack integrators to capture share in Spain's underdeveloped Basque and Catalonia automotive corridors. Target second-life stationary storage applications where retired automotive packs feed grid-scale buffering contracts with guaranteed buyback clauses. Pursue joint venture structures with regional governments competing for EU Just Transition Fund allocations to secure site permits and subsidy eligibility. For Investors and Strategic Acquirers: Roll-up economics work for modular pack specialists with established fleet operator relationships because warranty servicing capabilities and end-of-life takeback infrastructure create switching costs that concentrate contract volumes. Five-to-ten-year viability hinges on positioning ahead of EU AI Act enforcement on predictive algorithm risk classification. Monitor ECHA fluorinated compound restriction timelines as inflection indicator for electrolyte formulation requalification costs that will reshape competitive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Backward Integration | EU Critical Raw Materials Act incentives reduce import dependency for lithium and phosphate precursors. |
| Cell-to-Pack Manufacturing Scale-Up | Elimination of module housings aligns with EU Battery Regulation embodied carbon thresholds for Green Deal subsidy access. |
| Smart Battery Management Firmware Certification | CE marking acceleration closes launch delays caused by EU AI Act algorithm risk classification requirements. |
| Second-Life Stationary Storage Partnership | Grid-scale buffering contracts with French utilities and Spanish solar developers open circular economy revenue streams. |
| Regional Joint Venture Formation | Salzgitter and Basque region facilities leverage local content rules to qualify for national electrification procurement frameworks. |
Research Methodology
Multiple input streams — primary interviews with cell production engineers and OEM procurement leads, secondary validation against ECHA substance databases and EU Battery Regulation implementation guidance, and trade flow analysis of cathode precursor imports — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged include battery system architects at Tier 1 suppliers, regulatory compliance officers at pack assemblers, fleet procurement managers at logistics operators, and cathode material R&D directors. Secondary sources encompass EU official journal regulatory texts, national automotive production statistics, and customs declarations for lithium carbonate and graphite anode shipments.
Historical production capacity deployment patterns were cross-referenced against expert panel assessments of EU Battery Regulation enforcement timelines to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled span pack architecture type, end-use application, vehicle class, and regional production cluster. CAGRs were derived from installed capacity ramp schedules and OEM platform launch cadences, with particular weighting applied to commercial vehicle electrification mandates and stationary storage procurement frameworks.
Revisions become necessary when ECHA substance restriction timelines accelerate, EU AI Act algorithm certification requirements harden, or lithium carbonate price volatility exceeds historical bands. Forecasts reflect documented assumptions on localization thresholds and carbon footprint declaration compliance rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
US EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market