
 Europe Electric Bus Battery Pack Market | 2026-2036
Europe Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Bus Battery Pack Market Insights
Procurement channels between cell manufacturers and European bus OEMs is rewriting traditional supply relationships. Northvolt AB leverages its Swedish gigafactory output to secure long-term contracts with domestic transit manufacturers. CATL sustains cost competitiveness through scale advantages in LFP cell production for continental fleet operators. Akasol AG specializes in modular pack architectures that integrate with multiple European bus platforms.
A Europe Electric Bus Battery Pack constitutes an integrated energy storage system comprising lithium-ion cells, thermal management hardware, battery management electronics, and structural enclosures designed to deliver sustained high-current discharge for zero-emission passenger transport. Cell chemistry selection determines energy density, cycle life, and thermal stability under demanding urban duty cycles. LFP chemistry dominates municipal deployments where safety and longevity outweigh gravimetric density requirements. NMC variants occupy intercity applications demanding extended range from constrained pack volumes. Smart Battery Systems technology leads technology segmentation as operators prioritize predictive diagnostics and charge optimization.
EMA, ECHA, and the EU Green Deal collectively mandate stricter carbon thresholds and chemical safety protocols for heavy-duty vehicle batteries sold across member states. REACH compliance and forthcoming CSRD disclosure rules add traceability and due diligence burdens throughout cell supply chains. Stakeholders must monitor how delegated acts under the EU Battery Regulation reshape minimum recycled content quotas and carbon footprint declarations before placing packs on the European market.
Market Dynamics
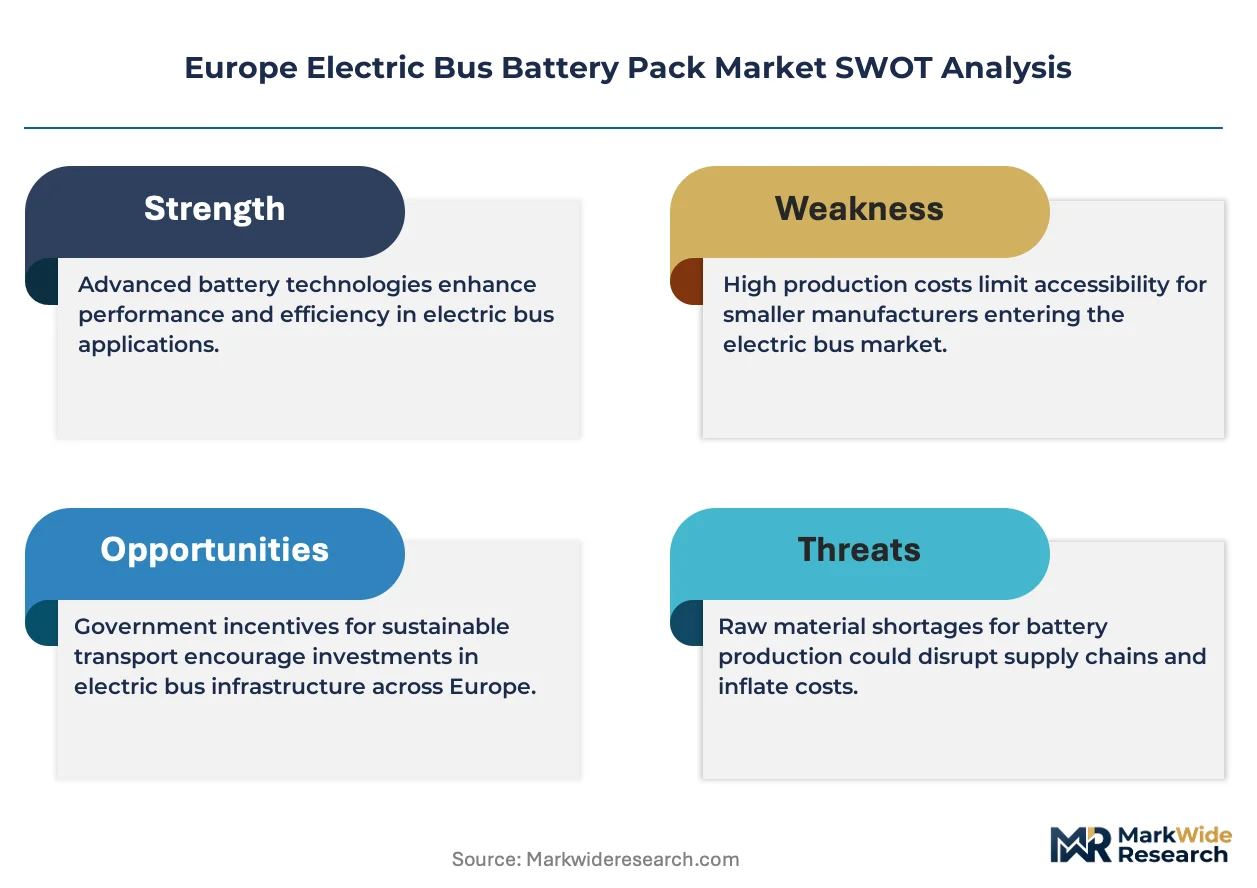
EU Green Deal carbon thresholds and delegated acts under the EU Battery Regulation are compressing procurement cycles and mandating recycled content quotas, forcing pack suppliers to reconfigure supply chains before placing products on the European market.
Growth Catalysts
- EU Green Deal mandates:Binding CO2 standards for heavy-duty vehicles accelerate municipal fleet electrification programs across Germany and France.
- LFP chemistry dominance:Thermal stability and cycle life advantages in lithium iron phosphate cells satisfy safety requirements for urban duty cycles.
- Nordic corridor budgets:Public transport electrification allocations in Sweden, Norway, and Denmark concentrate demand for high-capacity packs.
Market Restraints
- Cell supply concentration:Asian cell manufacturers control LFP production scale, exposing European pack assemblers to input cost volatility and currency risk.
- REACH compliance burdens:Chemical safety protocols and traceability requirements add due diligence costs throughout cathode material supply chains.
- Gravimetric density limits:LFP chemistry's lower energy density constrains range extension for intercity bus platforms requiring maximum pack volume efficiency.
Strategic Opportunities
- Eastern European fleet modernization:Poland, Czechia, and Romania present underpenetrated transit electrification budgets with EU cohesion fund backing.
- CSRD disclosure alignment:Corporate Sustainability Reporting Directive rules create first-mover advantage for pack suppliers with verified carbon footprint declarations.
- Smart Battery Systems convergence:Integration of predictive diagnostics with charge optimization software enables premium pricing for connected fleet management.
Industry Challenges
- Thermal engineering talent scarcity:Pack manufacturers compete for specialists in liquid cooling system design and simulation modeling.
- Certification timeline compression:UN ECE R100 and EU Battery Regulation delegated acts require simultaneous homologation updates across multiple member state approval bodies.
- Legacy depot infrastructure:Grid connection upgrades and high-power charging installation delay fleet deployment schedules for municipal operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Bus Battery Pack Market |
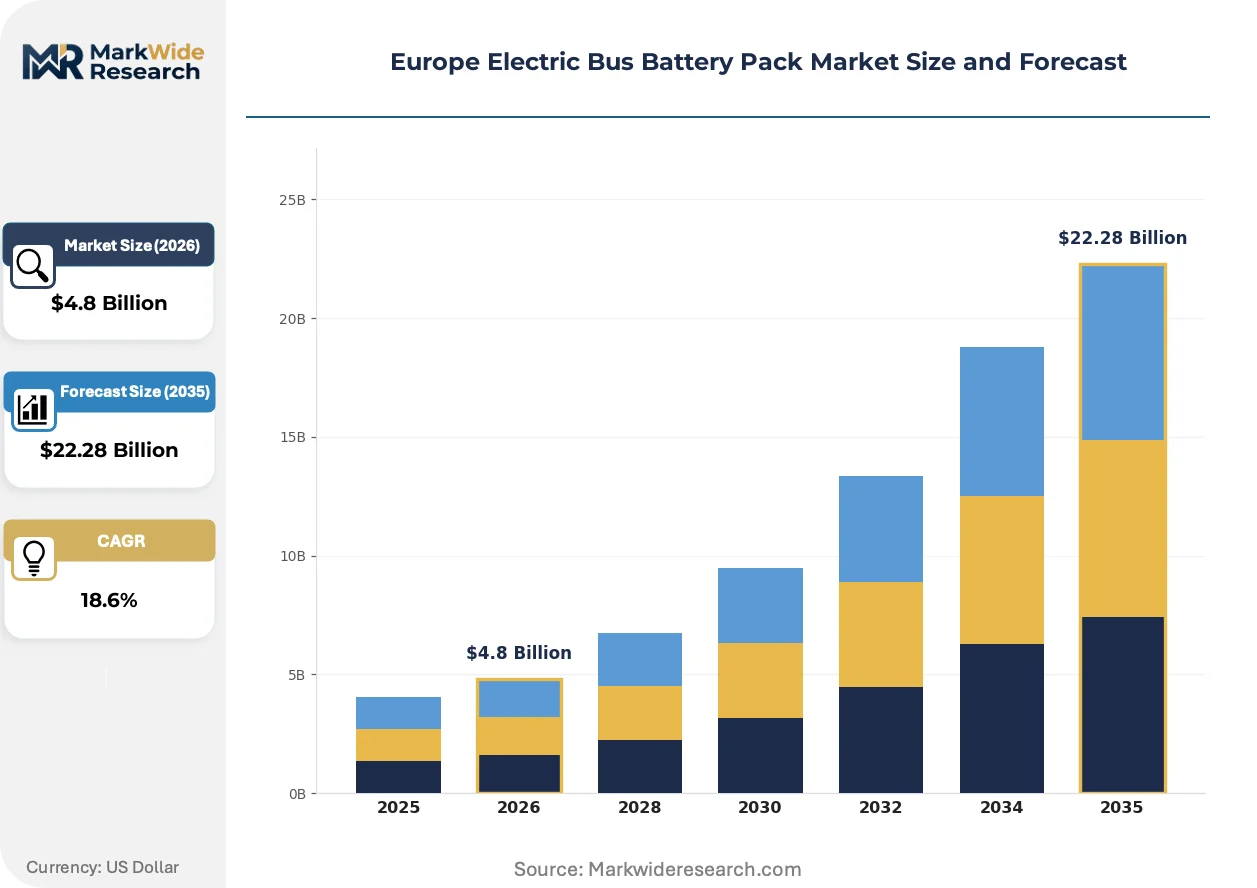
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, NCA, LTO Application: Public Transport, Intercity Buses, School Buses, Tour Buses Technology: Fast Charging, Wireless Charging, V2G, Smart Battery Systems End User: Public Transport Operators, Fleet Managers, Municipalities, Private Companies |
| Companies Covered | Northvolt AB, Panasonic Holdings Corporation, Contemporary Amperex Technology Co. Ltd. (CATL), Akasol AG, SK On, BYD Company Ltd., Microvast Holdings Inc, BMZ Holding GmbH, LG Energy Solution Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Bus Battery Pack Market Trends and Innovations
Cell-to-pack architectures and solid-state prototyping are compressing pack volume requirements while thermal runaway prevention systems raise safety benchmarks. These shifts are redefining supplier qualification criteria and procurement evaluation frameworks.
Silicon-anode blending in NMC cells is rendering obsolete conventional graphite-only anode designs for intercity bus applications. German and French OEMs are qualifying these chemistries for extended-range platforms. The technology is rendering obsolete previous generation energy density limitations that forced larger pack footprints.
Delegated acts under the EU Battery Regulation mandate minimum recycled content quotas and carbon footprint declarations for industrial batteries placed on the European market. Pack suppliers must establish audited recycling partnerships and lifecycle assessment documentation before contract eligibility. Heavy-duty vehicle segments face the steepest compliance timelines, with Nordic operators already incorporating these requirements into tender specifications.
Swedish and Norwegian transit authorities are unbundling battery pack procurement from complete bus purchases, creating direct contracting relationships with specialized pack suppliers. Municipal fleet managers now negotiate separate warranties and service agreements for energy storage systems. This pattern is most visible in the Nordic corridor, where public transport electrification budgets support dedicated technical evaluation teams.
Europe Electric Bus Battery Pack Market Segmentation
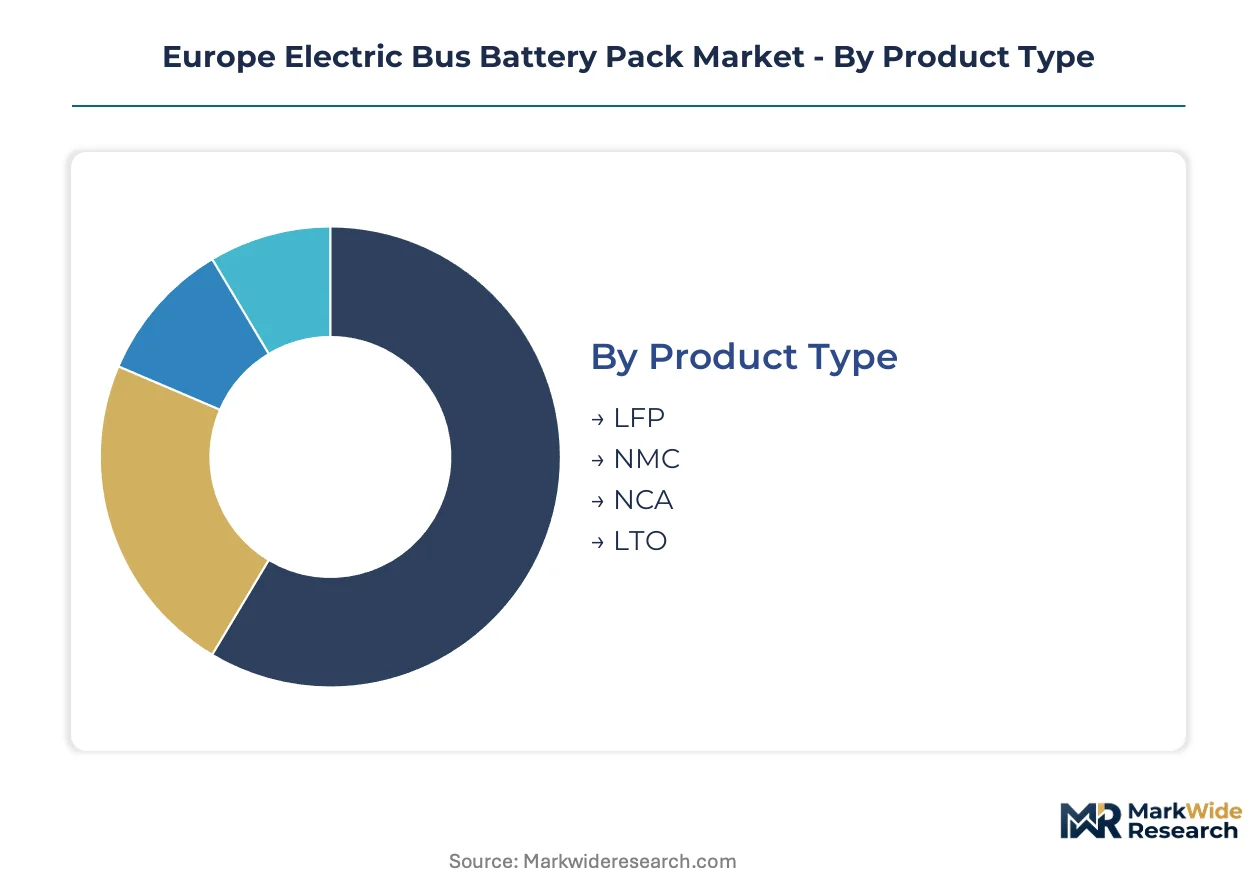
Segmentation in the Europe Electric Bus Battery Pack Market reveals distinct procurement cycles and technical requirements across chemistry types, duty cycles, and operator categories. Procurement timelines vary from 18-month municipal tender cycles to multi-year fleet modernization programs, reshaping how pack suppliers allocate engineering resources and inventory.
Product Type:
LFP cells turn over fastest in procurement cycles due to standardized municipal specifications, while NMC variants face longer qualification periods for intercity range requirements. LTO occupies niche replacement schedules given its extreme cycle life.
- LFP:Lithium iron phosphate chemistry delivers thermal stability above 270°C and 3,000-6,000 cycle life under standard urban duty profiles. German and French municipal operators specify LFP for depot-charged single-shift routes where safety protocols outweigh energy density targets.
- NMC:Nickel-manganese-cobalt layered oxide cells achieve 220-250 Wh/kg gravimetric density enabling 400km+ intercity ranges from constrained pack volumes. Nordic corridor operators deploy NMC for cross-regional express services linking Oslo, Gothenburg, and Copenhagen.
- NCA:Nickel-cobalt-aluminum cathodes serve premium tour bus segments demanding maximum range from minimal roof-pack footprint.
- LTO:Lithium titanate oxide anodes enable 10,000+ cycle life and sub-10-minute fast charging for high-frequency airport shuttle circuits.
LFP anchors the volume base while NMC gains share at the steepest rate as intercity electrification accelerates.
Application:
Cost tiers separate this category, with intercity platforms commanding 40-60% pack cost premiums over urban duty equivalents due to range and thermal management complexity.
- Public Transport:Urban fixed-route buses operate 200-300km daily cycles with depot overnight charging. Municipal procurement in Berlin, Paris, and Amsterdam concentrates demand for standardized 300-400kWh LFP packs with 8-year warranty terms.
- Intercity Buses:Long-distance coaches require 500-600kWh NMC configurations with active liquid cooling for sustained 100kW+ discharge rates. FlixBus and European coach operators are piloting these platforms on Amsterdam-London and Munich-Milan corridors.
- School Buses:Predictable twice-daily routes with extended midday dwell times suit smaller 150-200kWh packs with simple air-cooling architectures.
- Tour Buses:Premium sightseeing operators in Barcelona, Rome, and Vienna prioritize silent operation and panoramic roof designs over maximum range.
Public transport absorbs the dominant procurement volume, though intercity applications expand most quickly as coach electrification timelines compress.
Technology:
Customer type stratification drives adoption velocity, with municipal technical teams embracing Smart Battery Systems while private fleet managers prioritize fast charging infrastructure compatibility.
- Fast Charging:350kW+ pantograph and plug-in systems enable opportunity charging at route termini. Warsaw and Prague transit authorities are deploying overhead fast-charging infrastructure for 12-meter single-deck routes.
- Wireless Charging:Inductive pads at bus stops extend effective range without driver intervention. Swedish pilot programs in Gothenburg and Stockholm test dynamic charging along dedicated bus lanes.
- V2G:Vehicle-to-grid bidirectional discharge allows parked buses to provide grid stabilization services. Dutch grid operators Enexis and Liander are structuring revenue-sharing agreements with Rotterdam's municipal fleet.
- Smart Battery Systems:Integrated battery management with predictive analytics and charge optimization algorithms commands 15-20% price premiums. Vienna's Wiener Linien mandates these systems for all new procurements.
Fast charging dominates current installations while Smart Battery Systems climb the fastest as CSRD disclosure requirements elevate telemetry value.
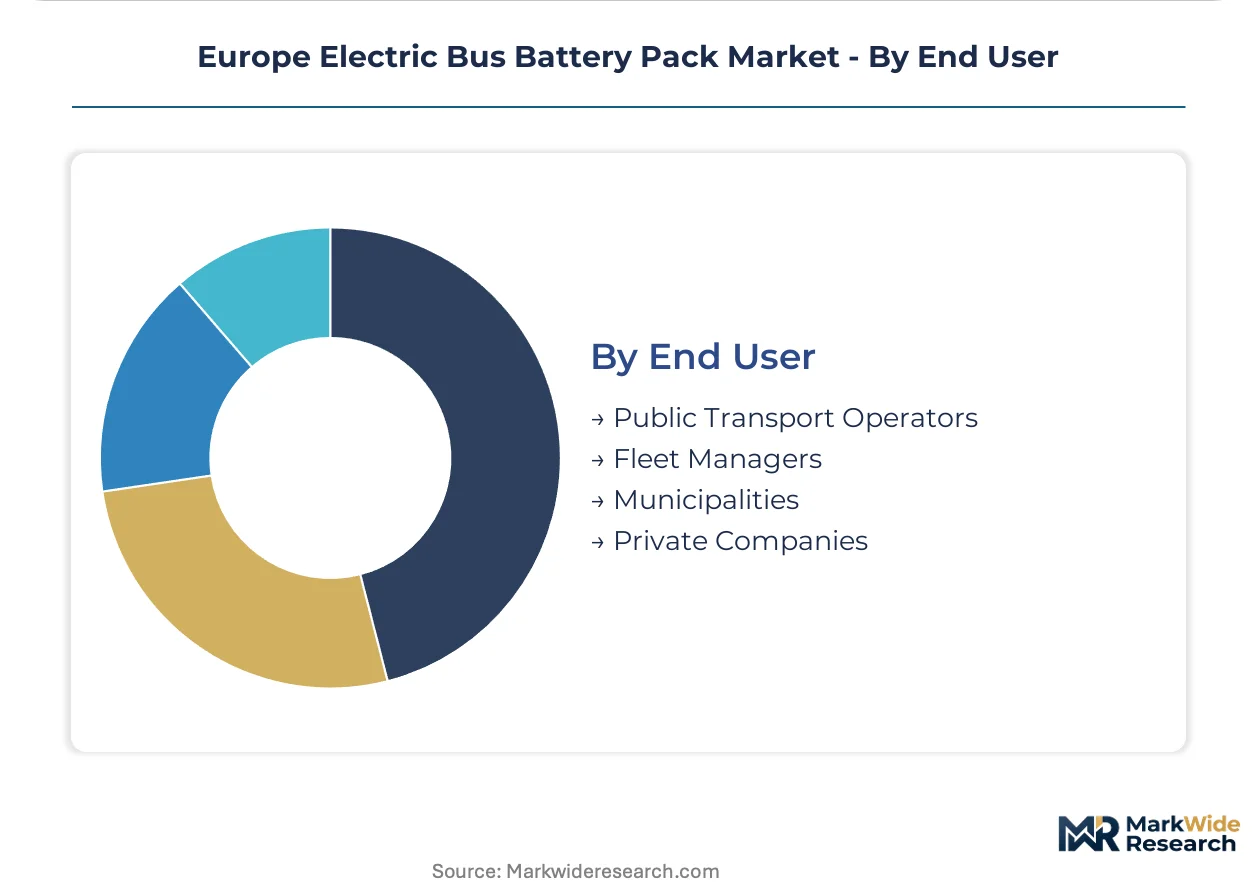
End User:
Supply concentration varies sharply across this category, with public transport operators consolidating procurement through framework agreements while private companies fragment across regional suppliers.
- Public Transport Operators:State-owned entities like RATP, BVG, and TFL aggregate demand through multi-year framework contracts. These buyers specify technical standards that cascade to subcontracted pack suppliers.
- Fleet Managers:Commercial operators like Transdev and Arriva manage mixed electrification portfolios across multiple municipal concessions. Their procurement emphasizes interoperability and residual value guarantees.
- Municipalities:City governments in secondary markets such as Porto, Ljubljana, and Tallinn are launching first-generation electrification programs with EU cohesion fund support.
- Private Companies:Corporate campus shuttles and airport operators represent dispersed demand with customized service requirements.
Public transport operators command the procurement volume base while municipalities gain influence fastest as EU funding democratizes electrification access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA homologation standards anchor Germany's procurement frameworks, while EU Green Deal carbon thresholds cascade across member state electrification timelines. The analysis window concentrates on five national markets where transit authority budgets and regulatory enforcement create distinct competitive environments.
Germany
Berlin's BVG and Munich's MVG aggregate demand through multi-year framework contracts specifying LFP chemistry for depot-charged fleets. The KBA enforces UN ECE R100 certification timelines that compress supplier qualification periods. Northvolt AB leverages its Swedish gigafactory output to secure long-term contracts with domestic OEMs in Baden-Württemberg and Lower Saxony.
France
Paris-based RATP commands standardized 300-400kWh pack specifications with 8-year warranty terms across Île-de-France electrification programs. ANSM chemical safety protocols intersect with REACH compliance burdens for cathode material traceability. The Auvergne-Rhône-Alpes cluster concentrates battery pack assembly operations serving Lyon and Grenoble municipal fleets.
Sweden
Gothenburg and Stockholm transit authorities unbundle battery procurement from complete bus purchases, creating direct contracting relationships with specialized pack suppliers. The Swedish Transport Agency mandates CSRD-aligned carbon footprint declarations in tender specifications. Västra Götaland County hosts pilot programs testing dynamic inductive charging along dedicated bus lanes.
Netherlands
Rotterdam's municipal fleet structures revenue-sharing agreements with Enexis and Liander for V2G grid stabilization services. The Dutch Human Environment and Transport Inspectorate enforces EU Battery Regulation delegated acts on recycled content quotas. Randstad metropolitan operators prioritize Smart Battery Systems integration for predictive diagnostics and charge optimization.
Poland
Warsaw transit authorities deploy 350kW+ pantograph fast-charging infrastructure for 12-meter single-deck routes with EU cohesion fund backing. The country's national automotive regulator compresses homologation timelines for industrial battery placements. Lesser Poland and Silesian Voivodeships present underpenetrated fleet modernization budgets as secondary markets electrify.
Europe Electric Bus Battery Pack Market Competitive Landscape
European cell specialists and Asian scale manufacturers split the market across divergent sourcing strategies. Pack assemblers face procurement bifurcation between domestic supply security premiums and cost-optimized LFP imports. Three archetypes occupy distinct positions: gigafactory-integrated cell producers, modular pack architects, and chemistry-agnostic system integrators. Capacity expansion and strategic partnerships dominate competitive moves as suppliers position for EU Battery Regulation compliance deadlines.
Within the gigafactory-integrated tier, Northvolt AB exemplifies European supply security positioning, while Contemporary Amperex Technology Co. Ltd. anchors cost-competitive LFP scale. Akasol AG occupies a specialist position in modular pack architectures that integrate across multiple OEM platforms. These three entities represent the structural tension between regional sourcing mandates and global manufacturing efficiency that defines procurement negotiations.
| Leading Market Players |
|---|
| Northvolt AB |
| Panasonic Holdings Corporation |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| Akasol AG |
| SK On |
| BYD Company Ltd. |
| Microvast Holdings Inc |
| BMZ Holding GmbH |
| LG Energy Solution Ltd. |
| Others |
Pricing and Supply Chain Analysis
REACH compliance burdens and delegated acts under the EU Battery Regulation compress supplier margins while widening the spread between certified and uncertified pack offerings. This regulatory chokepoint forces European pack assemblers to absorb due diligence costs or pass them downstream, reshaping procurement relationships with municipal transit authorities.
Pricing Analysis
The customization-premium spread separates configured-to-order NMC intercity packs from standardized LFP municipal configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from Asian cell manufacturers' LFP production scale advantages. Municipal operators in Germany and France exhibit highest price sensitivity, while Nordic corridor authorities prioritize CSRD-aligned carbon footprint declarations over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests on CATL's European module assembly facilities, Northvolt AB's Swedish gigafactory output, and SK On's Hungarian production base. Cathode active material supply draws from Chinese LFP precursor refiners and South Korean NMC cathode producers. Single-source vulnerability concentrates in lithium carbonate and cobalt sulfate feedstocks. Distribution runs through OEM-integrated pack assembly partnerships and direct municipal procurement channels in Sweden and Norway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Electric Bus Battery Pack Market participants should treat predictive maintenance subscriptions and battery health monitoring services as the primary revenue expansion layer, with telemetry-enabled fleet management contracts outpacing hardware shipment growth across municipal procurement cycles.
For Market Incumbents: Pre-empt regulatory compliance fragmentation by securing audited recycling partnerships before EU Battery Regulation delegated acts enforce minimum recycled content quotas. Invest in thermal engineering talent acquisition to address liquid cooling system design scarcity. Deepen backward integration into cell supply through offtake agreements with Northvolt AB or CATL to defend against input cost volatility from Asian LFP production concentration. For New Entrants and Emerging Players: Eastern European municipalities in Poland, Czechia, and Romania represent the most penetrable entry point, with EU cohesion fund backing creating first-mover procurement windows. Modular pack architectures that integrate across multiple OEM platforms enable faster qualification timelines than custom engineering approaches. Target direct contracting relationships with unbundled battery procurement programs in Swedish and Norwegian transit authorities. For Investors and Strategic Acquirers: The market sits at a compliance-driven consolidation phase that favors chemistry-agnostic system integrators with established CSRD documentation capabilities. Long-term viability hinges on carbon footprint verification infrastructure and lifecycle assessment partnerships. Monitor Nordic operator tender specifications as the signal for EU-wide recycled content mandate adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Partnership | Establishes audited material recovery pathways before EU Battery Regulation delegated acts enforce quotas. |
| Thermal Engineering Acquisition | Addresses liquid cooling system design scarcity compressing pack manufacturer qualification timelines. |
| Smart Battery Systems Integration | Enables premium pricing for predictive diagnostics as Vienna's Wiener Linien mandates telemetry mandates. |
| Eastern European Market Entry | Captures EU cohesion fund electrification budgets in Poland, Czechia, and Romania before incumbent saturation. |
| CSRD Disclosure Alignment | Creates first-mover advantage for pack suppliers with verified carbon footprint declarations in Nordic tenders. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, transit authority procurement databases, and cell manufacturer capacity announcements. The research team conducted structured interviews with battery pack procurement managers at municipal operators, thermal engineering directors at European OEMs, and regulatory affairs leads specializing in REACH and EU Battery Regulation compliance. Secondary validation drew from KBA homologation records, ECHA chemical safety protocols, and UN ECE R100 certification timelines. Bottom-up demand modeling triangulated against top-down market sizing across chemistry types and duty cycle applications.
Forecast inputs incorporate cell chemistry adoption curves, municipal fleet electrification budget allocations, and delegated act implementation timelines. Segmentation dimensions span chemistry type, application duty cycle, cooling architecture, and end-user procurement structure. CAGRs were derived from installed base turnover analysis and replacement cycle compression under EU Green Deal mandates. Battery management system penetration rates and V2G infrastructure deployment schedules informed technology segment trajectories.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, euro-yuan exchange rates, or EU cohesion fund disbursement schedules would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement consistency and cell import tariff stability. Quarterly review of Nordic operator tender specifications and delegated act publication timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
India EV Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
China Electric Vehicle Battery Materials Market