
 India Insulin Infusion Pump Market | 2026-2036
India Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
India Insulin Infusion Pump Market Insights
Multi-source procurement of insulin infusion pump components is hardening among Indian distributors as supply chain resilience takes priority over cost minimization. Medtronic leverages its established service infrastructure across tier-1 cities to sustain recurring revenue from consumables and patient support programs. Ypsomed anchors its position through localized manufacturing partnerships that reduce import dependency for disposable infusion sets.
An insulin infusion pump is a programmable electromechanical device that delivers continuous subcutaneous insulin through a disposable reservoir and cannula system, typically achieving basal rates of 0.025 to 35 units per hour with bolus dose increments of 0.1 to 25 units. Its primary purpose is to mimic physiological pancreatic insulin secretion for intensive diabetes management in type 1 and insulin-dependent type 2 patients. Smart pumps with integrated continuous glucose monitoring algorithms command premium positioning due to closed-loop automation capabilities, while wearable pump formats are gaining fastest traction among pediatric and adolescent user segments seeking discretion and lifestyle flexibility. Traditional pumps retain volume dominance in hospital procurement channels where cost sensitivity and staff familiarity override feature sophistication.
CDSCO's Medical Device Rules mandate registration and quality testing for all imported and domestically manufactured insulin pumps, creating compliance barriers that favor established players with regulatory dossier experience. The Bureau of Indian Standards specifies electrical safety and electromagnetic compatibility requirements that shape product design decisions for India-bound devices. Stakeholders must monitor how the government's PLI scheme for medical electronics alters the cost calculus between imported finished pumps and locally assembled alternatives.
Market Dynamics
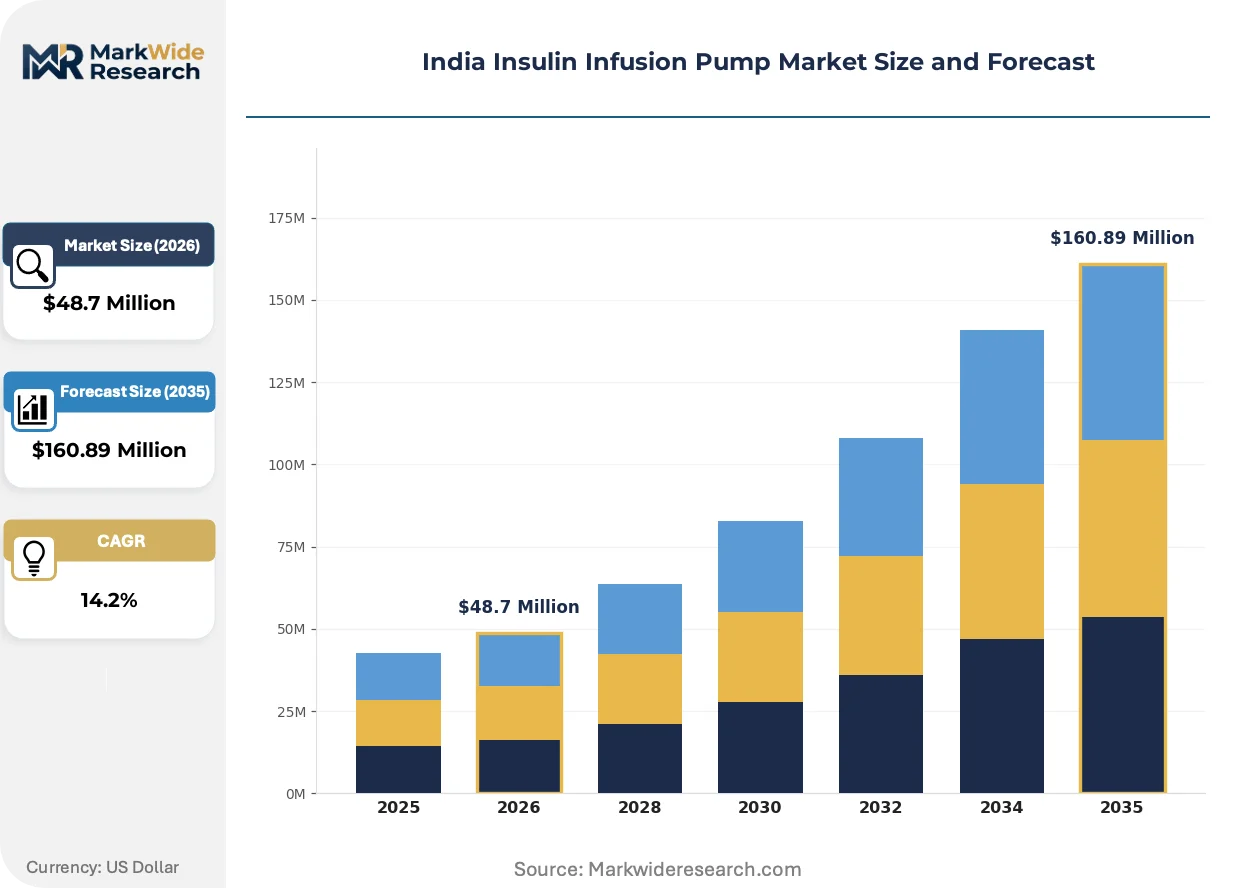
CDSCO's tightened Medical Device Rules are compressing market entry timelines for imported insulin pumps while simultaneously accelerating local assembly investments through the PLI scheme for medical electronics.
Growth Catalysts
- Type 1 diabetes prevalence expansion:Rising pediatric and adolescent diagnoses in Maharashtra, Karnataka, and Tamil Nadu are expanding the addressable patient base for intensive insulin therapy devices.
- CGM-pump integration protocols:Closed-loop algorithm advancement is electrifying demand for smart pump systems capable of automated basal rate adjustments based on real-time glucose data.
- Homecare reimbursement pathways:Expanded insurance coverage for outpatient diabetes management is redirecting procurement volumes from hospital inpatient channels toward residential settings.
Market Restraints
- Import dependency for precision motors:Domestic manufacturers lack captive supply of miniature electromechanical actuators, exposing cost structures to currency volatility and shipping disruptions.
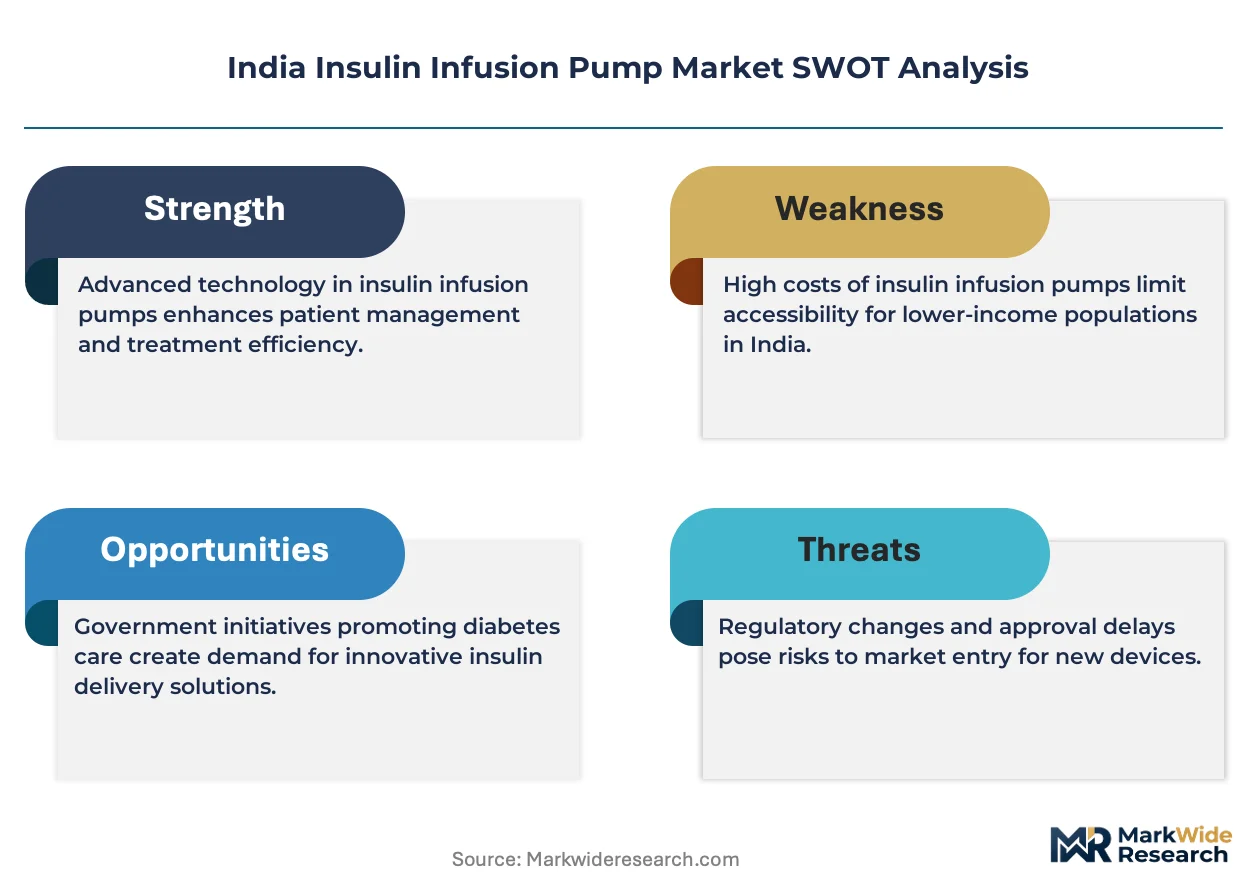
- CDSCO registration dossier complexity:Extended clinical evidence requirements for Class C medical devices create 18-24 month approval timelines that freeze product refresh cycles.
- Continuous glucose monitor substitution:Standalone CGM systems with predictive alerts are capturing patients who might otherwise escalate to full pump therapy.
Strategic Opportunities
- Tier-2 city diabetes center expansion:Hyderabad, Pune, and Ahmedabad present underpenetrated demand for pump therapy services beyond the Mumbai-Bangalore-Chennai triangle.
- Disposable infusion set localization:BIS-certified domestic manufacturing partnerships can displace imported consumables and capture recurring revenue streams.
- PLI scheme for medical electronics:Production-linked incentives are altering the cost calculus between fully imported pumps and locally assembled alternatives with imported subassemblies.
Industry Challenges
- Certified diabetes educator scarcity:Patient onboarding and pump training requires specialized clinical personnel concentrated in tier-1 metro hospitals, constraining homecare rollout velocity.
- Legacy EMR integration friction:Pump data interoperability with hospital information systems demands proprietary middleware development that fragments vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Insulin Infusion Pump Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $160.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pumps, Wearable Pumps, Traditional Pumps, Smart Pumps Technology: Micro-Dosing, Continuous Glucose Monitoring, Wireless Connectivity, Automated Dosing End User: Homecare, Hospitals, Clinics, Specialty Diabetes Centers Distribution Channel: Direct Sales, Online Retail, Pharmacy Chains, Specialty Distributors |
| Companies Covered | Medtronic, Ascensia Diabetes Care, Insulet Corporation, Tandem Diabetes Care, Ypsomed, Novo Nordisk, Sanofi, Eli Lilly, Becton Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Insulin Infusion Pump Market Trends and Innovations
Electromechanical miniaturization and algorithmic glucose prediction are converging to reshape device form factors and patient autonomy expectations across the Indian diabetes care landscape.
Patch pump architectures are electrifying competitive positioning by eliminating external tubing and enabling discreet wearability. Adolescent and young adult patient segments in Bangalore and Mumbai are adopting these wearable formats at accelerated rates. This technology compression is forcing traditional tethered pump manufacturers to accelerate wireless connectivity roadmaps or cede lifestyle-sensitive demographics.
CDSCO's Medical Device Rules amendment is mandating post-market surveillance reporting for all Class C diabetes devices. This regulatory tightening is elevating compliance costs for import-dependent distributors while creating structural advantage for manufacturers with established pharmacovigilance infrastructure. Maharashtra-based specialty diabetes centers are prioritizing procurement from vendors with demonstrated adverse event tracking capabilities.
Direct-to-patient consumable replenishment is disrupting traditional hospital pharmacy procurement channels. Homecare-focused patients in Chennai and Hyderabad are subscribing to automated infusion set and reservoir delivery services that bypass institutional purchasing. This channel disintermediation is most visible among insulin-dependent professionals seeking minimal clinical visit disruption.
India Insulin Infusion Pump Market Segmentation
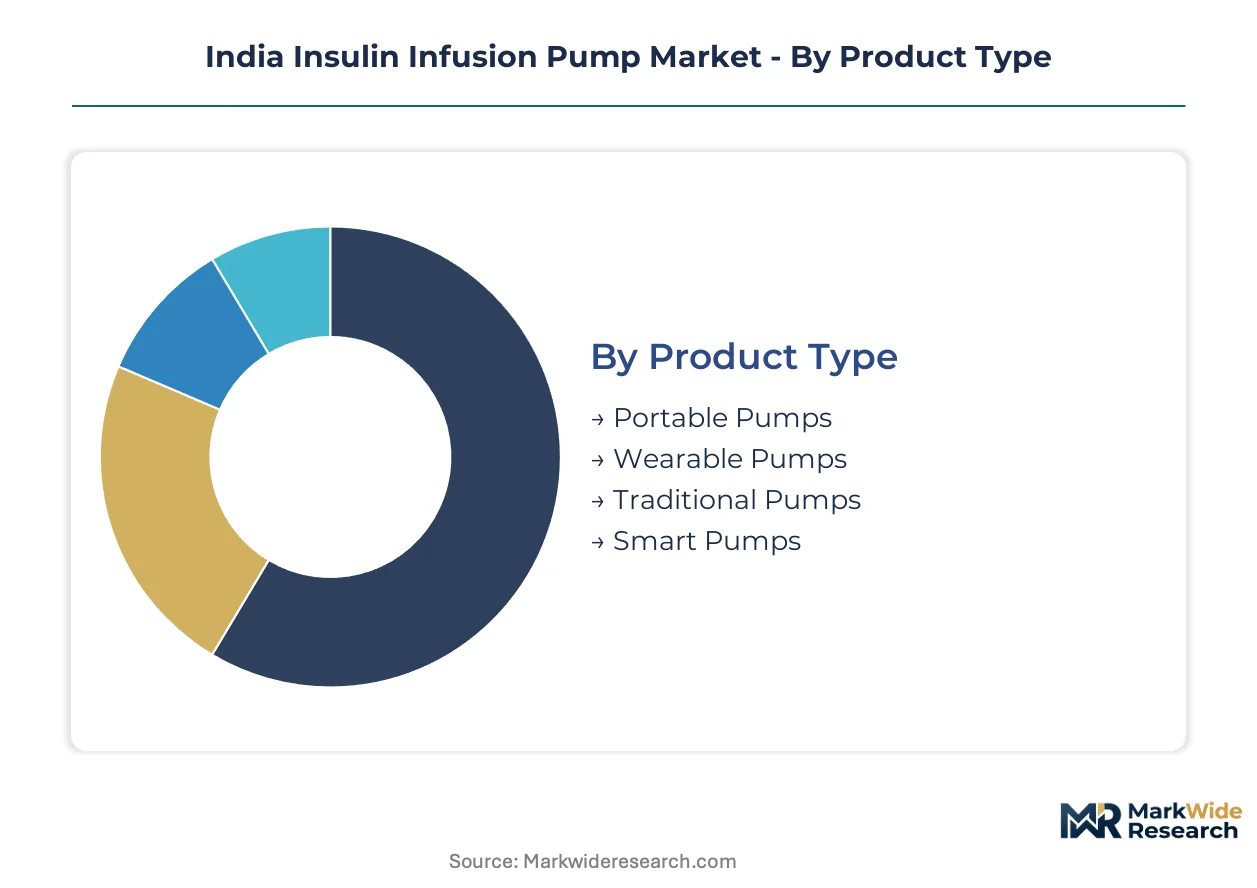
Segmentation in India's insulin infusion pump market reveals distinct procurement patterns across device sophistication levels and care delivery settings. Each category exposes different margin structures and regulatory exposure for manufacturers and distributors operating under CDSCO's Class C device framework.
Product Type:
Customization versus standardization tensions dominate this category, with programmable feature sets commanding premium positioning against basic hospital-grade alternatives.
- Portable Pumps:Compact electromechanical units with detachable reservoirs and programmable basal profiles. Demand concentrates in Mumbai and Bangalore among traveling professionals who require therapy continuity during domestic mobility. Battery optimization and altitude calibration features differentiate mid-tier offerings.
- Wearable Pumps:Patch-form devices with fully integrated subcutaneous delivery eliminating external tubing. Adolescent patients in Chennai and Hyderabad are adopting these formats fastest, driven by discretion requirements in educational and social settings. Form factor miniaturization remains the primary engineering constraint.
- Traditional Pumps:Tethered systems with external reservoirs and infusion sets. Hospital procurement channels in Maharashtra favor these devices for staff familiarity and lower capital outlay.
- Smart Pumps:Closed-loop systems with CGM integration and predictive algorithmic dosing. Specialty diabetes centers in Karnataka prioritize these for intensive glycemic management protocols.
Most installed capacity flows through Traditional Pumps. Expansion is steepest in Wearable Pumps.
Technology:
Cost tier stratification separates patented algorithmic systems from commodity electromechanical components in this category.
- Micro-Dosing:Precision motor control achieving 0.025 unit basal increments through miniature actuator engineering. Pediatric endocrinology practices in Tamil Nadu specify these capabilities for insulin-sensitive patients requiring granular titration.
- Continuous Glucose Monitoring:Real-time interstitial glucose sensing with predictive trend arrows and alert thresholds. Homecare patients in Pune and Ahmedabad are integrating these systems fastest as standalone CGM availability expands.
- Wireless Connectivity:Bluetooth and proprietary radio protocols enabling smartphone app control and cloud data transmission. Data sovereignty concerns under India's digital health framework are delaying full feature deployment.
- Automated Dosing:Algorithm-driven basal rate adjustment without manual intervention. CDSCO's adverse event reporting requirements for autonomous dosing functions are extending approval timelines for these systems.
Revenue concentration sits with Micro-Dosing capabilities. Regulatory velocity favors Wireless Connectivity integration.
End User:
Application urgency creates divergent procurement cycles between acute institutional settings and chronic outpatient management.
- Homecare:Residential settings where patients or caregivers manage device operation independently. Insurance reimbursement expansion in Maharashtra and Karnataka is redirecting volume from inpatient channels toward domiciliary care.
- Hospitals:Acute care institutions with 24-hour clinical supervision and centralized pharmacy control. Staff training standardization and EMR integration requirements dominate purchasing criteria.
- Clinics:Outpatient facilities with periodic patient contact and limited device troubleshooting capacity. Cost sensitivity and space constraints favor simpler tethered systems.
- Specialty Diabetes Centers:Dedicated endocrinology institutions with certified educators and pump training infrastructure. These facilities in Mumbai, Bangalore, and Chennai generate highest per-patient consumable attachment rates.
Patient volume concentrates in Specialty Diabetes Centers. Channel shift momentum favors Homecare.
Distribution Channel:
Margin structure and inventory risk allocation distinguish direct manufacturer engagement from intermediated retail pathways.
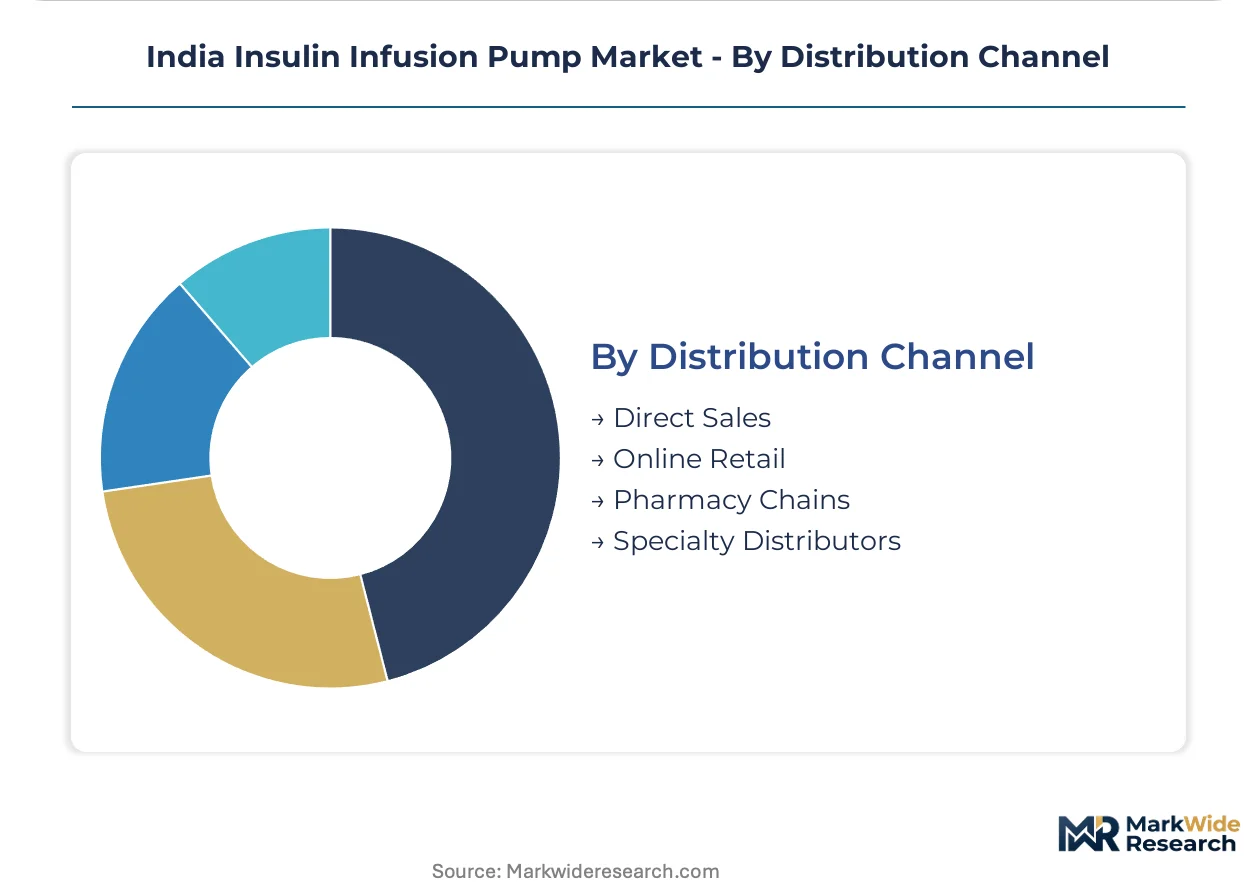
- Direct Sales:Manufacturer-to-institution contracts with bundled training and service agreements. Large hospital networks in Delhi NCR and Mumbai negotiate multi-year consumable supply commitments.
- Online Retail:E-commerce platforms with patient-direct fulfillment and subscription replenishment models. Urban professionals in Hyderabad and Pune are adopting automated infusion set delivery services.
- Pharmacy Chains:Multi-outlet retailers with limited clinical consultation capacity. These channels primarily handle consumable resupply rather than initial device procurement.
- Specialty Distributors:Regional medical device wholesalers with field technical support and educator networks. CDSCO import license holding requirements favor established distributors with regulatory compliance infrastructure.
Transaction volume flows through Specialty Distributors. Digital penetration is climbing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Mumbai-Pune corridor anchors India's insulin infusion pump demand through concentrated specialty diabetes infrastructure and private insurance penetration. Karnataka and Tamil Nadu follow as secondary demand clusters, while Telangana and Gujarat emerge as expansion frontiers.
Maharashtra
Mumbai's Jaslok Hospital and Lilavati Hospital drive premium pump procurement for intensive glycemic protocols. CDSCO's Class C device registration requirements filter import channels through licensed distributors with pharmacovigilance infrastructure. Pune's expanding endocrinology clinics are adopting wearable pump formats for adolescent patient segments.
Karnataka
Bangalore's Manipal Hospital and Apollo Sugar clusters generate concentrated demand for smart pump systems with CGM integration. The state's medical electronics manufacturing incentives under PLI schemes are attracting assembly investments for disposable infusion sets. Mysore and Hubli diabetes centers are extending pump therapy access beyond the capital.
Tamil Nadu
Chennai's Dr. Mohan's Diabetes Specialities Centre and Madras Medical College anchor pediatric pump adoption for type 1 management. BIS electrical safety certification requirements shape product specifications for India-bound devices. Coimbatore's private hospital networks are expanding homecare reimbursement pathways for outpatient insulin delivery.
Telangana
Hyderabad's AIG Hospitals and Yashoda Hospitals are building certified diabetes educator capacity to support pump onboarding velocity. The state's pharmaceutical manufacturing heritage is attracting consumable localization partnerships for infusion set production. Secunderabad's diagnostic chains are integrating pump therapy into comprehensive diabetes management bundles.
Gujarat
Ahmedabad's Sterling Hospital and Apollo Hospitals drive demand for cost-optimized traditional pump systems in hospital procurement channels. DGFT import licensing frameworks govern device entry for distributors serving western India. Surat's expanding middle-class patient base is adopting subscription-based consumable replenishment models.
India Insulin Infusion Pump Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wearable form factors and closed-loop automation. The market structures around three tiers: multinational device manufacturers with service infrastructure, pharmaceutical companies with diabetes portfolios extending into delivery systems, and regional distributors with CDSCO import licenses and educator networks. Competitive moves concentrate on local manufacturing partnerships under PLI schemes and direct-to-patient consumable subscription models that bypass hospital pharmacy channels.
Among multinational device specialists, Medtronic and Insulet Corporation exemplify the service-anchored archetype with recurring revenue from consumables and patient support programs. Ypsomed represents the localization-focused tier through domestic manufacturing partnerships that reduce import dependency for disposable infusion sets. Tandem Diabetes Care occupies the algorithmic differentiation position with closed-loop system capabilities. These three anchors illustrate how regulatory compliance infrastructure, manufacturing geography, and technology sophistication stratify competitive positioning under CDSCO's tightened Medical Device Rules.
| Leading Market Players |
|---|
| Medtronic |
| Ascensia Diabetes Care |
| Insulet Corporation |
| Tandem Diabetes Care |
| Ypsomed |
| Novo Nordisk |
| Sanofi |
| Eli Lilly |
| Becton Dickinson and Company |
| Others |
Pricing and Supply Chain Analysis
BIS electrical safety certification gates qualified supply for India-bound insulin pumps while simultaneously filtering premium-tier pricing access to vendors with demonstrated compliance infrastructure. CDSCO's Class C device registration requirements impose fixed compliance costs that stratify pricing power between established importers and emerging local assemblers seeking PLI scheme benefits.
Pricing Analysis
Input-cost pass-through from miniature electromechanical actuators and precision motors governs landed cost structures for imported pump systems. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop smart pumps with CGM integration from basic tethered systems and wearable patch formats. Pricing pressure stems from PLI scheme incentives accelerating local assembly investments that compress import-dependent distributor margins. Hospital procurement committees in Maharashtra exhibit highest price sensitivity due to bulk volume negotiations, while specialty diabetes centers in Bangalore prioritize algorithmic sophistication over capital outlay.
Supply Chain Analysis
Warehouse-distribution layer concentration in Mumbai and Delhi NCR hubs governs downstream fulfillment velocity for consumable replenishment. Manufacturing gravity centers on Switzerland, Germany, and China for precision motor assemblies and electromechanical subsystems. Raw material dependencies span medical-grade plastics for reservoir housings, lithium-ion cells for power management, and biocompatible adhesives for patch pump adhesion. Single-source vulnerability for miniature actuator supply exposes cost structures to currency volatility and shipping disruptions. Distribution runs through specialty medical device wholesalers with CDSCO import licenses and field technical support networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India insulin infusion pump market functions as a stable compounder anchored by irreversible epidemiological expansion in type 1 diabetes prevalence across Maharashtra, Karnataka, and Tamil Nadu.
For Market Incumbents: Hedge against PLI scheme-induced margin compression by accelerating localized manufacturing partnerships for disposable infusion sets before competitor assembly investments mature. Deepen backward integration into precision motor supply through Swiss and German supplier alliances to insulate cost structures from currency volatility. Control certified diabetes educator networks in tier-2 cities to preempt channel disintermediation from direct-to-patient subscription models. For New Entrants and Emerging Players: Closed-loop algorithmic differentiation offers the most penetrable wedge for specialty diabetes centers in Hyderabad and Pune seeking automated basal rate adjustment capabilities. Target adolescent patient segments in Chennai and Ahmedabad with wearable patch pump formats that eliminate external tubing and enable lifestyle discretion. Pursue online retail subscription models for automated infusion set replenishment that bypass established hospital pharmacy procurement channels. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with CDSCO import licenses and educator networks because regulatory compliance infrastructure creates natural scarcity value and captive patient onboarding relationships. Long-term viability hinges on consumable recurring revenue attachment rates rather than device hardware margins. Watch PLI scheme beneficiary announcements as inflection indicators for manufacturing cost competitiveness shifts between imported and locally assembled alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Registration Pathway | Accelerated approval timelines favor established dossier experience over novel entrant submissions. |
| PLI Scheme Manufacturing Partnership | Production-linked incentives alter cost calculus between imported pumps and locally assembled alternatives. |
| Specialty Diabetes Center Alliance | Mumbai, Bangalore, and Chennai clusters generate highest per-patient consumable attachment rates. |
| Direct-to-Patient Subscription Model | Automated infusion set delivery services disintermediate traditional hospital pharmacy procurement channels. |
| Certified Educator Network Expansion | Patient onboarding velocity in tier-2 cities depends on specialized clinical personnel concentration. |
Research Methodology
Multiple input streams — primary interviews with endocrinologists and hospital procurement managers, secondary validation through CDSCO registration databases and GPO contracts, and trade flow analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed certified diabetes educators, biomedical engineers at specialty centers, medical device distributors with import licenses, and PLI scheme administrators. Secondary sources included Bureau of Indian Standards certification records, hospital procurement databases, and medical electronics import manifests.
Data-stream reconciliation across device type segmentation, technology tier stratification, and end-user channel analysis informed the analytical framework over the projection horizon. Segmentation dimensions encompassed pump form factor, algorithmic sophistication level, care delivery setting, and geographic adoption cluster. CAGRs were derived from patient population epidemiology, insurance reimbursement trajectory, and technology substitution elasticities calibrated against historical analog markets.
The model holds under stable regulatory enforcement of CDSCO Medical Device Rules and sustained PLI scheme incentive structures; deviation in adverse event reporting stringency or import licensing frameworks would shift competitive positioning between local and foreign manufacturers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
North America Insulin Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market