
 Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market | 2026-2036
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market Foresight
Subscription-based patient monitoring and companion diagnostic software is repositioning how LGLL therapeutics are bundled and reimbursed. Bristol Myers Squibb leverages its immuno-oncology infrastructure to sustain clinical trial recruitment across rare lymphoproliferative indications. Hoffmann-La Roche anchors its position through integrated diagnostic-therapeutic platforms that streamline biomarker-driven treatment selection. AbbVie differentiates via deep specialization in T-cell modulation pathways relevant to LGLL pathogenesis.
Large granular lymphocytic leukemia therapeutics target clonal expansions of CD3+CD8+ or CD3-CD16+ lymphocytes with cytotoxic or natural killer cell phenotypes, primarily addressing autoimmune cytopenias and splenomegaly through immunosuppressive or cytotoxic intervention. Monoclonal antibodies retain the largest revenue share among product types due to established rituximab protocols and emerging CD20-directed combinations, while CAR-T therapies represent the fastest-expanding segment as academic centers refine autologous cell manufacturing for relactory cases. Small molecules command concentrated margin pools where oral JAK or STAT3 inhibitors reduce infusion burden.
The FDA orphan drug program and EMA's PRIME designation collectively shape development economics by compressing regulatory review timelines and extending market exclusivity for LGLL indications. HIPAA-compliant real-world evidence frameworks in the United States and GDPR-aligned clinical data governance in Europe determine how post-market safety databases inform label expansion. Stakeholders must monitor how CMS coverage decisions for cell and gene therapies reshape site-of-care requirements and patient access infrastructure.
Market Dynamics
Orphan drug designation pathways from the FDA and EMA are compressing clinical trial timelines while specialized hematology clinics consolidate treatment protocols around biomarker-driven patient stratification.
Growth Catalysts
- Orphan Drug Acceleration:The FDA's orphan drug designation grants seven-year market exclusivity and tax credits for clinical trials, incentivizing biopharma investment in LGLL indications. EMA's PRIME designation mirrors these benefits across European markets.
- Companion Diagnostic Integration:Flow cytometry panels detecting STAT3 mutations are automating patient selection for JAK inhibitor protocols, reducing time-to-treatment decisions in academic medical centers.
- Hematology Clinic Consolidation:Specialized cancer centers in the United States are centralizing LGLL care, creating concentrated demand pools that justify dedicated clinical trial infrastructure and specialized pharmacy services.
Market Restraints
- Autologous Cell Manufacturing Costs:CAR-T production requires dedicated cleanroom facilities and vector supply contracts, with per-patient manufacturing expenses constraining site expansion beyond major academic centers.
- Diagnostic Fragmentation:Lack of standardized CD57 and CD16 flow cytometry protocols across community hospitals delays diagnosis and restricts addressable patient pools to tertiary referral networks.
- Reimbursement Uncertainty:CMS coverage determinations for cell and gene therapies remain inconsistent across Medicare Administrative Contractors, creating access disparities between geographic regions.
Strategic Opportunities
- Real-World Evidence Frameworks:HIPAA-compliant patient registries in the United States enable post-market surveillance that supports label expansion for combination immunomodulatory protocols.
- Allogeneic CAR-T Platforms:Off-the-shelf cell therapies from healthy donor lymphocytes promise to eliminate patient-specific manufacturing delays and reduce treatment costs.
- Subscription Monitoring Models:Software platforms tracking minimal residual disease through periodic flow cytometry are creating recurring revenue streams that complement drug pricing structures.
Industry Challenges
- Cell Therapy Talent Scarcity:Vector production and cryopreservation specialists command premium compensation, constraining manufacturing scale-up at emerging contract development organizations.
- Biomarker Standardization Delays:Discordance between STAT3 mutation assays from different diagnostic vendors complicates clinical trial enrollment and retrospective data pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market |
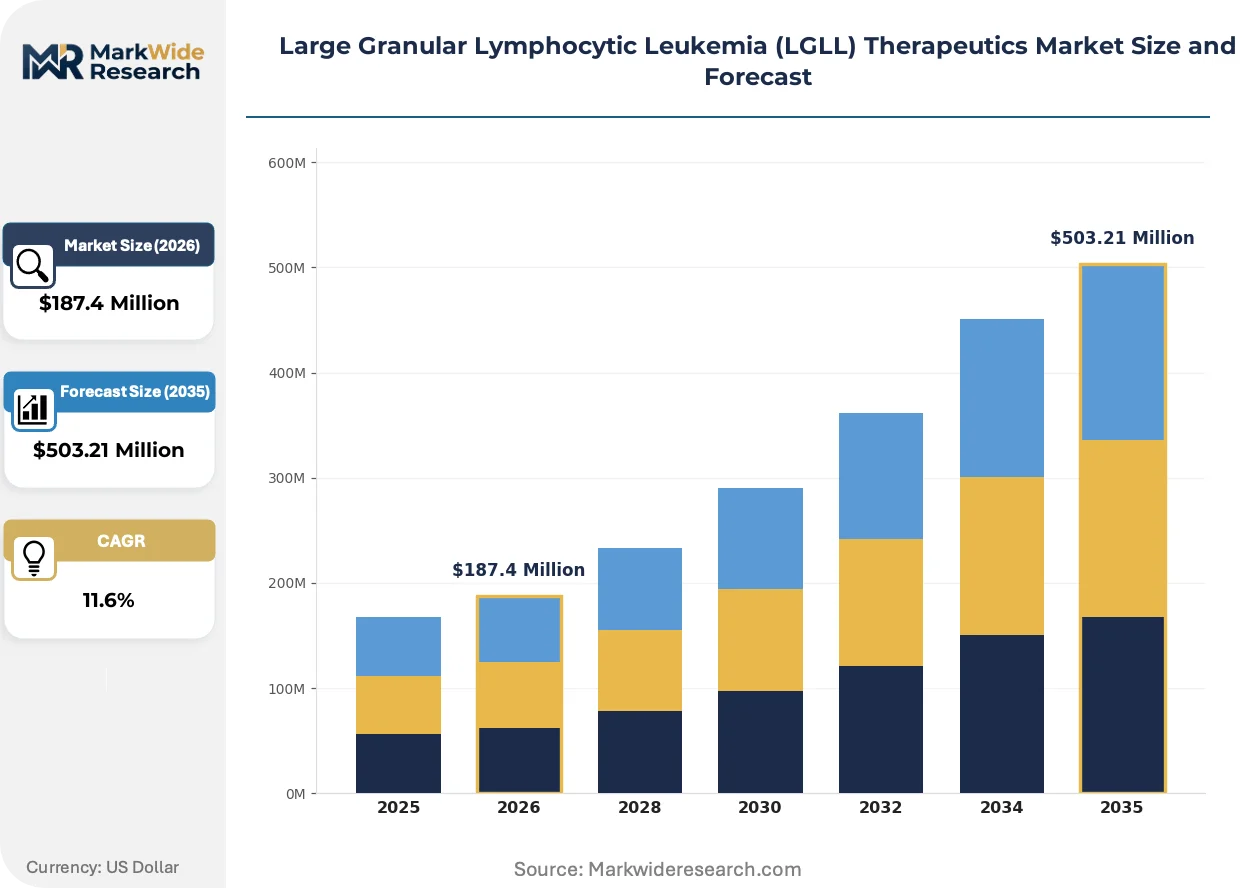
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Immune Checkpoint Inhibitors, CAR-T Therapies Application: Oncology, Hematology, Clinical Trials, Palliative Care End User: Hospitals, Research Institutions, Specialty Clinics, Home Care Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Bristol Myers Squibb and Company, GSK Plc, Sanofi SA, Emcure Pharma, Dren Bio, Inc., Abcuro, Hoffmann-La Roche AG, AbbVie Inc., Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market Shifts & Advancements
Next-generation sequencing panels and artificial intelligence-assisted flow cytometry are converging to compress diagnostic timelines while reshaping how treatment protocols are selected and monitored.
Automated minimal residual disease tracking platforms are automating longitudinal patient surveillance, with academic medical centers adopting cloud-based flow cytometry interpretation tools that reduce pathologist review time. These systems enable earlier detection of clonal expansion recurrence, compressing the interval between laboratory result and treatment modification decisions.
The FDA's breakthrough therapy designation pathway is streamrolling submission requirements for combination protocols, compressing the regulatory review cycle from 12 months to 6 months for therapies addressing unmet needs in refractory cytopenias. Hematology clinics are restructuring clinical trial operations to align with these compressed timelines, prioritizing sites with dedicated regulatory affairs staff.
Site-of-care economics are restructuring procurement patterns for infused therapies, with hospital outpatient departments displacing physician office administration for high-complexity immunomodulatory protocols. United States cancer centers are consolidating infusion capacity into specialized lymphoproliferative disorder units, capturing technical fees and reducing per-dose logistics overhead through centralized pharmacy operations.
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market Segmentation
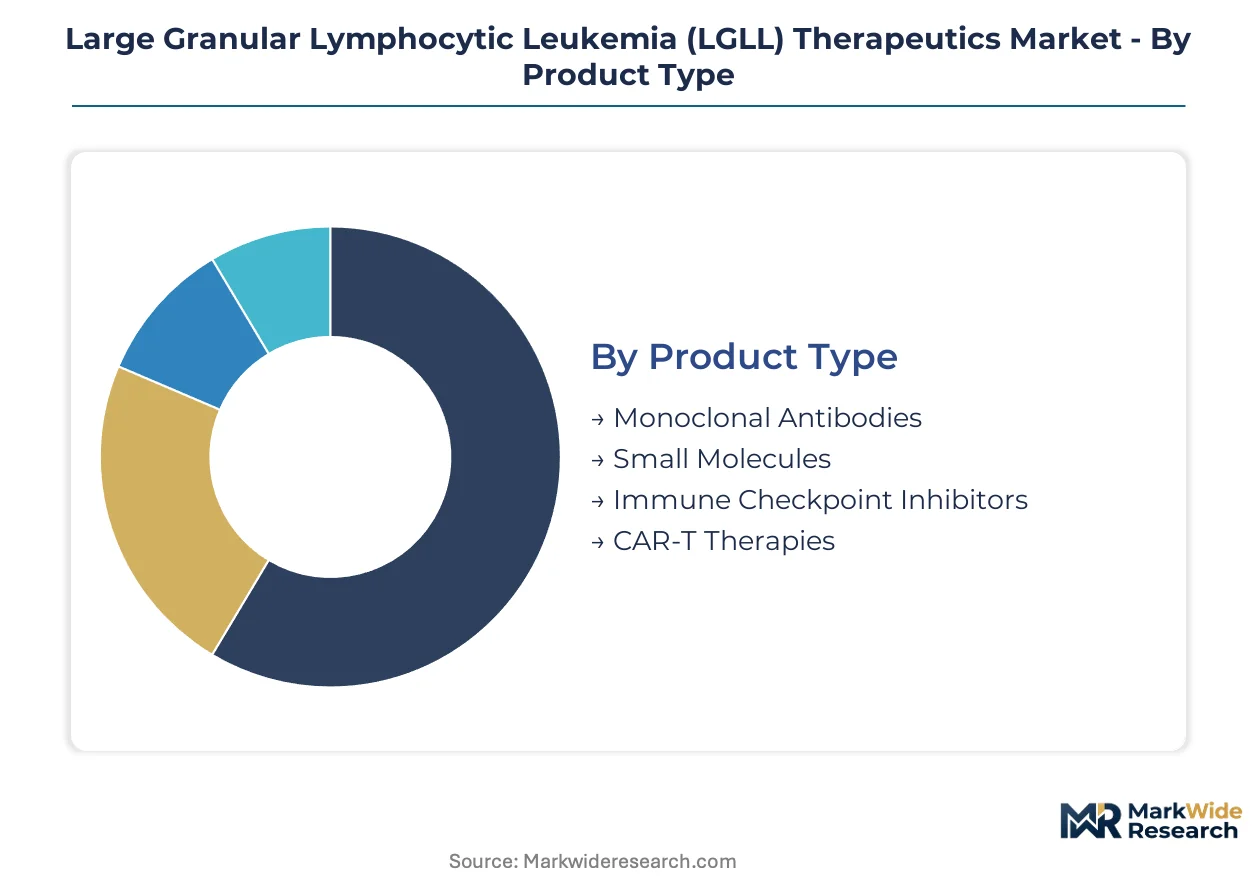
LGLL therapeutics segmentation reflects divergent manufacturing economics and site-of-care requirements across modality classes. Product type distinctions determine cleanroom investment thresholds, while administration route shapes reimbursement coding and patient access infrastructure.
Product Type:
Supply concentration in monoclonal antibody manufacturing creates scale advantages that cell therapy platforms have yet to replicate.
- Monoclonal Antibodies:Rituximab-based protocols dominate current treatment algorithms through established CD20-directed mechanisms. United States hematology clinics standardize around these infusions due to predictable supply chains and familiar reimbursement pathways.
- Small Molecules:Oral JAK and STAT3 inhibitors reduce site-of-care burden through ambulatory dispensing. European academic centers prioritize these for patient populations distant from infusion centers, though biomarker testing requirements fragment prescriber adoption.
- Immune Checkpoint Inhibitors:PD-1 and CTLA-4 blockers expand the addressable patient pool in combination protocols.
- CAR-T Therapies:Autologous manufacturing constraints limit production to specialized academic centers with dedicated vector supply contracts.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: CAR-T Therapies.
Application:
Clinical trial density concentrates in oncology and hematology departments with dedicated lymphoproliferative disorder infrastructure.
- Oncology:Academic medical centers anchor protocol development through specialized leukemia units with integrated flow cytometry laboratories. United States NCI-designated cancer centers capture the majority of investigator-initiated studies.
- Hematology:Dedicated hematology clinics consolidate LGLL diagnosis and treatment selection through STAT3 mutation screening programs. German university hospitals lead European adoption of biomarker-driven stratification.
- Clinical Trials:FDA orphan drug incentives compress enrollment timelines at sites with dedicated regulatory affairs staff.
- Palliative Care:Symptom management protocols address cytopenia-related quality of life in refractory populations.
Oncology commands current revenue concentration. Hematology clinics are gaining the fastest.
End User:
Site-of-care economics favor hospital outpatient departments over physician offices for complex immunomodulatory administration.
- Hospitals:Hospital outpatient departments capture technical fees and centralized pharmacy operations for infused therapies. United States cancer centers consolidate lymphoproliferative disorder units to reduce per-dose logistics overhead.
- Specialty Clinics:Dedicated hematology clinics in France and Germany automate flow cytometry interpretation through cloud-based platforms.
- Research Institutions:Academic medical centers manufacture CAR-T products through institutional good manufacturing practice facilities.
- Home Care:Oral small molecule dispensing expands ambulatory access for stable patients with reliable monitoring infrastructure.
Hospitals retain the dominant share. Specialty clinics are climbing the fastest.
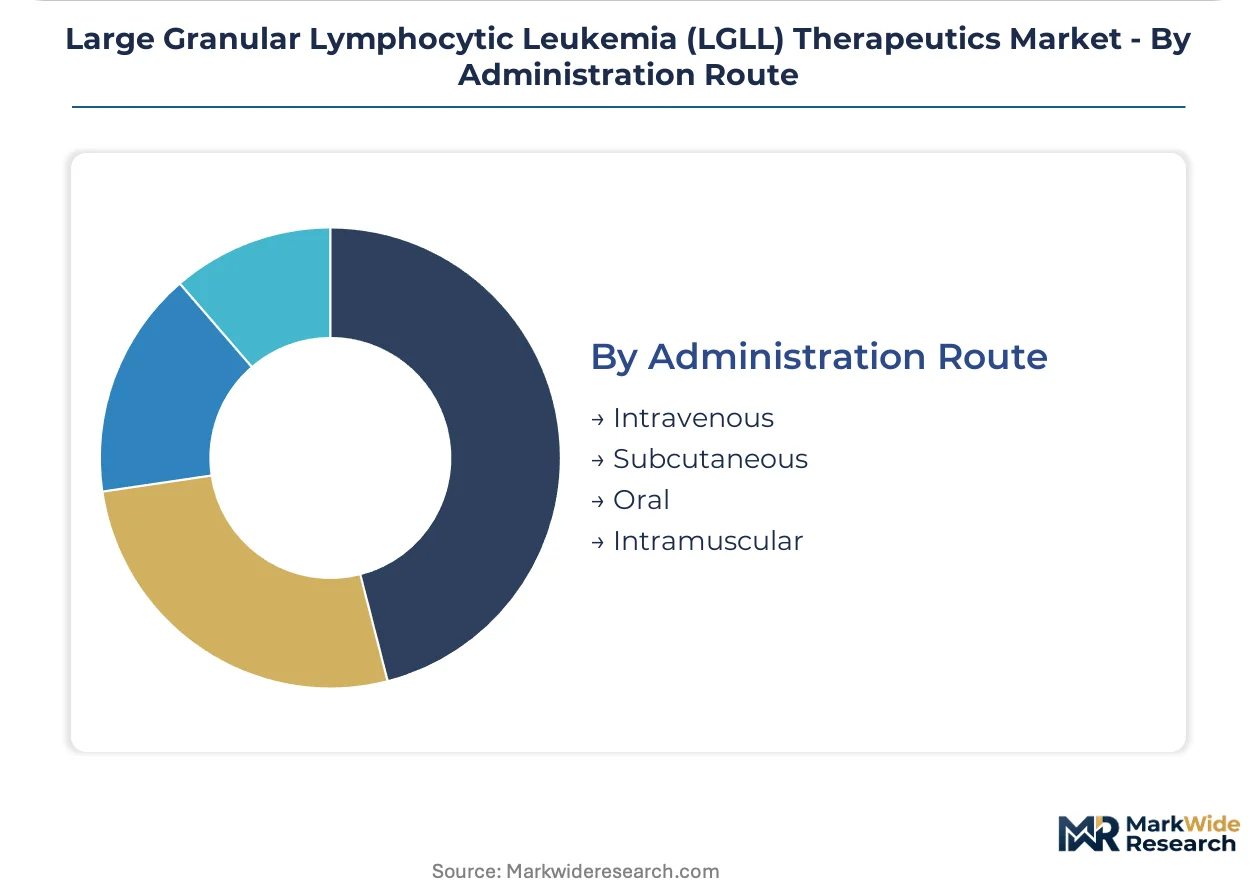
Administration Route:
Intravenous capacity constraints at academic centers are accelerating interest in subcutaneous and oral alternatives.
- Intravenous:Infusion suites require specialized nursing staff and emergency preparedness for cytokine release syndrome. United States Medicare reimbursement codes favor hospital-based administration for high-complexity protocols.
- Oral:JAK inhibitor tablets eliminate scheduling coordination and travel burden for rural patient populations. Japanese regulatory pathways prioritize oral submissions to address aging demographics and home-based care preferences.
- Subcutaneous:Self-administration potential reduces clinic capacity constraints for maintenance therapy.
- Intramuscular:Limited current application in LGLL protocols, though depot formulations attract development interest.
Intravenous dominates current protocols. Oral administration shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates LGLL clinical trial density while Germany advances biomarker standardization through university hospital networks. Japan's aging demographics accelerate oral therapy prioritization. Market access infrastructure varies sharply across these three markets.
United States
NCI-designated cancer centers anchor investigator-initiated studies through specialized leukemia units with integrated flow cytometry laboratories. FDA orphan drug designation compresses regulatory review timelines while extending market exclusivity periods. The Boston-Cambridge corridor concentrates CAR-T manufacturing infrastructure within academic medical center partnerships.
Germany
University hospitals lead European adoption of STAT3 mutation screening programs for biomarker-driven patient stratification. EMA PRIME designation mirrors FDA incentives across centralized regulatory pathways. The Rhine-Ruhr metropolitan region consolidates hematology clinic networks through cloud-based diagnostic interpretation platforms.
Japan
Aging demographics and home-based care preferences prioritize oral JAK inhibitor development over infusion-dependent protocols. PMDA regulatory pathways accommodate tablet formulations through streamlined submission frameworks. The Kanto region surrounding Tokyo anchors specialized hematology units within integrated cancer center networks.
United Kingdom
NHS England's specialized commissioning frameworks concentrate LGLL treatment within designated tertiary referral centers. MHRA post-Brexit regulatory autonomy enables accelerated access schemes for rare disease therapies. The London-Oxford-Cambridge golden triangle houses centralized flow cytometry reference laboratories.
Switzerland
Swissmedic's streamlined orphan drug procedures attract biopharma headquarters for European market access strategy. Private insurance reimbursement infrastructure supports premium pricing for novel immunomodulatory protocols. The Basel-Zurich corridor concentrates pharmaceutical R&D operations with dedicated rare disease therapeutic units.
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with immuno-oncology majors commanding clinical trial infrastructure while emerging biotechs occupy targeted mechanism niches. The vendor base concentrates around three strategic archetypes: integrated diagnostic-therapeutic platforms, T-cell modulation specialists, and autologous cell manufacturing operators. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and capacity expansion through dedicated lymphoproliferative disorder units.
Among established immuno-oncology players, Bristol Myers Squibb and Hoffmann-La Roche anchor the competitive landscape through distinct positioning archetypes. Bristol Myers Squibb exemplifies the clinical trial infrastructure model, leveraging existing immuno-oncology networks to sustain recruitment across rare lymphoproliferative indications. Hoffmann-La Roche occupies the integrated platform position, streamlining biomarker-driven treatment selection through diagnostic-therapeutic convergence. AbbVie sits within the T-cell modulation specialization tier, differentiating through pathway expertise relevant to LGLL pathogenesis.
| Leading Market Players |
|---|
| Bristol Myers Squibb and Company |
| GSK Plc |
| Sanofi SA |
| Emcure Pharma |
| Dren Bio, Inc. |
| Abcuro |
| Hoffmann-La Roche AG |
| AbbVie Inc. |
| Teva Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Orphan drug premium tiers diverge sharply from generic immunosuppressive protocols, with FDA exclusivity windows and STAT3 biomarker status creating parallel pricing tracks that reshape manufacturing investment toward vector production in the United States and monoclonal antibody fermentation in Switzerland. This bifurcation concentrates supply chain capacity within certified academic medical centers while pushing oral small molecule production toward contract manufacturers in Germany and Japan.
Pricing Analysis
Capacity additions in autologous cell manufacturing facilities across Massachusetts and North Carolina are reshaping price floors for CAR-T protocols, though per-patient production costs still exceed monoclonal antibody infusions by an order of magnitude. Three-tier pricing structure across premium cell therapies, standard biologics, and economy oral generics dominates reimbursement negotiations with CMS and private payers. Pricing pressure stems from Medicare Administrative Contractor inconsistency in coverage determinations for gene therapies. Community hematology clinics exhibit highest price sensitivity due to limited patient volume to amortize specialized pharmacy infrastructure.
Supply Chain Analysis
FDA current good manufacturing practice certification and EMA advanced therapy medicinal product qualification create dual-gated entry barriers for vector producers and cryopreservation specialists. Supply concentrates in the United States, Germany, and Switzerland for clinical-grade reagents, with plasmid DNA and lentiviral vectors drawing from specialized bioreactor networks in the Boston-Cambridge corridor. Single-source vulnerability pervades autologous leukapheresis collection logistics, where patient-specific scheduling hinges on regional apheresis center density. Distribution runs through hospital outpatient departments with dedicated lymphoproliferative disorder units rather than community infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LGLL therapeutics function as a stable compounder anchored by orphan drug exclusivity economics and concentrated prescriber bases within NCI-designated cancer centers. FDA and EMA regulatory incentives sustain predictable revenue streams across biologic and cell therapy modalities.
For Market Incumbents: Deploy companion diagnostic co-development partnerships to lock in biomarker-driven patient flow before JAK inhibitor patents expire. Incumbent biopharma players should deepen integration with academic medical center CAR-T manufacturing facilities to preempt emerging allogeneic platform threats. STAT3 mutation assay standardization investments will defend formulary positioning against diagnostic fragmentation risks.
For New Entrants and Emerging Players: Cloud-based minimal residual disease tracking platforms offer the most penetrable entry vector, with subscription software penetrating hematology clinics ahead of therapeutic commercialization. New entrants should target German university hospital networks where biomarker-driven stratification protocols concentrate prescriber influence. A reimbursement strategy bundling diagnostic interpretation with therapy access accelerates hospital pharmacy committee adoption.
For Investors and Strategic Acquirers: Consolidation pressure builds where allogeneic CAR-T platforms achieve proof-of-concept, compressing the window for autologous manufacturing asset acquisition. Investors should frame LGLL exposure within rare disease therapeutic baskets holding 5-10 year FDA exclusivity profiles. The signal to watch is CMS national coverage determination for cell and gene therapies, which would trigger site-of-care expansion and manufacturing scale-up investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA simultaneous review of STAT3 assay and JAK inhibitor streamlines biomarker-driven prescribing in academic centers. |
| Allogeneic CAR-T Platform Advancement | Off-the-shelf manufacturing from healthy donor lymphocytes eliminates patient-specific apheresis bottlenecks at specialized sites. |
| Real-World Evidence Registry Buildout | HIPAA-compliant post-market surveillance supports label expansion for combination immunomodulatory protocols beyond initial indications. |
| Site-of-Care Consolidation | Hospital outpatient department lymphoproliferative disorder units capture technical fees and reduce per-dose logistics overhead. |
| Oral Small Molecule Prioritization | Japan PMDA tablet formulation pathways address aging demographics and home-based care preferences in rural populations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA orphan drug designations, EMA PRIME submissions, ClinicalTrials.gov enrollment data, and CMS coverage determination records. Bottom-up patient volume modeling and top-down therapeutic class revenue triangulation anchored forecast integrity.
Segment-weighting approaches distributed value across monoclonal antibody, small molecule, and CAR-T modalities while cross-referencing administration route, biomarker stratification status, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to diagnosed incident cases and treatment penetration assumptions, with orphan drug exclusivity windows and companion diagnostic adoption curves serving as key forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for allogeneic CAR-T manufacturing would alter the outlook if off-the-shelf platforms displace autologous production economics faster than baseline assumptions. Forecasts rest on stable FDA orphan drug incentive structures and EMA PRIME designation continuity. A model refresh is warranted upon material change in CMS national coverage determination for cell and gene therapies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Phenylketonuria Therapeutics Market