
 Rosacea Therapeutics Market | 2026-2036
Rosacea Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Rosacea Therapeutics Market Analytics
Asset-light licensing partnerships between biotech developers and commercial dermatology platforms is rewriting competitive economics in rosacea therapeutics. Galderma leverages its integrated dermatology channel to sustain brand loyalty across prescription and aesthetic portfolios. AbbVie anchors its position through R&D intensity in immunology-derived skin therapies. Sol-Gel Technologies competes via proprietary microencapsulation delivery systems that extend topical drug release profiles.
Rosacea therapeutics encompass pharmaceutical and device-based interventions targeting the chronic inflammatory facial condition characterized by erythema, papules, and telangiectasia, with topical metronidazole, azelaic acid, and ivermectin formulations serving as first-line anti-inflammatory agents alongside pulsed-dye laser systems for vascular component reduction. Topical agents dominate current prescription volumes due to favorable tolerability profiles, though combination treatments capturing simultaneous anti-inflammatory and vascular mechanisms command premium positioning and faster growth trajectories. Oral medications occupy a narrower niche reserved for moderate-to-severe papulopustular presentations where topical monotherapy proves inadequate.
FDA oversight through the Center for Drug Evaluation and Research shapes clinical trial endpoints and labeling claims for rosacea indications, while EMA dermatology guidelines influence European market access and reimbursement thresholds for novel therapies. The EPA regulates active pharmaceutical ingredient manufacturing emissions, and ISO 13485 standards govern quality management for light therapy devices entering clinical channels. Stakeholders must monitor pipeline progression in JAK inhibitor and neurogenic inflammation pathways that could displace existing mechanism classes without requiring the full development timelines of first-in-class molecules.
Market Dynamics
The rosacea therapeutics landscape is being reshaped by the FDA's 505(b)(2) pathway, which compresses development timelines for reformulated topical agents and rewards delivery-system innovation over de novo molecular discovery.
Growth Catalysts
- Specialist channel expansion:Dermatology clinics in the United States report intensifying patient visit volumes for inflammatory skin conditions, creating pull-through demand for prescription-grade therapies.
- Microencapsulation platforms:Proprietary delivery systems that extend topical drug release profiles are improving adherence curves and expanding addressable severity segments.
- Reimbursement infrastructure:Developed prior authorization frameworks for chronic dermatological conditions reduce out-of-pocket friction and sustain prescription continuity.
Market Restraints
- API manufacturing emissions:EPA oversight of active pharmaceutical ingredient production raises compliance costs and constrains domestic manufacturing capacity for topical formulations.
- Generic substitution pressure:Patent cliffs on first-generation metronidazole and azelaic acid formulations compress pricing power for originator brands in mature markets.
- Laser device capital intensity:Pulsed-dye laser systems require substantial upfront investment and specialized technician training, limiting penetration in smaller dermatology practices.
Strategic Opportunities
- JAK inhibitor pipelines:Immunology-derived skin therapies targeting neurogenic inflammation pathways offer mechanism-class expansion without full de novo development timelines.
- Aesthetic crossover positioning:Combination treatments addressing both anti-inflammatory and vascular mechanisms command premium positioning in cash-pay cosmetic dermatology channels.
- Asset-light licensing:Biotech developers partnering with established commercial dermatology platforms access distribution without building captive sales infrastructure.
Industry Challenges
- Clinical endpoint standardization:FDA Center for Drug Evaluation and Research maintains stringent Investigator Global Assessment requirements that prolong Phase III enrollment and increase trial failure risk.
- ISO 13485 certification timelines:Light therapy device manufacturers face extended quality management system audits that delay commercial launches for laser and LED-based vascular treatments.
- Formulation stability expertise:Microencapsulation and extended-release topical development requires specialized pharmaceutical engineering talent that concentrates among a limited supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosacea Therapeutics Market |
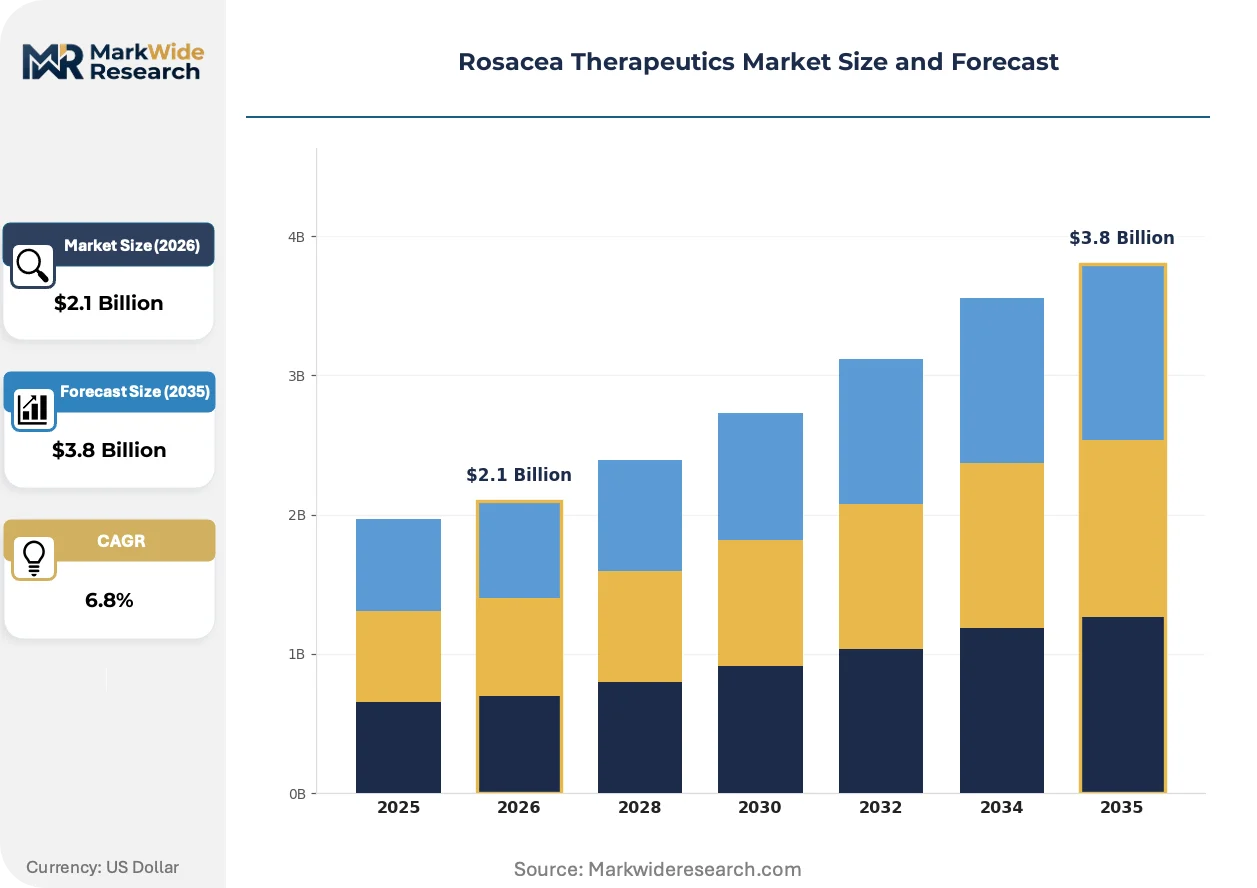
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Oral Medications, Light Therapy Devices, Combination Treatments Delivery Mode: Transdermal, Oral, Light-Based, Injectable End User: Dermatology Clinics, Homecare, Hospitals, Cosmetic Centers Treatment Stage: Acute Phase, Maintenance Phase, Recurrence Phase, Preventive Phase |
| Companies Covered | Galderma, Bausch Health Companies Inc., AbbVie Inc., Bayer AG, Nestlé Skin Health, LEO Pharma A/S, Pfizer Inc., Sol-Gel Technologies Ltd., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosacea Therapeutics Market Evolving Landscape
Reformulation science and mechanism-class expansion are displacing traditional drug development economics in rosacea therapeutics, with delivery innovation now outpacing molecular discovery as the primary value creation lever.
Microencapsulation technology enables controlled-release profiles for existing anti-inflammatory agents, extending duration of action and reducing application frequency. Dermatology clinics adopting these platforms report improved patient adherence and expanded treatment persistence. Sustained-release topical formulations are rendering obsolete conventional immediate-release creams that require twice-daily application and suffer from high discontinuation rates.
EMA dermatology guidelines are tightening reimbursement thresholds for novel rosacea therapies across European markets, demanding superior efficacy margins versus existing standard-of-care options. Manufacturers must now generate health economic evidence beyond pure clinical endpoints to secure market access. This regulatory friction most affects oral medication developers targeting moderate-to-severe papulopustular presentations, who face compressed pricing headroom in Germany and France.
Patient acquisition patterns are fragmenting across telemedicine dermatology platforms and traditional specialist offices, with digital channels capturing growing shares of initial diagnosis and prescription initiation. This channel rotation disrupts legacy pharmaceutical rep-driven detailing models and rewards direct-to-consumer educational investments. The United States exhibits the most pronounced shift, where cash-pay aesthetic crossover demand concentrates in metropolitan telehealth corridors.
Rosacea Therapeutics Market Segmentation
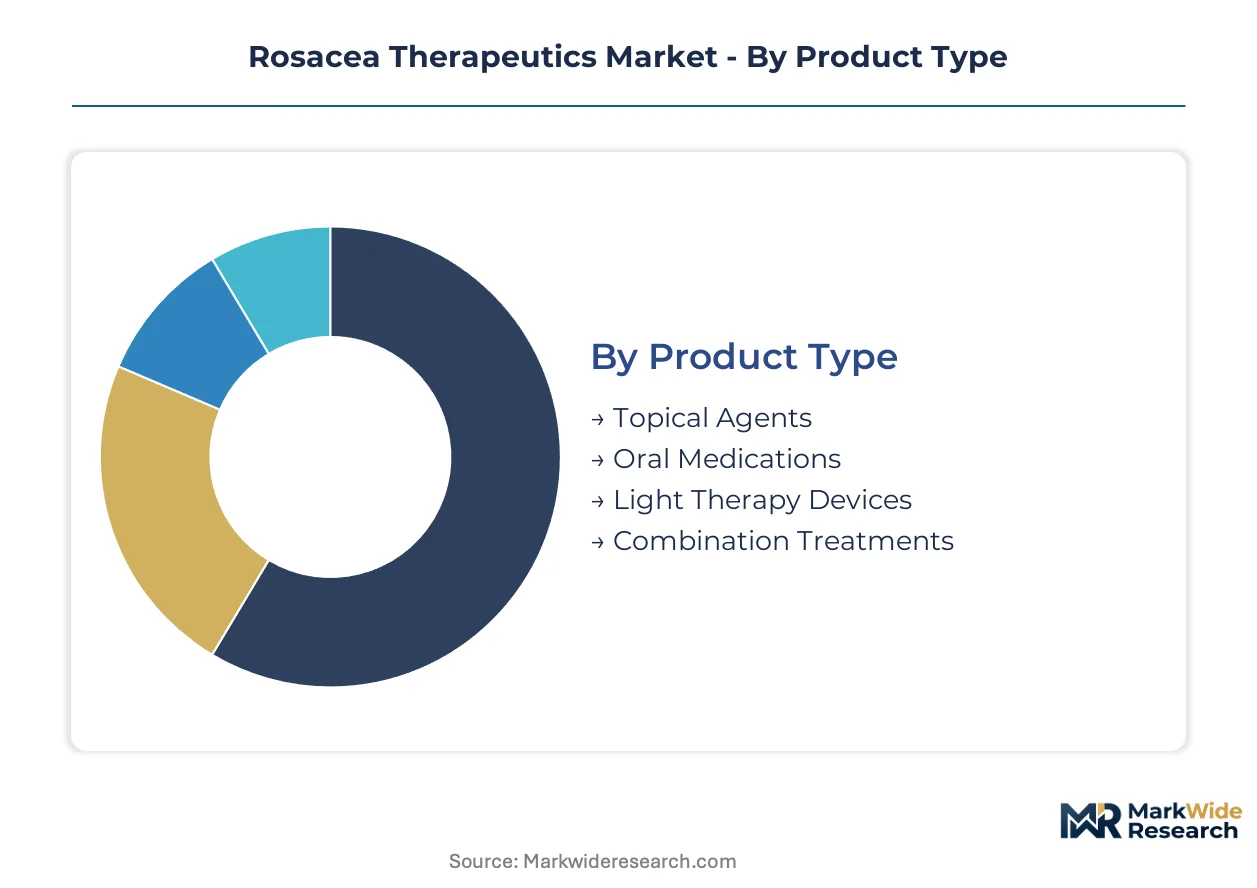
Rosacea therapeutics segmentation reveals distinct commercial dynamics across administration routes and care settings. Product formulation and delivery innovation now outpaces molecular discovery as the primary axis of competitive differentiation.
Product Type:
The use-case spectrum spans from daily maintenance regimens to procedural interventions for vascular manifestations.
- Topical Agents:Cream, gel, and foam formulations containing metronidazole, azelaic acid, or ivermectin serve as first-line anti-inflammatory therapy. Patient volumes concentrate in United States dermatology clinics where reimbursement infrastructure supports chronic prescription continuity for erythema and papulopustular presentations.
- Combination Treatments:Integrated protocols addressing simultaneous anti-inflammatory and vascular mechanisms command premium positioning. Aesthetic crossover demand in metropolitan cosmetic dermatology channels drives fastest share expansion as cash-pay patients seek comprehensive symptom resolution.
- Oral Medications:Systemic therapies including doxycycline and isotretinoin target moderate-to-severe papulopustular cases where topical monotherapy fails.
- Light Therapy Devices:Pulsed-dye laser and LED systems reduce telangiectasia through selective photothermolysis of vascular lesions.
The dominant share belongs to topical agents, while combination treatments are closing the gap fastest.
Delivery Mode:
Cost tier stratification separates mass-market formulations from capital-intensive device-based interventions.
- Transdermal:Microencapsulation platforms enable extended-release profiles that improve adherence curves. Sol-Gel Technologies and similar developers concentrate specialized pharmaceutical engineering talent for controlled-release topical engineering.
- Light-Based:Laser and LED systems require substantial upfront capital investment and ISO 13485 quality management certification. Smaller dermatology practices face barriers to adoption due to technician training requirements and equipment financing constraints.
- Oral:Systemic delivery occupies a narrower niche reserved for refractory cases, with EMA dermatology guidelines tightening reimbursement thresholds across European markets.
- Injectable:Emerging botulinum toxin and filler adjuncts target neurogenic inflammation pathways in select aesthetic protocols.
Transdermal delivery captures volume leadership, though light-based modalities show steepest expansion trajectory in cash-pay channels.
End User:
Customer type fragmentation reflects the divergence between medical necessity and aesthetic optimization demand.
- Dermatology Clinics:Specialist offices generate the highest prescription volumes for inflammatory skin conditions. United States clinic networks report intensifying patient visit volumes that pull through demand for prescription-grade and procedural rosacea therapies.
- Cosmetic Centers:Aesthetic practices capture premium-positioned combination treatments addressing both vascular and inflammatory components. Telemedicine platforms increasingly initiate diagnosis and prescription in metropolitan corridors.
- Homecare:Over-the-counter and prescription maintenance regimens support treatment persistence between clinical visits.
- Hospitals:Acute care settings manage severe ocular rosacea complications and refractory cases requiring systemic intervention.
Dermatology clinics retain the dominant share, while cosmetic centers are expanding most quickly through aesthetic crossover positioning.
Treatment Stage:
Application timing determines formulation selection, with acute interventions differing substantially from chronic maintenance protocols.
- Maintenance Phase:Long-term topical regimens sustain remission and prevent inflammatory flares. Microencapsulation delivery systems reduce application frequency and improve persistence curves for daily therapy adherence.
- Acute Phase:Intensive protocols combining oral and topical agents address active papulopustular eruptions and severe erythema.
- Recurrence Phase:Escalation strategies reintroduce prior effective therapies or rotate mechanism classes to restore disease control.
- Preventive Phase:Trigger avoidance education and subclinical anti-inflammatory prophylaxis target high-risk patient profiles.
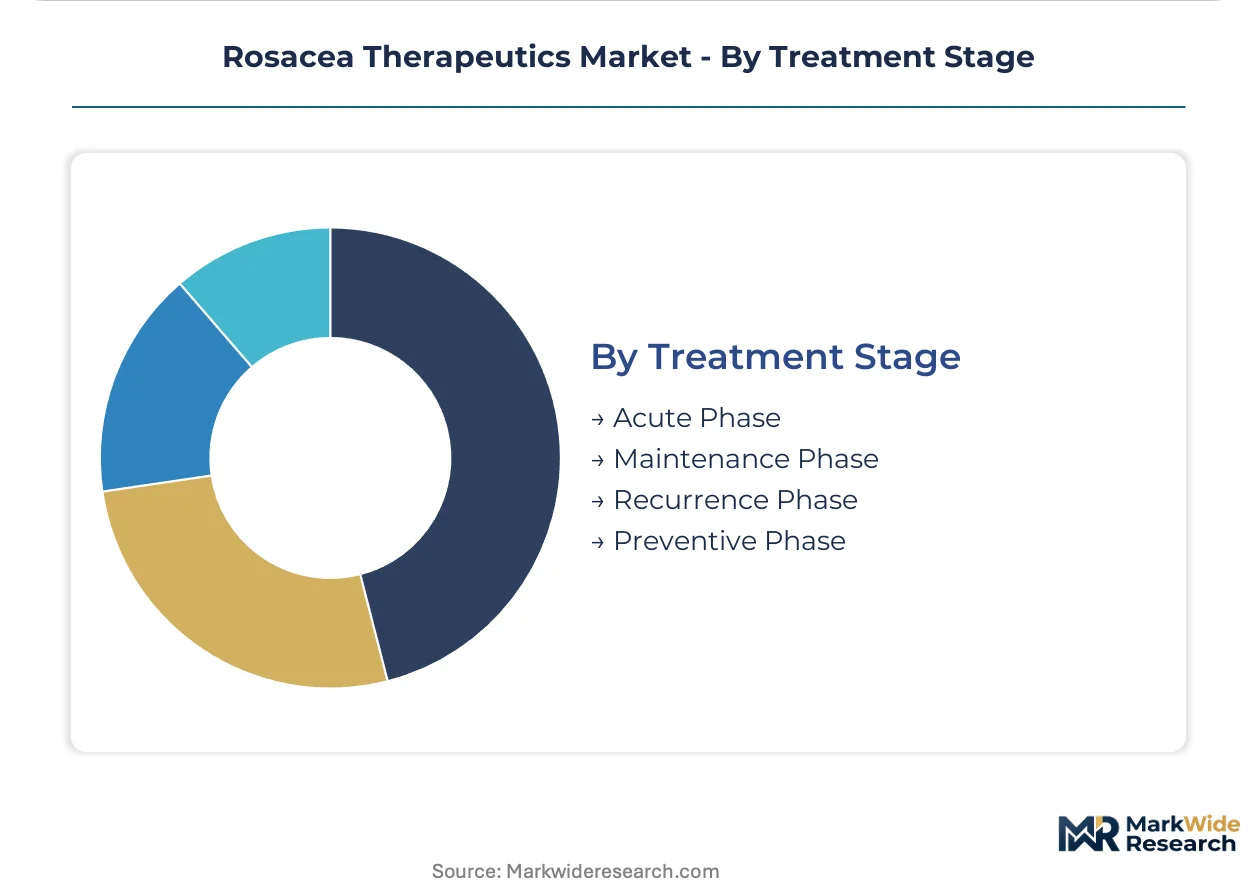
The maintenance phase holds the dominant share, while the preventive phase is gaining traction fastest through patient education investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in rosacea therapeutics concentrates in the United States, where specialist access and reimbursement infrastructure sustain premium positioning, while European markets face compressed margins under tightened health technology assessment frameworks.
United States
Dermatology clinic networks in metropolitan corridors report intensifying patient visit volumes for inflammatory skin conditions, pulling through demand for prescription-grade and procedural therapies. FDA oversight through the Center for Drug Evaluation and Research shapes clinical trial endpoints and labeling claims, with the 505(b)(2) pathway accelerating reformulated topical approvals. Boston and San Francisco anchor the highest concentration of biotech developers pursuing JAK inhibitor pipelines for neurogenic inflammation pathways.
Germany
EMA dermatology guidelines and the Federal Joint Committee's health technology assessments demand superior efficacy margins versus standard-of-care for novel therapy reimbursement. The KBA does not regulate this sector, though the country's national pharmaceutical regulator enforces strict manufacturing standards for API production. The Rhine-Main cluster around Frankfurt concentrates dermatology-focused contract research organizations supporting pan-European trial enrollment.
United Kingdom
NICE appraisals tighten reimbursement thresholds for oral medications targeting moderate-to-severe papulopustular presentations, compressing pricing headroom for systemic therapies. The MHRA operates under retained EU legislation post-Brexit while developing independent approval pathways. London's Harley Street medical district captures premium aesthetic crossover demand for combination treatments addressing vascular and inflammatory components.
Japan
PMDA review timelines for dermatology indications extend commercialization schedules compared to FDA pathways, though conditional early approval schemes for serious conditions offer acceleration mechanisms. METI industrial policy supports domestic pharmaceutical manufacturing capacity. The Kanto region around Tokyo hosts the densest concentration of dermatology specialist clinics and aesthetic medicine practices in Asia-Pacific.
France
ANSM pharmacovigilance requirements and HAS transparency committee evaluations create dual regulatory hurdles for market access. The country's national pharmaceutical regulator maintains stringent post-marketing surveillance obligations for topical formulations. The Île-de-France region, particularly Paris and its western suburbs, concentrates both hospital-based dermatology departments and high-end cosmetic dermatology centers serving cash-pay patients.
Rosacea Therapeutics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in delivery technology and API supply. The rosacea therapeutics market structures around three distinct competitive tiers: global dermatology platforms with integrated commercial infrastructure, mid-cap specialists leveraging proprietary formulation science, and generic manufacturers capturing volume in off-patent molecular categories. Dominant competitive moves include asset-light licensing partnerships between biotech developers and established commercial platforms, plus vertical integration into microencapsulation manufacturing to secure supply of specialized delivery systems.
Within the integrated platform tier, Galderma and AbbVie exemplify archetypes of dermatology-focused commercial scale and immunology-derived R&D intensity respectively. Sol-Gel Technologies occupies a position among delivery-system specialists, representing the microencapsulation platform approach that extends topical drug release profiles. These three companies anchor distinct strategic vectors: channel integration, mechanism-class expansion, and formulation innovation.
| Leading Market Players |
|---|
| Galderma |
| Bausch Health Companies Inc. |
| AbbVie Inc. |
| Bayer AG |
| Nestlé Skin Health |
| LEO Pharma A/S |
| Pfizer Inc. |
| Sol-Gel Technologies Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic API manufacturing capacity is tightening supplier leverage and compressing margin structures for topical formulation developers across the United States. This utilization squeeze simultaneously elevates input costs and reduces pricing flexibility for finished goods, particularly for microencapsulation-dependent delivery platforms.
Pricing Analysis
The customization-premium spread between standard immediate-release topicals and configured-to-order extended-release formulations spans three-tier pricing stratification across premium, standard, and economy levels. Originators with proprietary microencapsulation platforms command premium positioning through ISO 13485-certified quality tiers and vertical integration into specialized pharmaceutical engineering. Cost compression in the generic metronidazole segment is intensifying because of patent cliff exposure and Indian API import competition. Cash-pay cosmetic dermatology channels exhibit the lowest price sensitivity, while Medicaid-dependent patient populations drive volume through prior authorization-constrained standard tiers.
Supply Chain Analysis
Export-control regime friction around pharmaceutical manufacturing equipment is constraining capacity expansion timelines for domestic microencapsulation facilities. Active pharmaceutical ingredient supply concentrates in India and China for azelaic acid and ivermectin precursors, with domestic United States production limited to specialized metronidazole grades. Finished formulation draws from excipient networks spanning Germany and Switzerland for controlled-release polymers. Single-source vulnerability sits with the limited supplier base for pharmaceutical-grade microencapsulation engineering talent. Distribution runs through specialty pharmacy channels and dermatology clinic direct purchasing, bypassing traditional wholesale consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rosacea therapeutics market functions as a defensive-moat arena where FDA regulatory entrenchment through the 505(b)(2) pathway creates durable barriers against rapid competitive replication.
For Market Incumbents: Insulate brand positioning through captive supply of microencapsulation manufacturing capacity and exclusive channel partnerships with metropolitan dermatology clinic networks. The emerging threat of JAK inhibitor mechanism-class displacement demands accelerated R&D investment in neurogenic inflammation pathways. Prior authorization infrastructure control represents the critical lever for sustaining prescription continuity against generic substitution pressure. For New Entrants and Emerging Players: Cash-pay aesthetic crossover protocols in United States metropolitan telehealth corridors represent the most penetrable entry point for premium-positioned combination treatments. European oral medication segments facing HAS and NICE reimbursement compression offer white-space acquisition targets for mechanism-class expansion. A direct-to-consumer educational investment strategy bypasses legacy pharmaceutical rep-driven detailing models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated dermatology platforms with captive distribution infrastructure and chronic condition patient retention programs. Long-term viability centers on regulatory asset accumulation rather than single-product cycles. The signal to monitor is FDA 505(b)(2) approval velocity for reformulated topical agents, which indicates pipeline optionality value. Material acceleration in JAK inhibitor clinical progression would force portfolio repositioning toward immunology-derived skin therapy developers.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Platform Licensing | Proprietary delivery systems extend topical release profiles and improve patient adherence curves. |
| 505(b)(2) Regulatory Pathway Navigation | FDA streamlined approvals accelerate reformulated topical timelines versus de novo molecular development. |
| Dermatology Clinic Network Partnership | Specialist channel integration captures intensifying patient visit volumes for inflammatory conditions. |
| Aesthetic Crossover Positioning | Cash-pay cosmetic dermatology channels command premium pricing for combination vascular-inflammatory protocols. |
| JAK Inhibitor Pipeline Diversification | Immunology-derived mechanisms target neurogenic inflammation without full first-in-class development investment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic administrators, pharmaceutical regulatory affairs leads, formulary access specialists, and microencapsulation manufacturing engineers. Secondary validation drew from FDA 505(b)(2) approval databases, EMA dermatology guideline publications, ClinicalTrials.gov enrollment records, and ISO 13485 certification registries. Bottom-up prescription volume modeling and top-down market sizing triangulation anchored value estimates.
Calibration against historical approval timelines and reimbursement adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions included product formulation, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from patent expiry schedules, pipeline progression rates, and channel expansion trajectories. Forecast inputs incorporated FDA review cycle durations and EMA health technology assessment evolution patterns.
Practitioners should monitor 505(b)(2) approval velocity and EMA reimbursement threshold tightening for early signals of competitive dynamics shift. Forecasts reflect assumptions regarding regulatory pathway continuity and specialist channel access stability. Material shifts in FDA dermatology division staffing or European health technology assessment stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market