
 Global Interstitial Cystitis Market | 2026-2036
Global Interstitial Cystitis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interstitial Cystitis Market Foresight
A shortage of fellowship-trained urologists with pelvic medicine subspecialty certification is redrawing competitive dynamics across the interstitial cystitis landscape. Pfizer Inc. leverages its established pain management portfolio to sustain formulary access in urology clinics. Astellas Pharma Inc. anchors its position through specialized urology sales infrastructure. Seikagaku Corporation differentiates via its hyaluronic acid instillations pipeline.
Interstitial cystitis denotes a chronic bladder pain syndrome characterized by pelvic discomfort, urinary urgency, and frequency without demonstrable infection, typically diagnosed through cystoscopy with hydrodistention and assessed via validated symptom indices such as the O'Leary-Sant Interstitial Cystitis Symptom and Problem Index. Oral medications dominate current prescribing patterns, though nerve stimulation devices represent the fastest-expanding modality as rechargeable sacral neuromodulation systems gain reimbursement traction. Bladder instillations retain stable utilization in refractory cases, with margin pools concentrating among compounded formulations and branded hyaluronic acid variants.
The FDA regulates device-based therapies through premarket notification and premarket approval pathways, while the EMA's MDR framework imposes stricter clinical evidence requirements on implantable neuromodulation systems entering European markets. Japan's PMDA maintains distinct pharmacovigilance protocols for intravesical agents, creating differentiated approval timelines across major jurisdictions. Stakeholders must monitor evolving reimbursement coding for remote neuromodulation programming and position their clinical evidence generation to match payer evidence requirements in each target market.
Market Dynamics
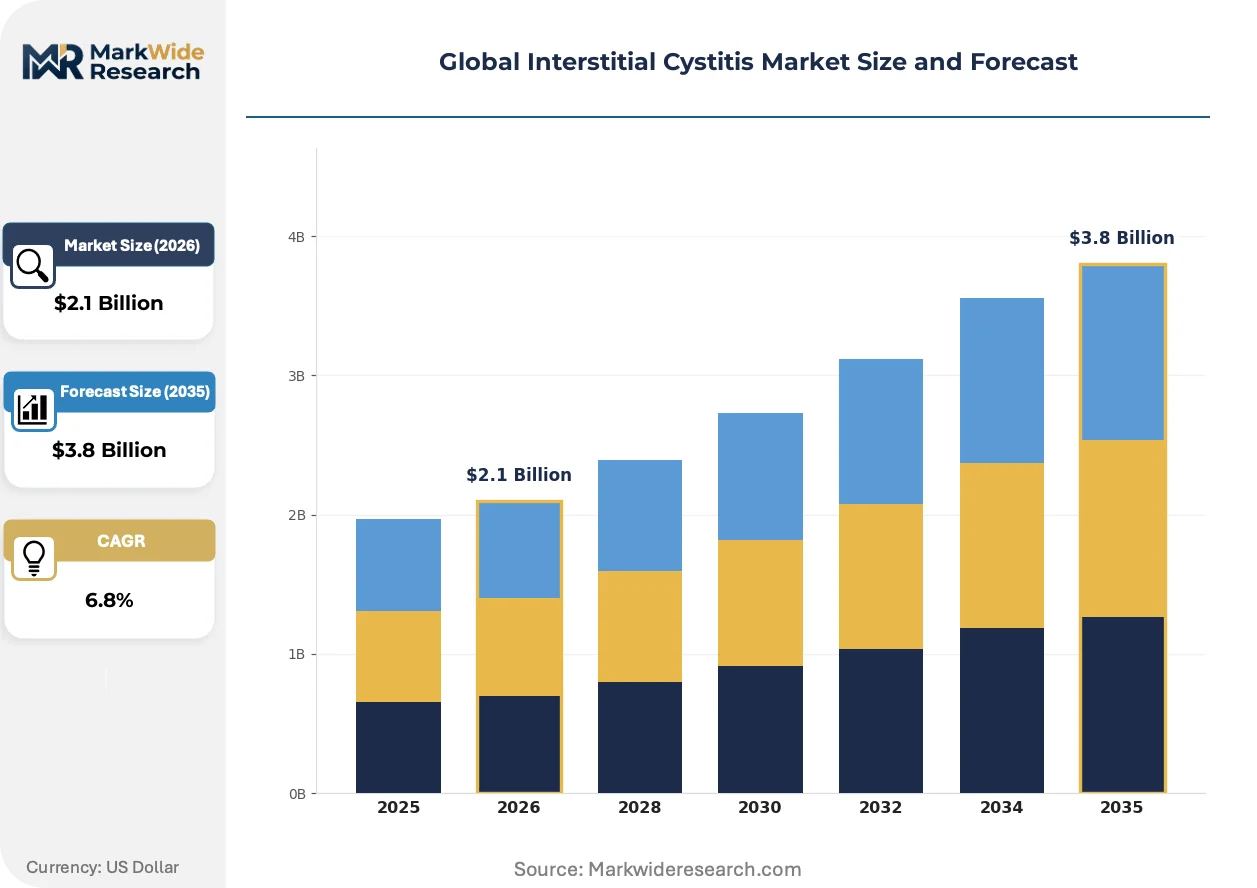
The interstitial cystitis treatment landscape is restructuring around neuromodulation device reimbursement expansion, as sacral nerve stimulation systems secure Category 1 CPT codes that accelerate hospital capital budgeting cycles for implantable therapies.
Growth Catalysts
- MDR clinical evidence harmonization:The EU's Medical Device Regulation creates streamlined pathways for implantable neuromodulation systems, reducing redundant trials across member states and compressing time-to-market for European launches.
- Academic medical center clustering:Pelvic pain specialty programs concentrate at Johns Hopkins, Mayo Clinic, and Cleveland Clinic, generating referral networks that concentrate high-complexity patients and drive protocol standardization.
- Hyaluronic acid compounding flexibility:US 503B outsourcing facilities enable pharmacy-level formulation customization for intravesical instillations, expanding access beyond branded product formularies.
Market Restraints
- Polymer supply concentration:Medical-grade hyaluronic acid raw material production clusters with three Japanese and Korean suppliers, exposing formulation pipelines to single-source disruption risk.
- FDA premarket approval timelines:Novel neuromodulation algorithms face 18-24 month PMA review cycles, delaying revenue recognition for device manufacturers with rechargeable platform upgrades.
- Oral pentosan polysulfate substitution:Generic sodium pentosan polysulfate commoditization compresses margin pools for first-line pharmaceutical prescribing, diverting R&D investment toward device modalities.
Strategic Opportunities
- India urology infrastructure buildout:Corporate hospital chains in Mumbai, Delhi, and Bangalore are establishing dedicated pelvic medicine units, creating first-mover positioning for neuromodulation training and device placement programs.
- Remote programming CPT unbundling:US Medicare's evaluation of separate reimbursement for wireless neuromodulation parameter adjustment creates service revenue streams independent of implant hardware sales.
- Biomarker-guided patient stratification:Integration of urinary cytokine panels with artificial intelligence classification tools enables precision matching of IC subtype to optimal therapy modality.
Industry Challenges
- Fellowship pipeline constraints:Female pelvic medicine and reconstructive surgery training programs graduate fewer than 50 US specialists annually, creating patient access bottlenecks that extend diagnosis-to-treatment intervals.
- Interoperability fragmentation:Proprietary neuromodulation programming software from Boston Scientific, Medtronic, and Axonics lacks standardized data exchange protocols, complicating multi-device patient management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interstitial Cystitis Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Bladder Instillations, Nerve Stimulation Devices, Pain Management Therapies, Surgical Interventions Therapy Area: Chronic Pain Relief, Anti-inflammatory Treatment, Neuromodulation, Urinary Symptom Control, Psychological Support End User: Urology Clinics, Specialized Hospitals, Ambulatory Surgery Centers, Rehabilitation Centers, Pain Management Centers Delivery Mode: Oral, Intravesical, Transcutaneous, Intravenous, Implantable Device |
| Companies Covered | Johnson & Johnson (Janssen Pharmaceuticals), Pfizer Inc., Viatris Inc., Teva Pharmaceutical Industries Ltd., Astellas Pharma Inc., Kyorin Pharmaceutical Co., Ltd., UCB Pharma, Seikagaku Corporation, Grünenthal GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interstitial Cystitis Market Shifts & Advancements
Neuromodulation hardware is fragmenting into rechargeable and primary battery platforms, while diagnostic protocols incorporate molecular phenotyping that segments the historically heterogeneous patient population into actionable treatment cohorts.
Sacral nerve stimulation technology is bifurcating into full implantable pulse generators and external trial systems that reduce upfront patient commitment. Academic medical centers in the United States are adopting conditional 2-week external trials before permanent implantation, compressing the sales cycle for device manufacturers. This dual-path approach is bifurcating the market into high-certainty surgical candidates and observation-phase patients who require less intensive follow-up infrastructure.
Japan's PMDA revised its pharmacovigilance guidance for intravesical biologics in 2023, mandating real-world evidence collection through the Medical Information Database Network. Japanese urology clinics must now submit post-market safety data for hyaluronic acid instillations, increasing compliance costs for foreign manufacturers. Domestic players with established pharmacovigilance infrastructure are capturing market share as European competitors delay re-registration.
Self-referral patterns are fragmenting traditional primary care gatekeeping for interstitial cystitis diagnosis. Patients in Germany and the United Kingdom are accessing pelvic pain specialty clinics directly through online scheduling platforms, bypassing general practitioner consultation requirements. This channel shift concentrates case volume at centers with digital marketing capabilities while depleting community urology practices of complex referrals.
Global Interstitial Cystitis Market Segmentation
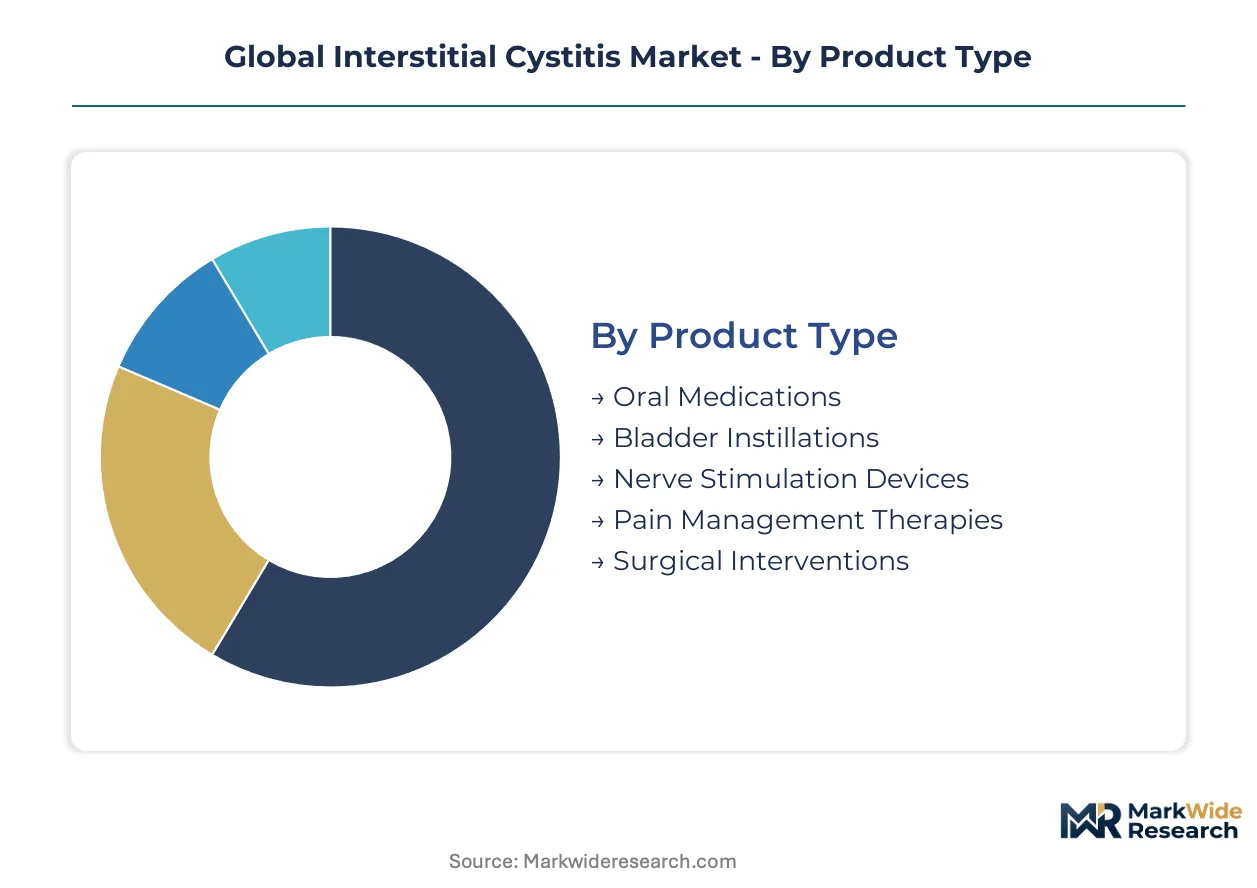
Interstitial cystitis treatment modalities span pharmaceutical, device, and procedural categories with divergent reimbursement pathways and regulatory requirements. Patient stratification by symptom severity and prior treatment history determines access to invasive neuromodulation versus conservative pharmacological management.
Product Type:
FDA PMA timelines for implantable devices stretch 18-24 months, while oral medications navigate abbreviated NDA pathways, compressing commercialization schedules for pharmaceutical entrants.
- Oral Medications:Pentosan polysulfate sodium and amitriptyline formulations constitute first-line prescribing. Generic substitution has commoditized this segment, with US urology clinics prioritizing formulary cost containment over brand loyalty.
- Bladder Instillations:Hyaluronic acid and dimethyl sulfoxide solutions administered via catheter directly to bladder mucosa. Japanese PMDA pharmacovigilance mandates for intravesical biologics favor domestic manufacturers with established post-market surveillance infrastructure.
- Nerve Stimulation Devices:Sacral neuromodulation systems with rechargeable pulse generators.
- Pain Management Therapies:Multimodal analgesic protocols combining neuropathic agents.
- Surgical Interventions:Hydrodistention and urinary diversion procedures for refractory cases.
Oral medications handle the majority of throughput; nerve stimulation devices are climbing the fastest on share.
Therapy Area:
Cost tiering separates maintenance pharmacotherapy from capital-intensive device implantation, with academic medical centers capturing complex neuromodulation cases.
- Chronic Pain Relief:Multidisciplinary protocols targeting pelvic floor dysfunction and central sensitization. Johns Hopkins and Mayo Clinic specialty programs concentrate high-complexity referrals.
- Anti-inflammatory Treatment:Intravesical and systemic agents modulating bladder mucosal integrity. Compounding flexibility through US 503B outsourcing facilities expands access beyond branded formularies.
- Neuromodulation:Electrical stimulation of sacral nerves to modulate bladder afferent signaling.
- Urinary Symptom Control:Antimuscarinics and beta-3 agonists managing urgency-frequency.
- Psychological Support:Cognitive behavioral therapy addressing pain catastrophization.
Chronic pain relief absorbs the largest patient volume; neuromodulation is expanding most quickly as rechargeable platforms secure Category 1 CPT codes.
End User:
Referral patterns concentrate severe cases at centers with fellowship-trained pelvic medicine specialists, fragmenting volume across community and academic tiers.
- Urology Clinics:Private practice and group settings managing initial diagnosis and medical therapy. Cleveland Clinic and Johns Hopkins networks generate protocol standardization that community practices adopt.
- Specialized Hospitals:Academic medical centers with female pelvic medicine fellowship programs. Fewer than 50 US specialists graduate annually, creating access bottlenecks that extend diagnosis-to-treatment intervals.
- Ambulatory Surgery Centers:Outpatient settings for trial stimulation and implantation procedures.
- Rehabilitation Centers:Pelvic floor physical therapy and biofeedback programs.
- Pain Management Centers:Interdisciplinary clinics coordinating opioid-sparing protocols.
Urology clinics manage the majority of throughput; specialized hospitals are gaining share fastest through referral network consolidation.
Delivery Mode:
Application requirements differentiate acute intervention from chronic maintenance, with implantable systems requiring surgical infrastructure.
- Oral:Systemic absorption with convenience advantages for maintenance therapy. Generic pentosan polysulfate commoditization has diverted manufacturer investment toward device modalities.
- Intravesical:Direct bladder instillation bypassing systemic metabolism. EU MDR harmonization creates streamlined pathways for catheter delivery systems, reducing redundant trials across member states.
- Transcutaneous:Non-invasive electrical stimulation for home-based therapy.
- Intravenous:Hospital-administered agents for acute exacerbations.
- Implantable Device:Permanent neuromodulation systems with remote programming capabilities.
Oral delivery handles the majority of throughput; implantable devices show the steepest expansion trajectory as remote programming CPT unbundling creates service revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates neuromodulation device utilization while Germany and Japan favor bladder instillation protocols, creating divergent reimbursement and prescribing patterns across major markets.
United States
Academic medical centers at Johns Hopkins, Mayo Clinic, and Cleveland Clinic drive sacral neuromodulation adoption through specialized pelvic pain fellowship programs. FDA premarket approval pathways for implantable devices stretch 18-24 months, compressing revenue timelines for rechargeable platform upgrades. Boston and Baltimore surgical corridors concentrate device placement volume as Category 1 CPT codes accelerate hospital capital budgeting.
Germany
Self-referral patterns through digital scheduling platforms bypass traditional general practitioner gatekeeping, concentrating patients at centers with online marketing capabilities. EMA's MDR framework imposes stricter clinical evidence requirements on implantable systems entering European markets. Berlin and Munich academic hospitals generate protocol standardization that community urology practices adopt across the federal system.
Japan
PMDA pharmacovigilance mandates for intravesical biologics require real-world evidence collection through the Medical Information Database Network, favoring domestic manufacturers with established post-market surveillance infrastructure. Tokyo and Osaka urology clinics must submit post-market safety data for hyaluronic acid instillations. Japanese suppliers dominate medical-grade hyaluronic acid raw material production.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore are establishing dedicated pelvic medicine units, creating first-mover positioning for neuromodulation training programs. CDSCO regulates device imports through distinct licensing pathways that differ from pharmaceutical registration timelines. Hyderabad and Chennai surgical centers are building referral networks for complex pelvic pain cases.
United Kingdom
NHS England's specialized commissioning frameworks restrict access to sacral nerve stimulation to designated centers, creating tiered patient pathways. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance requirements for device manufacturers. London teaching hospitals concentrate fellowship-trained specialists while regional centers manage maintenance pharmacotherapy.
Global Interstitial Cystitis Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical conglomerates controlling oral medication formularies while device manufacturers and hyaluronic acid specialists occupy distinct niches. The market structure reflects therapy modality fragmentation rather than consolidated category dominance. Three archetypes prevail: pain management portfolio generalists, urology-dedicated sales infrastructure operators, and intravesical formulation specialists. Portfolio diversification and geographic expansion through training partnerships represent the dominant competitive vectors.
Within the pharmaceutical tier, Pfizer Inc. and Astellas Pharma Inc. anchor distinct positioning through established urology channel relationships, while Seikagaku Corporation occupies the formulation specialist position. These three entities exemplify how competitive separation occurs through therapy modality focus rather than direct product confrontation, with each representing a strategic archetype visible across the competitive set.
| Leading Market Players |
|---|
| Johnson & Johnson (Janssen Pharmaceuticals) |
| Pfizer Inc. |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Astellas Pharma Inc. |
| Kyorin Pharmaceutical Co., Ltd. |
| UCB Pharma |
| Seikagaku Corporation |
| Grünenthal GmbH |
| Others |
Supply & Pricing Matrix
Generic sodium pentosan polysulfate substitution into first-line oral therapy protocols simultaneously redistributes manufacturing volume toward Indian and Chinese API producers and collapses branded pricing power across urology formularies. This displacement forces incumbent pharmaceutical manufacturers toward device modalities and intravesical formulations where supply concentration and regulatory barriers preserve margin structures.
Pricing Analysis
Contract-based long-term offtake agreements dominate hyaluronic acid raw material procurement, while spot purchasing governs compounded intravesical formulations dispensed through 503B outsourcing facilities. Price differentiation rests on FDA certification tier and geographic delivery cost, with Japanese medical-grade suppliers commanding premiums over Korean alternatives. Pricing pressure stems from generic oral medication commoditization that diverts payer budgets toward capital-intensive neuromodulation hardware. Community urology clinics exhibit highest price sensitivity due to formulary cost containment mandates, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Osaka-Kobe pharmaceutical corridor concentration creates single-source vulnerability for medical-grade hyaluronic acid feedstocks. Manufacturing draws from Japanese and Korean polymer suppliers, Chinese API producers, and German precision electronics for implantable pulse generators. Tariff exposure on device components imported into India compounds logistics risk for neuromodulation system assemblers. Distribution runs through hospital procurement committees at academic medical centers, GPO contracts for community urology networks, and direct-to-clinic pharmacy channels for compounded instillations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from rechargeable sacral neuromodulation platforms that displace oral pharmacotherapy revenue pools. Defense requires structural repositioning toward modalities with embedded supply chain barriers.
For Market Incumbents: Consolidate formulation expertise around intravesical biologics where PMDA pharmacovigilance infrastructure requirements exclude commodity competitors. Secure backward integration into medical-grade hyaluronic acid polymer supply through captive Japanese supplier relationships. Counter generic oral substitution by embedding device training partnerships within Johns Hopkins and Mayo Clinic fellowship programs that lock in referral channel control. For New Entrants and Emerging Players: Lead with remote neuromodulation programming service models that exploit Medicare CPT unbundling evaluation to capture recurring revenue independent of hardware margins. Target ambulatory surgery centers in underserved US metropolitan corridors lacking academic medical center proximity. Penetrate India through corporate hospital chain training partnerships in Mumbai and Bangalore before established players consolidate pelvic medicine unit infrastructure. For Investors and Strategic Acquirers: FDA PMA timeline compression for rechargeable platform upgrades reshapes the acquisition landscape toward device manufacturers with cleared iterative improvement pathways. Five-to-ten year viability favors neuromodulation hardware specialists over oral pharmaceutical portfolios facing generic erosion. Monitor Category 1 CPT code expansion signals as inflection indicators for hospital capital budgeting acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Remote programming CPT unbundling creates service revenue streams independent of implant sales at Boston Scientific and Medtronic. |
| Hospital System Partnership | Johns Hopkins pelvic pain fellowship program generates protocol standardization that community practices adopt across referral networks. |
| CE Marking Pathway | EU MDR harmonization reduces redundant trials across member states for Axonics rechargeable sacral neuromodulation launches. |
| Software Companion Development | Artificial intelligence classification tools for urinary cytokine panels enable precision matching of IC subtype to therapy modality. |
| Manufacturing Scale-Up | 503B outsourcing facility expansion compounds access to customized hyaluronic acid formulations beyond branded product formularies. |
Research Methodology
Desk research of FDA 510(k) and PMA filings, EMA MDR submission databases, and Japanese PMDA pharmacovigilance guidance preceded structured interviews with female pelvic medicine fellowship directors, urology clinic procurement managers, and neuromodulation device reimbursement specialists. Secondary validation drew from CMS Medicare claims data, hospital GPO contract repositories, and hyaluronic acid raw material trade flow records. Bottom-up patient volume estimates by therapy modality triangulated against top-down pharmaceutical and device manufacturer revenue disclosures.
Variance decomposition across oral medication, bladder instillation, and neuromodulation device segments informed analytical framework construction throughout the forecast period. Modeled dimensions span product type, therapy area, end user tier, and delivery mode, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway differentiation. CAGRs derived from procedure volume trajectories at academic medical centers, reimbursement code adoption curves, and raw material supply expansion plans across the analysis window.
Forecasts assume regulatory continuity in FDA PMA review timelines and Japanese PMDA pharmacovigilance mandates; material policy shifts would require re-modeling. Specific risk factors include fellowship pipeline constraints that extend diagnosis-to-treatment intervals and polymer supply concentration that exposes formulation pipelines to single-source disruption. Practitioners should keep alternative scenarios live as remote neuromodulation reimbursement determinations and MDR harmonization implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Immunology Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Recto-Vaginal Fistula Market