
 Organ Transplant Immunosuppressant Drugs Market | 2026-2036
Organ Transplant Immunosuppressant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Transplant Immunosuppressant Drugs Market Intelligence
The distinction between patented, next-generation biologics and off-patent small molecule generics is hardening. This split creates separate value pools for innovation-focused and volume-focused participants. Novartis AG leverages its strong portfolio in mTOR and calcineurin inhibitors to command the premium segment. Astellas Pharma specializes in calcineurin inhibitors for specific transplant types, while Sanofi competes with a mix of established therapies and pipeline assets for broad market coverage.
Organ transplant immunosuppressant drugs are pharmacological agents designed to prevent allograft rejection by modulating the host's immune response. These therapies primarily function by inhibiting pathways like T-cell activation, a critical step in the rejection cascade. Calcineurin inhibitors remain the foundational therapy class, though mTOR inhibitors are gaining traction for specific patient profiles. Kidney transplant applications constitute the largest volume segment due to higher procedural frequency, with liver transplants representing a significant secondary market.
Market access and clinical trial protocols are governed by stringent regulatory bodies, including the US FDA, the European Medicines Agency (EMA), and Japan's PMDA. These agencies mandate extensive evidence of safety and efficacy, particularly for novel biologics, influencing R&D timelines and costs. The key decision for developers now involves balancing the pursuit of breakthrough therapies against the optimization of existing drug delivery and formulation for life-cycle management.
Market Dynamics
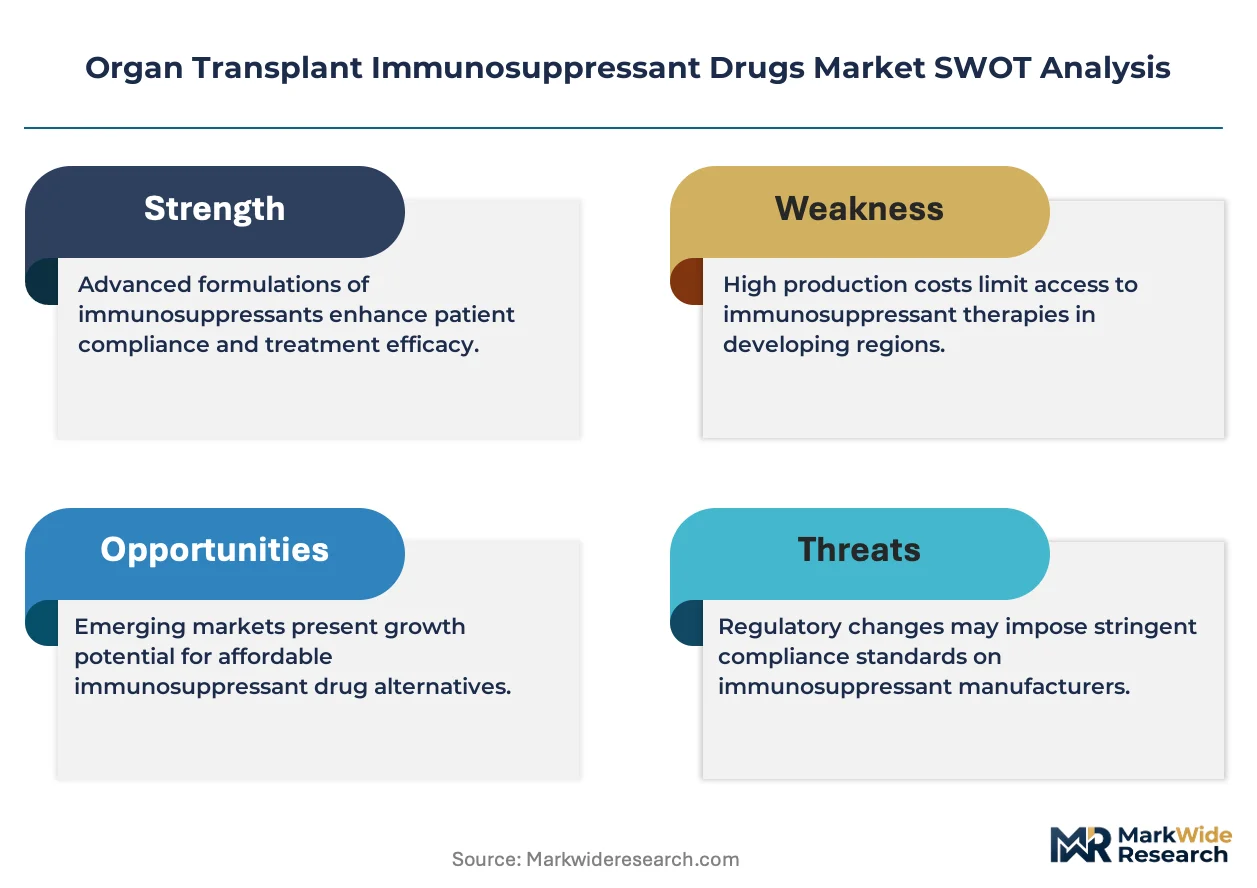
The central dynamic shaping the market is the bifurcation between high-cost, patented biologics and volume-driven, off-patent small molecule generics. This structural split creates distinct value pools and competitive arenas for innovation-focused and scale-focused participants.
Growth Catalysts
- Advanced Biologics:The development of next-generation biologics, such as co-stimulation blockers, provides more targeted immunosuppression, leading to improved graft survival and reduced side effects for specific patient cohorts.
- Kidney Transplant Volume:A rising incidence of end-stage renal disease globally is increasing the number of kidney transplant procedures, which are the largest volume driver for immunosuppressant drug consumption.
- Demographic Shifts in Developed Nations:Aging populations and improved longevity in countries like Japan and Germany are expanding the eligible patient pool for solid organ transplantation, sustaining demand for long-term immunosuppressive therapy.
Market Restraints
- High Development Costs:The research and development of novel biologics is exceptionally capital-intensive, with extensive preclinical and clinical trial phases mandated by regulators like the US FDA.
- Stringent Regulatory Scrutiny:Regulatory bodies, including the European Medicines Agency (EMA), enforce rigorous protocols for proving safety and efficacy, creating long and uncertain pathways to market approval.
- Generic Erosion:The patent expiration of foundational therapies, particularly first-generation calcineurin and mTOR inhibitors, leads to rapid price erosion and market share loss to generic competitors.
Strategic Opportunities
- Life-Cycle Management:Reformulating established drugs into new delivery systems, such as long-acting injectables or oral formulations with improved bioavailability, can extend patent life and defend market share.
- Personalized Dosing Regimens:Developing therapies linked to specific biomarkers or pharmacogenomic tests allows for patient stratification, improving outcomes and justifying premium pricing for targeted treatments.
- Expansion into Underserved Transplants:Focusing research on immunosuppressive protocols for less common procedures, such as lung or intestinal transplants, addresses significant unmet clinical needs and offers a path for market entry.
Industry Challenges
- Patient Adherence:Ensuring long-term patient compliance with complex, multi-drug regimens remains a significant operational hurdle, impacting therapeutic efficacy and leading to preventable graft rejection events.
- Clinical Trial Recruitment:Enrolling sufficient numbers of patients for clinical trials in specific transplant types can be difficult, slowing down the development and approval of new therapies.
- Intellectual Property Disputes:The complex patent landscape surrounding biologics and the emergence of biosimilars create a contentious environment, leading to costly and protracted legal challenges for innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Transplant Immunosuppressant Drugs Market |
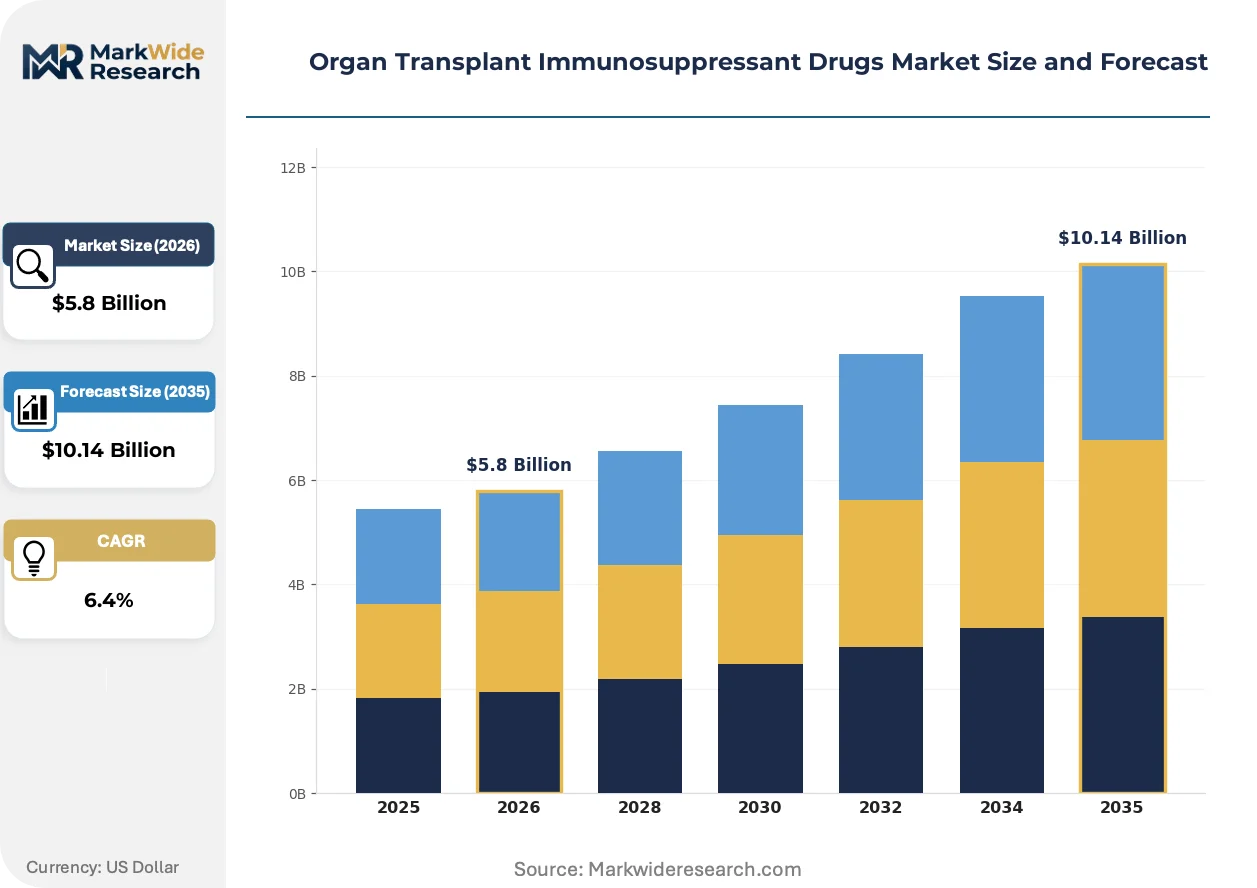
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcineurin Inhibitors, mTOR Inhibitors, Corticosteroids, Antiproliferative Agents, Co-stimulation Blockers Application: Kidney Transplant, Liver Transplant, Heart Transplant, Lung Transplant, Pancreas Transplant End User: Specialty Clinics, Ambulatory Surgical Centers, Organ Transplant Centers, Research Institutions Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular, Inhalation |
| Companies Covered | Sanofi, Pfizer, Novartis AG, Viatris, Bristol-Myers Squibb, Roche, GlaxoSmithKline, Veloxis Pharmaceuticals, Astellas Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Transplant Immunosuppressant Drugs Market Strategic Shifts & Innovations
The market's evolution is defined by a dual focus. One path pursues breakthrough therapies like cell-based treatments, while the other concentrates on optimizing the delivery and personalization of existing, foundational drug classes to improve long-term outcomes.
Co-stimulation blockers represent a significant therapeutic advance, offering a more selective method of inhibiting T-cell activation compared to broadly acting calcineurin inhibitors. These biologics are being adopted for specific patient profiles in kidney transplantation where minimizing nephrotoxicity is a primary clinical goal. This targeted mechanism of action is integrating with established protocols, creating a multi-layered approach to preventing rejection while mitigating long-term side effects.
Regulatory frameworks are adapting to the complexity of new therapies. The European Medicines Agency's (EMA) specific pathways for Advanced Therapy Medicinal Products (ATMPs) provide clearer guidelines for the development of cell-based and gene-based immunosuppressive agents. This structure encourages investment in novel therapeutic modalities beyond conventional drugs, particularly affecting innovators in the biologics space who can now navigate a more defined route to market.
A clear shift toward personalized immunosuppression regimens, guided by pharmacogenomic testing, is gaining traction. Clinicians are increasingly using genetic markers to predict a patient's metabolic response to drugs like tacrolimus, a calcineurin inhibitor, thereby avoiding a one-size-fits-all dosing strategy. This trend is most visible within major academic transplant centers across North America and Europe, where advanced diagnostics are used to tailor therapy from the outset.
Organ Transplant Immunosuppressant Drugs Market Segmentation
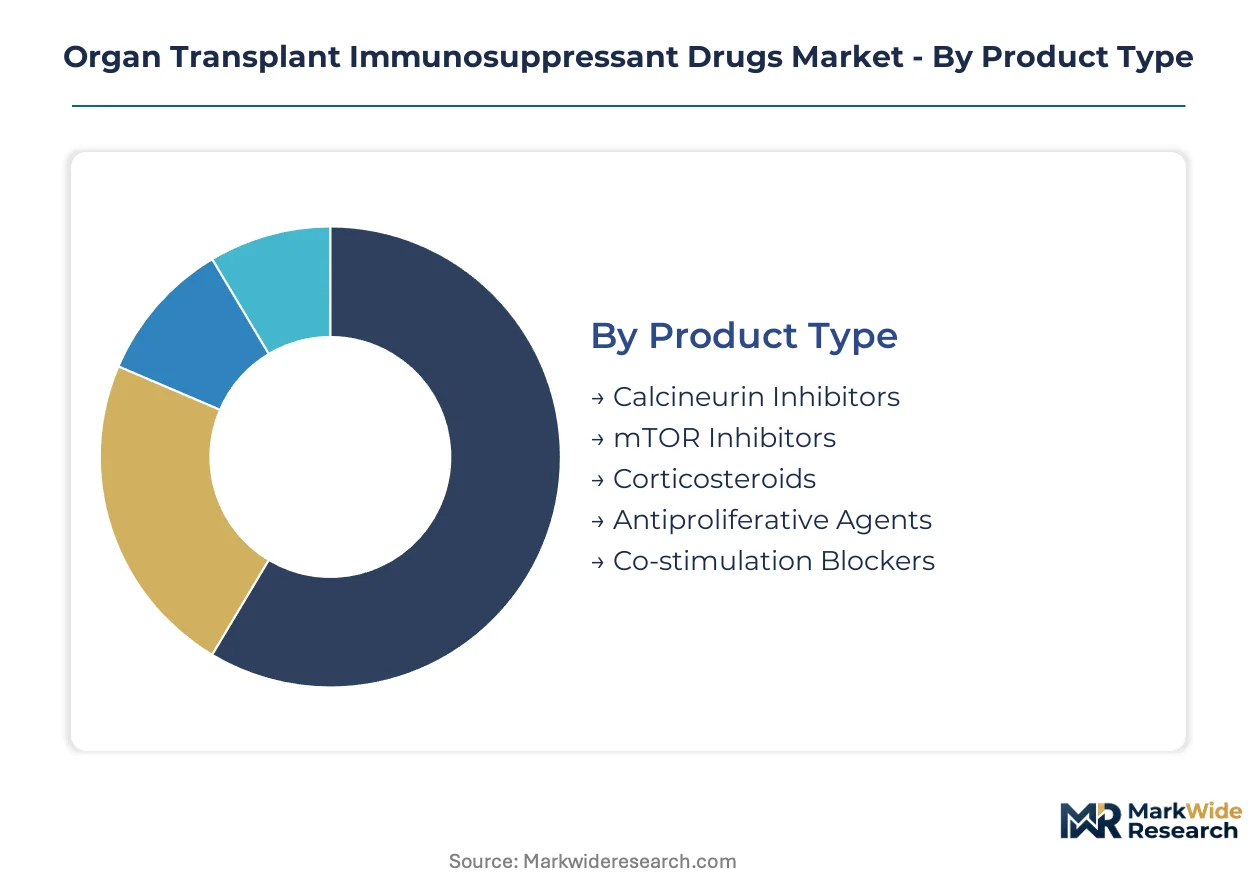
Segmentation analysis for organ transplant immunosuppressant drugs details the market's structure, revealing where innovation drives premium pricing and where established therapies maintain volume. This granular view helps identify specific growth pockets and competitive pressures across the therapeutic landscape.
Product Type:
The distinction between established and advanced therapies drives product type segmentation, reflecting ongoing innovation and replacement cycles.
- Calcineurin Inhibitors:These agents block T-cell activation by inhibiting the calcineurin enzyme, a crucial step in immune response. They remain foundational therapies, with significant demand in kidney and liver transplant protocols across Germany and Japan.
- Co-stimulation Blockers:These advanced biologics selectively inhibit T-cell co-stimulation pathways, offering targeted immunosuppression. Their adoption is growing in specific kidney transplantation patient profiles, where minimizing nephrotoxicity is a key clinical objective.
- mTOR Inhibitors:These drugs target the mammalian target of rapamycin pathway, preventing cell proliferation and modulating immune responses. They are often used in combination regimens to achieve optimal immunosuppression.
- Corticosteroids:Corticosteroids provide broad anti-inflammatory and immunosuppressive effects. Clinicians use them for induction therapy and to manage acute rejection episodes.
- Antiproliferative Agents:These agents inhibit lymphocyte proliferation, a critical component of the immune response. They are commonly integrated into multi-drug immunosuppressive regimens.
Volume placements concentrate in Calcineurin Inhibitors; the faster expansion belongs to Co-stimulation Blockers.
Application:
Application segmentation highlights the varying procedural volumes and clinical needs across different organ types.
- Kidney Transplant:This procedure involves replacing a diseased kidney with a healthy one, demanding long-term immunosuppression. Kidney transplants represent the largest volume segment for immunosuppressant drug consumption globally, particularly in developed nations with high incidence of end-stage renal disease.
- Liver Transplant:Replacing a diseased liver with a healthy donor organ constitutes a significant secondary market for these therapies. Complex immunosuppressive protocols are tailored to the unique immunological challenges of liver transplantation.
- Heart Transplant:Surgical replacement of a failing heart requires robust and lifelong immunosuppression to prevent rejection. These patients often receive complex multi-drug regimens.
- Lung Transplant:This procedure replaces diseased lungs; it presents unique challenges due to high rejection rates and susceptibility to infection. Immunosuppression protocols are highly specialized for lung transplant recipients.
- Pancreas Transplant:Often performed concurrently with kidney transplants for diabetic patients, this complex procedure requires specialized immunosuppression strategies. It addresses both endocrine and exocrine functions.
Kidney Transplant procedures generate the highest volume, with Liver Transplant applications showing significant secondary market activity.
End User:
The end-user landscape differentiates based on the specialized care settings required for transplant patients.
- Organ Transplant Centers:These specialized medical facilities perform transplant surgeries and provide intensive post-operative care. They serve as the primary point of drug administration and management for transplant recipients.
- Specialty Clinics:Specialty clinics offer long-term post-transplant follow-up and ongoing immunosuppressant management. These clinics play a crucial role in ensuring patient adherence and monitoring drug levels in countries like the United States and Canada.
- Ambulatory Surgical Centers:These outpatient facilities typically handle less complex surgical procedures. Their role in initial transplant care is limited, focusing more on minor interventions or diagnostics.
- Research Institutions:Research institutions conduct clinical trials and develop novel immunosuppressive strategies. They advance the understanding of rejection mechanisms and explore new therapeutic modalities.
Organ Transplant Centers remain the primary care providers, while Specialty Clinics ensure long-term patient management.
Administration Route:
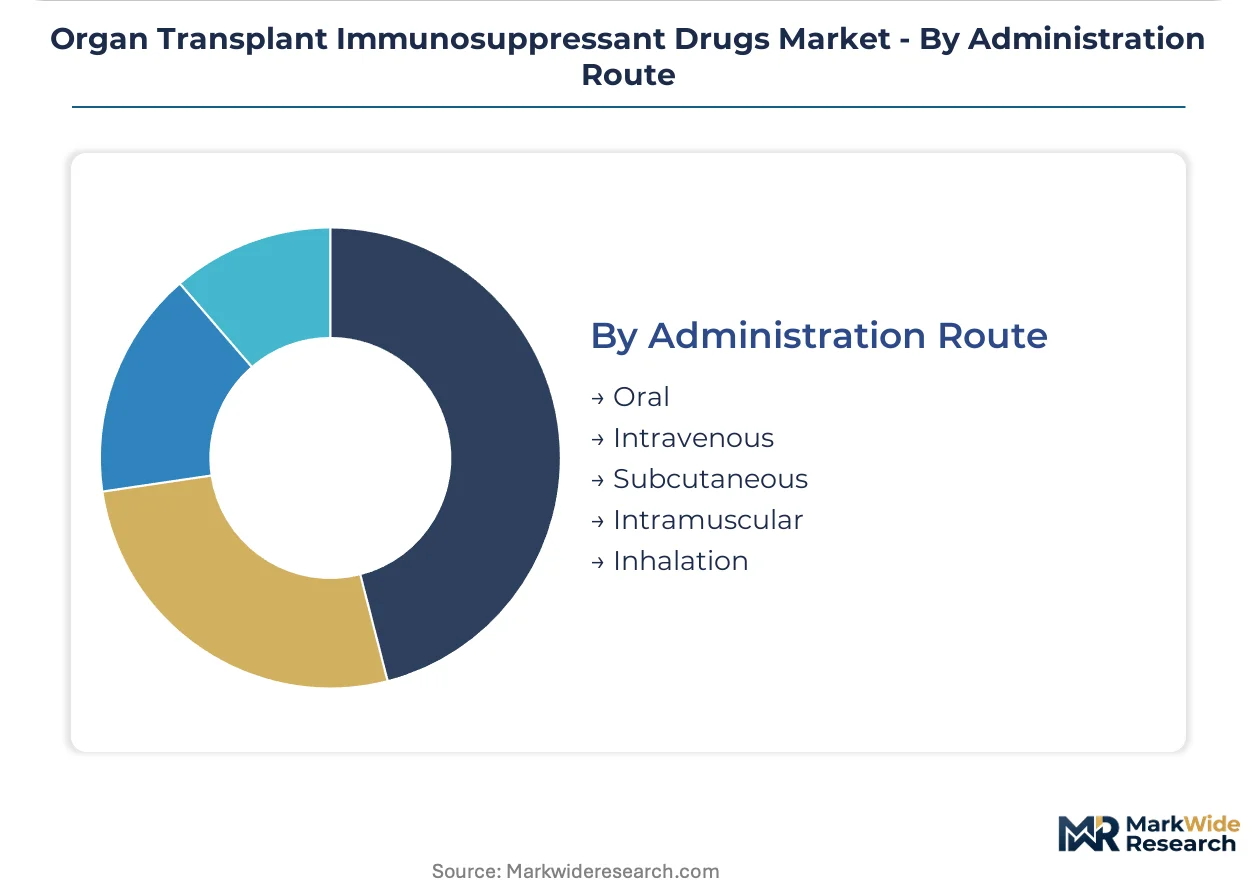
Administration route segmentation reflects the diverse delivery mechanisms optimizing patient adherence and therapeutic efficacy.
- Oral:Medications taken by mouth offer significant patient convenience for long-term maintenance therapy. This route is the primary method for daily immunosuppressant regimens.
- Intravenous:Administered directly into a vein, intravenous delivery is critical for rapid action during induction therapy or acute rejection episodes. This route ensures immediate systemic drug levels in hospital settings.
- Subcutaneous:Injected under the skin, subcutaneous administration offers an alternative for specific biologics. It can facilitate home administration for certain long-acting formulations, improving patient quality of life.
- Intramuscular:Injected into a muscle, this route is less common for chronic immunosuppression. It finds occasional use for certain drug formulations or specific patient needs.
- Inhalation:Delivered via the respiratory tract, inhalation is being explored for lung transplant patients. This route aims to target local immunity and potentially reduce systemic side effects.
Oral administration dominates for maintenance therapy, and Intravenous routes are critical for acute interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical centers and biotech clusters drive significant research into novel immunosuppressive therapies, anchoring North American innovation. This region benefits from a high volume of complex transplant procedures and robust healthcare infrastructure. Demand for advanced biologics is particularly strong in these specialized hubs.
United States
Demand for organ transplant immunosuppressants in the United States stems from high procedural volumes for kidney and liver transplants. The US FDA's rigorous approval processes encourage significant R&D investment in novel biologics. Major academic medical centers in cities like New York and Los Angeles lead clinical trials and advanced patient care, driving demand for premium therapies.
Germany
Germany's sophisticated healthcare system and aging population sustain a consistent demand for long-term immunosuppressive therapy, particularly for calcineurin inhibitors. The European Medicines Agency (EMA) sets stringent standards for drug approval, influencing market access for new treatments. Munich and Berlin host prominent research institutions and transplant centers, fostering innovation in patient management protocols.
Japan
Japan exhibits a concentrated demand for immunosuppressant drugs, driven by its advanced medical technology and demographic shifts. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug development, ensuring high safety and efficacy standards. Tokyo's leading university hospitals and research institutes are at the forefront of adopting personalized dosing regimens and advanced diagnostic tools.
France
France maintains a strong market for immunosuppressants due to its universal healthcare coverage and established transplant programs. National health policies prioritize patient access to essential medications, including foundational immunosuppressive agents. Paris and Lyon are key centers for pharmaceutical innovation and clinical research, contributing to the development of new therapeutic options.
Organ Transplant Immunosuppressant Drugs Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and market approach. This market structure is bifurcated between companies focused on developing high-cost, patented biologics and those specializing in volume-driven, off-patent small molecule generics. Innovation-focused firms pursue breakthrough therapies, while scale-focused participants optimize existing drug delivery. Strategic partnerships and life-cycle management are dominant competitive moves.
Specialists in advanced biologics and foundational therapies include Novartis AG, a Swiss-based pharmaceutical company that leverages its strong portfolio in mTOR and calcineurin inhibitors. Astellas Pharma, a Japanese company, occupies a position specializing in calcineurin inhibitors for specific transplant types. French-based Sanofi competes with a mix of established therapies and pipeline assets, aiming for broad market coverage across various immunosuppressant classes.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer |
| Novartis AG |
| Viatris |
| Bristol-Myers Squibb |
| Roche |
| GlaxoSmithKline |
| Veloxis Pharmaceuticals |
| Astellas Pharma |
| Others |
Cost & Logistics Intelligence
Stringent regulatory mandates for drug purity and sustainable manufacturing practices gate both qualified supply and premium-tier pricing access for organ transplant immunosuppressants. This ensures high-quality products reach transplant recipients.
Pricing Analysis
Patient outcome improvement serves as a primary value-based pricing anchor for novel immunosuppressants. Pricing stratifies across premium biologics and economy generics, reflecting innovation versus volume. Brand premium and FDA/EMA certification levels drive differentiation for patented therapies. Pricing softness runs through off-patent small molecules due to intense generic competition. Academic transplant centers and large hospital systems, focused on long-term patient care, are less price-sensitive for advanced biologics compared to smaller clinics managing maintenance therapies.
Supply Chain Analysis
FDA and EMA certifications gate market access for immunosuppressant drug manufacturers. Geographic supply concentration for active pharmaceutical ingredients (APIs) draws from India and China, while complex biologics often source from Switzerland and the United States. Key raw material dependencies include specialized chemical precursors and cell culture media. Single-source vulnerability for specific APIs remains a structural supply chain risk. Distribution runs through a network of specialized pharmaceutical distributors and direct channels to organ transplant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intensifying generic erosion is driving market consolidation, as smaller firms struggle to compete on volume-driven pricing. This environment favors strategic players with diversified portfolios.
For Market Incumbents: Extend patent life through novel formulations and indication expansion, particularly for established calcineurin inhibitors. Invest in advanced biologics R&D to counter biosimilar competition and maintain a premium market position. Focus on life-cycle management strategies to defend market share against generic erosion, especially in developed markets like Germany and Japan. Pursue clinical trial investments for less common transplant types to secure new revenue streams.
For New Entrants and Emerging Players: The European Medicines Agency's (EMA) ATMP pathways in Europe open a window for cell-based immunosuppressive therapies. Target underserved transplant applications, such as lung or intestinal transplants, where unmet clinical needs are substantial. A go-to-market angle focused on personalized dosing regimens, guided by pharmacogenomic testing, offers a path to premium pricing. Focus on specific patient cohorts that benefit from targeted immunosuppression, minimizing broad-spectrum side effects.
For Investors and Strategic Acquirers: Successful Phase III trial completion for a novel biologic is the leading indicator that significant market shifts are imminent. The market maintains long-term viability over a 5-10 year window, driven by an aging global population and increasing transplant volumes. Acquisition target archetypes include companies with promising biologics pipelines or advanced diagnostic capabilities for personalized medicine. Regulatory approvals for co-stimulation blockers in new indications serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expands therapeutic options and targets specific patient populations for improved outcomes. |
| Manufacturing Scale-Up | Ensures reliable supply of novel biologics to meet increasing global patient demand. |
| Licensing Agreement | Accelerates market penetration for innovative therapies through established distribution networks. |
| Pipeline Diversification | Reduces reliance on single drug classes and broadens treatment coverage across transplant types. |
| Personalized Dosing Platform | Optimizes patient treatment, reduces side effects, and justifies premium pricing for targeted care. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by comprehensive primary research. Interviews with transplant surgeons, R&D executives, hospital procurement managers, and regulatory affairs specialists provided critical market insights. This approach facilitated robust bottom-up and top-down triangulation to validate market size and growth projections.
Market segmentation across product type, application, end user, and administration route formed the basis for granular modeling. Patient demographics and transplant procedural volumes were integrated as industry-specific dimensions over the analysis window. Compound annual growth rates were derived from historical trends and projected future demand, considering factors like drug patent expirations and new product launches.
The model assumes a particular technology adoption path; alternative pathways for cell-based therapies would alter the outlook. Forecasts reflect assumptions regarding clinical trial success rates and regulatory policy shifts. A model refresh is warranted upon material change in global transplant volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Omeprazole Market