
 Paediatric Sports Medicine Market | 2026-2036
Paediatric Sports Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric Sports Medicine Market Analytics
Hospital procurement departments are collapsing as the dominant buyer archetype as sports academies and dedicated paediatric clinics gain purchasing share. Arthrex specializes in arthroscopic systems sized for adolescent anatomy, sustaining its position through instrument miniaturisation. Stryker Corporation dominates orthopaedic implant portfolios with paediatric-specific trauma hardware, while Smith & Nephew plc competes through advanced wound care protocols tailored to younger healing profiles.
Paediatric sports medicine encompasses the diagnosis, treatment, and prevention of musculoskeletal injuries in athletes under eighteen years, employing biomechanically adapted instruments with smaller working channels and lower insertion forces than adult equivalents. Bracing solutions lead product type revenue due to recurring replacement cycles tied to growth spurts, while performance monitors represent the fastest-expanding category as wearable sensor accuracy improves for developing bodies. Rehabilitation applications anchor clinical service volumes, though injury prevention programming is displacing reactive care models among elite youth academies.
The FDA's Humanitarian Device Exemption pathway and the EU MDR's stricter clinical evaluation requirements for paediatric indications are extending product development timelines and raising capital barriers for entrants. ISO 13485 quality management standards and ASTM F08 sports equipment committees shape material safety benchmarks for devices contacting immature bone and cartilage. Stakeholders must monitor how regulatory divergence between the United States and European Union affects portfolio rationalisation decisions for adolescent-specific product lines.
Market Dynamics
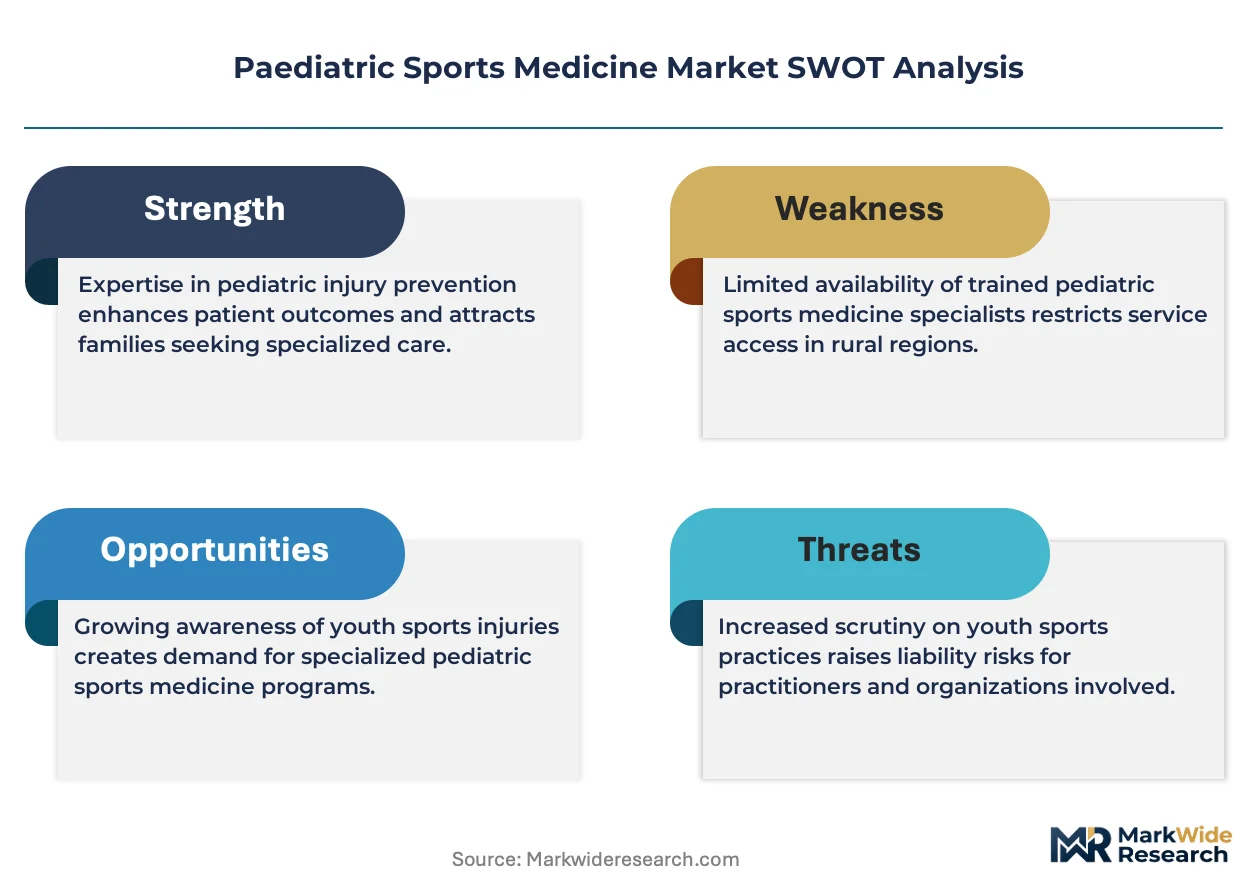
Early-age athletic specialization is compressing injury onset timelines and forcing biomechanical adaptation of surgical instruments designed for immature anatomy, while regulatory divergence between FDA paediatric device pathways and EU MDR clinical evidence requirements fragments product development strategies.
Growth Catalysts
- Youth Academy Expansion:Structured training programmes in the United States, Germany, and Australia are enrolling athletes below age twelve, generating demand for age-appropriate bracing and monitoring systems.
- Wearable Sensor Maturation:Accelerometer and gyroscope calibration for adolescent gait patterns enables real-time load monitoring during growth spurts, preventing overuse injuries before surgical intervention.
- FDA Humanitarian Device Exemption:This pathway accelerates market access for rare paediatric conditions, incentivizing manufacturers to address anatomically specific trauma hardware gaps.
Market Restraints
- Titanium Alloy Cost Volatility:Raw material price swings for implant-grade Ti-6Al-4V compress margins on paediatric trauma plates designed for temporary fixation prior to skeletal maturity.
- European Contract Manufacturer Concentration:Sterile packaging and final assembly for EU-bound devices clusters in Ireland and Switzerland, exposing supply chains to single-site regulatory audit failures.
- Bioresorbable Screw Degradation Uncertainty:Variable resorption rates in adolescent bone create liability exposure that slows clinical adoption of polymer-based fixation alternatives.
Strategic Opportunities
- Brazilian Private Sports Medicine Clinics:Underpenetrated outpatient networks in São Paulo and Rio de Janeiro lack dedicated adolescent orthopaedic capacity, creating first-mover advantages for equipment suppliers.
- Tele-rehabilitation Protocols:Remote physiotherapy platforms combined with home-based motion capture reduce travel burdens on rural families managing post-surgical recovery.
- Japan's Sports Agency Subsidies:METI-funded injury prevention mandates for school athletic associations create procurement tailwinds for performance monitoring wearables.
Industry Challenges
- Paediatric Orthopaedic Surgeon Scarcity:Fellowship-trained specialists capable of arthroscopic procedures on adolescent anatomy remain concentrated in major metropolitan academic centres, limiting procedure volume expansion.
- ISO 13485 Certification Timelines:Quality management audits for paediatric-specific device lines extend six to nine months longer than adult equivalents due to additional biocompatibility documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric Sports Medicine Market |
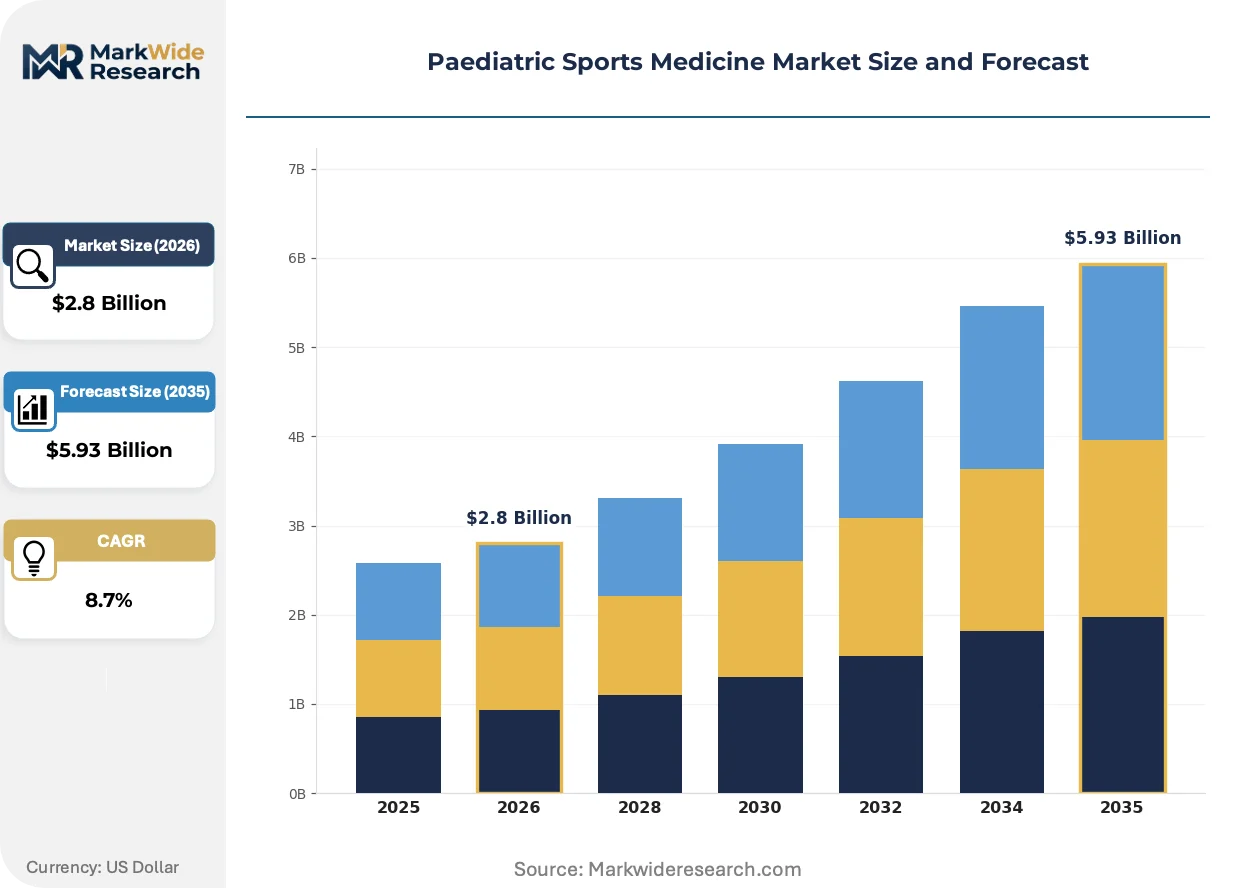
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rehabilitation Equipment, Physiotherapy Devices, Performance Monitors, Bracing Solutions Application: Injury Prevention, Performance Enhancement, Rehabilitation, Fitness Testing End User: Clinics, Hospitals, Sports Academies, Fitness Centers Service Type: Therapeutic Services, Coaching Services, Training Programs, Nutritional Counseling |
| Companies Covered | Stryker Corporation, Smith & Nephew plc, Arthrex, Inc., Zimmer Biomet Holdings, Inc., CONMED Corporation, Johnson & Johnson, Medtronic plc, Mueller Sports Medicine, Inc., Össur hf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric Sports Medicine Market Evolving Landscape
Three interconnected shifts are restructuring competitive advantage: instrument miniaturisation, regulatory evidence escalation, and the migration of care delivery from hospital settings to dedicated youth sports facilities.
Patient-specific 3D-printed surgical guides calibrated to adolescent CT scans are supplanting standard arthroscopic entry portals in complex knee reconstruction cases. Elite youth academies in the United States and Australia are adopting these guides for anterior cruciate ligament procedures on skeletally immature athletes. This technology is compressing operative time and reducing revision rates, shifting procurement criteria toward digital surgical planning capabilities.
The EU Medical Device Regulation's stricter clinical evaluation requirements for paediatric indications are extending notified body review timelines by twelve to eighteen months for novel implant submissions. Manufacturers must now generate prospective paediatric cohort data rather than extrapolating from adult trials, raising capital requirements for product development. Small and mid-sized portfolio holders are responding by prioritising CE-marked adult devices with off-label paediatric use over dedicated adolescent line extensions.
Hospital outpatient departments are losing surgical volume to dedicated paediatric sports medicine clinics operated by orthopaedic group practices. These clinics bundle imaging, bracing, and rehabilitation under single-site contracts that bypass traditional hospital procurement committees. This consolidation is most visible in suburban United States markets where high school sports participation density supports standalone facility economics.
Paediatric Sports Medicine Market Segmentation
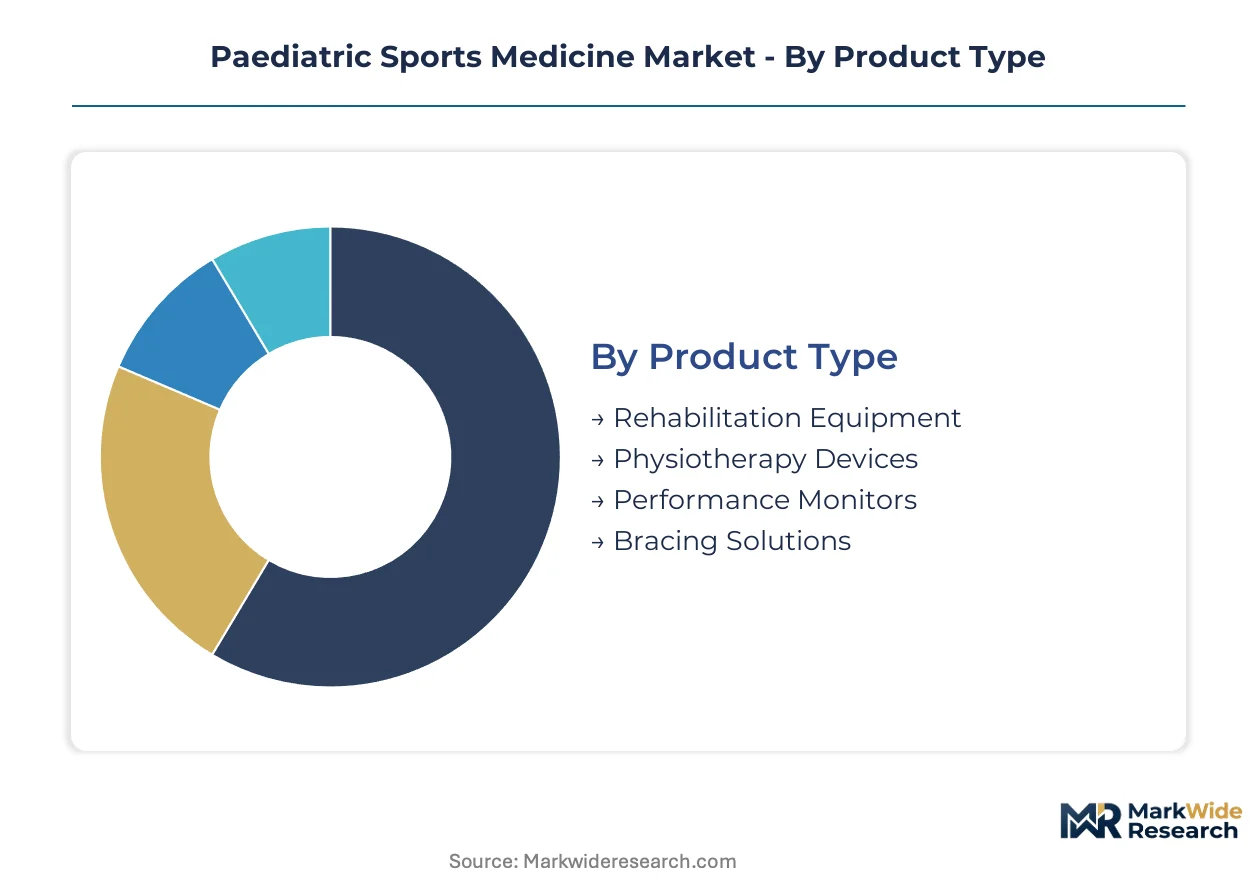
Segmentation in paediatric sports medicine reveals divergent growth vectors between hardware-intensive product lines and service-based delivery models. Understanding substitution dynamics across these boundaries determines portfolio allocation for manufacturers and care providers alike.
Product Type:
Substitution pressure runs strongest through wearable-enabled categories where software analytics displace standalone hardware, while capital-intensive equipment faces longer replacement cycles tied to facility budgets.
- Bracing Solutions:Orthotic systems incorporate adjustable polypropylene frames and moisture-wicking interfaces sized for adolescent limb circumference ranges. Demand clusters in United States high school athletic departments and German youth football academies where growth-spurt-related replacement drives recurring procurement.
- Performance Monitors:Accelerometer- and gyroscope-based wearables calibrated for adolescent gait patterns transmit load data to coaching staff in real time. Australian cricket academies and Japanese school athletic associations represent concentrated adoption as injury prevention mandates tighten.
- Rehabilitation Equipment:Range-of-motion devices and resistance systems adapted for paediatric anthropometrics.
- Physiotherapy Devices:Ultrasound and electrical stimulation units with paediatric-specific output limits.
Bracing Solutions anchors the volume base while Performance Monitors gains share at the steepest rate.
Application:
Cost tier stratification separates institutional purchasers investing in preventive infrastructure from reactive care budgets constrained by insurance reimbursement.
- Injury Prevention:Biomechanical screening protocols and load management algorithms identify at-risk movement patterns before tissue damage occurs. Elite United States soccer academies and Australian swimming institutes deploy these systems to reduce surgical intervention rates among skeletally immature athletes.
- Rehabilitation:Post-surgical protocols combining manual therapy with instrumented outcome measurement restore function after ACL reconstruction or shoulder instability repair. Hospital outpatient departments in suburban United States markets and dedicated paediatric orthopaedic clinics in Germany concentrate service volume.
- Performance Enhancement:Strength and conditioning programming optimized for adolescent development windows.
- Fitness Testing:Standardized assessment batteries for talent identification and return-to-play clearance.
Rehabilitation commands the largest current spend while Injury Prevention climbs the fastest as academies shift from reactive to predictive care models.
End User:
Customer type migration is concentrating purchasing power outside traditional hospital procurement committees.
- Sports Academies:Dedicated youth training facilities bundle imaging, bracing, and rehabilitation under single-site contracts that bypass hospital supply chains. United States suburban markets with high school sports density and Brazilian private academies in São Paulo represent expansion frontiers.
- Clinics:Orthopaedic group practices operating standalone paediatric sports medicine centres capture surgical volume previously routed through hospital outpatient departments. These entities negotiate direct with device manufacturers, compressing distributor margins.
- Hospitals:Academic medical centres with fellowship-trained paediatric orthopaedic surgeons.
- Fitness Centers:Commercial gyms adding adolescent athletic development programming.
Hospitals retain the procedural volume base while Sports Academies expands most quickly as care delivery decentralizes.
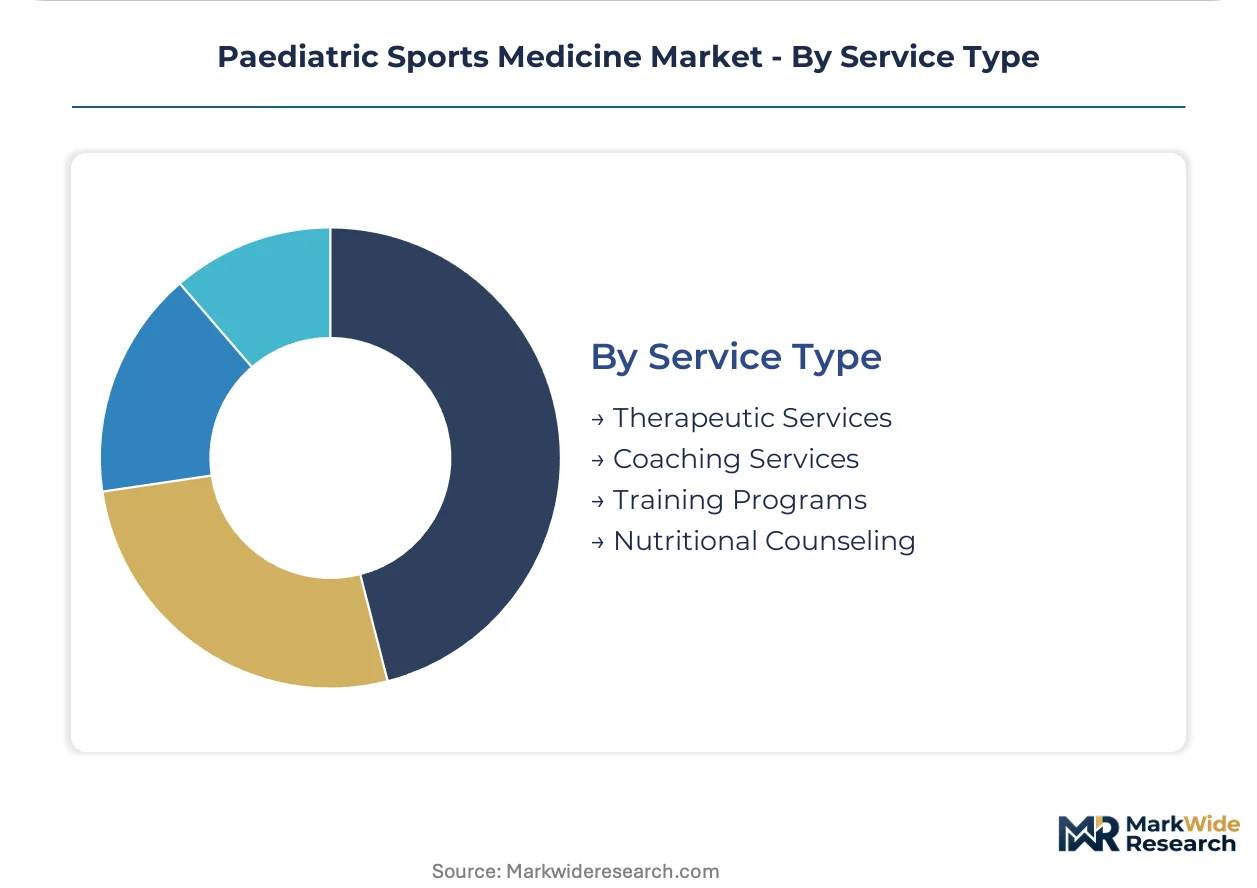
Service Type:
Margin structure varies sharply between reimbursed therapeutic interventions and discretionary coaching engagements.
- Therapeutic Services:Physiotherapy and athletic training delivered by licensed professionals carries insurance eligibility and recurring revenue potential. United States clinic networks and German rehabilitation centres dominate this segment through contracted relationships with youth sports leagues.
- Training Programs:Structured athletic development curricula combine technical skill instruction with physical preparation. Australian institute programmes and Japanese school-based initiatives demonstrate scalability through standardized curriculum deployment.
- Coaching Services:Individual and small-group technical instruction.
- Nutritional Counseling:Dietary planning for adolescent athletes with growth and performance objectives.
Therapeutic Services underpins revenue stability while Training Programs scales fastest through digital delivery platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth medical corridor anchors United States paediatric orthopaedic capacity through its concentration of fellowship-trained surgeons and dedicated adolescent sports medicine centres. This infrastructure underwrites North American demand leadership.
United States
High school athletic departments in Texas and California drive bracing solution procurement through mandatory injury prevention mandates. The FDA's Humanitarian Device Exemption pathway accelerates market access for rare paediatric conditions. Suburban Atlanta and Phoenix clinic networks capture surgical volume previously routed through hospital outpatient departments.
Germany
Youth football academies in Bavaria and North Rhine-Westphalia generate concentrated demand for age-appropriate arthroscopic systems. The EU Medical Device Regulation's stricter clinical evaluation requirements extend notified body review timelines for novel implant submissions. Munich's orthopaedic device cluster hosts specialised manufacturers serving adolescent trauma hardware gaps.
Australia
Cricket and swimming institutes in New South Wales and Victoria deploy wearable load monitoring systems for skeletally immature athletes. The Therapeutic Goods Administration (TGA) maintains alignment with ISO 13485 quality management standards for devices contacting immature bone. Sydney's sports medicine corridor bundles imaging, bracing, and rehabilitation under single-site academy contracts.
Japan
METI-funded injury prevention mandates for school athletic associations create procurement tailwinds for performance monitoring wearables in Kanto and Kansai regions. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees paediatric-specific device approvals through JIS standards compliance. Osaka's rehabilitation equipment manufacturers supply standardised assessment batteries for talent identification programmes.
Brazil
Private sports medicine clinics in São Paulo and Rio de Janeiro lack dedicated adolescent orthopaedic capacity, creating first-mover advantages for equipment suppliers. ANVISA regulates medical device imports through simplified registration pathways for established international manufacturers. The São Paulo metropolitan corridor concentrates purchasing power among outpatient networks bypassing traditional hospital procurement.
Paediatric Sports Medicine Market Competitive Landscape
Concentration sits with diversified orthopaedic conglomerates possessing paediatric-specific trauma hardware portfolios and dedicated instrument miniaturisation capabilities. The vendor base stratifies across three tiers: multinational implant manufacturers with adolescent line extensions, specialised arthroscopy firms with anatomy-calibrated systems, and regional bracing specialists with growth-adjustable orthotic platforms. Dominant competitive moves include portfolio diversification into wearable-enabled monitoring categories and strategic partnerships with elite youth academies for clinical validation data.
Within the diversified orthopaedic tier, Stryker Corporation and Zimmer Biomet Holdings occupy positions exemplifying scale-driven coverage of trauma hardware gaps. Smith & Nephew plc represents the wound care and sports medicine specialization vector. Arthrex, Inc. anchors the arthroscopy-focused archetype with instrument miniaturisation capabilities sized for adolescent anatomy. These three entities collectively illustrate the competitive structure: conglomerate breadth, procedural specialization, and anatomical calibration each command distinct procurement relationships with decentralising care delivery networks.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew plc |
| Arthrex, Inc. |
| Zimmer Biomet Holdings, Inc. |
| CONMED Corporation |
| Johnson & Johnson |
| Medtronic plc |
| Mueller Sports Medicine, Inc. |
| Össur hf |
| Others |
Value Network & Pricing Analysis
Bioresorbable polymer substitution for titanium alloy fixation hardware is redrawing procurement geography toward Swiss and German polymer compounders while compressing premium-tier implant margins through raw material cost volatility. Sports academies and dedicated paediatric clinics now command volume leverage that hospital procurement departments once held, forcing manufacturers to restructure discount tiering around academy network scale rather than institutional purchasing consortiums.
Pricing Analysis
Volume-discount tiering separates elite youth academy networks from standalone paediatric clinics and individual hospital purchasers. Pricing stratifies across premium, standard, and economy tiers differentiated by ISO 13485 certification grade and after-sales service bundling including surgical training and instrument maintenance. Cost compression in the economy tier is intensifying because Brazilian and Australian distributors are consolidating purchasing power through multi-academy contracts. Sports academies exhibit the highest price sensitivity due to capital constraints on standalone facility economics, while academic medical centres with fellowship-trained surgeons demonstrate lowest sensitivity given reimbursement capture and research funding offsets.
Supply Chain Analysis
Inventory lead times for adolescent-specific arthroscopic instruments extend six to nine months beyond adult equivalents due to additional biocompatibility documentation and sterilization validation cycles. Manufacturing concentrates in Switzerland, Germany, and the United States for precision-machined titanium components and polymer compounding. Raw material dependencies draw from implant-grade Ti-6Al-4V suppliers, medical-grade polypropylene resin producers, and sensor-grade accelerometer foundries. Single-source vulnerability concentrates in Irish and Swiss sterile packaging facilities where EU MDR audit failures could disrupt EU-bound device flows. Distribution runs through orthopaedic group purchasing organizations in North America and direct manufacturer relationships with academy networks in Australia and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where remote physiotherapy platforms and wearable data analytics subscriptions expand faster than hardware replacement cycles, creating recurring revenue streams that hardware margins alone cannot match.
For Market Incumbents: Consolidate control over digital surgical planning capabilities and academy validation partnerships to defend against specialized arthroscopy firms capturing volume through patient-specific 3D-printed guide technology. Backward integration into polymer compounding for bioresorbable screws reduces titanium cost exposure while securing supply continuity. Channel control through exclusive academy network contracts limits distributor margin compression.
For New Entrants and Emerging Players: Anchor in Brazilian private sports medicine clinics in São Paulo and Rio de Janeiro where dedicated adolescent orthopaedic capacity remains underdeveloped and first-mover positioning is achievable. Tele-rehabilitation protocols combined with home-based motion capture represent the most penetrable application layer, addressing rural family travel burdens with software-centric delivery models.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional bracing specialists possessing growth-adjustable orthotic platforms and established academy relationships. Long-term viability hinges on recurring replacement cycles tied to adolescent growth spurts and prevention-mandate policy tailwinds. Monitor FDA paediatric device pathway expansion and EU MDR notified body capacity as inflection indicators for development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR's stricter clinical evaluation requirements extend notified body review timelines for novel paediatric implants. |
| Hospital System Partnership | Orthopaedic group practices operating standalone paediatric sports medicine centres bypass traditional hospital procurement committees. |
| Software Companion Development | Remote physiotherapy platforms reduce travel burdens on rural families managing post-surgical recovery. |
| Reimbursement Strategy | Therapeutic services carry insurance eligibility that training programs and coaching services cannot access. |
| Academy Validation Partnership | Elite youth academies in Texas and California provide clinical validation data for FDA Humanitarian Device Exemption submissions. |
Research Methodology
Operator-level perspectives from paediatric orthopaedic surgeons, sports academy medical directors, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up academy network sizing and top-down orthopaedic device market triangulation cross-checked volume assumptions.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios and raw material cost volatility assumptions over the projection horizon. Segmentation dimensions modeled include product type, application, end user, and service type alongside regional regulatory cluster differentiation. CAGRs were derived from academy enrollment growth rates, procedure volume expansion, and wearable adoption curves specific to adolescent athletic populations.
Material uncertainties — FDA paediatric device pathway reforms, EU MDR notified body capacity constraints, titanium alloy price swings, and bioresorbable screw degradation liability exposure — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and academy network expansion that external shocks could revise. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Global Tourette Syndrome Treatment Market