
 Global Specialty Injectable Generics Market | 2026-2036
Global Specialty Injectable Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Injectable Generics Market Foresight
The EU Green Deal is decoupling pharmaceutical manufacturing from carbon-intensive supply chains, forcing injectable generics producers to revalidate cold-chain logistics and packaging standards. Fresenius Kabi leverages its European fill-finish network to sustain compliance with tightened EMA environmental guidelines. Teva Pharmaceutical Industries anchors its competitive position through backward integration into active pharmaceutical ingredient production for complex parenterals.
Specialty injectable generics are sterile, bioequivalent formulations of complex drugs administered via intravenous, intramuscular, or subcutaneous routes, requiring aseptic processing, endotoxin control, and particulate matter thresholds below USP <788> limits; their primary purpose is to reduce therapy costs for biologics, oncology agents, and critical-care medicines while maintaining therapeutic equivalence. Lyophilized injectables command premium margins due to stability requirements and limited manufacturing capacity, while oncology within the therapy area dimension absorbs the largest share of development investment as patent cliffs for monoclonal antibodies deepen. Hospital pharmacies dominate distribution channels because of cold-chain custody requirements and restricted drug handling protocols that retail and online channels cannot replicate at scale.
FDA, EMA, and WHO prequalification standards collectively govern market access, with FDA's Complex Generic Guidance and EMA's biosimilar framework creating divergent evidentiary demands that shape regional filing strategies and development costs. India's CDSCO has aligned with ICH Q5B and Q5D guidelines for biologics-related injectables, tightening local manufacturing standards for export-oriented producers. Stakeholders must monitor how FDA's forthcoming product-specific guidance for peptide injectables reshapes ANDA filing requirements and manufacturing investment thresholds.
Market Dynamics
The FDA's Complex Generic Guidance is compressing development timelines for peptide and oligonucleotide injectables, while EMA environmental mandates force simultaneous revalidation of cold-chain infrastructure. This dual regulatory pressure is reshaping capital allocation across sterile manufacturing networks.
Growth Catalysts
- Patent cliff acceleration:Monoclonal antibody exclusivity expirations are expanding the addressable biosimilar pipeline. Hospital formularies in the United States are accelerating therapeutic substitution protocols.
- EMA Green Deal compliance:Tightened carbon accounting for pharmaceutical logistics is favoring producers with European fill-finish assets. Cold-chain revalidation creates compliance moats for early adopters.
- Lyophilization capacity scarcity:Limited aseptic lyophilization lines command premium pricing for stable injectable formulations. Oncology supply contracts increasingly specify endotoxin-controlled manufacturing.
Market Restraints
- API supply concentration:China and India dominate starting material production for complex parenterals. Geopolitical friction threatens just-in-time sourcing for European and North American fill-finish sites.
- Regulatory divergence costs:FDA peptide guidance and EMA biosimilar frameworks demand non-overlapping evidentiary packages. Dual filing strategies inflate development budgets without parallel market access.
- Substitution ceiling effects:Critical-care injectables face prescriber resistance despite bioequivalence certification. Physician familiarity with reference products slows volume conversion.
Strategic Opportunities
- German reference pricing expansion:AMNOG assessments are widening specialty pharmacy networks for biosimilar oncology injectables. Hospital procurement consortia consolidate purchasing power.
- Continuous manufacturing adoption:FDA Emerging Technology Program approvals for aseptic processing reduce batch failure rates. Real-time release testing compresses quality control timelines.
- Pre-filled syringe standardization:Combination product pathways for self-administered biologics open retail channel access. Rheumatology and endocrinology applications bypass hospital custody requirements.
Industry Challenges
- Aseptic processing talent scarcity:Qualified personnel for isolator technology and barrier systems command wage premiums. Training pipelines lag capacity expansion timelines.
- Legacy equipment integration:Automated visual inspection systems require retrofitting of established fill-finish lines. Capital deployment conflicts with short-cycle ANDA filing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Injectable Generics Market |
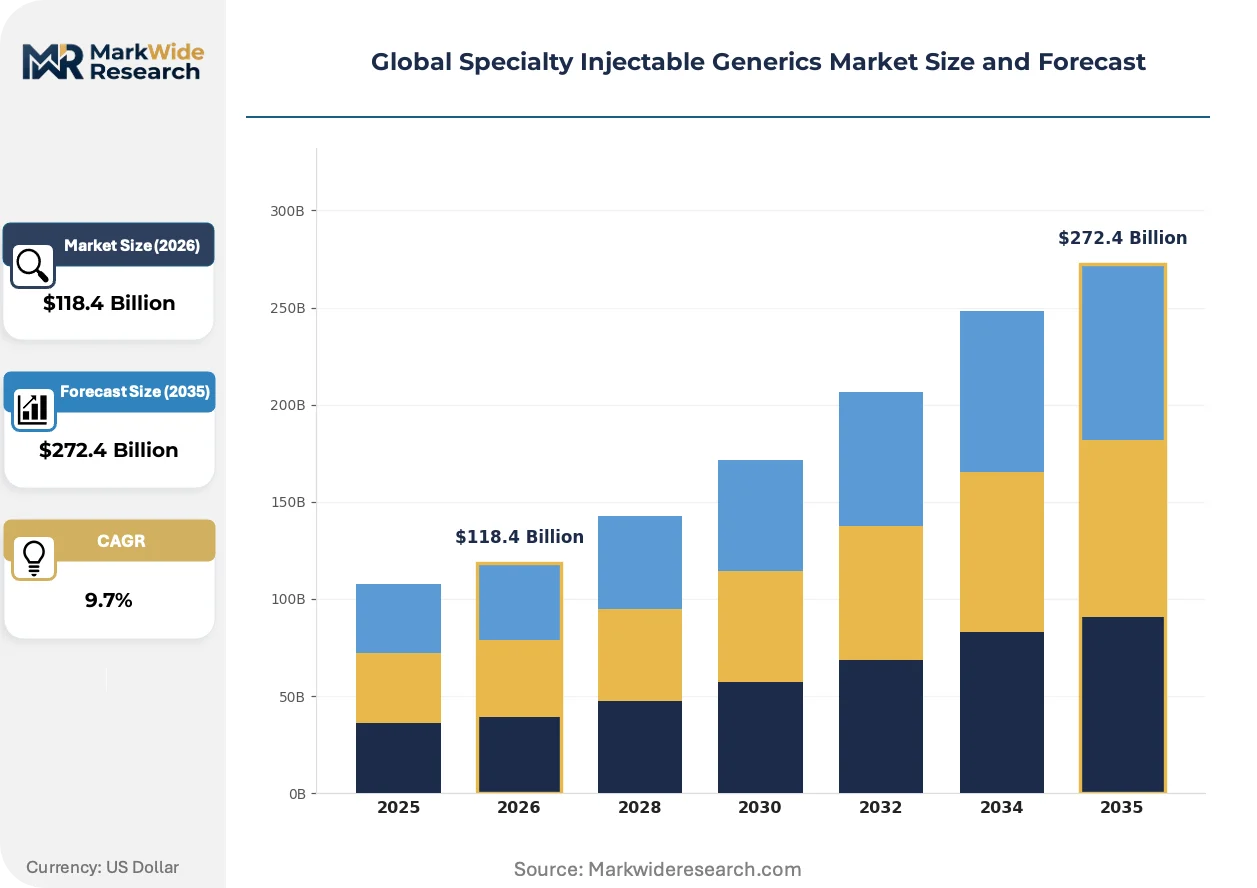
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $272.4 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solutions, Injectable Suspensions, Injectable Emulsions, Lyophilized Injectables, Depot Injectables Therapy Area: Oncology, Endocrinology, Cardiology, Neurology, Immunology, Rheumatology End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Ambulatory Care Centers, Home Healthcare Providers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors, Direct-to-Physician |
| Companies Covered | Fresenius Kabi, Teva Pharmaceutical Industries, Pfizer, Novartis AG, Hikma Pharmaceuticals, Baxter International, Dr. Reddy’s Laboratories, Sagent Pharmaceuticals, Sun Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Injectable Generics Market Shifts & Advancements
Single-use technologies and closed-system processing are displacing stainless-steel infrastructure across sterile injectable manufacturing. These shifts reduce cross-contamination risk while enabling faster product changeovers.
Modular aseptic processing skids are modularizing facility design for multi-product injectable sites. Contract manufacturers in India and Germany are adopting these platforms to reduce qualification timelines. The technology is modularizing capital deployment, allowing producers to scale capacity in 12-month increments rather than 36-month greenfield cycles.
EMA's F-Gas Regulation is phasing out hydrofluorocarbon propellants in metered-dose applications, forcing reformulation of certain respiratory injectables. Industrial gas suppliers are accelerating investment in low-global-warming-potential alternatives. Lyophilized oncology formulations face the steepest reformulation costs due to stability validation requirements.
Hospital pharmacy consolidation is compressing supplier rosters for high-value oncology injectables. Integrated delivery networks in the United States are centralizing purchasing through specialty pharmacy carve-outs. This concentration is most visible in Texas and Florida, where health system mergers have reduced qualified vendor pools by half.
Global Specialty Injectable Generics Market Segmentation
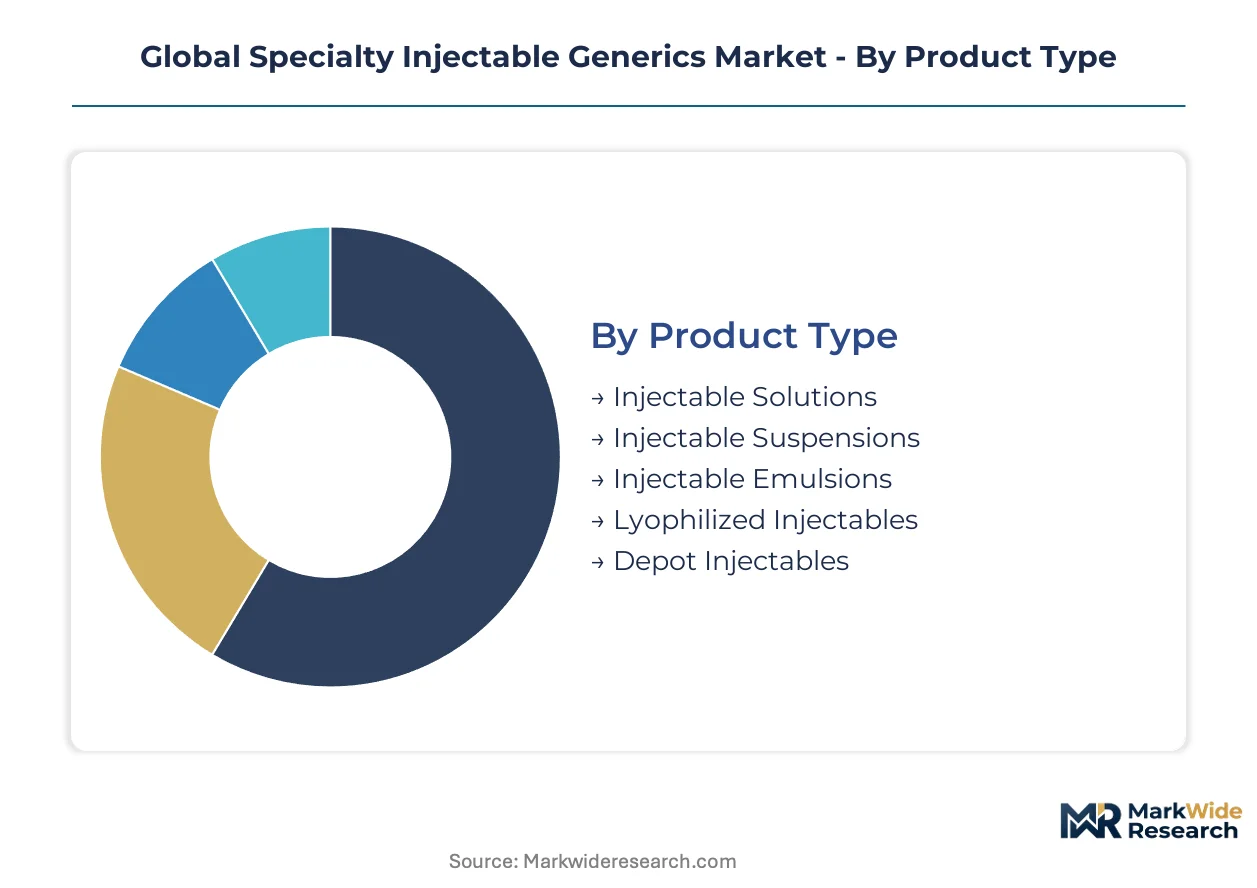
Segmentation in specialty injectable generics reveals how formulation complexity, therapy criticality, and custody requirements fragment commercial pathways. Each dimension carries distinct regulatory burdens and margin structures that reshape competitive positioning across sterile manufacturing networks.
Product Type:
Customization intensity spans from ready-to-use solutions requiring minimal reconstitution to depot formulations demanding sophisticated release engineering.
- Lyophilized Injectables:Freeze-dried formulations requiring aseptic reconstitution prior to administration. Oncology supply contracts in Germany and the United States increasingly mandate endotoxin-controlled lyophilization lines, with capacity scarcity commanding premium pricing.
- Injectable Solutions:Ready-to-administer liquid formulations with the shortest preparation time. Hospital pharmacies in India prioritize these for emergency protocols, though cold-chain custody requirements limit retail channel penetration.
- Injectable Suspensions:Particulate-laden formulations requiring resuspension validation. CDSCO tightened particulate matter thresholds for export-oriented producers.
- Injectable Emulsions:Lipid-based delivery systems for hydrophobic APIs. Stability validation costs concentrate production among European fill-finish specialists.
- Depot Injectables:Extended-release formulations using polymer matrices. Rheumatology applications in the United States drive demand for monthly dosing intervals.
Leading the category by volume: Injectable Solutions. Growing fastest: Lyophilized Injectables.
Therapy Area:
Cost tier stratification separates acute intervention therapies from chronic management protocols with divergent pricing power.
- Oncology:Cytotoxic and supportive-care injectables for cancer treatment. Monoclonal antibody patent cliffs are expanding biosimilar pipelines, with AMNOG assessments in Germany accelerating therapeutic substitution.
- Immunology:Biologics for autoimmune modulation. Pre-filled syringe standardization is opening retail channel access, bypassing hospital custody requirements.
- Endocrinology:Hormone replacement and diabetes management injectables. Home healthcare adoption in the United States is shifting volume toward self-administration models.
- Cardiology:Critical-care agents for acute cardiovascular events. Prescriber resistance to substitution persists despite bioequivalence certification.
- Neurology:Injectable therapies for seizure disorders and neurodegenerative conditions. Limited manufacturing capacity constrains supply security.
- Rheumatology:Anti-inflammatory biologics for joint disease. Subcutaneous formulation development is reducing infusion center dependency.
Climbing the fastest: Oncology. Generating highest per-unit margins: Immunology.
End User:
Customer type determines custody sophistication, with acute-care settings demanding validated cold-chain infrastructure that ambulatory and home settings cannot replicate.
- Hospitals:Integrated delivery networks with centralized pharmacy operations. Texas and Florida health system mergers have reduced qualified vendor pools by half.
- Specialty Clinics:Focused infusion centers for oncology and immunology. These facilities concentrate high-value biologic administration outside acute-care settings.
- Home Healthcare Providers:Nursing services for subcutaneous and intramuscular administration. Pre-filled syringe adoption is expanding addressable therapy categories.
- Diagnostic Laboratories:Imaging agent and contrast media consumers. Batch size requirements differ from therapeutic dosing protocols.
- Ambulatory Care Centers:Same-day surgical and procedural facilities. Limited on-site pharmacy infrastructure restricts formulary breadth.
Highest volume concentration: Hospitals. Expanding most quickly: Home Healthcare Providers.
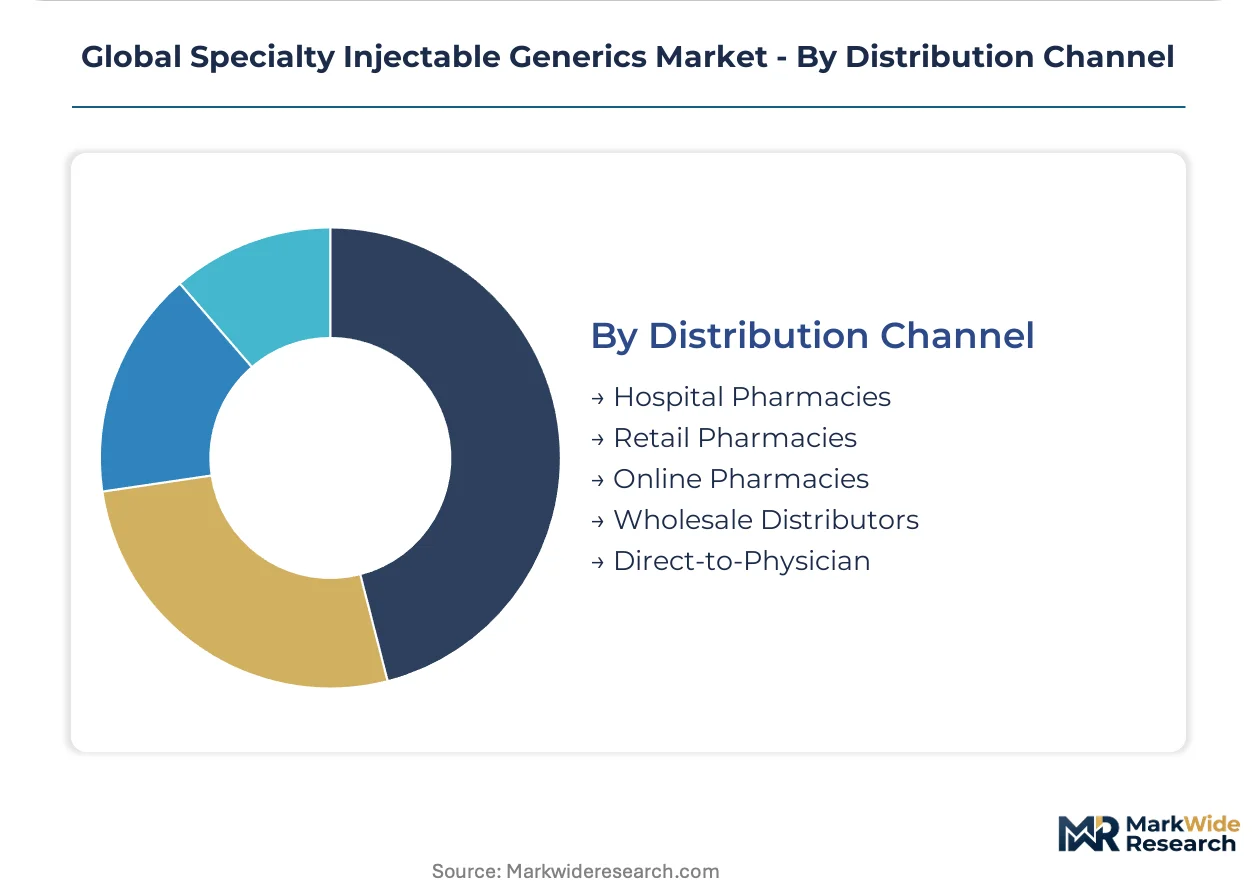
Distribution Channel:
Supply concentration reflects custody capability, with hospital pharmacies dominating high-value oncology while retail and direct channels capture self-administered categories.
- Hospital Pharmacies:Closed-system distribution with cold-chain validation. EMA Green Deal carbon accounting is favoring producers with European logistics assets.
- Wholesale Distributors:Third-party logistics for multi-site health systems. Inventory consolidation reduces working capital requirements.
- Retail Pharmacies:Community-based dispensing for outpatient prescriptions. Limited to stable formulations with minimal storage constraints.
- Online Pharmacies:Direct-to-patient delivery platforms. Regulatory frameworks for temperature-controlled shipping remain fragmented across jurisdictions.
- Direct-to-Physician:Manufacturer-controlled distribution for limited-distribution drugs. Oncology practices in the United States increasingly favor this model for biosimilar onboarding.
Controlling largest volume share: Hospital Pharmacies. Gaining share fastest: Direct-to-Physician.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty injectable generics production concentrates in Germany, India, and the United States, while consumption spreads across hospital networks in these markets and beyond. Regulatory divergence between FDA peptide guidance and EMA environmental mandates shapes regional filing strategies. Cold-chain infrastructure investments cluster where fill-finish capacity meets stringent carbon accounting requirements.
United States
Hospital procurement consortia in Texas and Florida are consolidating vendor pools by half, driving volume toward integrated delivery networks with centralized pharmacy operations. FDA Complex Generic Guidance compresses development timelines for peptide injectables while tightening ANDA filing requirements. The Greater Boston corridor anchors sterile manufacturing investment as emerging technology program approvals accelerate aseptic processing adoption.
Germany
AMNOG assessments are widening specialty pharmacy networks for biosimilar oncology injectables, with hospital procurement consortia consolidating purchasing power. EU Green Deal carbon accounting forces simultaneous revalidation of cold-chain logistics and packaging standards. The Rhine-Ruhr industrial belt sustains fill-finish capacity expansion as EMA environmental guidelines tighten compliance thresholds for pharmaceutical manufacturing.
India
Export-oriented producers face CDSCO alignment with ICH Q5B and Q5D guidelines for biologics-related injectables, tightening local manufacturing standards. Hyderabad and Bangalore clusters drive contract manufacturing adoption of modular aseptic processing skids to reduce qualification timelines. CDSCO's regulatory convergence with international standards reshapes capital allocation across sterile manufacturing networks.
Switzerland
Swissmedic maintains stringent batch release protocols for complex parenterals entering European distribution channels, favoring producers with established European logistics assets. The Basel pharmaceutical cluster sustains lyophilization capacity investment as oncology supply contracts mandate endotoxin-controlled manufacturing lines. Swiss pre-filled syringe standardization opens retail channel access for self-administered biologics in rheumatology and endocrinology applications.
Japan
PMDA's biosimilar framework creates distinct evidentiary demands from FDA pathways, inflating development budgets for dual-filing strategies. The Kanto region around Tokyo anchors sterile injectable demand as hospital formularies accelerate therapeutic substitution protocols for monoclonal antibody expirations. Japanese pharmaceutical distributors are consolidating inventory management for temperature-sensitive oncology formulations.
Global Specialty Injectable Generics Market Competitive Landscape
The competitive structure tilts toward vertically integrated multinationals with captive API production and European fill-finish assets. Hospital pharmacy consolidation compresses supplier rosters, rewarding scale and regulatory sophistication over pure manufacturing cost. Three archetypes dominate: integrated pharmaceutical conglomerates with backward integration into complex parenteral APIs; European fill-finish specialists leveraging EMA Green Deal compliance moats; and Indian contract manufacturers adopting modular aseptic platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing lyophilization line access through multi-year oncology supply contracts.
Within the integrated multinational tier, Fresenius Kabi and Teva Pharmaceutical Industries exemplify divergent strategic positioning. Fresenius Kabi occupies a position anchored by European fill-finish network density and EMA environmental compliance infrastructure. Teva Pharmaceutical Industries represents backward integration archetype, with in-house API production for complex parenterals securing supply chain control. Among specialty-focused players, Hikma Pharmaceuticals sits within the complex generic injectable specialist category.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Teva Pharmaceutical Industries |
| Pfizer |
| Novartis AG |
| Hikma Pharmaceuticals |
| Baxter International |
| Dr. Reddy's Laboratories |
| Sagent Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Lyophilization line scarcity feeds directly into three-tier pricing stratification across premium, standard, and economy levels, with endotoxin-controlled capacity in Germany and the United States commanding contract premiums while Indian modular facilities compete on volume throughput for injectable solutions.
Pricing Analysis
Value-based pricing anchors on clinical outcome equivalence for oncology biosimilars substituting reference monoclonals. Price differentiation rests on EMA environmental compliance certification versus standard GMP tiering, with carbon-accounted cold-chain logistics extracting premiums from hospital procurement consortia. Cost compression in standard-grade injectable solutions intensifies as Indian contract manufacturers scale modular aseptic platforms. Hospital pharmacies exhibit highest price sensitivity due to formulary consolidation, while specialty clinics absorbing self-administered biologics show lowest sensitivity.
Supply Chain Analysis
Qualified isolator technicians and barrier-system operators in Germany, India, and the United States command wage premiums that propagate through finished-dose pricing. Active pharmaceutical ingredient production draws from Chinese and Indian starting-material concentration, with complex parenteral synthesis tethered to just-in-time sourcing vulnerabilities. Tariff exposure on HFC propellants under EMA F-Gas Regulation threatens respiratory injectable reformulation timelines. Distribution runs through hospital pharmacy closed systems with validated cold-chain custody, bypassing retail channels for high-value oncology formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
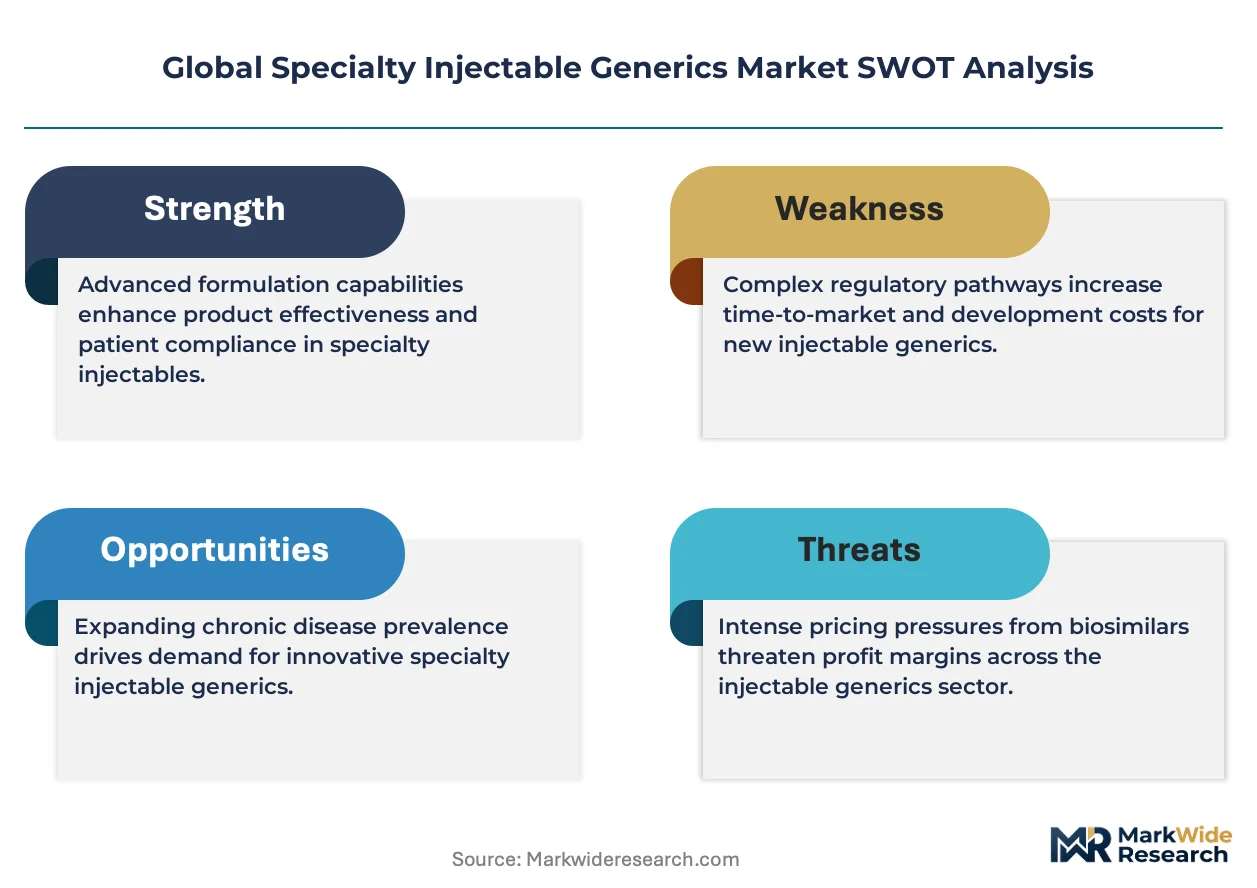
This market reads as supply-constrained, with lyophilization capacity scarcity propping pricing power for endotoxin-validated lines while compressing margins for commodity injectable solutions.
For Market Incumbents: Lock in multi-year oncology supply contracts securing lyophilization line access before modular capacity expansion in India saturates standard-grade segments. Deepen backward integration into peptide API production to offset substitution ceiling effects in critical-care injectables where prescriber resistance persists. Prioritize EMA Green Deal compliance infrastructure as a pricing moat against emerging European fill-finish competitors.
For New Entrants and Emerging Players: Enter via pre-filled syringe standardization for self-administered immunology and endocrinology applications, bypassing hospital custody requirements that incumbent distribution networks dominate. Target home healthcare provider segments in the United States where subcutaneous formulation demand outpaces supply. Pursue direct-to-physician distribution partnerships with oncology practices accelerating biosimilar onboarding protocols.
For Investors and Strategic Acquirers: FDA product-specific guidance publication for peptide injectables is the leading indicator that ANDA filing investment thresholds will reshape competitive moats around complex generic capabilities. Position acquisition screening toward European fill-finish specialists with EMA environmental compliance infrastructure and captive lyophilization assets. Watch for hospital procurement consortia consolidation velocity in Texas and Florida as demand-concentration signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Endotoxin-controlled line additions in Germany secure oncology contract premiums under EMA guidelines. |
| Modular Aseptic Platform Adoption | Hyderabad and Bangalore contract manufacturers compress qualification timelines for multi-product flexibility. |
| Pre-filled Syringe Standardization | Combination product pathways open retail channel access for rheumatology self-administration models. |
| Backward Integration into Peptide API | In-house synthesis reduces sourcing vulnerability from India-China starting material concentration. |
| EMA Green Deal Compliance Infrastructure | Carbon-accounted cold-chain logistics extract pricing premiums from hospital procurement consortia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with sterile manufacturing executives, hospital pharmacy directors, regulatory affairs specialists, and GPO contracts managers. FDA Complex Generic Guidance documents, EMA biosimilar framework submissions, CDSCO alignment notifications with ICH standards, and hospital procurement database extracts supplied segmentation baselines. Bottom-up volume modeling triangulated against top-down expenditure estimates from national health accounts.
Reconciling manufacturer capacity disclosures with hospital formulary adoption rates produced volume trajectories across the projection horizon. Segmentation dimensions spanned formulation type, therapy criticality, administration route, and regional regulatory cluster complexity. CAGRs derived from slope analysis of patent cliff timing, biosimilar approval velocity, and procurement consolidation patterns. Forecast inputs incorporated lyophilization line commissioning schedules, modular skid adoption curves, and EMA environmental compliance investment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence acceleration or geopolitical disruption to API sourcing corridors. Assumptions reflect documented filing pathway timelines, carbon accounting enforcement trajectories, and prescriber substitution elasticity parameters. Material deviation in FDA peptide guidance publication timing or EMA F-Gas Regulation phase-out velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Muscle Wasting Disorders Market