
 Bartter Syndrome Treatment Market | 2026-2036
Bartter Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bartter Syndrome Treatment Market Analytics
Orphan drug pricing and reimbursement negotiation is rewriting how value accrues across the Bartter syndrome value chain. Novartis leverages its established nephrology franchise to sustain pediatric specialist access across European markets. Pfizer anchors its position through manufacturing scale in electrolyte replacement therapies. Amneal Pharmaceuticals competes on cost positioning in generic potassium-sparing diuretic formulations.
Bartter syndrome treatment encompasses pharmacological management of salt-wasting tubulopathies through potassium conservation, prostaglandin inhibition, and electrolyte repletion protocols targeting serum potassium above 3.5 mEq/L and normalizing metabolic alkalosis. The therapeutic objective centers on preventing growth failure, nephrocalcinosis, and polyuria-related dehydration in pediatric and adolescent populations. Diuretics and potassium supplements together capture the dominant share of current prescribing patterns, while intravenous delivery modes command premium reimbursement in acute decompensation episodes managed through hospitals and specialty pharmacies. Oral formulations maintain the volume base in stable maintenance therapy, though home care channels are gaining traction as caregiver training programs expand.
FDA orphan drug incentives and EMA's pediatric investigation plans shape clinical development priorities and extended exclusivity timelines for novel Bartter syndrome therapies. REACH compliance and FDA current good manufacturing practice standards govern active pharmaceutical ingredient sourcing and finished dosage form release specifications across all marketed products. Stakeholders must monitor how real-world evidence requirements from payers in Germany and Japan reshape post-approval study commitments and pricing negotiations for maintenance therapies.
Market Dynamics
Orphan drug incentives from FDA and EMA are compressing clinical trial timelines for rare tubulopathies, redirecting R&D capital toward pediatric nephrology while tightening specialist recruitment competition across academic medical centers.
Growth Catalysts
- EMA Pediatric Investigation Plans:Extended exclusivity timelines reward developers targeting adolescent electrolyte disorders, funneling venture funding into nephrology-focused biotechs.
- Prostaglandin inhibition protocols:Refined dosing algorithms for indomethacin and celecoxib are reducing nephrocalcinosis progression rates in tertiary pediatric units.
- Japan's academic medical hub concentration:Tokyo and Osaka pediatric nephrology centers generate concentrated demand for intravenous electrolyte replacement therapies.
Market Restraints
- Potassium chloride API concentration:Three Indian manufacturers control bulk supply, exposing formulation specialists to input volatility and qualification delays.
- REACH compliance costs:ECHA documentation requirements for electrolyte excipients inflate regulatory overhead for European generic diuretic producers.
- Oral bioavailability ceiling:Potassium salt gastrointestinal irritation limits maximum tolerated doses in maintenance therapy, capping therapeutic efficacy.
Strategic Opportunities
- Germany's real-world evidence mandates:Post-approval study commitments for maintenance therapies create first-mover advantage for registry-building sponsors.
- Home infusion nursing networks:Caregiver training programs in the United States are shifting acute decompensation management from emergency departments to residential settings.
- Sustained-release potassium formulations:Osmotic pump technology convergence with pediatric-friendly dosing is opening compliance improvement whitespace.
Industry Challenges
- Pediatric nephrology fellowship scarcity:United States training programs graduate fewer than 50 specialists annually, constraining protocol expansion at community hospitals.
- Multi-source API qualification timelines:FDA current good manufacturing practice audits for Indian and Chinese potassium salt suppliers extend supply security planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bartter Syndrome Treatment Market |
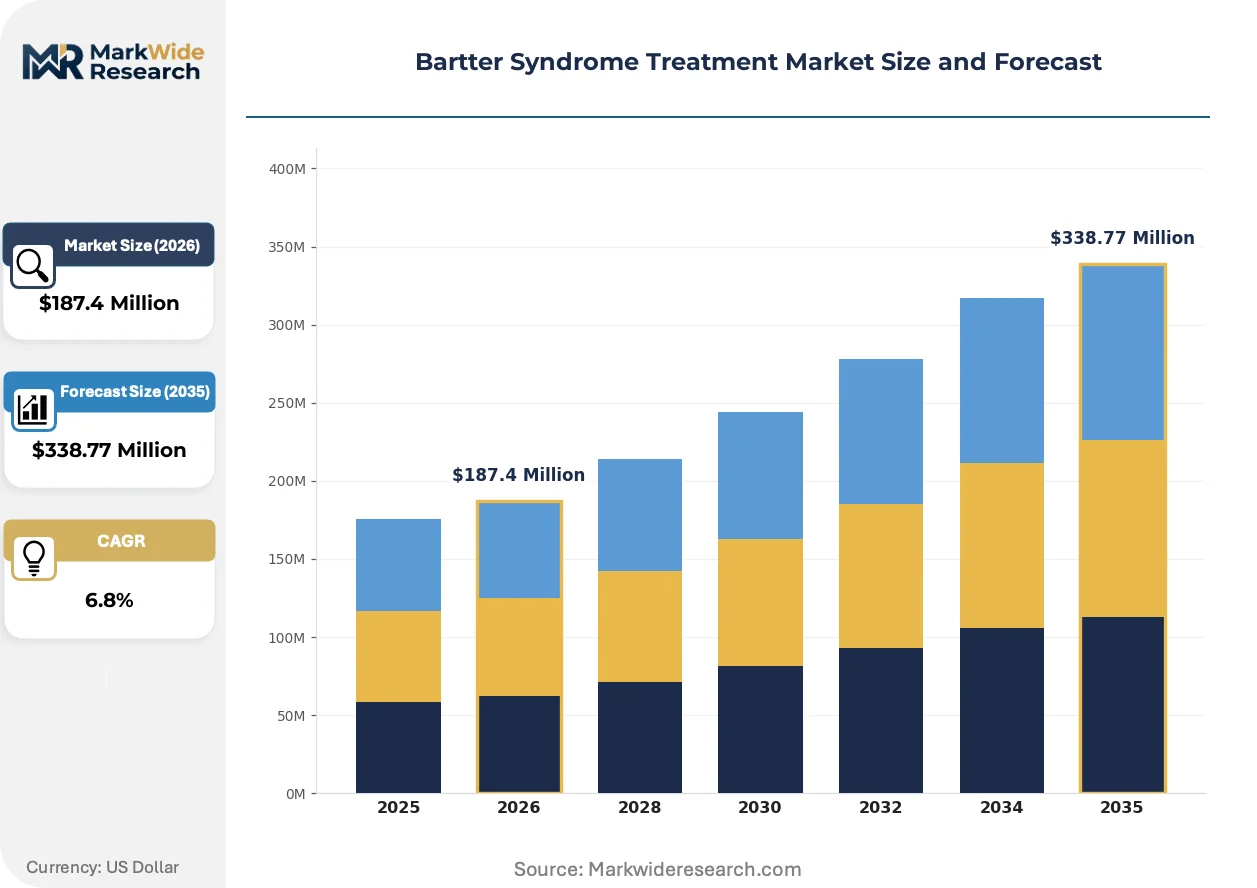
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diuretics, Non-steroidal Anti-inflammatory Drugs, Potassium Supplements, Electrolyte Solutions Therapy Area: Pediatric Medicine, Nephrology, General Practice, Genetics Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Abbott Laboratories, Novartis, Pfizer, Eli Lilly, Bristol-Myers Squibb, Boehringer Ingelheim, Sanofi, Merck & Co., Amneal Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bartter Syndrome Treatment Market Evolving Landscape
Digital biomarker integration and decentralized trial infrastructure are compressing evidence generation cycles for rare disease therapeutics, reshaping how pediatric tubulopathy treatments reach regulatory submission.
Remote patient monitoring platforms is virtualizing electrolyte surveillance for Bartter syndrome patients, enabling real-time potassium trend detection. Academic medical centers in Boston and Heidelberg are piloting continuous telemetry-linked dosing adjustments. This capability is virtualizing the traditional quarterly clinic visit model into asynchronous specialist oversight.
REACH compliance deadlines for pharmaceutical excipients are forcing reformulation investments across European potassium-sparing diuretic portfolios. Manufacturers must substitute legacy bulking agents ahead of 2026 authorization sunsets. Pediatric liquid formulations face disproportionate impact due to limited alternative solubilizer options.
Caregiver-administered subcutaneous infusion protocols are displacing hospital-based intravenous repletion for stable patients. Home care agencies in Japan and Germany are certifying nursing staff for electrolyte monitoring. This channel migration is most visible in adolescent populations with established vascular access.
Bartter Syndrome Treatment Market Segmentation
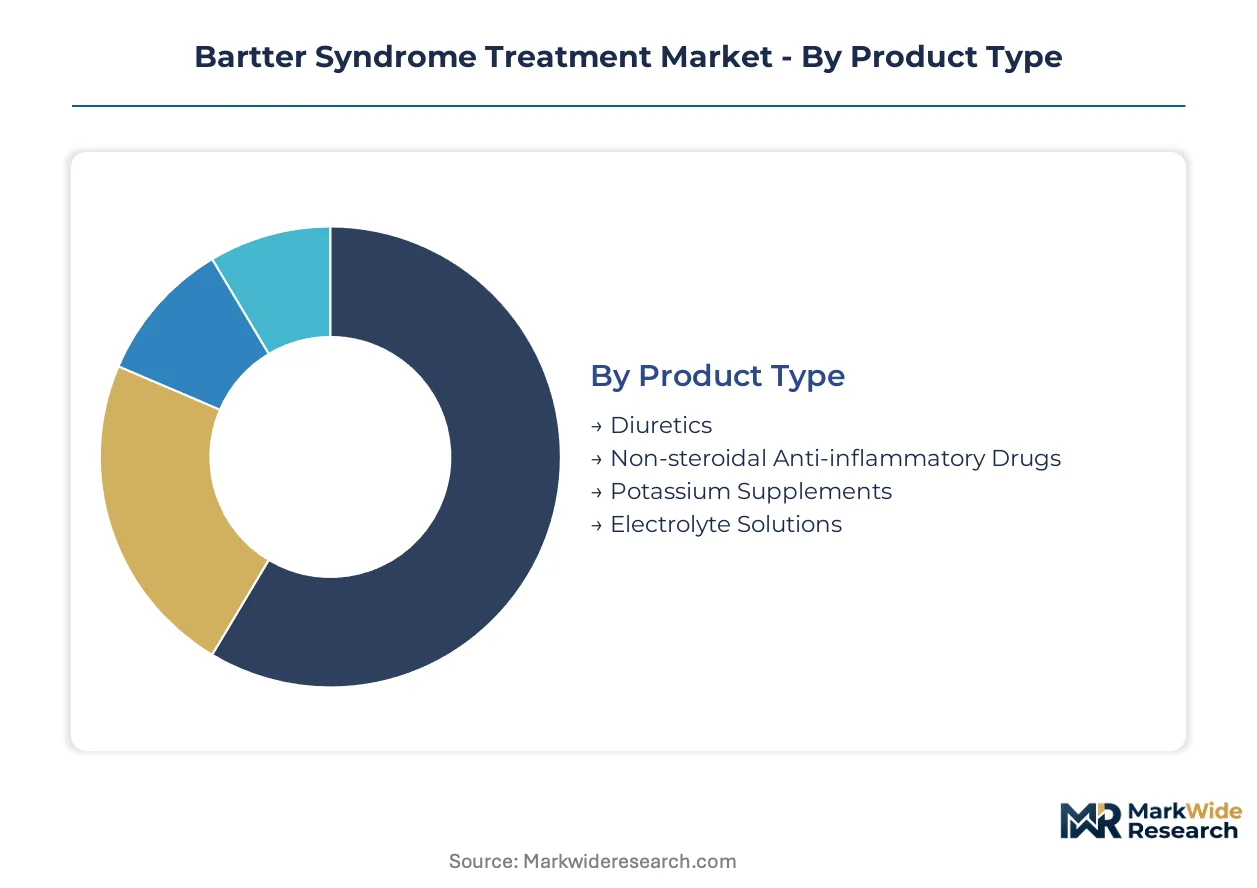
Bartter syndrome treatment segmentation reveals how therapeutic complexity fragments across pediatric nephrology workflows. Each dimension—product formulation, clinical setting, delivery route, and care site—carries distinct reimbursement logic and supply chain requirements that shape commercial strategy.
Product Type:
After-sales service intensity concentrates in electrolyte replacement products where home monitoring compliance and caregiver training programs determine therapeutic outcomes and repeat prescription rates.
- Diuretics:Potassium-sparing agents like spironolactone and amiloride form the pharmacological backbone of Bartter syndrome management, blocking distal sodium reabsorption to mitigate salt-wasting. Demand clusters in tertiary pediatric nephrology units at academic medical centers in the United States and Germany, where protocol standardization drives consistent prescribing.
- Non-steroidal Anti-inflammatory Drugs:Prostaglandin inhibitors—primarily indomethacin and celecoxib—reduce polyuria and nephrocalcinosis progression through cyclooxygenase blockade. Japanese pediatric nephrology centers in Tokyo and Osaka generate concentrated demand for optimized dosing algorithms that balance efficacy with gastrointestinal tolerability.
- Potassium Supplements:Oral potassium chloride and citrate formulations address persistent hypokalemia, with generic manufacturers competing on excipient quality and pediatric palatability.
- Electrolyte Solutions:Intravenous and oral rehydration therapies manage acute decompensation episodes, with specialty pharmacy distribution networks handling cold-chain logistics for parenteral formulations.
Diuretics hold the largest share; momentum sits with non-steroidal anti-inflammatory drugs as prostaglandin inhibition protocols refine.
Therapy Area:
Cost tier differentiation separates high-complexity subspecialty management from primary care coordination, with reimbursement rates scaling according to diagnostic technology intensity and specialist time allocation.
- Pediatric Medicine:Dedicated pediatric nephrology departments manage the majority of confirmed Bartter syndrome cases, integrating growth monitoring, electrolyte surveillance, and developmental assessment into longitudinal care protocols. Academic medical centers in Boston, Heidelberg, and Osaka anchor this segment through fellowship-trained specialist concentration.
- Nephrology:Adult and transitional nephrology services handle adolescent patients progressing from pediatric protocols, with particular concentration in German university hospitals where tubulopathy referral networks are mature.
- General Practice:Primary care physicians coordinate stable maintenance therapy and acute episode triage, particularly in rural United States counties distant from tertiary centers.
- Genetics:Molecular diagnostic services identify SLC12A1, KCNJ1, CLCNKB, and BSND mutations to confirm subtype classification and guide family counseling, with testing concentrated in reference laboratories.
Nephrology captures the highest reimbursement per case; genetics is climbing the fastest as molecular confirmation becomes standard of care.
Delivery Mode:
Volume concentration favors oral formulations for maintenance therapy, while margin accretion concentrates in parenteral routes where hospital administration and specialty pharmacy handling fees apply.
- Oral:Tablets, capsules, and liquid formulations dominate maintenance prescribing for potassium supplements and diuretics, with palatability and dosing frequency driving pediatric adherence challenges.
- Intravenous:Hospital and infusion center administration of electrolyte solutions and high-dose potassium replacement commands premium reimbursement during acute decompensation episodes.
- Subcutaneous:Emerging home infusion protocols for stable patients are displacing emergency department visits, with nursing network certification expanding in Japan and Germany.
- Transdermal:Limited current application for Bartter syndrome specifically, though iontophoretic potassium delivery research continues in academic settings.
Oral formulations maintain volume leadership; subcutaneous delivery is gaining share fastest through home care channel expansion.
End User:
Customer type fragmentation splits between institutional purchasers with formulary committees and dispersed home care settings where caregiver training investment determines therapeutic fidelity.
- Hospitals:Tertiary pediatric centers manage acute decompensation, diagnostic workup, and protocol initiation, with purchasing decisions driven by nephrology department preference and group purchasing organization contracts.
- Clinics:Outpatient nephrology and genetics clinics handle stable patient monitoring and medication adjustment, with visit frequency tied to electrolyte stability.
- Home Care:Certified nursing services for subcutaneous infusion and caregiver training programs are expanding in the United States and Germany, shifting site of care from institutional to residential settings.
- Specialty Pharmacies:Dispensing of orphan-designated therapies and compounded formulations occurs through limited distribution networks with mandatory risk evaluation and mitigation strategy compliance.
Hospitals retain the largest share; home care shows the steepest expansion trajectory as infusion nursing networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across major markets. Japanese and German purchasers absorb premium pricing for orphan-designated therapies, while Indian and Chinese buyers prioritize cost-optimized generic alternatives.
United States
FDA orphan drug incentives accelerate pediatric nephrology trial enrollment at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center. The 21st Century Cures Act mandates real-world evidence integration into rare disease approvals. Tertiary centers in Massachusetts and Ohio concentrate specialist expertise and drive protocol standardization.
Germany
EMA pediatric investigation plans extend market exclusivity for developers targeting adolescent electrolyte disorders. Germany's G-BA requires post-approval outcomes data for maintenance therapy reimbursement. University hospitals in Heidelberg and Berlin anchor tubulopathy referral networks and generate concentrated demand for intravenous electrolyte replacement.
Japan
PMDA Sakigake designation fast-tracks novel Bartter syndrome therapies through priority review pathways. METI funding supports pediatric rare disease infrastructure at designated core hospitals. Tokyo and Osaka pediatric nephrology centers generate disproportionate demand for optimized prostaglandin inhibition protocols.
India
CDSCO streamlined approval pathways for rare disease therapies remain underdeveloped, channeling demand toward cost-sensitive generic potassium supplements. Price controls on essential medicines compress margins for domestic formulation specialists. Hyderabad and Mumbai manufacturing clusters supply bulk potassium chloride API to global formulation networks.
United Kingdom
NICE technology appraisals for ultra-rare conditions apply modified cost-effectiveness thresholds to Bartter syndrome therapies. NHS England specialized commissioning funds designated pediatric nephrology centers. London and Manchester academic medical hubs coordinate national tubulopathy registries and drive molecular diagnostic adoption.
Bartter Syndrome Treatment Market Competitive Landscape
Multinational pharmaceutical conglomerates and generic formulation specialists split the market along innovation-versus-access fault lines. Consolidation characterizes the branded orphan drug segment where extended exclusivity timelines reward early development commitments. Three strategic archetypes dominate: nephrology franchise holders leveraging specialist access networks, manufacturing-scale players optimizing electrolyte replacement production costs, and emerging biotechs pursuing novel mechanism targets. Competitive intensity concentrates on M&A activity to secure pediatric rare disease pipelines and strategic partnerships with academic medical centers for real-world evidence generation.
Within the nephrology franchise tier, Novartis and Pfizer exemplify contrasting scale-based positioning. Novartis occupies a position anchored in European pediatric specialist networks, while Pfizer represents manufacturing-scale dominance in electrolyte replacement therapies. Amneal Pharmaceuticals sits within the generic formulation archetype, competing on cost positioning in potassium-sparing diuretic markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Novartis |
| Pfizer |
| Eli Lilly |
| Bristol-Myers Squibb |
| Boehringer Ingelheim |
| Sanofi |
| Merck & Co. |
| Amneal Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Hyderabad's bulk potassium chloride API manufacturing cluster anchors global formulation supply, with capacity utilization swings directly transmitting into downstream pricing power for European and North American diuretic specialists. REACH compliance costs and FDA current good manufacturing practice audit backlogs amplify input cost volatility, forcing formulation manufacturers to absorb margin compression or renegotiate long-term offtake terms with tertiary hospital purchasers.
Pricing Analysis
After-sales service revenue from caregiver training programs and home monitoring compliance contracts drives lifetime value accrual for electrolyte replacement therapy providers. Three-tier pricing structure across orphan-designated biologics, branded maintenance formulations, and generic potassium supplements separates reimbursement tiers by regulatory exclusivity status and pediatric palatability investment. Cost compression in generic diuretic segments is intensifying because Indian API suppliers face ECHA documentation delays, while academic medical centers in Boston and Heidelberg exhibit lowest price sensitivity due to dedicated rare disease funding streams.
Supply Chain Analysis
Contract manufacturing concentration for oral potassium formulations rests with mid-tier Indian pharmaceutical services firms and European specialist producers. Active pharmaceutical ingredient supply draws from Hyderabad, Mumbai, and selected Chinese chemical parks, with prostaglandin inhibitor synthesis anchored in Italian and Japanese facilities. Single-source vulnerability concentrates in potassium chloride API where three Indian manufacturers control bulk qualification, while distribution runs through specialty pharmacy networks with cold-chain mandates for parenteral electrolyte solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bartter syndrome treatment constitutes a defensive-moat market where regulatory entrenchment through FDA orphan drug exclusivity and EMA pediatric investigation plans erects decade-long barriers against substitutable competition.
For Market Incumbents: Pre-empt generic erosion in potassium-sparing diuretics by securing backward integration into Indian API supply through strategic toll manufacturing agreements. Expand capacity in subcutaneous infusion nursing certification programs across German home care networks before emerging entrants capture site-of-care migration. Patent cliff exposure for legacy prostaglandin inhibitors demands accelerated novel mechanism R&D targeting SLC12A1 mutation subtypes. For New Entrants and Emerging Players: Rural United States counties distant from Boston and Cincinnati tertiary centers offer concentrated underpenetration where primary care coordination gaps create white-space opportunity for telemedicine-linked electrolyte monitoring platforms. Japanese adolescent populations transitioning from pediatric to adult nephrology services represent a penetrable segment lacking protocol standardization. A go-to-market angle anchored in caregiver-administered subcutaneous protocols with nursing network partnerships bypasses hospital formulary committee gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechs with Phase II-ready novel tubulopathy mechanisms and established real-world evidence registry infrastructure. Long-term viability hinges on molecular diagnostic integration and extended exclusivity capture through pediatric indication expansion. The inflection indicator to monitor is FDA breakthrough therapy designation frequency for rare renal tubular disorders, signaling regulator willingness to accelerate novel mechanism approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA and EMA incentives compress clinical trial timelines for rare tubulopathies and extend exclusivity horizons. |
| Real-World Evidence Registry Buildout | Germany's G-BA mandates post-approval outcomes data, creating first-mover advantage for sponsors with established patient tracking infrastructure. |
| Home Infusion Nursing Network Expansion | Caregiver training programs in the United States and Japan shift acute decompensation management from emergency departments to residential settings. |
| API Supply Security Agreements | Multi-source qualification for Indian and Chinese potassium salt suppliers extends planning horizons against ECHA documentation delays. |
| Sustained-Release Formulation Development | Osmotic pump technology convergence with pediatric-friendly dosing opens compliance improvement whitespace in maintenance therapy. |
Research Methodology
Cross-validation between primary interviews with pediatric nephrologists, formulary directors at tertiary hospitals, regulatory affairs specialists, and specialty pharmacy procurement managers anchors the qualitative findings. Secondary validation draws from FDA orphan drug designations, EMA pediatric investigation plan submissions, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up prescription volume modeling and top-down rare disease epidemiology triangulation reconcile demand estimates across the analysis window.
Calibration against historical electrolyte replacement therapy pricing and prostaglandin inhibitor utilization patterns informs the analytical framework. Segmentation dimensions span product formulation, delivery mode, therapy area, and regional regulatory cluster. CAGRs derive from epidemiology-adjusted patient population projections and pricing trajectory assumptions, with specific inputs including pediatric nephrology fellowship graduation rates and orphan drug reimbursement negotiation outcomes.
Practitioners should monitor API supplier audit backlogs, REACH authorization sunset timelines, and real-world evidence mandate expansions for early signals of forecast revision. Assumptions reflect current regulatory incentive structures and specialist concentration patterns. Quarterly review of pediatric nephrology center expansion announcements and home care nursing certification program launches is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Hemophilia Market