
 Tardive Dyskinesia (TD) Treatment Market | 2026-2036
Tardive Dyskinesia (TD) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tardive Dyskinesia (TD) Treatment Market Analytics
Deutetrabenazine is hardening its position as the preferred VMAT2 inhibitor backbone, displacing earlier-generation tetrabenazine formulations in formulary positioning across managed care networks. Neurocrine Biosciences leverages its first-mover regulatory architecture to sustain exclusive market presence in the VMAT2 space. Teva Pharmaceutical Industries Ltd. anchors its portfolio through deep neurology franchise integration and global distribution scale. AbbVie Inc. competes via its neuropsychiatry pipeline breadth and institutional relationships with academic medical centers.
Tardive Dyskinesia Treatment encompasses pharmacological interventions targeting involuntary hyperkinetic movements arising from prolonged dopamine receptor antagonist exposure, with VMAT2 inhibitors functioning through reversible vesicular monoamine transporter-2 blockade to reduce dopamine release at nerve terminals. The primary commercial purpose centers on mitigating debilitating orofacial and limb chorea in patients requiring ongoing antipsychotic therapy. VMAT2 Inhibitors command the dominant margin pool given their disease-modifying positioning and premium pricing architecture, while Oral administration routes retain volume leadership due to patient compliance preferences and outpatient management suitability. Home Care channels represent the fastest-growing end user segment as payors push for site-of-care cost containment and long-acting formulations enable remote monitoring protocols.
FDA neurology division oversight shapes clinical trial endpoints and labeling claims for all new TD therapeutics, while EMA's Committee for Medicinal Products for Human Use imposes parallel efficacy standards across European markets. The central bank of regulatory complexity sits with CMS national coverage determination processes, which dictate reimbursement access for Medicare beneficiaries comprising the majority of TD patients. Stakeholders must monitor emerging FDA guidance on digital biomarker endpoints and their potential to reshape trial design economics for late-stage pipeline assets.
Market Dynamics
VMAT2 inhibitor commercialization is hardening formulary positioning as managed care networks consolidate preferred drug lists around reversible dopamine modulation therapies. Neurocrine Biosciences' first-mover architecture forces late entrants to navigate complex patent thickets and CMS national coverage determination pathways.
Growth Catalysts
- CMS Reimbursement Architecture:Medicare Part D coverage for movement disorder specialists sustains prescribing volume among the elderly TD population requiring chronic antipsychotic maintenance.
- Psychiatric Hospital Expansion:Inpatient neurology units are embedding TD screening protocols into routine antipsychotic monitoring, creating protocol-driven demand for pharmacological intervention.
- Long-Acting Injectable Formulations:Depot VMAT2 preparations reduce caregiver burden and enable remote monitoring, aligning with site-of-care cost containment mandates from commercial payors.
Market Restraints
- Specialist Concentration Risk:TD diagnosis and treatment initiation concentrates among board-certified movement disorder neurologists, creating geographic access deserts in rural and underserved urban corridors.
- Prior Authorization Friction:Commercial payors impose step-therapy requirements mandating tetrabenazine failure before deutetrabenazine or valbenazine approval, delaying optimal therapy initiation.
- Generic Substitution Threat:Patent cliffs for first-generation VMAT2 inhibitors expose originator portfolios to compounded pharmacy alternatives and international parallel trade.
Strategic Opportunities
- Home Care Channel Penetration:Remote patient monitoring platforms enable TD symptom tracking outside institutional settings, reducing per-patient healthcare utilization costs for Medicare Advantage plans.
- Digital Biomarker Integration:FDA guidance on smartphone-based chorea quantification opens pathways for decentralized clinical trial endpoints and real-world evidence generation.
- Schizophrenia-Adjunct Positioning:VMAT2 inhibitors are penetrating prophylactic protocols for patients on high-risk first-generation antipsychotics before TD symptom emergence.
Industry Challenges
- Movement Disorder Specialist Scarcity:Fellowship-trained neurologist supply fails to match TD prevalence growth, forcing reliance on telemedicine platforms with variable diagnostic accuracy.
- Longitudinal Trial Design Complexity:Irreversible TD cases require extended placebo-controlled observation periods, inflating per-patient study costs and screening failure rates.
- Formulary Exclusion Mechanics:Pharmacy benefit managers deploy therapeutic substitution algorithms that override prescriber intent, fragmenting patient continuity across plan years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tardive Dyskinesia (TD) Treatment Market |
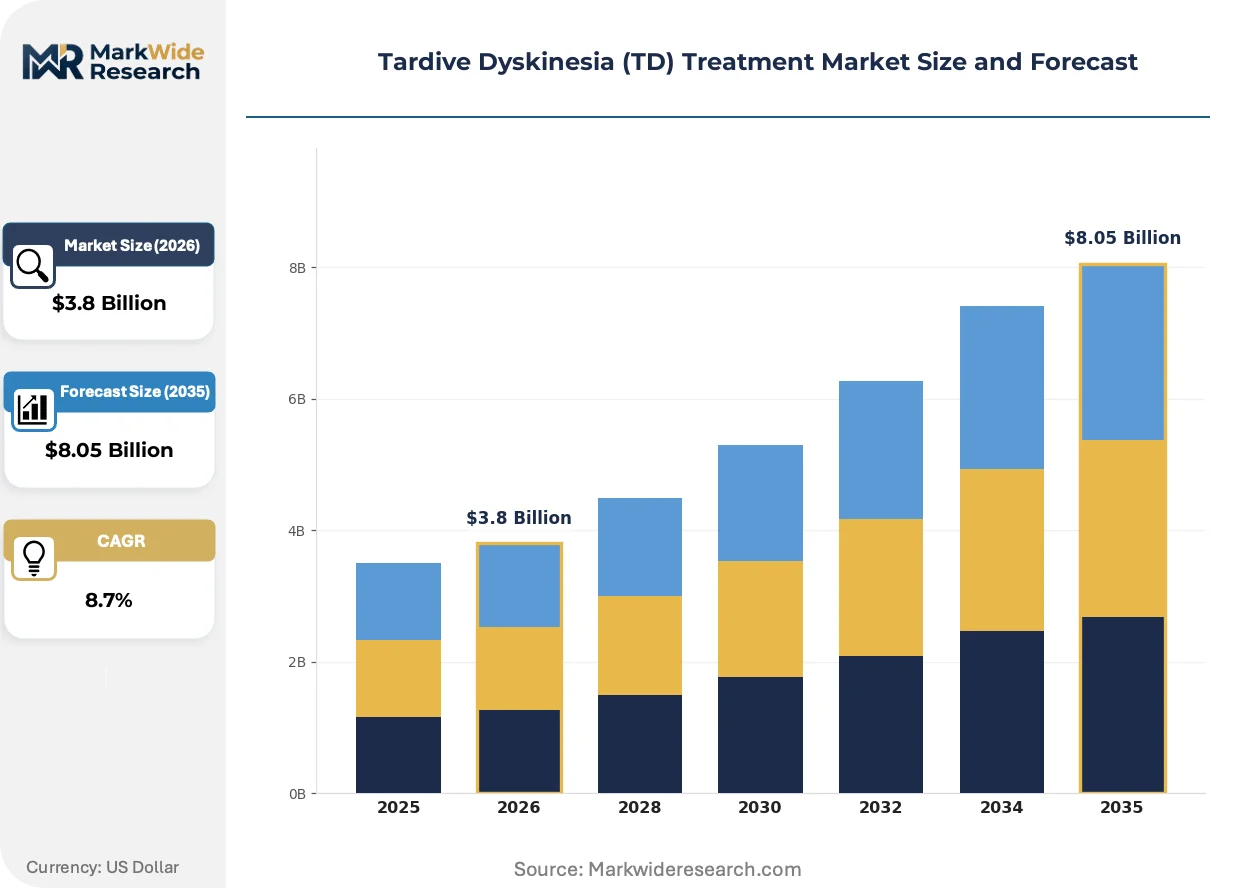
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, VMAT2 Inhibitors, Beta-Blockers, Botulinum Toxin Administration Route: Oral, Intramuscular, Subcutaneous, Topical Patient Type: Adults, Adolescents, Elderly, Special Populations End User: Hospitals, Clinics, Home Care, Research Institutes |
| Companies Covered | Sun Pharmaceutical Industries Ltd, AbbVie Inc., Neurocrine Biosciences Inc., Luye Pharma Group, Mitsubishi Tanabe Pharma Corporation, Teva Pharmaceutical Industries Ltd., Adamas Pharmaceuticals, Inc, SteriMax Inc., Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tardive Dyskinesia (TD) Treatment Market Evolving Landscape
Digital health infrastructure is reshaping how TD symptoms are quantified and managed, compressing the gap between clinical trial endpoints and real-world functional outcomes. Three convergent developments are restructuring competitive positioning.
Smartphone-based chorea assessment applications are decentralizing TD severity measurement from clinic-based examination to continuous home monitoring. Academic medical centers in California and Massachusetts are piloting FDA-cleared digital biomarker platforms that capture orofacial movement frequency through front-facing camera analysis. This technology is decentralizing the traditional site-of-care model, enabling decentralized clinical trial participation and expanding addressable patient pools beyond movement disorder clinic catchment areas.
EMA's Committee for Medicinal Products for Human Use has tightened efficacy standards for novel VMAT2 inhibitors, requiring demonstration of sustained benefit beyond six months for full marketing authorization. European regulators now mandate patient-reported outcome measures alongside clinician-rated scales, elevating trial complexity and documentation burdens. Neurology franchises with existing EU regulatory infrastructure are absorbing these compliance costs more efficiently than emerging entrants lacking centralized EMA rapporteur relationships.
Site-of-care economics are compressing institutional infusion revenue as payors steer stable TD patients toward oral outpatient regimens. Medicare Advantage plans in Florida and Arizona are deploying prior authorization algorithms that flag inpatient VMAT2 initiations for retrospective review. Home health agencies are capturing this displaced volume through nurse-administered long-acting formulations, restructuring traditional neurology practice revenue streams around remote monitoring fees rather than clinic visit billing.
Tardive Dyskinesia (TD) Treatment Market Segmentation
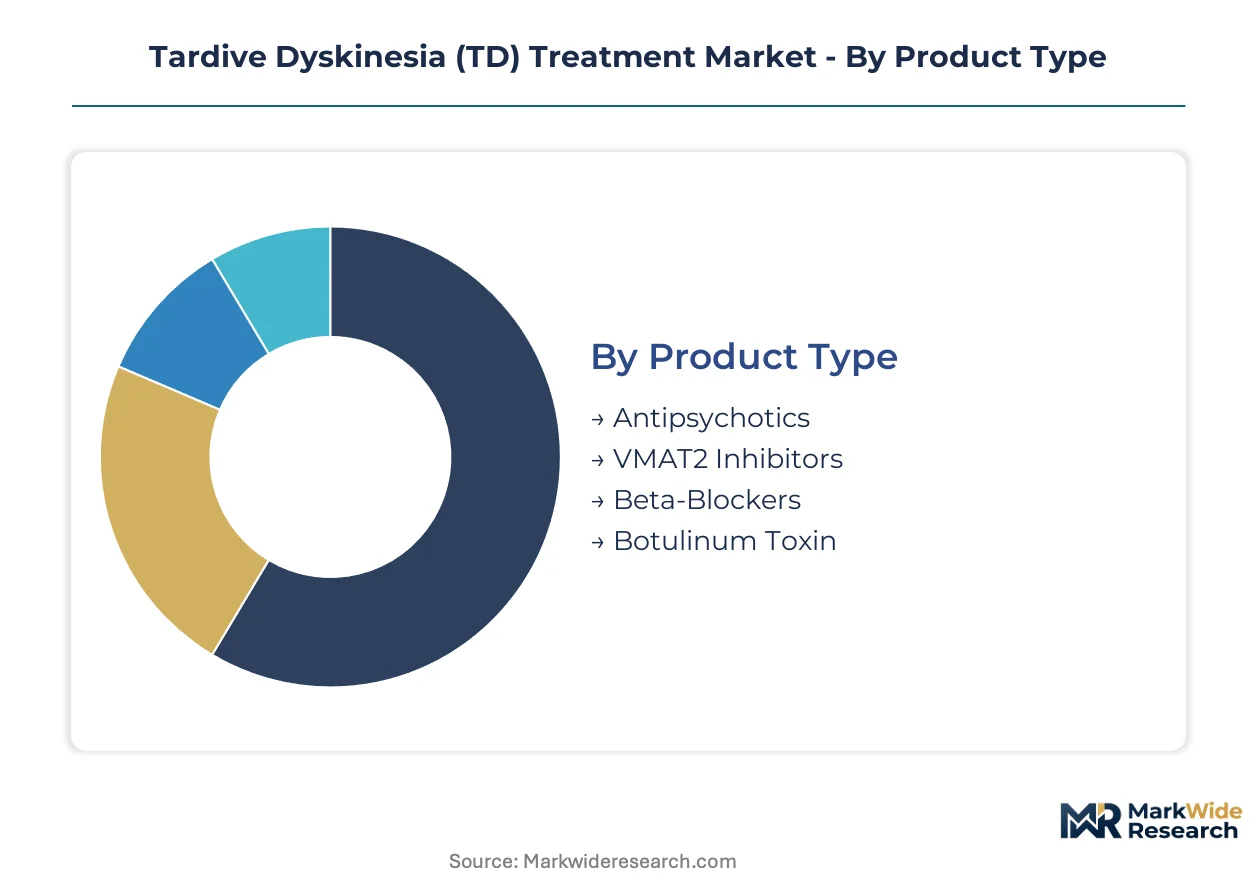
TD treatment segmentation reveals how reimbursement architecture and site-of-care economics fragment demand across pharmacological categories and delivery settings. Product type and administration route decisions cascade through formulary positioning, patient compliance, and Medicare billing codes.
Product Type:
Cost tier differentiation separates disease-modifying therapies from symptomatic management options across commercial and government payor formularies.
- VMAT2 Inhibitors:Reversible vesicular monoamine transporter-2 blockade reduces dopamine release at nerve terminals. Managed care networks in the United States consolidate preferred drug lists around deutetrabenazine and valbenazine as first-line options for orofacial chorea, though prior authorization friction delays initiation.
- Antipsychotics:Second-generation dopamine receptor antagonists with lower extrapyramidal side effect profiles serve dual purposes—maintaining psychiatric stability while minimizing additional TD risk. Academic medical centers prioritize these for schizophrenia patients requiring chronic maintenance.
- Beta-Blockers:Symptomatic tremor suppression for mild limb chorea without disease-modifying effect.
- Botulinum Toxin:Focal injection therapy for isolated orofacial movement disorders refractory to systemic pharmacotherapy.
Volume sits with VMAT2 Inhibitors; growth tilts toward Antipsychotics as prophylactic protocols expand.
Administration Route:
Patient compliance preferences and outpatient billing suitability determine route selection across institutional and home-based care models.
- Oral:Tablet and capsule formulations dominate chronic maintenance therapy through pharmacy benefit coverage. Medicare Part D reimbursement sustains prescribing volume among elderly TD populations requiring daily dosing regimens.
- Intramuscular:Long-acting depot preparations reduce caregiver burden and enable remote monitoring protocols. Home health agencies in Florida and Arizona capture displaced institutional volume through nurse-administered formulations.
- Subcutaneous:Patient-administered options for stable patients with demonstrated injection competence.
- Topical:Limited penetration for localized symptom management without systemic exposure.
Oral administration retains volume leadership; Intramuscular routes are expanding most quickly as site-of-care cost containment mandates intensify.
Patient Type:
Comorbidity burden and antipsychotic exposure duration stratify treatment complexity across demographic cohorts.
- Elderly:Patients over 65 with prolonged first-generation antipsychotic exposure present the highest TD prevalence and Medicare-dependent reimbursement profiles. Movement disorder specialists concentrate in urban corridors, creating access deserts for rural beneficiaries.
- Adults:Working-age patients on chronic antipsychotic maintenance balance symptom control against employment-related functional outcomes.
- Adolescents:Pediatric TD cases require specialized dosing protocols and developmental monitoring.
- Special Populations:Patients with intellectual disabilities or substance use comorbidities need modified treatment approaches.
Elderly patients anchor volume; Adults show the steepest expansion trajectory as early intervention protocols penetrate schizophrenia-adjunct positioning.
End User:
Site-of-care economics and reimbursement coding differentiate institutional from remote treatment initiation pathways.
- Home Care:Remote patient monitoring platforms enable TD symptom tracking outside institutional settings. Medicare Advantage plans deploy prior authorization algorithms that flag inpatient VMAT2 initiations for retrospective review, redirecting stable patients toward nurse-administered home protocols.
- Hospitals:Inpatient neurology units embed TD screening into routine antipsychotic monitoring, creating protocol-driven demand for pharmacological intervention upon admission.
- Clinics:Outpatient movement disorder centers manage dose titration and long-term monitoring for stabilized patients.
- Research Institutes:Academic medical centers pilot digital biomarker platforms and decentralized clinical trial participation.
Hospitals retain acute initiation volume; Home Care channels are gaining share fastest as payor site-of-care steering intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients generate the majority of VMAT2 inhibitor prescriptions through Medicare Part D reimbursement channels, while Germany and Japan anchor European and Asian demand through their respective national health technology assessment frameworks.
United States
Movement disorder specialists concentrate in urban academic medical centers, creating access deserts for rural Medicare beneficiaries requiring TD intervention. FDA neurology division oversight shapes clinical trial endpoints and labeling claims for all new therapeutics entering this market. The Cleveland Clinic and Mayo Clinic anchor TD treatment protocol development, with both institutions embedding digital biomarker pilot programs into outpatient monitoring workflows.
Germany
The Federal Joint Committee (G-BA) mandates comparative effectiveness evidence for VMAT2 inhibitor reimbursement, extending market access timelines versus US pathways. EMA's Committee for Medicinal Products for Human Use imposes parallel efficacy standards requiring sustained benefit demonstration beyond six months. Heidelberg University Hospital and Charité Berlin coordinate multicenter TD registries that feed into national health technology assessment submissions.
Japan
PMDA prioritizes patient-reported outcome measures alongside clinician-rated scales for neurological drug approvals, elevating documentation requirements for VMAT2 inhibitor sponsors. The Ministry of Health, Labour and Welfare maintains stringent pricing controls through biennial National Health Insurance price revisions. Tokyo Medical University Hospital and Osaka University Hospital lead TD specialist training programs that address fellowship-trained neurologist scarcity.
United Kingdom
NICE technology appraisals require cost-effectiveness thresholds that filter high-price VMAT2 inhibitors through restricted access schemes. NHS England's specialized commissioning framework concentrates TD treatment initiation in designated movement disorder centers. King's College Hospital and Salford Royal NHS Foundation Trust operate hub-and-spoke models that extend specialist reach into underserved northern regions through telemedicine platforms.
Canada
Health Canada aligns neurological drug review timelines with FDA decisions, accelerating commercialization for sponsors with prior US approval. Provincial formularies impose therapeutic substitution policies that prioritize tetrabenazine before newer VMAT2 inhibitors. Toronto Western Hospital and McGill University Health Centre anchor TD clinical trial networks that generate real-world evidence for CADTH reimbursement submissions.
Tardive Dyskinesia (TD) Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator pharmaceutical companies commanding premium pricing for VMAT2 inhibitors while generic compounders capture volume in first-generation tetrabenazine markets. The competitive structure tilts toward consolidation among neurology-focused franchises with established FDA rapporteur relationships and CMS national coverage determination expertise. Three archetypes dominate: first-mover VMAT2 specialists with patent-protected portfolios, diversified neuropsychiatry divisions of large-cap pharmaceutical groups, and emerging entrants navigating complex regulatory thickets. Capacity expansion through long-acting formulation development and strategic partnerships for digital biomarker integration represent the dominant competitive moves reshaping positioning.
Within the first-mover specialist tier, Neurocrine Biosciences Inc. and Adamas Pharmaceuticals, Inc. exemplify archetypes built around VMAT2 inhibitor commercialization architecture. Among diversified neuropsychiatry franchises, AbbVie Inc. and Teva Pharmaceutical Industries Ltd. occupy positions leveraging institutional relationships with academic medical centers and global distribution scale. Lundbeck A/S represents the European-origin specialist model with deep CNS therapeutic area concentration.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| AbbVie Inc. |
| Neurocrine Biosciences Inc. |
| Luye Pharma Group |
| Mitsubishi Tanabe Pharma Corporation |
| Teva Pharmaceutical Industries Ltd. |
| Adamas Pharmaceuticals, Inc |
| SteriMax Inc. |
| Lundbeck A/S |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient spot indices for tetrabenazine derivatives cascade through contract manufacturing organizations into three-tier pricing structures across premium, standard, and economy levels, with FDA-certified facilities commanding 40-60% markups over Indian and Chinese API suppliers serving compounding pharmacies.
Pricing Analysis
Volume concentrates in first-generation tetrabenazine generics while margins pool with deutetrabenazine and valbenazine originators protected by CMS national coverage determinations. Price differentiation hinges on FDA breakthrough therapy designation status and movement disorder specialist prescribing networks. Pricing pressure stems from Medicare Part D rebate negotiations and therapeutic substitution algorithms deployed by pharmacy benefit managers. Safety-net hospitals and rural Medicare beneficiaries exhibit highest price sensitivity; academic medical centers with bundled payment contracts show lowest.
Supply Chain Analysis
Workforce availability for sterile injectable manufacturing concentrates in Ireland, Switzerland, and the Research Triangle Park corridor of North Carolina, constraining long-acting VMAT2 depot production scale-up. Finished dosage form supply draws from Teva's global distribution hubs, Lundbeck's European manufacturing network, and Sun Pharmaceutical's Indian facilities. Single-source vulnerability sits with specialty CMOs holding FDA Type II active DMFs for modified-release formulations. Distribution runs through specialty pharmacy channels and hospital outpatient infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Movement disorder specialist scarcity props pricing power for VMAT2 inhibitors, as fellowship-trained neurologist supply fails to match TD prevalence growth across Medicare-dependent populations.
For Market Incumbents: Lock in exclusive CMS national coverage determination pathways through real-world evidence generation partnerships with Cleveland Clinic and Mayo Clinic TD registries. Deepen backward integration into long-acting injectable CMO capacity in Ireland and North Carolina to preempt supply constraints. Counter generic substitution threats through digital biomarker companion platforms that reinforce brand loyalty among movement disorder specialists.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in VMAT2 inhibitor markets offers white-space entry through prophylactic schizophrenia-adjunct positioning before TD symptom emergence. Target home care channel penetration in Florida and Arizona Medicare Advantage markets with nurse-administered depot formulations. Pursue FDA breakthrough therapy designation to accelerate commercialization timelines and secure favorable formulary positioning.
For Investors and Strategic Acquirers: Distressed-cycle entries favor neurology-focused franchises with existing FDA rapporteur relationships and EMA centralized procedure infrastructure in Massachusetts and California clusters. Long-term viability hinges on digital biomarker integration capabilities and remote patient monitoring platform ownership. Watch FDA guidance on smartphone-based chorea quantification as inflection signal for decentralized clinical trial economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Development | Enables home care channel capture and Medicare site-of-care cost containment compliance. |
| Digital Biomarker Platform Integration | Positions sponsors for FDA guidance on decentralized chorea quantification endpoints. |
| Movement Disorder Specialist Network Expansion | Addresses geographic access deserts and builds prescriber loyalty for formulary defense. |
| EMA Centralized Procedure Filing | Accelerates European market access through rapporteur relationships with Germany and UK agencies. |
| Prophylactic Schizophrenia-Adjunct Positioning | Expands addressable patient pool to pre-symptomatic antipsychotic maintenance populations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with movement disorder neurologists, pharmacy benefit manager formulary directors, CMS reimbursement policy specialists, and VMAT2 inhibitor brand marketing executives. FDA approval databases, EMA centralized procedure submissions, ClinicalTrials.gov entries, and Medicare Part D utilization files provided structured secondary validation. Bottom-up patient prevalence modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Granularity-level modeling operated at the intersection of administration route, patient age cohort, and end-user channel across the projection horizon. Treatment line positioning, dosage form, and regional regulatory cluster segmentation informed volume allocation. CAGRs derived from epidemiological trend extrapolation, pricing trajectory assumptions, and reimbursement policy scenario analysis. Forecast inputs incorporated antipsychotic prescribing patterns from CMS Medicare data and VMAT2 inhibitor prior authorization approval rates from commercial payor audits.
Inputs from FDA neurology division guidance documents and EMA CHMP scientific advice letters were available through the study window; gaps in real-world VMAT2 inhibitor adherence data introduce uncertainty bands around long-acting formulation penetration assumptions. Forecasts reflect documented assumptions regarding Medicare Advantage site-of-care steering intensity and movement disorder specialist training pipeline expansion. Material deviation in FDA digital biomarker endpoint guidance or CMS national coverage determination timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market