
 Global Lung Transplant Therapeutics Market | 2026-2036
Global Lung Transplant Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lung Transplant Therapeutics Market Foresight
Hospital procurement consortiums is reconfiguring how lung transplant therapeutics reach end users, with centralized purchasing agreements now governing formulary placement across multi-site health systems. Astellas Pharma Inc. leverages its transplant-focused portfolio to sustain preferential contracting positions within these networks. XVIVO Perfusion AB competes through organ preservation technology leadership that extends into companion therapeutic protocols at major transplant hubs.
Lung transplant therapeutics encompass pharmaceutical and biologic agents administered before, during, and after allogeneic lung transplantation to prevent graft rejection, manage infection risk, and preserve pulmonary function, with immunosuppressant regimens typically combining calcineurin inhibitors, antiproliferative agents, and corticosteroids in individualized protocols. These therapeutics serve the essential clinical purpose of enabling long-term graft survival and recipient quality of life in a procedure with inherent immunologic complexity. Immunosuppressants anchor the product type landscape as the foundational revenue pool, while inhalation therapy delivery modes represent the fastest-growing structural segment due to targeted pulmonary drug deposition and reduced systemic exposure profiles.
FDA, EMA, and WHO standards collectively govern clinical trial endpoints, manufacturing quality, and post-market surveillance for lung transplant therapeutics, with FDA's breakthrough therapy designation and EMA's PRIME eligibility creating differentiated market access timelines that shape developer prioritization. The EU AI Act's emerging requirements for algorithm-driven diagnostic tools used in donor-recipient matching will introduce additional compliance layers for integrated therapeutic platforms. Stakeholders must monitor evolving pharmacovigilance obligations across jurisdictions as real-world evidence requirements tighten for maintenance immunosuppression protocols.
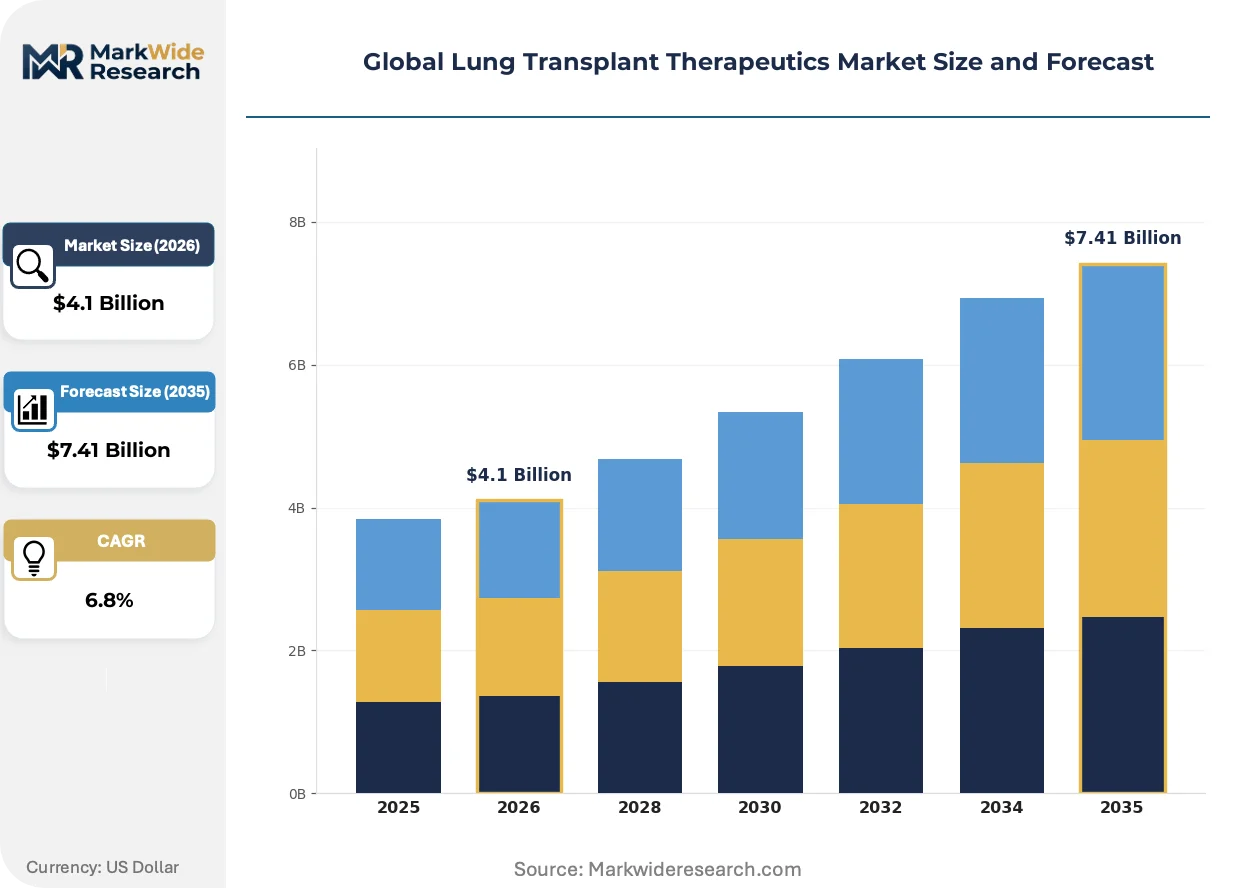
Market Dynamics
Hospital procurement consortiums are reconfiguring how lung transplant therapeutics reach end users, with centralized purchasing agreements now governing formulary placement across multi-site health systems and compressing traditional distribution margins.
Growth Catalysts
- Orphan Drug Designation:The FDA's pathway accelerates development timelines for rare disease indications, incentivizing biologics targeting chronic lung allograft dysfunction. Developers gain tax credits and market exclusivity.
- Ex Vivo Lung Perfusion:Organ preservation technology expands donor pool viability, creating companion therapeutic protocols at major transplant hubs. XVIVO Perfusion AB's platform integrates with immunosuppressant regimens.
- Japan's Organ Procurement Network:Dense referral hospital infrastructure and standardized allocation algorithms sustain procedure volume concentration. METI funding supports transplant center expansion.
Market Restraints
- Supply Concentration Risk:Calcineurin inhibitor API production concentrates in Chinese and Indian contract manufacturers. Geopolitical friction threatens active pharmaceutical ingredient continuity.
- Regulatory Friction:EMA's PRIME eligibility creates divergent assessment timelines versus FDA breakthrough therapy pathways. Developers face parallel submission complexity.
- Technical Limitation:Chronic rejection surveillance lacks validated biomarker panels. Clinicians rely on spirometry and imaging with delayed sensitivity.
Strategic Opportunities
- Inhalation Delivery Convergence:Nebulized immunosuppressant formulations combining lipid nanoparticle carriers with targeted pulmonary deposition reduce systemic exposure profiles.
- EMA Accelerated Assessment:The framework compresses review timelines for therapies addressing unmet transplant needs, creating first-mover access advantages.
- Germany's Transplant Centers:Underpenetrated eastern Länder present expansion targets for integrated therapeutic and diagnostic service platforms.
Industry Challenges
- Pharmacovigilance Talent Gap:Real-world evidence collection for maintenance immunosuppression requires specialized epidemiologists. Competition with oncology and rare disease programs constrains hiring pipelines.
- Legacy EHR Integration:Donor-recipient matching algorithms must interface with hospital information systems lacking standardized data architecture. Custom API development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lung Transplant Therapeutics Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Antibacterial Agents, Antiviral Drugs, Anti-inflammatory Medications, Antifungal Treatments Therapy Area: Chronic Obstructive Pulmonary Disease, Idiopathic Pulmonary Fibrosis, Pulmonary Hypertension, Cystic Fibrosis, Alpha-1 Antitrypsin Deficiency End User: Specialized Transplant Centers, Research Institutes, Long-term Care Facilities, Organ Procurement Organizations, Rehabilitation Clinics Delivery Mode: Oral Administration, Intravenous Injection, Subcutaneous Infusion, Inhalation Therapy, Controlled-Release Formulations |
| Companies Covered | Astellas Pharma Inc., TransMedics, F. Hoffmann-La Roche Ltd., Novartis AG, Bristol Myers Squibb, Dr. Reddy's Laboratories Ltd., Pfizer Inc., XVIVO Perfusion AB, BioLife Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lung Transplant Therapeutics Market Shifts & Advancements
Digital biomarker platforms and algorithm-driven diagnostics are compressing traditional clinical trial endpoints, forcing developers to restructure evidence-generation strategies around real-time graft monitoring.
Machine learning-based rejection risk scoring is virtualizing the traditional biopsy-dependent surveillance model. Transplant centers in the United States and Germany are piloting continuous algorithmic monitoring of donor-derived cell-free DNA. This compression of diagnostic latency is enabling earlier immunosuppressant titration and reducing acute rejection episodes.
EMA's emerging requirements under the EU AI Act for algorithm-driven diagnostic tools will introduce additional compliance layers for integrated therapeutic platforms. Developers must document training data provenance and algorithmic interpretability. The inhalation therapy segment faces the steepest adaptation curve given its convergence with digital companion diagnostics.
Consolidated purchasing agreements are displacing traditional distributor relationships across multi-site health systems in the United States. Astellas Pharma Inc. leverages its transplant-focused portfolio to sustain preferential contracting positions. German hospital networks are replicating this procurement centralization, compressing margin structures for mid-tier generic immunosuppressant suppliers.
Global Lung Transplant Therapeutics Market Segmentation
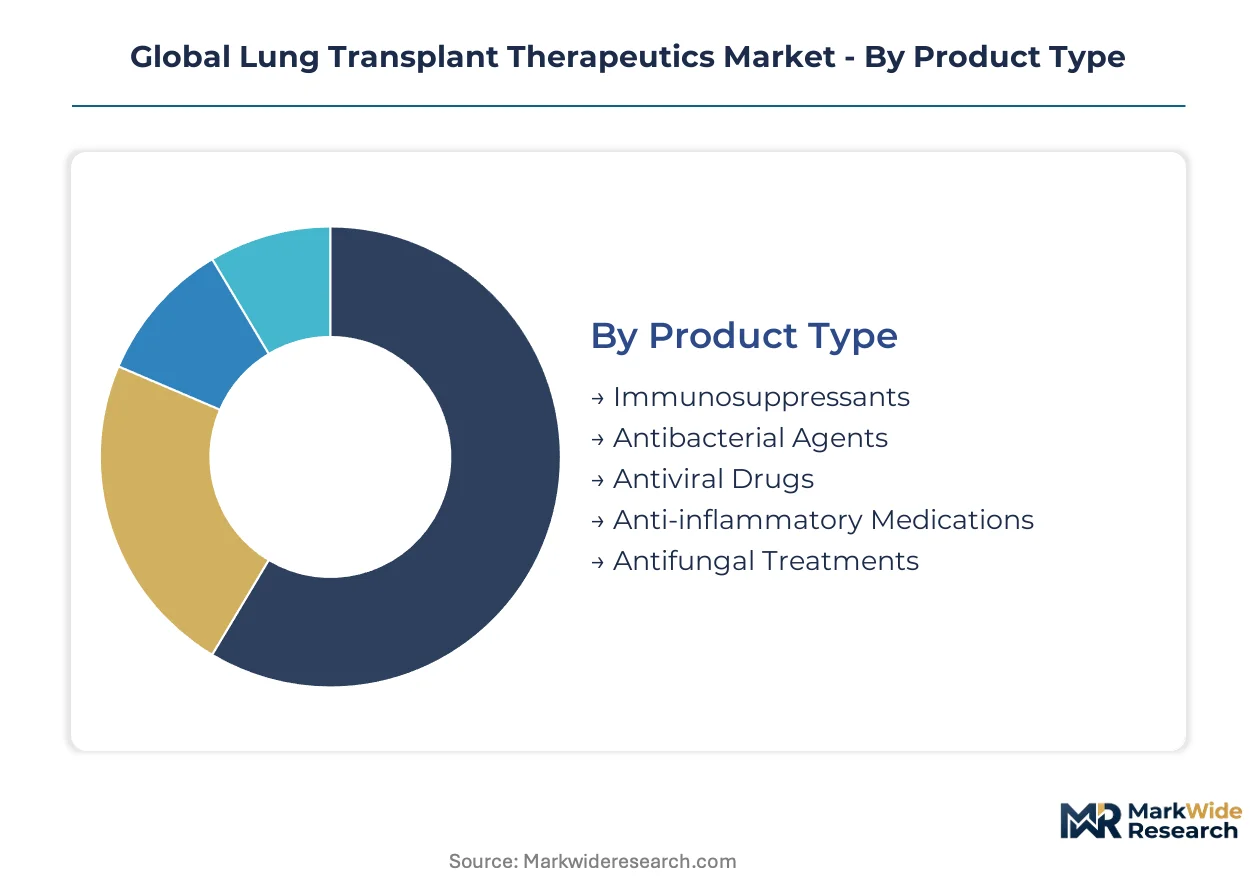
Segmentation in lung transplant therapeutics reveals distinct clinical workflows and procurement patterns. Each category maps to specific decision-makers, from formulary committees selecting immunosuppressant protocols to transplant surgeons specifying delivery modes. Understanding these divisions exposes where pricing power concentrates and where generic substitution threatens margins.
Product Type:
Clinical protocols span prophylaxis, induction, maintenance, and rescue therapy, with each phase demanding different mechanistic profiles and safety windows.
- Immunosuppressants:Calcineurin inhibitors, antiproliferative agents, and corticosteroids form the backbone of maintenance protocols. Demand clusters at specialized transplant centers in the United States, Germany, and Japan where procedure volume justifies dedicated pharmacy infrastructure and therapeutic drug monitoring capabilities.
- Antibacterial Agents:Prophylactic and empiric antibiotic regimens target opportunistic pathogens during the critical post-operative window. Procurement concentrates through hospital consortiums seeking volume discounts on broad-spectrum coverage for Pseudomonas and Staphylococcus prevention.
- Antiviral Drugs:Cytomegalovirus prophylaxis and preemptive therapy protocols.
- Anti-inflammatory Medications:Adjunctive corticosteroid-sparing approaches for chronic rejection management.
- Antifungal Treatments:Aspergillus prophylaxis in high-risk recipient profiles.
The dominant share belongs to Immunosuppressants, while Inhalation Therapy delivery modes are gaining share fastest through targeted pulmonary deposition advantages.
Therapy Area:
Disease etiology determines recipient risk stratification, organ allocation priority, and post-transplant complication profiles.
- Chronic Obstructive Pulmonary Disease:The largest recipient population with expanding transplant eligibility criteria. Transplant centers in Germany and Japan report rising volumes as bilateral lung replacement becomes standard for emphysema-dominant phenotypes.
- Idiopathic Pulmonary Fibrosis:Rapidly progressive fibrotic disease with high waitlist mortality driving urgency in organ allocation algorithms. United States centers prioritize IPF patients within lung allocation scoring systems, concentrating demand for urgent immunosuppressant induction protocols.
- Pulmonary Hypertension:Complex perioperative management requirements.
- Cystic Fibrosis:Younger recipient demographics with unique infection profiles.
- Alpha-1 Antitrypsin Deficiency:Genetic emphysema indication with targeted augmentation therapy history.
COPD maintains volume leadership, though IPF is expanding most quickly through earlier referral patterns and revised allocation scoring.
End User:
Procurement authority varies sharply across settings, from centralized hospital consortiums to fragmented long-term care networks.
- Specialized Transplant Centers:High-volume academic medical centers performing the majority of procedures. Astellas Pharma Inc. and XVIVO Perfusion AB concentrate direct sales forces here, leveraging integrated therapeutic and technology platforms to secure preferential contracting.
- Research Institutes:Early-phase clinical trial sites investigating novel immunosuppressant combinations and biomarker-driven rejection surveillance. FDA breakthrough therapy and EMA PRIME designations channel investigational supply to these centers.
- Long-term Care Facilities:Post-discharge maintenance therapy administration.
- Organ Procurement Organizations:Perfusion solution and preservation therapeutic procurement.
- Rehabilitation Clinics:Pulmonary function recovery and medication adherence support.
Specialized Transplant Centers command the largest procurement budgets, while Research Institutes are climbing fastest through expanded investigator-initiated trial funding.
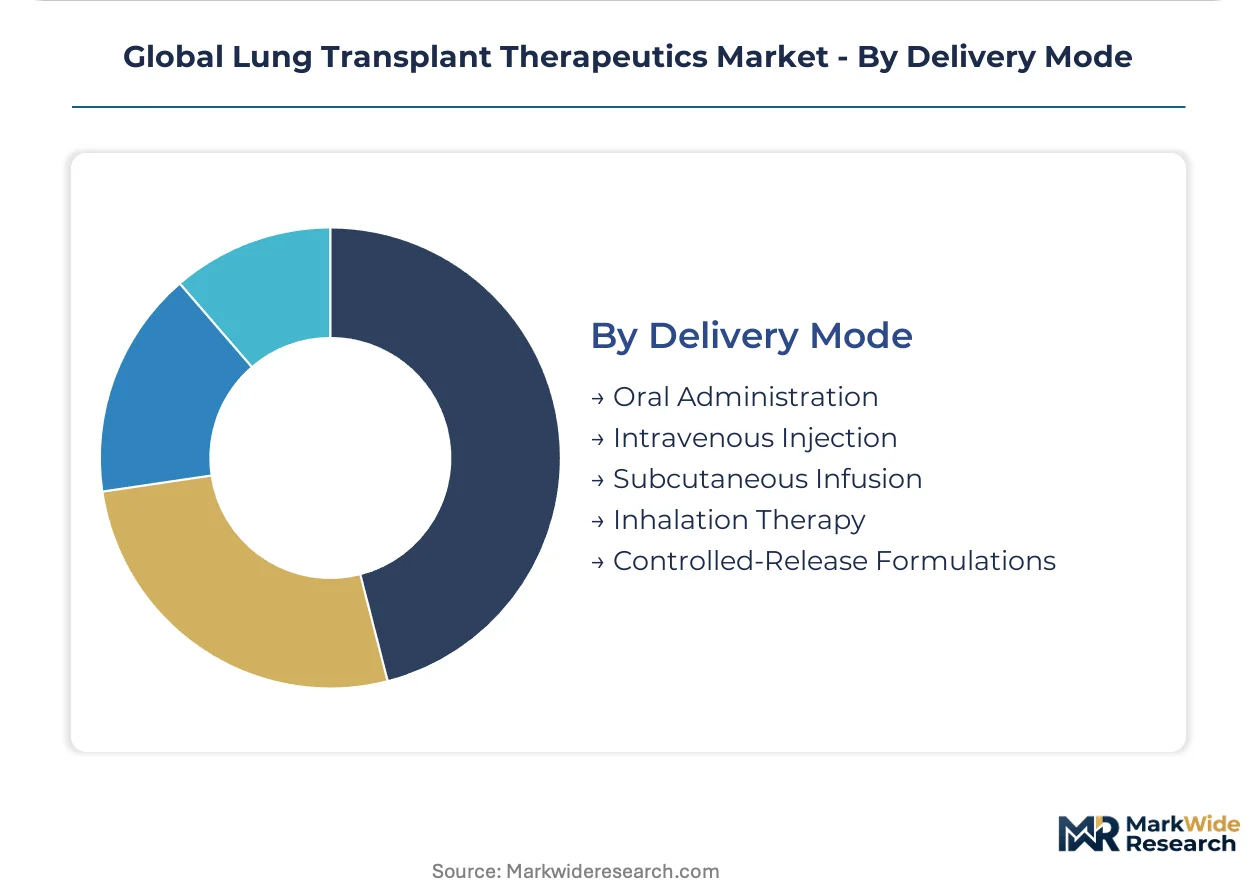
Delivery Mode:
Route selection balances systemic exposure, pulmonary targeting, and patient compliance across the post-transplant timeline.
- Oral Administration:Tacrolimus, mycophenolate, and prednisone tablets dominate maintenance phases. Patient adherence programs and generic substitution pressure characterize this mature segment where cost tier differentiation determines formulary placement.
- Inhalation Therapy:Nebulized immunosuppressant formulations with lipid nanoparticle carriers enable direct pulmonary deposition. German and United States transplant hubs are piloting these protocols to reduce systemic calcineurin inhibitor exposure and nephrotoxicity.
- Intravenous Injection:Perioperative induction and rescue therapy.
- Subcutaneous Infusion:Emerging depot formulations for adherence optimization.
- Controlled-Release Formulations:Extended-release tacrolimus for trough level stability.
Oral Administration retains the dominant position, though Inhalation Therapy shows the steepest expansion trajectory through technology convergence with digital companion diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations and EMA accelerated assessment frameworks concentrate developer investment in jurisdictions with established regulatory pathways and dense transplant infrastructure.
United States
High-volume academic medical centers in Pittsburgh, Houston, and Cleveland sustain the world's largest lung transplant procedure volume. CMS reimbursement policies for immunosuppressive drugs create predictable revenue streams for maintenance therapy suppliers. The United Network for Organ Sharing allocation algorithm revision in 2017 concentrated IPF patients at specialized centers, intensifying demand for urgent induction protocols.
Germany
Transplant centers in Bavaria and North Rhine-Westphalia report rising bilateral lung replacement volumes for COPD-dominant phenotypes. The German Transplantation Society's standardized follow-up protocols mandate therapeutic drug monitoring, entrenching calcineurin inhibitor demand. Underpenetrated eastern Länder present expansion targets for integrated therapeutic platforms.
Japan
METI funding supports transplant center expansion in Tokyo, Osaka, and Nagoya. The Japan Organ Transplant Network's standardized allocation algorithms sustain procedure concentration at high-volume sites. Dense referral hospital infrastructure enables rapid post-operative therapeutic intervention.
United Kingdom
NHS England's specialized commissioning framework concentrates lung transplantation at Papworth and Harefield. NICE technology appraisals for immunosuppressant regimens create formulary gatekeeping. Research institutes in London and Cambridge pilot digital biomarker platforms for rejection surveillance.
Switzerland
Swissmedic's alignment with EMA centralized procedures accelerates market access for novel maintenance therapies. University Hospital Zurich and Geneva University Hospitals anchor a small but high-intensity transplant cluster. Bilateral research partnerships with German centers extend protocol development capabilities.
Global Lung Transplant Therapeutics Market Competitive Landscape
On the supply side, the industry is consolidated around a handful of integrated pharmaceutical portfolios and specialized organ technology providers. Large-cap developers with transplant-focused therapeutic franchises compete against mid-sized perfusion technology specialists. Two strategic archetypes dominate: diversified immunosuppressant manufacturers and organ preservation platform operators. Competitive moves center on hospital procurement consortium penetration and companion diagnostic integration.
Among diversified pharmaceutical developers, Astellas Pharma Inc. and F. Hoffmann-La Roche Ltd. exemplify the integrated portfolio archetype. Novartis AG occupies a position within the calcineurin inhibitor segment. On the technology side, XVIVO Perfusion AB anchors the organ preservation specialist tier. These named entities represent the structural concentration visible in procurement data and transplant center contracting patterns.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| TransMedics |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Bristol Myers Squibb |
| Dr. Reddy's Laboratories Ltd. |
| Pfizer Inc. |
| XVIVO Perfusion AB |
| BioLife Solutions |
| Others |
Supply & Pricing Matrix
Chinese and Indian contract manufacturers concentrate calcineurin inhibitor API production, anchoring margin capture at the upstream synthesis tier while transplant centers and hospital consortiums extract value through formulary gatekeeping and volume contracting downstream.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating originator immunosuppressants from authorized generics and commodity API-sourced alternatives. Price differentiation rests on FDA breakthrough therapy designation status and therapeutic drug monitoring service bundling. Cost compression in the generic tier is intensifying because hospital consortiums centralize purchasing across multi-site health systems. Long-term care facilities exhibit the highest price sensitivity due to reimbursement rate constraints, while specialized transplant centers prioritize clinical outcome guarantees over per-unit cost.
Supply Chain Analysis
Extended payment terms from hospital procurement consortiums are reshaping supplier cash flow dynamics, with supply-chain finance facilities increasingly bridging manufacturing-to-delivery gaps. Active pharmaceutical ingredient production concentrates in China, India, and Switzerland, drawing from tacrolimus, mycophenolate mofetil, and cyclosporine chemical precursors. Single-source vulnerability threatens continuity for calcineurin inhibitor intermediates given geopolitical friction. Distribution runs through regional pharmaceutical wholesalers serving hospital networks and specialized transplant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
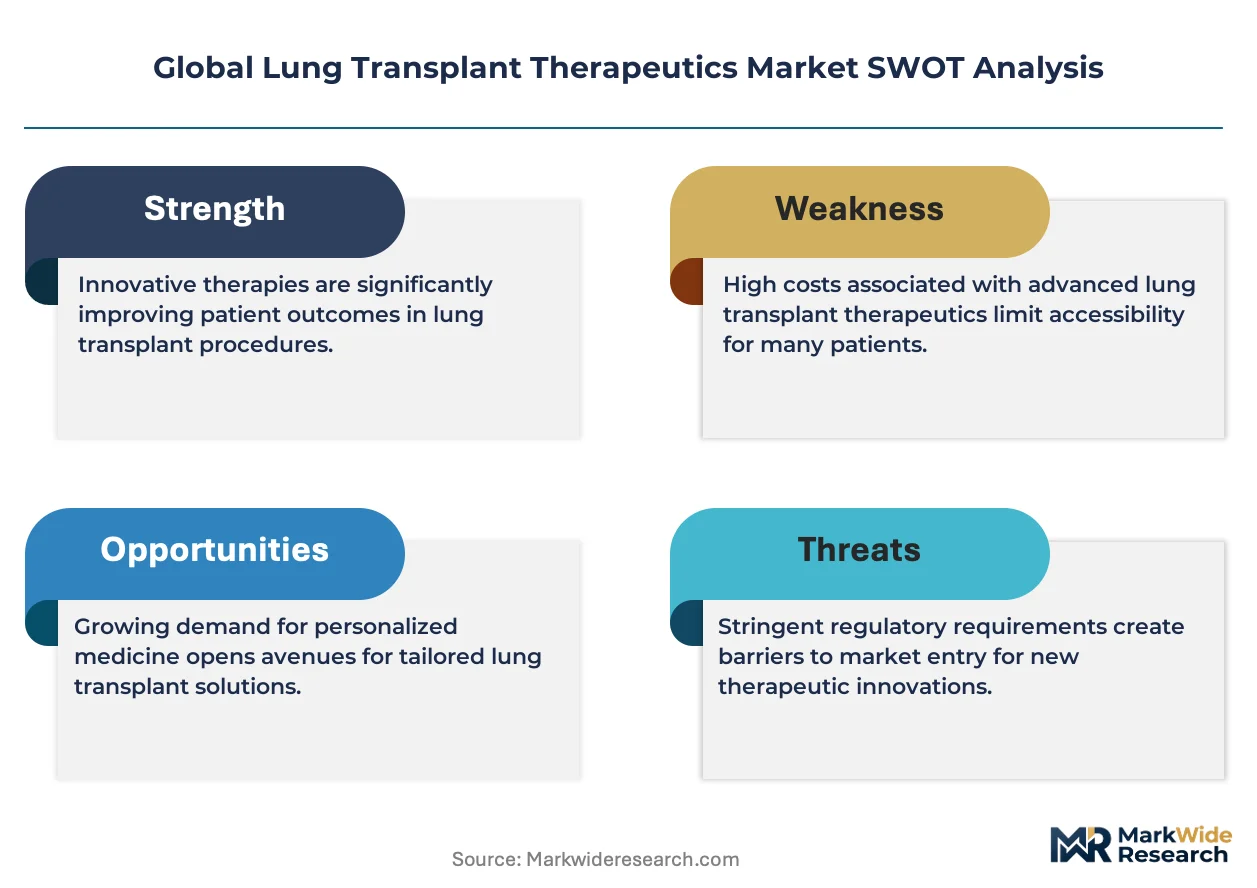
The lung transplant therapeutics market functions as a defensive-moat story where regulatory entrenchment through FDA orphan drug designation and EMA PRIME eligibility creates durable barriers to competitive replication.
For Market Incumbents: Build switching-cost moats by embedding therapeutic drug monitoring services into maintenance immunosuppressant contracts, locking transplant centers into integrated platforms. Pursue backward integration into organ preservation technology to capture companion protocol revenue. Generic substitution pressure from Dr. Reddy's Laboratories Ltd. and mid-tier API suppliers threatens margin pools in the oral administration segment. Capacity addition in inhalation therapy manufacturing secures first-mover positioning in nebulized immunosuppressant formulations. For New Entrants and Emerging Players: Establish a beachhead in the inhalation therapy delivery mode segment where lipid nanoparticle carrier technology remains underpenetrated relative to oral administration dominance. Eastern Länder in Germany present the most penetrable geography given underdeveloped transplant center density and receptive hospital procurement networks. A go-to-market angle anchored to EMA accelerated assessment pathway navigation offers faster access advantages than FDA breakthrough therapy competition. For Investors and Strategic Acquirers: Capital is best deployed toward organ preservation platform operators with companion therapeutic integration capabilities, given their structural positioning at the intersection of expanding donor pools and immunosuppressant protocol design. Long-term viability over a multi-year horizon hinges on digital biomarker convergence for rejection surveillance. The signal to watch as inflection indicator is FDA approval velocity for algorithm-driven diagnostic tools paired with maintenance therapy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for chronic lung allograft dysfunction biologics. |
| Hospital System Partnership | Preferential contracting with specialized transplant centers secures formulary placement across multi-site networks. |
| Software Companion Development | Machine learning-based rejection risk scoring virtualizes biopsy-dependent surveillance models at German and United States hubs. |
| Manufacturing Scale-Up | Capacity expansion in lipid nanoparticle carrier production supports nebulized immunosuppressant formulation growth. |
| Pipeline Diversification | EMA PRIME eligibility channels investigational supply to early-phase clinical trial sites investigating novel combinations. |
Research Methodology
Cross-validation between primary interviews with transplant surgeons, formulary directors, hospital procurement managers, and regulatory affairs specialists anchors the qualitative findings, while secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up demand modeling across immunosuppressant, antibacterial, antiviral, and inhalation therapy segments triangulates with top-down market sizing.
Calibration against historical procedure volume data and immunosuppressant utilization rates at specialized transplant centers in the United States, Germany, and Japan informs the analytical framework across the projection horizon. Segmentation dimensions include product type, therapy area, end user, and delivery mode alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves applied to base-year market estimates, with inputs including organ allocation algorithm revisions and ex vivo lung perfusion adoption trajectories.
Sensitivities concentrate around regulatory approval delays, API supply disruptions, and reimbursement policy shifts. Forecasts reflect documented assumptions regarding procedure volume growth and therapeutic protocol evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Neurodegenerative Disease Market