
 Generalized Anxiety Disorder (GAD) Market | 2026-2036
Generalized Anxiety Disorder (GAD) Market Size, Share, and Industry Trends Forecast 2026-2036
Generalized Anxiety Disorder (GAD) Market Foresight
Next-generation anxiolytic efficacy standards is bifurcating the competitive landscape into precision-targeted and broad-spectrum portfolios. Pfizer Inc. leverages its established neuroscience infrastructure to sustain commercial reach across psychiatric clinics and outpatient facilities. Eli Lilly and Company differentiates through R&D intensity in novel mechanism antidepressants with anxiety indications. H. Lundbeck A/S specializes in CNS-focused development, anchoring its position within European and North American regulatory corridors.
Generalized Anxiety Disorder constitutes a chronic psychiatric condition characterized by persistent, excessive worry and associated somatic symptoms lasting six months or more, with diagnostic criteria specified in the DSM-5 requiring impairment in social, occupational, or other functional domains. The condition primarily serves clinical and commercial purposes through management of debilitating anxiety symptoms that drive healthcare utilization and productivity loss. Pharmacotherapy dominates current revenue pools, particularly Selective Serotonin Reuptake Inhibitors and Serotonin-Norepinephrine Reuptake Inhibitors, where established safety profiles sustain prescriber confidence. Teletherapy within the Delivery Mode dimension represents the fastest-expanding channel, though in-person consultation retains higher reimbursement rates and clinical trial validation.
The FDA governs new drug approvals and label expansions for anxiolytic therapies, while the DEA regulates controlled substance scheduling that constrains benzodiazepine prescribing patterns. EMA oversight through centralized marketing authorization procedures shapes access timelines across European member states, with national health technology assessment bodies subsequently determining reimbursement. Stakeholders must monitor evolving digital therapeutics classification frameworks as regulators distinguish between wellness applications and clinically validated interventions.
Market Dynamics
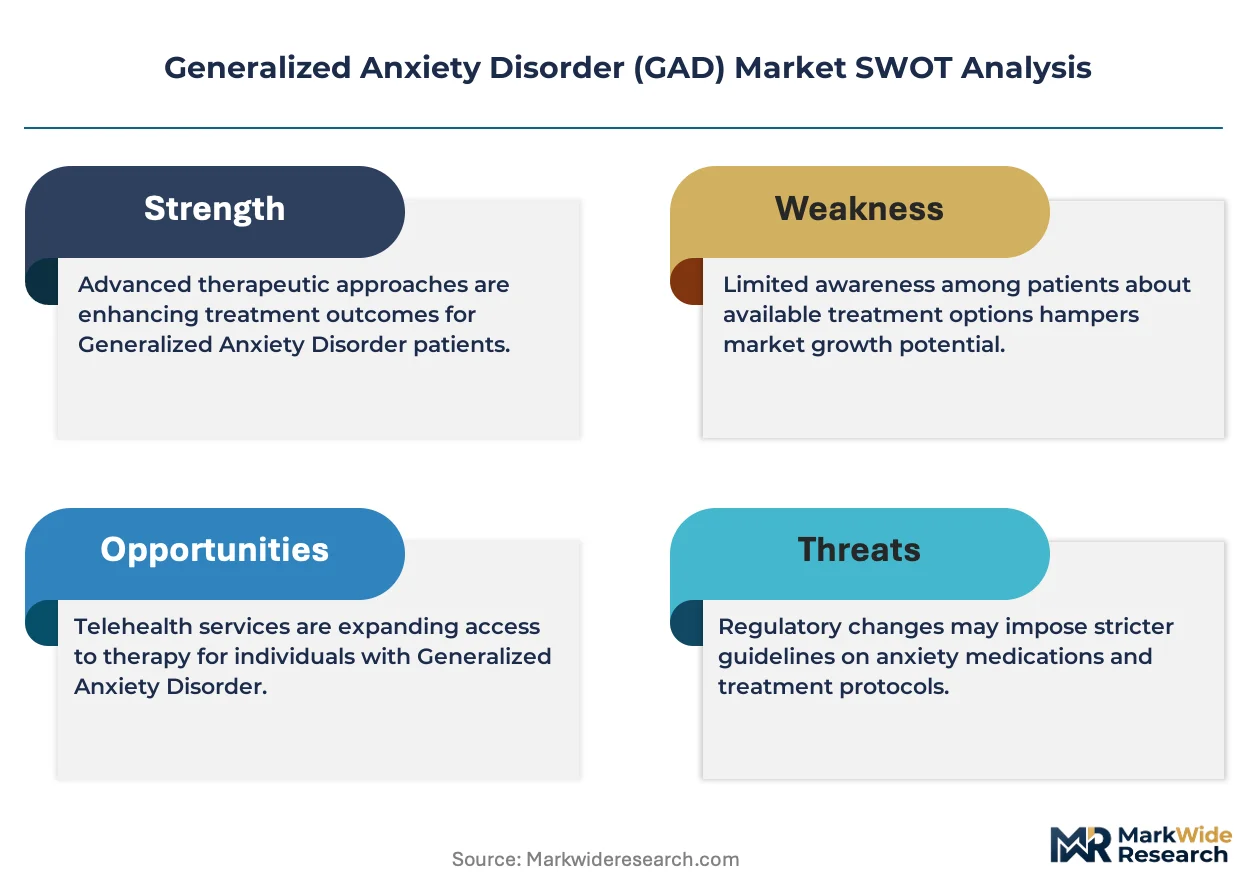
The FDA's accelerated approval pathways for central nervous system therapies are compressing development timelines while simultaneously fragmenting prescriber confidence between established and novel mechanisms.
Growth Catalysts
- Integrated care models:Psychiatric clinics are consolidating behavioral health services with primary care, creating bundled reimbursement opportunities that expand addressable patient populations.
- Digital health infrastructure:Telehealth platforms in the United States are extending specialist reach into underserved counties, reducing geographic barriers to diagnosis and maintenance therapy.
- EMA centralized procedures:Streamlined marketing authorization across European member states is reducing regulatory duplication costs for developers with CNS-focused portfolios.
Market Restraints
- Benzodiazepine scheduling constraints:DEA controlled substance classifications limit prescribing flexibility and impose inventory tracking burdens on outpatient facilities.
- Placebo response variability:High and inconsistent placebo rates in anxiety trials inflate sample size requirements and extend study durations.
- Generic SSRI/SNRI saturation:Patent expirations have commoditized first-line pharmacotherapy, compressing branded pricing power and R&D return thresholds.
Strategic Opportunities
- Digital therapeutics classification:Regulators are distinguishing clinically validated interventions from wellness applications, opening reimbursement pathways for prescription-grade software.
- Pharmacogenomic integration:Biomarker-guided dosing protocols are converging with electronic health record systems to enable personalized anxiolytic selection.
- Rural telepsychiatry networks:Federally qualified health centers in the United States are deploying asynchronous consultation models to reach frontier populations.
Industry Challenges
- Psychiatric trial recruitment:Patient retention in placebo-controlled anxiety studies requires intensive site support and digital adherence monitoring.
- Legacy EHR interoperability:Behavioral health data segmentation between systems impedes care coordination and outcome tracking across settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generalized Anxiety Disorder (GAD) Market |
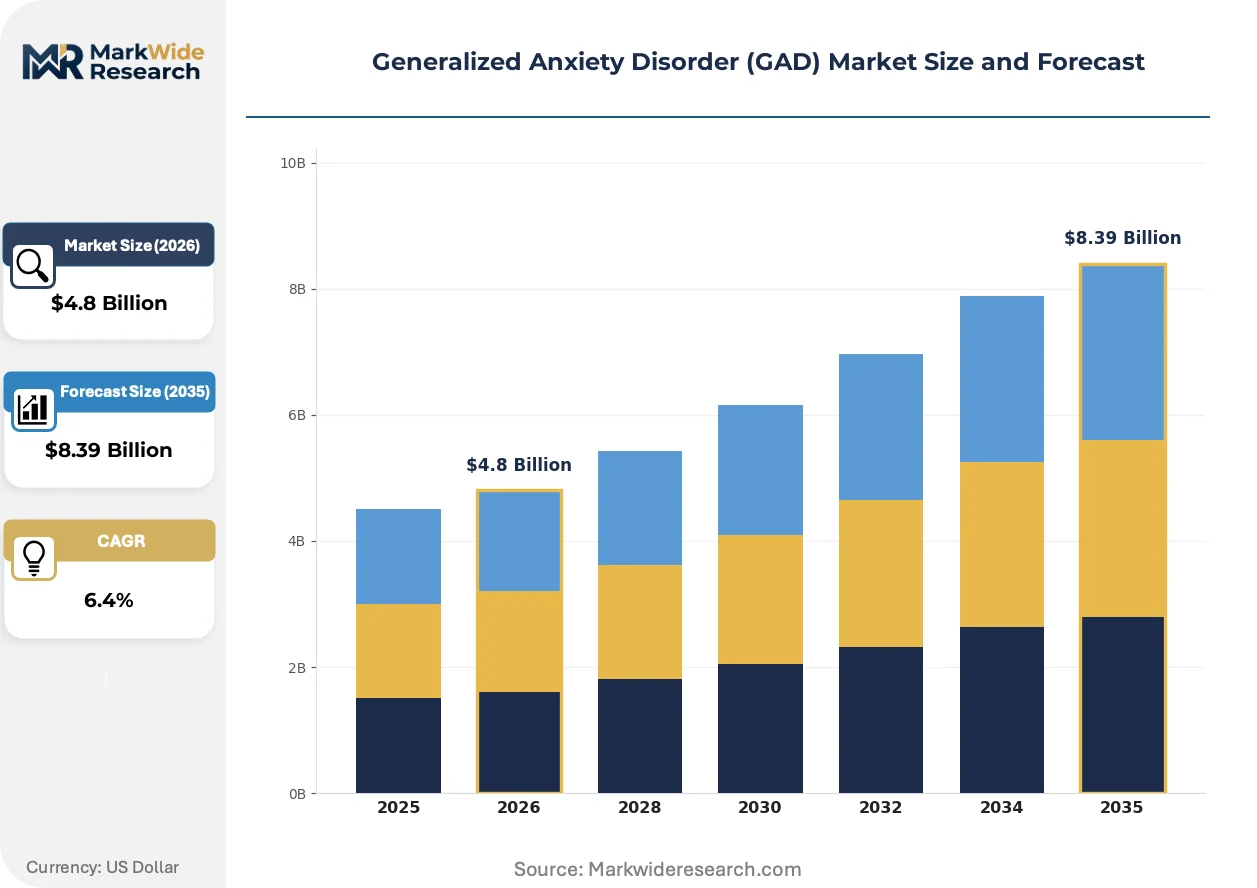
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Cognitive Behavioral Therapy, Pharmacotherapy, Mindfulness-Based Therapy, Psychodynamic Therapy, Acceptance & Commitment Therapy Product Type: Selective Serotonin Reuptake Inhibitors, Serotonin-Norepinephrine Reuptake Inhibitors, Benzodiazepines, Buspirone, Beta Blockers End User: Psychiatric Clinics, Outpatient Facilities, Mental Health Hospitals, Primary Care Centers Delivery Mode: In-person Consultation, Teletherapy, Mobile Applications, Online Self-Help Programs, Group Therapy |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Eli Lilly and Company, Bristol-Myers Squibb, Johnson & Johnson, H. Lundbeck A/S, AstraZeneca, Sanofi SA, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generalized Anxiety Disorder (GAD) Market Shifts & Advancements
Prescription digital therapeutics are bifurcating treatment pathways between software-based interventions and traditional pharmacotherapy, forcing developers to demonstrate comparative efficacy against both placebo and active drug controls.
Transcranial magnetic stimulation protocols are supplanting augmentation strategies for treatment-resistant cases. Academic medical centers are embedding TMS suites within mood disorder clinics, compressing referral-to-treatment intervals. The technology is enabling psychiatrists to offer device-based alternatives before trialing third-line pharmacotherapy.
EMA's evolving guidance on central nervous system biomarkers is reshaping trial design requirements. Developers must now pre-specify cognitive endpoints and functional impairment measures alongside traditional symptom scales. Early-phase programs targeting European approval are restructuring protocols to accommodate these evidentiary demands.
Patient-driven switching between teletherapy and in-person modalities is fragmenting continuity of care. Large employer health plans are responding with hybrid benefit structures that reimburse both channels at parity. This behavioral shift is most pronounced in metropolitan United States markets where platform competition has compressed session pricing.
Generalized Anxiety Disorder (GAD) Market Segmentation
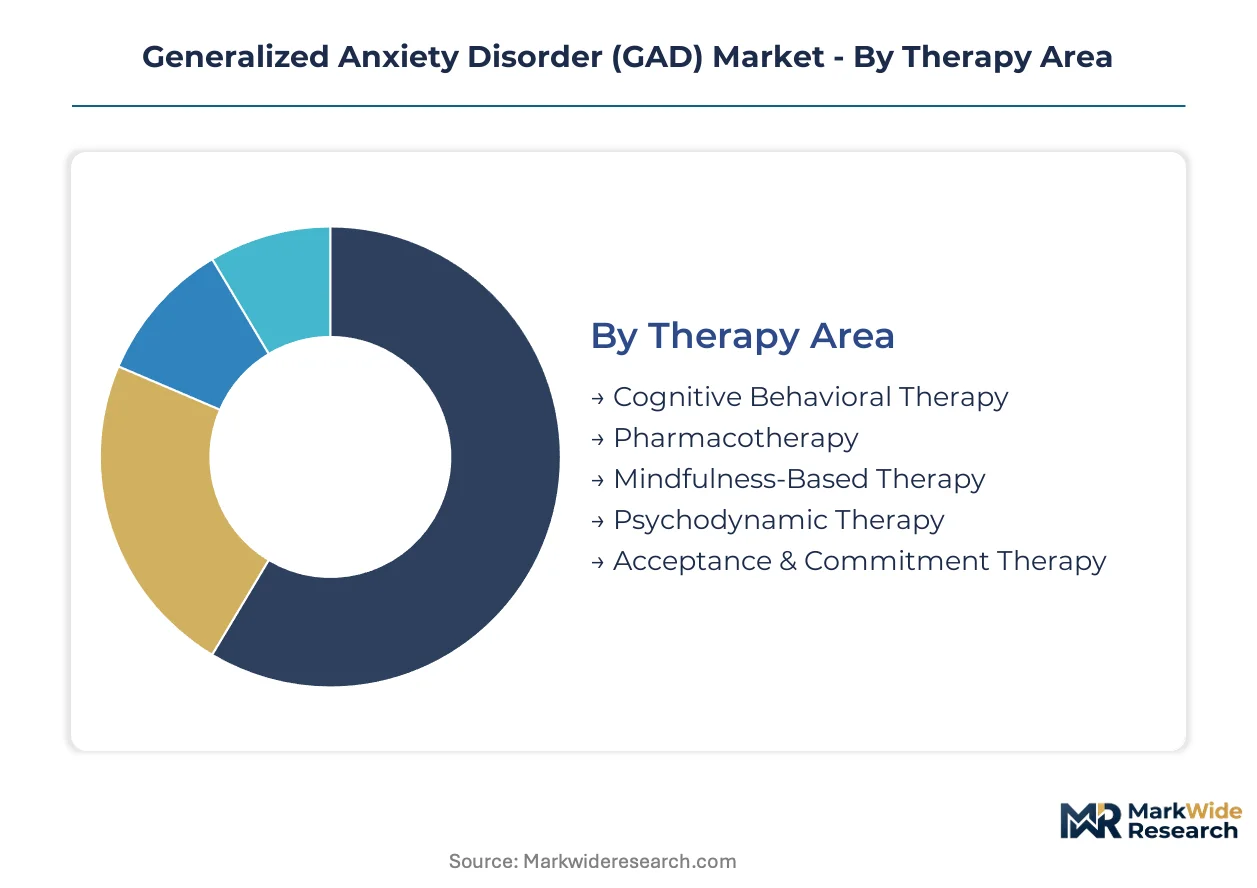
Treatment pathway selection in the Generalized Anxiety Disorder market hinges on symptom severity, comorbidity profiles, and reimbursement infrastructure. Segmentation reveals how clinical decision-making fragments across settings and modalities, with each category carrying distinct regulatory and commercial constraints.
Therapy Area:
Geographic penetration varies sharply by therapy type, with cognitive and behavioral modalities concentrated in North American and Western European markets while pharmacotherapy dominates emerging economies with limited specialist access.
- Cognitive Behavioral Therapy:Structured, time-limited psychotherapy targeting maladaptive thought patterns through behavioral activation and cognitive restructuring. Demand clusters in the United States and United Kingdom where licensed practitioner networks and insurance carve-outs sustain outpatient delivery. The modality faces capacity constraints from training pipeline limitations.
- Pharmacotherapy:Systemic drug intervention using serotonergic, noradrenergic, or GABA-ergic mechanisms to modulate anxiety circuitry. Volume concentrates in primary care centers across Germany and France where physician prescribing authority bypasses specialist referral requirements. Generic saturation compresses branded investment returns.
- Mindfulness-Based Therapy:Meditative attention training protocols adapted from MBSR curricula for anxiety-specific applications. Adoption spreads through employer wellness programs and direct-to-consumer digital platforms.
- Psychodynamic Therapy:Long-term exploratory treatment examining unconscious conflict and early relational patterns. Reimbursement restrictions in managed care environments limit growth outside private-pay markets.
- Acceptance & Commitment Therapy:Third-wave behavioral intervention emphasizing psychological flexibility and valued action. Clinical trial expansion in Australia and the Netherlands supports evidence base development.
Pharmacotherapy commands the established base. The steepest expansion runs through teletherapy-enabled Cognitive Behavioral Therapy delivery.
Product Type:
Cost tier stratification separates premium patented mechanisms from commoditized first-line agents, with pricing power inversely correlated to generic substitution rates.
- Selective Serotonin Reuptake Inhibitors:First-line serotonergic agents including sertraline, escitalopram, and paroxetine with established anxiolytic efficacy. Escitalopram maintains residual branded volume in Japan and Canada where formulation patents persist. Tolerability advantages drive prescriber preference over older tricyclic alternatives.
- Serotonin-Norepinephrine Reuptake Inhibitors:Dual-mechanism agents such as venlafaxine and duloxetine targeting both neurotransmitter systems. Duloxetine captures comorbid pain-anxiety presentations in United States Veterans Affairs systems. Noradrenergic component adds discontinuation syndrome liability.
- Benzodiazepines:GABA-A positive allosteric modulators including alprazolam and lorazepam for acute symptom control. DEA Schedule IV classification imposes dispensing limits and prescriber registration requirements.
- Buspirone:Serotonin 5-HT1A partial agonist lacking sedation or dependence liability. Generic availability restricts commercial promotion investment.
- Beta Blockers:Adrenergic antagonists such as propranolol targeting somatic anxiety manifestations. Off-label use for performance anxiety sustains niche demand.
SSRI/SNRI categories anchor volume. The most rapid share gains accrue to novel mechanism candidates in late-stage pipelines.
End User:
Customer type fragmentation reflects care cascade design, with gatekeeping functions determining which settings capture initial diagnosis and longitudinal management.
- Psychiatric Clinics:Specialist-directed care with diagnostic expertise and complex case management capacity. Integrated care contracts in the United States bundle psychiatric and psychotherapy services under single reimbursement structures.
- Outpatient Facilities:Community-based delivery with lower overhead and extended appointment availability. Federally qualified health centers in rural United States counties deploy psychiatric nurse practitioners to extend prescriber reach.
- Mental Health Hospitals:Inpatient and partial hospitalization programs for crisis stabilization and severe comorbidity management. Length-of-stay compression redirects volume to lower-acuity settings.
- Primary Care Centers:Frontline diagnosis and maintenance prescribing in systems with limited specialist density. United Kingdom NHS Improving Access to Psychological Therapies program embeds counselors in general practice.
Primary care settings absorb the majority of incident cases. Psychiatric clinics generate the highest per-patient revenue through bundled service models.
Delivery Mode:
Supply concentration in digital infrastructure separates platform-enabled modalities from facility-dependent delivery, with capital requirements determining competitive entry barriers.
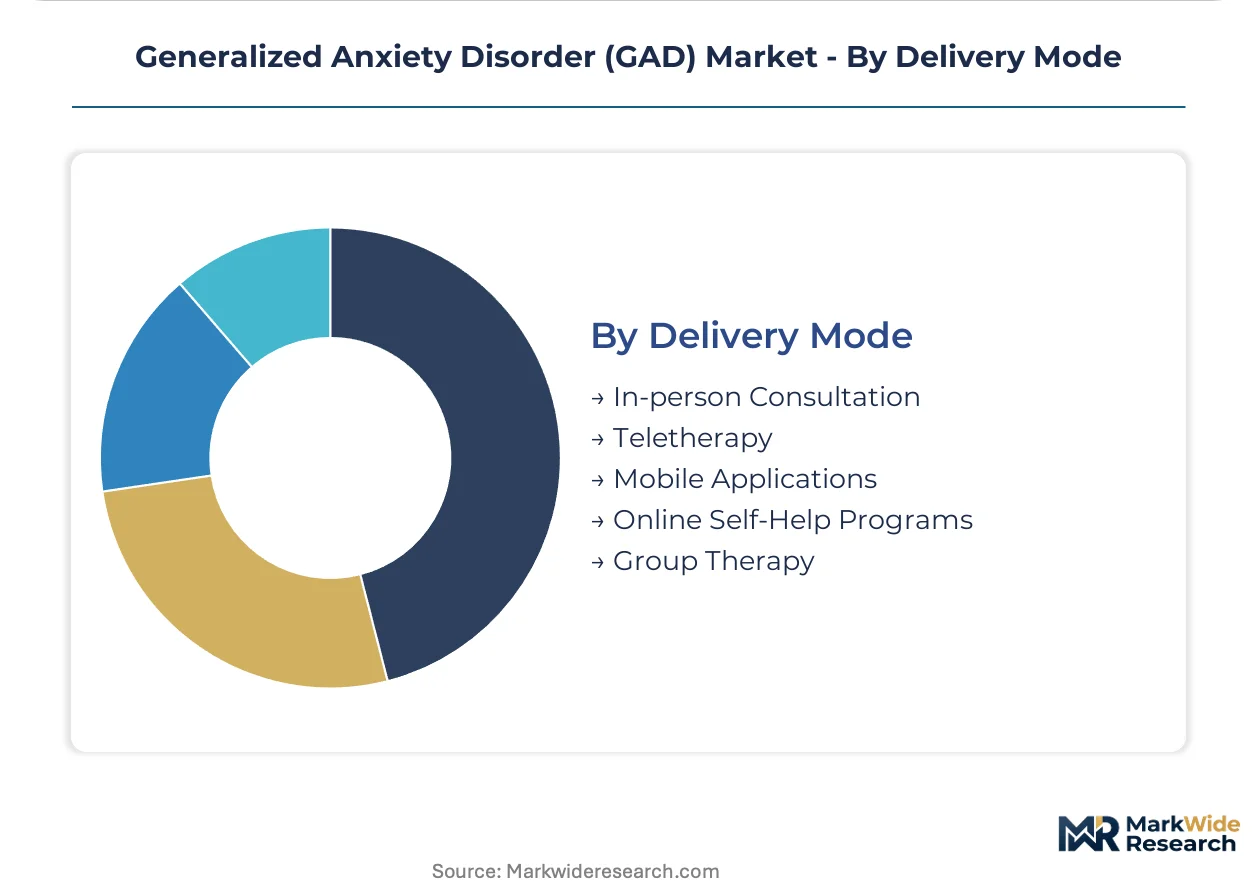
- In-person Consultation:Face-to-face therapeutic encounter with established efficacy evidence and higher reimbursement rates. Metropolitan United States markets sustain premium pricing for private practice psychiatrists.
- Teletherapy:Synchronous video-based mental health delivery extending specialist access beyond geographic constraints. State licensure compacts in the United States enable cross-border practitioner deployment.
- Mobile Applications:Smartphone-delivered interventions ranging from mood tracking to structured cognitive behavioral protocols. FDA breakthrough device designation pathways validate prescription-grade software.
- Online Self-Help Programs:Asynchronous web-based curricula with limited or no clinician involvement. Employer health plans in Germany subsidize subscription access as prevention investment.
- Group Therapy:Multi-participant sessions reducing per-patient cost and leveraging peer normalization effects. Community mental health centers in Canada deploy trauma-informed groups for refugee populations.
In-person consultation retains reimbursement advantage. Teletherapy platforms are gaining share fastest through employer benefit expansion and licensure portability reforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist psychiatric infrastructure concentrates in the United States and Western Europe, while generic manufacturing capacity clusters in India and Israel. Regulatory pathway efficiency varies sharply across these jurisdictions, reshaping where developers prioritize trial enrollment and commercial launches.
United States
FDA accelerated approval pathways for CNS therapies compress development timelines for novel anxiolytic mechanisms. The DEA's Schedule IV classification of benzodiazepines imposes dispensing limits that constrain legacy prescribing patterns. Psychiatric clinic density peaks in metropolitan corridors from Boston to San Francisco, where integrated care contracts bundle behavioral health with primary care reimbursement.
Germany
EMA centralized marketing authorization procedures streamline access across member states for developers with European psychiatric portfolios. Federal health technology assessment through IQWiG determines reimbursement parity between pharmacotherapy and psychotherapy modalities. The Rhine-Ruhr and Munich clusters host the continent's densest concentration of mood disorder research sites and specialist outpatient networks.
United Kingdom
NHS Improving Access to Psychological Therapies program embeds counselors in general practice, expanding CBT reach beyond traditional specialist gatekeeping. NICE guideline updates reshape formulary positioning for SSRI and SNRI selections across primary care trusts. London and the Southeast sustain the national majority of psychiatric research infrastructure and digital health pilot programs.
Japan
PMDA regulatory reforms for psychiatric drug development have shortened review timelines for agents with novel mechanisms. Escitalopram formulation patents sustain residual branded volume in a market historically resistant to generic substitution. Tokyo and Osaka metropolitan areas concentrate specialist psychiatrist density and academic medical center trial capacity.
India
CDSCO streamlined approval pathways for psychiatric generics support export-oriented manufacturing to regulated markets. Domestic demand concentrates in urban corridors where specialist access remains limited and primary care physicians manage the majority of anxiety diagnoses. Hyderabad and Mumbai clusters host active pharmaceutical ingredient production for global SSRI and SNRI supply chains.
Generalized Anxiety Disorder (GAD) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Generalized Anxiety Disorder market. Established neuroscience infrastructure separates developers with integrated psychiatric portfolios from generic manufacturers competing on price. Three archetypes dominate: multinational pharmaceutical conglomerates with CNS divisions, mid-cap specialists focused exclusively on mood and anxiety disorders, and high-volume generic producers. Consolidation through targeted acquisitions of late-stage CNS assets and strategic partnerships for digital therapeutic co-development represent the primary competitive vectors reshaping market structure.
Among the multinational pharmaceutical conglomerates, Pfizer Inc., Eli Lilly and Company, and H. Lundbeck A/S exemplify divergent strategic positioning within the CNS therapeutic space. Pfizer occupies a position anchored by established neuroscience commercial infrastructure spanning psychiatric clinics and outpatient facilities. Eli Lilly represents the R&D-intensive archetype prioritizing novel mechanism antidepressants with anxiety indications. H. Lundbeck A/S sits within the specialist tier, with portfolio concentration reflecting dedicated CNS development expertise across European and North American regulatory corridors.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| H. Lundbeck A/S |
| AstraZeneca |
| Sanofi SA |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient manufacturing scale in India and China anchors global cost floors for serotonergic and GABA-ergic compounds, compressing margins for branded developers while enabling generic saturation that reshapes prescriber tier preferences across reimbursement systems.
Pricing Analysis
DEA Schedule IV classification dictates the pricing tier structure for benzodiazepine-containing portfolios, separating controlled-substance premiums from unrestricted generic alternatives. Three-tier pricing structure across patented novel mechanisms, branded reformulations, and commoditized SSRI/SNRI generics stratifies prescriber access by insurance formulary depth. Cost compression in first-line pharmacotherapy intensifies as Indian and Israeli manufacturers expand API export capacity. Primary care centers exhibit highest price sensitivity, while psychiatric clinics with bundled reimbursement contracts absorb premium-tier therapies with reduced friction.
Supply Chain Analysis
Just-in-time inventory preferences dominate finished dose distribution, while strategic stockpiling of API concentrates around regulatory inspection cycles and patent cliff timing. Supply concentrates in India for sertraline and escitalopram intermediates, China for venlafaxine precursors, and Israel for specialized CNS active compounds. Raw material dependencies include 5-HTP fermentation feedstocks, noradrenergic receptor ligands, and GABA-A modulator scaffolds. Single-source vulnerability runs through Hyderabad API clusters subject to FDA inspection backlogs. Distribution runs through wholesale distributors to retail pharmacy chains and direct-to-clinic specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Teletherapy platform penetration remains below saturation across rural United States counties and European periphery markets, creating runway for modality expansion before reimbursement parity compresses differentiation.
For Market Incumbents: Compound defensive moats through backward integration into digital therapeutic development and captive telehealth infrastructure deployment. Pfizer Inc. and Eli Lilly and Company face emerging entrant pressure from prescription-grade software developers with FDA breakthrough device designations. Priority investment in pharmacogenomic biomarker platforms enables personalized dosing protocols that sustain pricing power against generic substitution.
For New Entrants and Emerging Players: Lead with asynchronous consultation models targeting Federally qualified health centers in frontier United States counties where psychiatrist density falls below national thresholds. White-space concentration appears in employer-sponsored digital mental health benefits outside metropolitan corridors. Go-to-market positioning through hybrid benefit structures reimbursing teletherapy and in-person modalities at parity captures switching behavior fragmentation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with late-stage novel mechanism pipelines and validated digital therapeutic endpoints. Long-term viability hinges on demonstrating comparative efficacy against active drug controls rather than placebo alone. Acquisition target archetype includes mid-cap CNS specialists with EMA centralized procedure experience and embedded European regulatory affairs capacity. Signal to watch: FDA label expansion decisions for multimodal depression-anxiety indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Novel mechanism candidates with biomarker endpoints reshape FDA submission requirements for CNS therapies. |
| Regulatory Approval Pathway | EMA centralized procedures reduce duplication costs for developers with European psychiatric portfolios. |
| Licensing Agreement | Digital therapeutic co-development partnerships bridge software validation and pharmaceutical commercial infrastructure. |
| Manufacturing Scale-Up | API capacity expansion in Hyderabad and Mumbai clusters supports global SSRI supply chain resilience. |
| Pipeline Diversification | Transcranial magnetic stimulation device portfolios augment pharmacotherapy for treatment-resistant case management. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists converged on the working assumptions underlying market size and growth trajectory estimates. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored volume and value outputs.
Segmentation dimensions modeled include therapy area, product type, end user, and delivery mode across the projection horizon. CAGRs derived from historical growth rate analysis adjusted for regulatory pathway efficiency and reimbursement policy shifts. Forecast inputs incorporated teletherapy adoption curves, generic substitution rates, and digital therapeutic classification framework evolution.
Underlying assumptions cover FDA accelerated approval pathway stability, DEA scheduling continuity, and EMA biomarker guidance implementation, with deviation risk concentrated in placebo response variability and digital health reimbursement parity timing. Revision becomes warranted when teletherapy platform consolidation crosses monopoly threshold or when novel mechanism clinical trial failure rates exceed historical CNS averages.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market