
 Global Ion Exchange Membrane Market | 2026-2036
Global Ion Exchange Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ion Exchange Membrane Market Intelligence
The divergence in manufacturing scale between vertically integrated producers and niche specialists is redrawing competitive lines. DuPont de Nemours, Inc. leverages its vast polymer science portfolio to innovate across multiple applications. Asahi Kasei sustains a dominant position in membranes for the chlor-alkali process. Concurrently, LANXESS specializes in high-performance solutions for industrial water treatment and metal recovery.
An ion exchange membrane is a semipermeable barrier designed to transport specific dissolved ions while blocking others. These membranes are typically fabricated from polymer materials, such as perfluorosulfonic acid (PFSA), to achieve selective ionic conductivity. Cation exchange membranes constitute the largest segment by volume due to their extensive use in various electrochemical processes. The water treatment end-user segment, particularly for desalination and wastewater treatment applications, remains the primary demand driver.
Regulations from bodies like the US EPA and China's MEE set stringent standards for water purity and industrial effluent, driving membrane adoption. Concurrently, the EU's REACH framework governs the chemical substances used in membrane manufacturing, influencing material selection. Stakeholder decisions on material innovation will need to balance performance requirements against an increasingly complex global regulatory landscape.
Market Dynamics
The market's central dynamic is the concurrent pull from two distinct sectors. Green energy initiatives demand high-performance membranes for hydrogen electrolysis and energy storage, while tightening environmental regulations require robust, cost-effective membranes for water and wastewater treatment.
Growth Catalysts
- Green Hydrogen Policies:Frameworks like the EU Green Deal are accelerating investment in electrolyzers for green hydrogen production, directly stimulating demand for proton exchange membranes and anion exchange membranes.
- Water Scarcity:Increasing water stress in regions like the Middle East and North Africa drives public and private investment in large-scale desalination plants, which rely heavily on ion exchange membranes for electrodialysis.
- Material Science Advances:The development of hydrocarbon-based and other non-fluorinated polymer membranes offers lower-cost alternatives to PFSA, expanding accessibility for applications where extreme chemical resistance is not required.
Market Restraints
- Raw Material Costs:The high cost and supply concentration of fluorinated polymers, particularly perfluorosulfonic acid (PFSA), create significant cost barriers for membrane manufacturers and end-users.
- Membrane Fouling:In industrial wastewater and desalination applications, biofouling and scaling reduce membrane permeability and lifespan, leading to higher operational costs for cleaning and replacement.
- Substitution by Other Technologies:Reverse osmosis and nanofiltration technologies present competitive alternatives in certain water treatment applications, particularly where complete deionization is not the primary objective.
Strategic Opportunities
- Redox Flow Batteries:The expansion of grid-scale energy storage creates a significant opportunity for ion exchange membranes, which are a critical component for separating electrolytes in redox flow battery systems.
- Carbon Capture and Utilization:Emerging electrochemical CO2 reduction technologies require specialized anion or cation exchange membranes to facilitate the conversion of captured carbon into valuable chemicals and fuels.
- Food and Beverage Processing:Untapped applications exist in the food industry for demineralization of whey, tartrate stabilization in wine, and pH adjustment in beverages using electrodialysis.
Industry Challenges
- Manufacturing Complexity:The fabrication of high-purity, defect-free membranes with uniform thickness and ion-exchange capacity requires substantial capital investment and specialized technical expertise.
- System Integration:Integrating membranes into larger systems like electrolyzers or electrodialysis stacks poses a challenge, as performance depends heavily on stack design, flow dynamics, and operational parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ion Exchange Membrane Market |
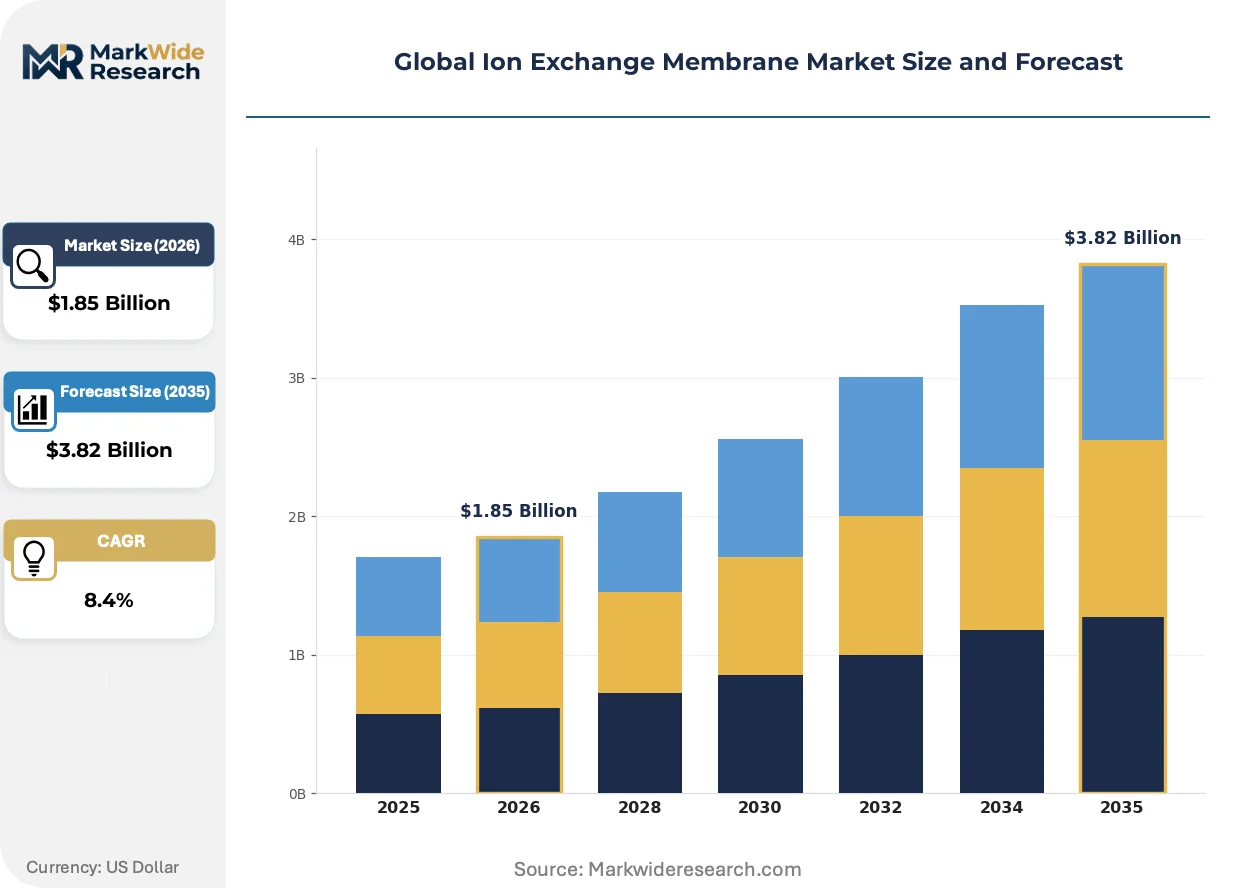
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membrane Type: Cation Exchange, Anion Exchange, Bipolar, Composite, Homogeneous Technology: Electrodialysis, Reverse Osmosis, Nanofiltration, Ultrafiltration, Microfiltration End User Industry: Power Generation, Chemical Processing, Water Treatment, Food & Beverage, Pharmaceuticals Application: Desalination, Wastewater Treatment, Metal Recovery, Gas Separation, Acid Recovery |
| Companies Covered | LANXESS, Asahi Kasei, 3M, FUJIFILM, AGC Engineering, DuPont de Nemours, Inc., Merck KGaA, ASTOM Corporation, Chemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ion Exchange Membrane Market Strategic Shifts & Innovations
Material innovation is responding to dual pressures for higher performance in green energy applications and greater cost-efficiency in environmental compliance. This is leading to a divergence in material platforms and a re-evaluation of system-level integration to maximize membrane value.
Anion exchange membranes (AEMs) are emerging as a viable alternative for electrochemical cells that can operate in alkaline conditions. The green hydrogen and fuel cell sectors are actively developing AEM-based systems to avoid the use of expensive platinum-group metal catalysts. This development is bifurcating the market, creating a distinct cost-performance pathway separate from established PFSA-based proton exchange membranes for acidic environments.
The EU's REACH framework continues to tighten its scrutiny over per- and polyfluoroalkyl substances (PFAS), which includes some polymers used in membrane manufacturing. This regulatory pressure is forcing a strategic shift toward developing and validating non-fluorinated, hydrocarbon-based membrane materials. The industrial water treatment segment is most affected, with suppliers accelerating research into alternative polymers to mitigate future supply chain and compliance risks.
A clear shift from purchasing membranes as standalone components to procuring complete, performance-guaranteed electrochemical stacks is underway. This change disrupts the traditional component-supplier model, creating an advantage for vendors who can offer integrated solutions. This trend is most prominent in new energy storage projects and advanced water treatment systems, where overall system efficiency is the primary procurement driver.
Global Ion Exchange Membrane Market Segmentation
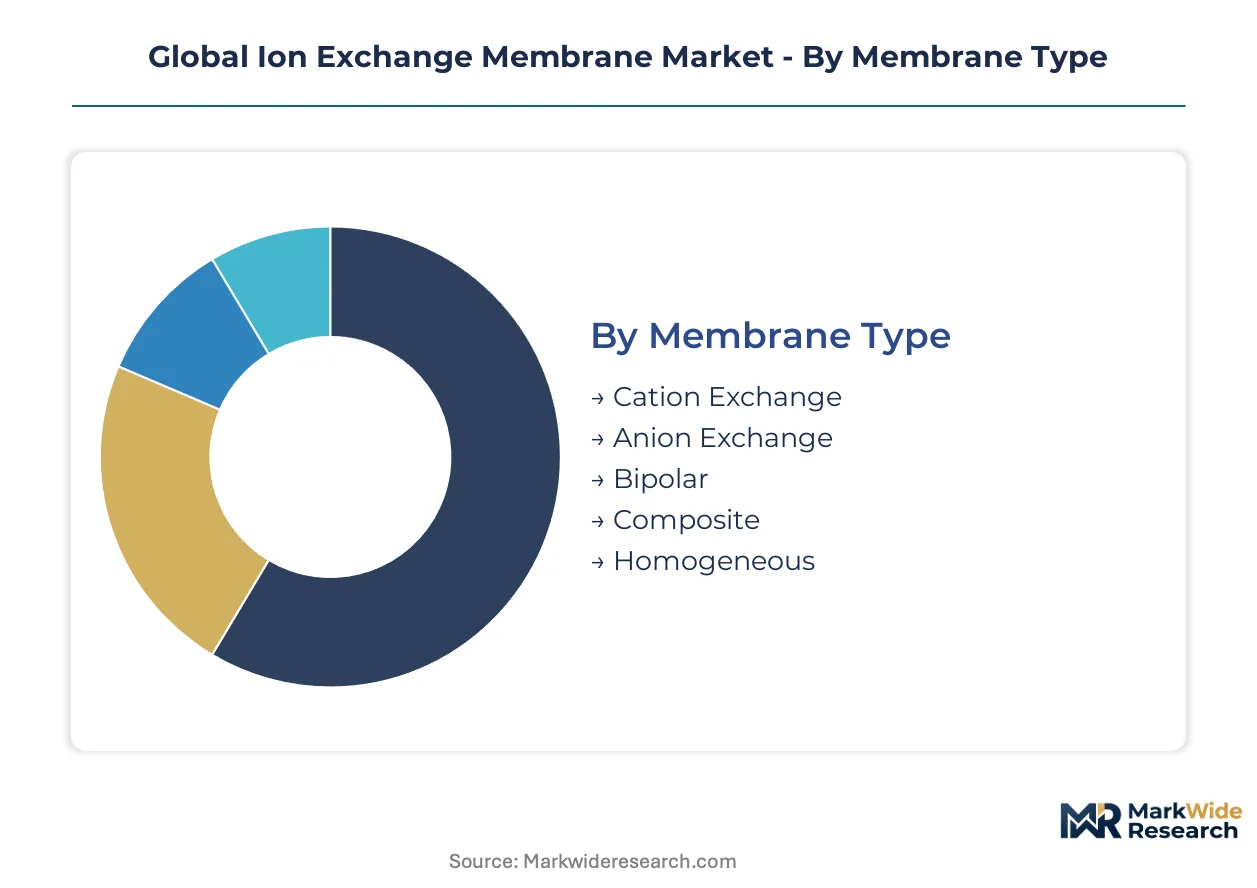
The ion exchange membrane market is segmented to provide a granular understanding of demand drivers and technological shifts. This detailed breakdown highlights specific opportunities for material innovation and application expansion across various industrial processes. Understanding these segments is critical for stakeholders to align product development with evolving market needs.
Membrane Type:
Margin pools within the membrane type category are influenced by manufacturing complexity and performance requirements in specialized applications.
- Cation Exchange:These membranes selectively transport positively charged ions, typically protons or metal cations, while rejecting anions. Demand concentrates in electrochemical processes like electrodialysis for water treatment and in proton exchange membrane fuel cells, driven by the need for efficient ion separation.
- Anion Exchange:Designed to transport negatively charged ions, these membranes are gaining traction as alternatives to proton exchange membranes in alkaline environments. The green hydrogen sector and emerging fuel cell technologies are actively developing AEM-based systems to avoid expensive platinum-group metal catalysts.
- Bipolar:These membranes consist of a cation exchange layer and an anion exchange layer, enabling the splitting of water into H+ and OH- ions. Applications include acid and base recovery from salt solutions, reducing chemical waste in industrial processes.
- Composite:Formed by combining different materials or layers, composite membranes are engineered for enhanced mechanical strength, chemical stability, or selective ion transport. These find use in specialized filtration and separation tasks.
- Homogeneous:Characterized by a uniform composition and structure throughout the membrane, homogeneous types offer consistent performance in less demanding electrochemical applications. They are often used where precise selectivity is paramount.
The dominant share belongs to Cation Exchange, while Anion Exchange is closing the gap fastest.
Technology:
Application focus largely dictates the adoption rate and volume contribution of various membrane technologies in the market.
- Electrodialysis:This technology uses an electric potential difference to drive ions across ion exchange membranes, separating them from water. It is extensively used for desalination and demineralization in water treatment, particularly in regions facing severe water scarcity.
- Reverse Osmosis:A pressure-driven membrane process that separates water from solutes by forcing water through a semipermeable membrane, rejecting most dissolved salts. Reverse osmosis presents a competitive alternative in large-scale desalination and wastewater purification.
- Nanofiltration:This pressure-driven membrane process falls between reverse osmosis and ultrafiltration, removing multivalent ions and larger molecules while allowing monovalent ions to pass. It is employed for water softening, color removal, and removal of specific organic compounds.
- Ultrafiltration:Utilizing membranes with pore sizes typically between 0.01 and 0.1 microns, ultrafiltration separates suspended solids, bacteria, and macromolecules from water. Applications include pre-treatment for reverse osmosis and industrial wastewater clarification.
- Microfiltration:This membrane technology removes suspended solids, bacteria, and large colloids from liquids, operating at lower pressures than ultrafiltration. It is commonly used for sterilization, clarification, and particle removal in various industrial settings.
Electrodialysis remains central to ion exchange membrane applications, but competitive pressure arises from Reverse Osmosis in certain water treatment segments.
End User Industry:
Demand volume for ion exchange membranes is heavily influenced by the regulatory environment and operational requirements of specific end-user industries.
- Water Treatment:This segment encompasses desalination, wastewater treatment, and ultrapure water production for various industries. Regulations from bodies like the US EPA and China's MEE drive membrane adoption for stringent water purity standards.
- Chemical Processing:Ion exchange membranes are vital for acid recovery, caustic soda production via the chlor-alkali process, and various separation tasks in chemical manufacturing. Asahi Kasei sustains a dominant position in membranes for the chlor-alkali process.
- Power Generation:Applications include demineralization of boiler feed water and condensate polishing in thermal and nuclear power plants. Maintaining water purity is critical for preventing scaling and corrosion in power generation equipment.
- Food & Beverage:Membranes are used for demineralization of whey, tartrate stabilization in wine, and pH adjustment in beverages. These processes enhance product quality and extend shelf life in the food industry.
- Pharmaceuticals:Ultrapure water production, purification of active pharmaceutical ingredients, and separation of biomolecules are key applications. High purity standards are paramount in pharmaceutical manufacturing processes.
Water Treatment drives the majority of demand, with Food & Beverage showing significant expansion.
Application:
Regulatory impact significantly shapes the adoption and growth trajectory of ion exchange membrane applications.
- Desalination:The removal of salts from seawater or brackish water to produce potable water, primarily through electrodialysis. Increasing water stress in regions like the Middle East and North Africa drives public and private investment in large-scale desalination plants.
- Wastewater Treatment:The purification of industrial and municipal wastewater to meet discharge limits or for reuse. Stringent environmental regulations globally, including those from the US EPA, compel industries to adopt advanced membrane technologies.
- Metal Recovery:The extraction and concentration of valuable metals from industrial effluents or mining solutions. This application offers both environmental compliance benefits and economic advantages through resource recovery.
- Gas Separation:Used in processes like carbon capture and utilization, where specialized membranes separate specific gases from mixtures. Emerging electrochemical CO2 reduction technologies require specialized membranes.
- Acid Recovery:The reclamation of acids from industrial waste streams, reducing chemical consumption and environmental discharge. This provides a sustainable solution for industries generating acidic byproducts.
Desalination and Wastewater Treatment collectively represent the largest segments, while Metal Recovery offers specialized growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's strong demand for industrial processing applications creates a pricing power asymmetry compared to regions heavily reliant on imported raw materials for membrane manufacturing. Regional market dynamics are shaped by localized environmental regulations, industrial concentration, and investment in green energy infrastructure. Water scarcity in arid regions also drives significant membrane adoption.
China
Demand for ion exchange membranes concentrates in China due to extensive industrial processing and a push for green hydrogen. The Ministry of Ecology and Environment (MEE) sets stringent wastewater discharge standards, compelling industries to adopt advanced treatment. Major industrial clusters in the Yangtze River Delta and Pearl River Delta drive significant membrane consumption for chemical separation and water purification.
United States
The United States market is driven by water treatment and green energy initiatives. The US Environmental Protection Agency (EPA) regulations on potable water and industrial effluent quality stimulate membrane adoption for desalination and wastewater reuse. California and Texas, facing water stress, invest heavily in electrodialysis plants and advanced water purification systems.
Germany
Germany benefits from strong governmental support for green hydrogen production and advanced materials research. The EU Green Deal accelerates investment in electrolyzers, boosting demand for high-performance proton and anion exchange membranes. North Rhine-Westphalia, a hub for chemical industries, sees significant application in industrial water treatment and resource recovery, influenced by REACH regulations.
Saudi Arabia
Saudi Arabia exhibits high demand for ion exchange membranes, primarily for large-scale desalination projects. Increasing water stress in the Middle East region drives public and private investment in electrodialysis technology. The NEOM project and other major infrastructure developments are integrating advanced water treatment solutions to ensure sustainable potable water supply.
Japan
Japan's market is characterized by advanced industrial water treatment and a focus on high-purity applications. Policies from the Ministry of Economy, Trade and Industry (METI) support material innovation and energy efficiency in industrial processes. The Kansai region, with its strong chemical and manufacturing base, utilizes ion exchange membranes for metal recovery and ultrapure water production.
Global Ion Exchange Membrane Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the ion exchange membrane market. The market structure features established chemical conglomerates alongside specialized membrane manufacturers. Strategic archetypes include vertically integrated polymer science giants, application-specific specialists, and regional solution providers. Dominant competitive moves include material innovation and strategic partnerships for system integration.
Vertically integrated polymer science giants, such as DuPont de Nemours, Inc., leverage extensive R&D capabilities to innovate across multiple applications. Asahi Kasei exemplifies an application-specific specialist, maintaining a dominant position in membranes for the chlor-alkali process. LANXESS occupies a position as a high-performance solution provider, specializing in industrial water treatment and metal recovery applications.
| Leading Market Players |
|---|
| LANXESS |
| Asahi Kasei |
| 3M |
| FUJIFILM |
| AGC Engineering |
| DuPont de Nemours, Inc. |
| Merck KGaA |
| ASTOM Corporation |
| Chemours |
| Others |
Cost & Logistics Intelligence
Non-fluorinated polymer membranes replacing expensive PFSA materials are reshaping the ion exchange membrane supply chain. This substitution dynamic simultaneously shifts manufacturing capabilities and redefines cost structures across key geographies.
Pricing Analysis
Configured-to-order pricing for specialized ion exchange membranes commands a premium over standard, high-volume offerings. Project-based contracts dominate for large-scale desalination, while value-based pricing applies to high-performance green energy applications. Customization for specific electrochemical processes and stringent performance requirements in fuel cells drive price differentiation. Cost compression on standard membranes stems from the emergence of lower-cost, hydrocarbon-based alternatives. Water treatment end-users exhibit higher price sensitivity compared to the green hydrogen sector, which prioritizes membrane performance.
Supply Chain Analysis
High inventory levels for standard ion exchange membranes contrast with longer lead times for custom, high-performance units. Supply centers on China for industrial processing and Germany for advanced materials research. Japan maintains specialized production for high-purity applications. The supply chain depends on specialized polymer resins and particularly on perfluorosulfonic acid (PFSA). Regulatory restrictions on per- and polyfluoroalkyl substances (PFAS) by EU REACH introduce a structural risk for fluorinated polymer-based membranes. Distribution runs through direct sales channels to large industrial end-users and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ion exchange membrane market demands a substitution defense strategy from incumbents. Reverse osmosis and nanofiltration technologies present a significant substitute threat in certain water treatment applications, necessitating strategic adaptation.
For Market Incumbents: Consolidate expertise in material science to counter competitive pressure from alternative separation technologies. Deepen vertical integration into advanced polymer manufacturing and invest in system-level integration capabilities for electrochemical stacks. Membrane fouling and high raw material costs threaten operational efficiency and market share. Leverage R&D in non-fluorinated, hydrocarbon-based membranes to mitigate future supply chain and compliance risks.
For New Entrants and Emerging Players: Anchor in niche applications requiring specialized membrane performance, such as redox flow batteries or carbon capture. Focus on developing high-performance anion exchange membranes for alkaline green hydrogen systems, or specialized membranes for electrochemical CO2 reduction. The food and beverage processing sector offers underpenetrated opportunities for electrodialysis applications. Offer integrated, performance-guaranteed electrochemical stack solutions rather than standalone components.
For Investors and Strategic Acquirers: The EU's REACH framework reshapes the acquisition landscape, favoring companies with validated non-fluorinated membrane technologies. Long-term viability hinges on companies capable of balancing performance requirements with an increasingly complex global regulatory landscape. Target agile mid-sized specialists possessing proprietary non-PFSA membrane formulations and manufacturing expertise. Increased investment in hydrocarbon-based membrane R&D or pilot projects by major chemical conglomerates serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Non-Fluorinated Membranes | Boosts supply resilience and addresses regulatory pressure from EU REACH on PFAS substances. |
| Joint Venture for Electrochemical Stack Integration | Enables offering complete, performance-guaranteed solutions for green hydrogen and energy storage projects. |
| R&D Investment in Anion Exchange Membranes (AEMs) | Captures growth in alkaline electrolysis and emerging fuel cell technologies for green energy. |
| Backward Integration into Polymer Precursor Production | Secures critical raw material supply and mitigates cost volatility for membrane manufacturing. |
| Regional Partnership for Water Treatment Projects | Expands market access in water-stressed regions like the Middle East for desalination applications. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings of this study. Industry stakeholders included R&D directors, procurement leads at water treatment facilities, and process engineers in chemical processing. Secondary validation drew from environmental agency reports (US EPA, China MEE), material science journals, and corporate filings. A bottom-up approach assessed market volumes from end-user demand, while top-down triangulation validated overall market sizing.
Sensitivity analysis informed the forecast framework, modeling various scenarios for technology adoption and regulatory impacts across the analysis window. Segmentation dimensions modeled included membrane type, end-user industry, application, and regional demand patterns. Compound Annual Growth Rates were derived from historical growth trends and projected future demand for green energy and water treatment. Key inputs included investment trends in green hydrogen infrastructure and global desalination plant capacity additions.
Decision-makers should treat outputs as directional under current regulatory and technological development assumptions; material deviation would warrant model refresh. Geopolitical shifts impacting raw material supply or significant breakthroughs in competing separation technologies represent key risk factors. Revision becomes warranted when green energy investment trends or water scarcity mitigation strategies cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market