
 Reverse Osmosis Films Market | 2026-2036
Reverse Osmosis Films Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Osmosis Films Market Intelligence
Membrane replacement subscription contracts is shifting how reverse osmosis films get monetized, moving capital expenditure into operational budgets for large desalination operators. DuPont leverages its integrated polymer science capabilities to control supply chains for thin-film composite chemistry. Toray Industries anchors production scale in Japan while extending technical service networks across Asian municipal markets. Koch Membrane Systems specializes in industrial wastewater configurations where fouling resistance commands premium positioning.
Reverse osmosis films are semipermeable barriers, typically thin-film polyamide composites measuring 100–200 nanometers active layer thickness, engineered to reject dissolved salts and organic contaminants under transmembrane pressures of 5–80 bar. Their primary commercial purpose is to produce potable water from seawater, brackish sources, or treated effluent by selective permeation. Polyamide composites dominate installed capacity due to superior salt rejection and flux rates, while spiral wound configurations occupy the majority of desalination and municipal treatment trains because of packing density advantages. Hollow fiber geometries are gaining traction in compact residential and commercial systems where footprint constraints override energy efficiency priorities.
The EPA enforces Maximum Contaminant Level Goals under the Safe Drinking Water Act that directly specify membrane performance thresholds for municipal adoption. California's State Water Resources Control Board imposes additional brine discharge regulations that shape system design and film selection for coastal desalination projects. REACH compliance in Europe restricts certain solvent chemistries used in interfacial polymerization, pushing manufacturers toward modified synthesis routes. Stakeholders must monitor how emerging per- and polyfluoroalkyl substances limits in drinking water standards cascade into new rejection specifications for next-generation membrane chemistry.
Market Dynamics
Membrane replacement subscription contracts are converting capital expenditure into operational budgets for large desalination operators, fundamentally restructuring how reverse osmosis films get monetized across municipal and industrial procurement channels.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:The United States is tightening filtration performance requirements for drinking water systems, mandating enhanced membrane rejection specifications that accelerate municipal upgrade cycles.
- Red Sea Desalination Corridor:Saudi Arabia's coastal utilities are expanding membrane replacement schedules as drought conditions intensify across the Arabian Peninsula, concentrating demand in high-salinity applications.
- Thin-Film Polyamide Chemistry:Advances in interfacial polymerization are delivering superior salt rejection and flux rates, enabling single-pass seawater desalination at reduced energy intensity.
Market Restraints
- Petrochemical Feedstock Volatility:Aromatic polyamide precursors and solvent chemistries face price instability tied to benzene and toluene markets, compressing manufacturing margins.
- Japanese Production Concentration:Toray Industries anchors substantial thin-film composite capacity in Japan, creating geographic supply vulnerability for Asian municipal procurement.
- REACH Solvent Restrictions:ECHA compliance mandates are eliminating certain interfacial polymerization chemistries, forcing costly synthesis route modifications without performance gains.
Strategic Opportunities
- India Brackish Water Belt:Gujarat and Rajasthan states present underpenetrated demand for low-pressure brackish water reverse osmosis systems in agricultural and small municipal applications.
- Per- and Polyfluoroalkyl Substances Mandates:Emerging drinking water standards for PFAS compounds are creating new rejection specifications that favor next-generation membrane surface modifications.
- Residential Compact Systems:Hollow fiber geometries are gaining traction in urban apartments where footprint constraints override energy efficiency priorities, opening channel partnerships with appliance distributors.
Industry Challenges
- Interfacial Polymerization Expertise Gap:Thin-film composite fabrication requires specialized chemical engineering talent that remains concentrated among legacy membrane manufacturers.
- California Brine Discharge Certification:The State Water Resources Control Board imposes extended approval timelines for coastal desalination projects, delaying film specification finalization.
- Legacy Train Integration:Spiral-wound replacement films must match hydraulic performance of aged pressure vessels, complicating retrofit engineering for municipal operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Osmosis Films Market |
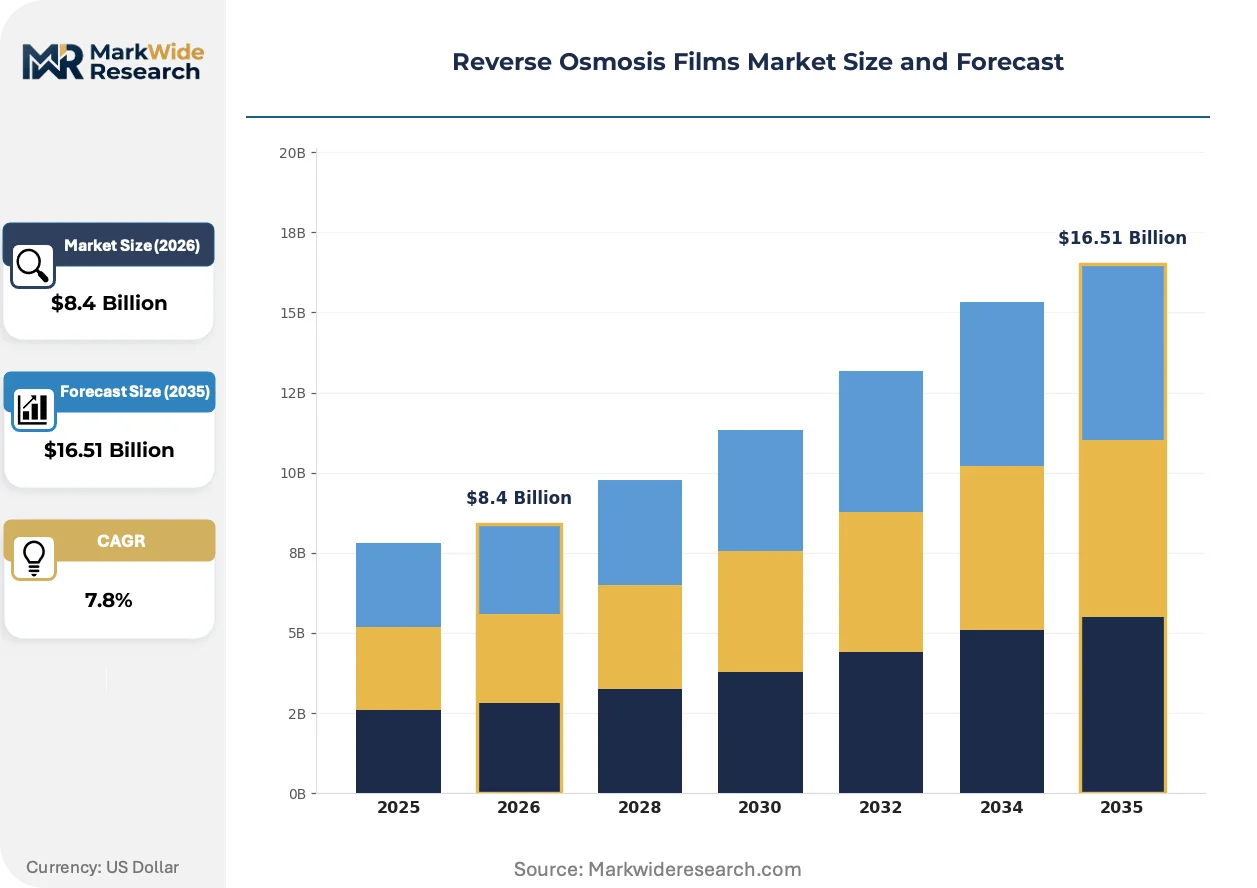
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Polyethersulfone, Cellulose Acetate, Composite Application: Desalination, Wastewater Treatment, Food Processing, Industrial Use End User: Municipal, Residential, Commercial, Pharmaceutical Technology: Spiral Wound, Hollow Fiber, Flat Sheet, Tubular |
| Companies Covered | DuPont, Koch Membrane Systems, Inc., Toray Industries, Inc., Mitsubishi Chemical Corporation, Toyobo Co., Ltd., Nitto Denko Corporation, Hydranautics, Veolia, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Osmosis Films Market Strategic Shifts & Innovations
Thin-film nanocomposite architectures are displacing conventional polyamide chemistry as fouling resistance and chlorine tolerance become decisive selection criteria for industrial wastewater operators.
Graphene oxide interlayers are consolidating next-generation membrane construction by enabling precise molecular sieving without sacrificing mechanical durability. Municipal utilities in Singapore and Israel are piloting these architectures for high-fouling secondary effluent applications. The technology is consolidating supplier differentiation around surface modification capabilities rather than base polymer chemistry.
REACH compliance deadlines in Europe are forcing solvent substitution in interfacial polymerization processes, with manufacturers migrating toward aqueous-based synthesis routes. ECHA restrictions on N-methyl-2-pyrrolidone are raising production costs for thin-film composite manufacturing. European membrane producers are responding by relocating finishing operations to jurisdictions with less stringent chemical handling regulations.
Subscription-based membrane replacement is displacing spot procurement for large desalination operators, with performance guarantees bundled into multi-year service agreements. Middle Eastern utilities along the Red Sea coast are pioneering this model, transferring technical risk to film suppliers. The shift is most visible in Saudi Arabia's independent water and power projects, where operational expenditure structures dominate capital planning cycles.
Reverse Osmosis Films Market Segmentation
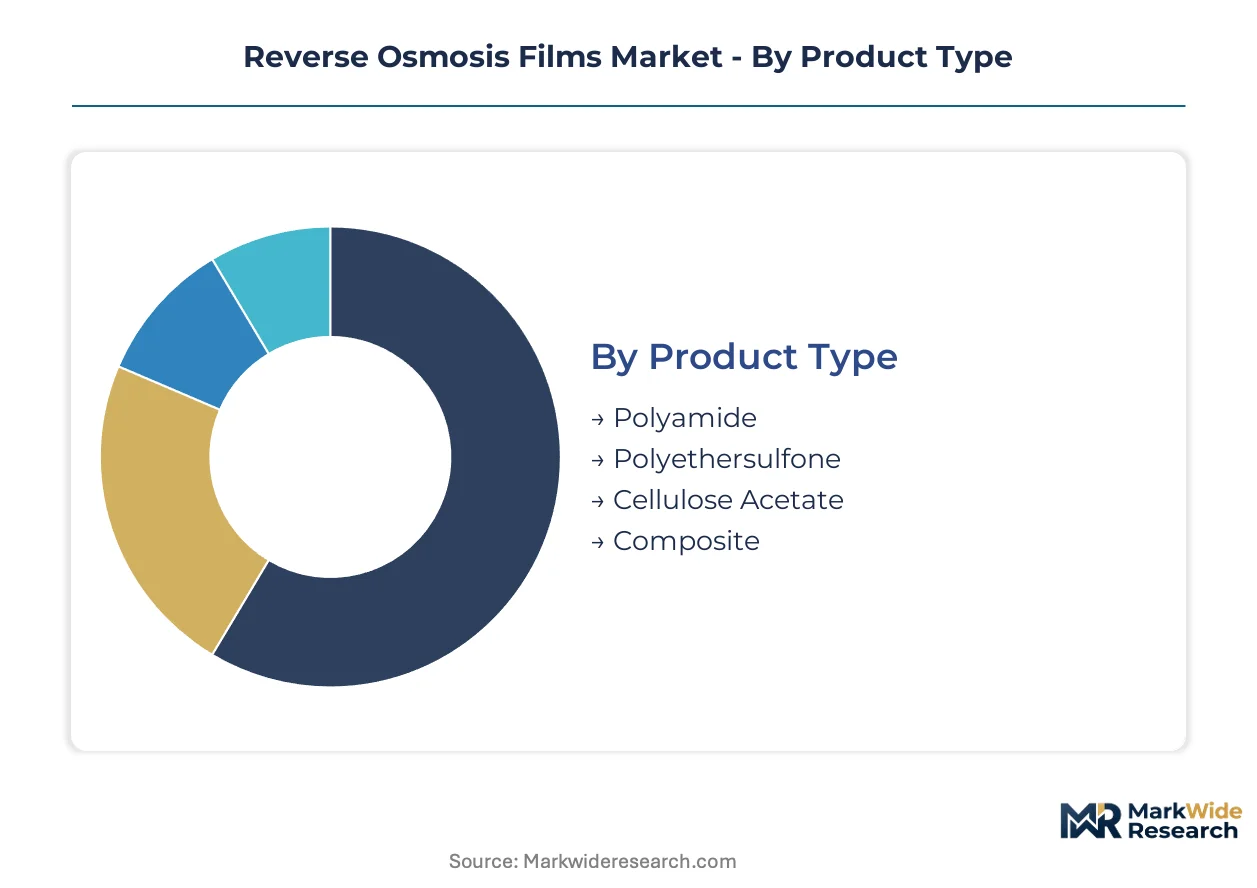
Reverse osmosis films segment across four interlocking dimensions that determine procurement economics, certification pathways, and technical service requirements. Product chemistry dictates rejection performance and regulatory compliance burdens. Application context shapes pressure specifications and replacement cadence.
Product Type:
EPA and ECHA certification requirements vary sharply across polymer chemistries, with thin-film composites facing the most stringent drinking water contact approvals.
- Polyamide:Thin-film polyamide composites dominate installed capacity through superior salt rejection exceeding 99.5% and flux rates enabling single-pass seawater desalination. Demand concentrates in Saudi Arabia's Red Sea desalination corridor where high-salinity feedwater mandates maximum rejection performance.
- Composite:Multi-layer thin-film nanocomposites integrate graphene oxide interlayers for fouling resistance and chlorine tolerance, consolidating next-generation positioning for industrial wastewater operators facing high-organic secondary effluent.
- Polyethersulfone:Hydrophilic sulfone chemistry delivers pH stability across 2-12 range for aggressive chemical cleaning protocols in pharmaceutical and food processing sterilization loops.
- Cellulose Acetate:Legacy acetate chemistry retains niche positioning in low-pressure brackish applications where chlorine tolerance eliminates dechlorination pretreatment costs.
Polyamide sits at the top of the volume ranking, with Composite climbing the fastest as fouling resistance becomes decisive for industrial operators.
Application:
Cost tier stratification separates premium desalination membranes from standard wastewater configurations and economy-grade food processing films.
- Desalination:Seawater and brackish water systems operate at 55-80 bar transmembrane pressure with polyamide chemistry rejecting dissolved salts for potable production. Saudi Arabia's independent water and power projects concentrate procurement through subscription-based replacement contracts.
- Wastewater Treatment:Industrial effluent and municipal reuse applications prioritize fouling resistance over flux rates, with thin-film nanocomposites gaining share in Singapore and Israel pilot programs for high-fouling secondary effluent.
- Food Processing:Dairy concentration and juice clarification employ sanitary-grade spiral wound configurations meeting FDA food contact substance notifications.
- Industrial Use:Boiler feedwater and process water purification span pressure ratings from 5-40 bar with chemistry matched to silica and hardness scaling potential.
Desalination commands the premium pricing tier, with Wastewater Treatment expanding most quickly as water reuse mandates tighten across municipal utilities.
End User:
Customer type determines whether procurement flows through capital expenditure budgets or operational expenditure structures with performance guarantees.
- Municipal:City water treatment utilities face EPA Lead and Copper Rule revisions mandating enhanced rejection specifications, accelerating membrane upgrade cycles in United States drinking water systems.
- Residential:Compact hollow fiber systems serve urban apartments where footprint constraints override energy efficiency, opening appliance distributor channel partnerships.
- Commercial:Hotels, hospitals, and office complexes deploy mid-scale systems with 12-24 month replacement schedules tied to warranty and service contracts.
- Pharmaceutical:USP Purified Water and Water for Injection systems require validated membrane change protocols with full traceability documentation.
Municipal procurement represents the largest absolute volume, with Residential gaining share fastest as point-of-use installation penetrates water-stressed urban markets.
Technology:
Packing density and cleaning accessibility create distinct margin structures across module geometries.
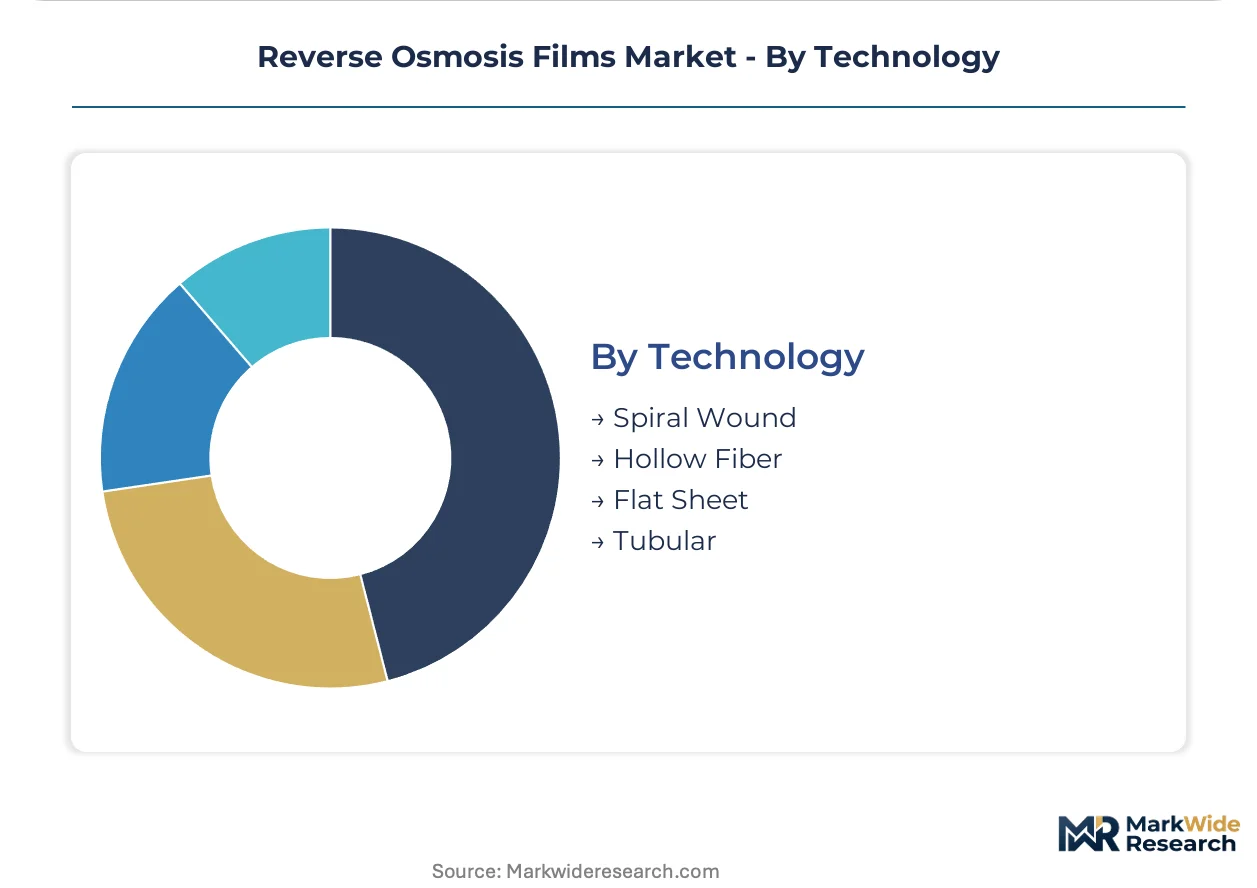
- Spiral Wound:Interleaved flat sheet membranes wound around permeate collection tubes deliver maximum packing density for large-scale desalination trains, occupying majority of municipal and industrial installed base.
- Hollow Fiber:Capillary bundle configurations enable compact residential and commercial systems with outside-in flow geometry simplifying backwash cleaning protocols.
- Flat Sheet:Plate-and-frame modules facilitate membrane replacement without vessel extraction, serving laboratory and pilot-scale applications requiring rapid chemistry testing.
- Tubular:Wide-bore ceramic or polymeric tubes tolerate high suspended solids for food processing and industrial wastewater with minimal pretreatment.
Spiral Wound maintains volume leadership, with Hollow Fiber showing the steepest expansion trajectory as compact system demand accelerates in space-constrained installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Red Sea desalination corridor concentrates membrane demand more intensely than any comparable cluster worldwide, while the United States confronts aging municipal infrastructure and tightening EPA mandates that accelerate replacement cycles.
United States
EPA Lead and Copper Rule revisions mandate enhanced filtration performance for drinking water systems, compelling municipal utilities across California, Texas, and Florida to accelerate membrane upgrade schedules. State-level regulators in California impose additional brine discharge requirements through the State Water Resources Control Board. The Colorado River Basin utilities are expanding tertiary treatment capacity as drought conditions intensify.
Saudi Arabia
Independent water and power projects along the Red Sea coast are pioneering subscription-based membrane replacement contracts that transfer technical risk to suppliers. SFDA drinking water contact approvals shape procurement specifications for potable applications. The Jubail industrial city cluster anchors high-salinity desalination demand where thin-film polyamide chemistry dominates specification sheets.
China
MIIT industrial water reuse mandates are driving membrane adoption across steel, petrochemical, and power generation facilities in the Yangtze River Delta and Pearl River Delta regions. GB standards for drinking water quality are tightening rejection specifications for municipal treatment trains. Tianjin's coastal desalination plants are expanding capacity to serve Beijing's water transfer requirements.
Japan
METI energy efficiency programs are subsidizing next-generation membrane installations that reduce desalination power consumption below 3 kWh per cubic meter. JIS certification requirements maintain strict quality barriers for thin-film composite imports. The Chubu region around Nagoya hosts concentrated industrial wastewater treatment demand from automotive and electronics manufacturing clusters.
Singapore
NEWater reuse mandates are positioning the city-state as a testbed for thin-film nanocomposite architectures in high-fouling secondary effluent applications. PUB technical specifications influence membrane selection across Southeast Asian municipal procurement. The Tuas Nexus integrated waste and water facility is consolidating demand for fouling-resistant surface modifications.
Reverse Osmosis Films Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated polymer science capabilities commanding premium positioning in desalination while regional fabricators capture municipal replacement volume. The market structure concentrates among Japanese, American, and Korean chemical conglomerates that control interfacial polymerization expertise. Three archetypes dominate: vertically integrated material suppliers, membrane-specialized engineering firms, and diversified chemical conglomerates with water treatment divisions. Competitive moves center on multi-year service contract bundling and aqueous synthesis route development to preempt REACH compliance costs.
Among Japanese chemical conglomerates, Toray Industries, Inc., Mitsubishi Chemical Corporation, and Nitto Denko Corporation occupy positions anchored by domestic production scale and extended technical service networks across Asian municipal markets. These Tokyo and Osaka-based companies exemplify the integrated-material-supplier archetype, with corporate structures reflecting long-tenured chemical industry consolidation. Their positioning represents the geographic supply concentration that Asian procurement channels must navigate.
| Leading Market Players |
|---|
| DuPont |
| Koch Membrane Systems, Inc. |
| Toray Industries, Inc. |
| Mitsubishi Chemical Corporation |
| Toyobo Co., Ltd. |
| Nitto Denko Corporation |
| Hydranautics |
| Veolia |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Subscription-based membrane replacement contracts across Saudi Arabia's independent water and power projects are compressing spot-market liquidity and forcing suppliers to absorb technical risk through performance-guaranteed operational expenditure structures, which elevates working capital requirements and reshapes margin allocation across the value chain.
Pricing Analysis
Capacity additions in Japan and South Korea are reshaping price floors for thin-film composite chemistry as Toray Industries and LG Chem expand fabrication scale. Three-tier pricing structure across premium desalination, standard municipal, and economy-grade industrial tiers separates customers by certification grade and after-sales bundling intensity. Cost compression in the economy tier is intensifying because REACH solvent restrictions are raising production costs without performance gains. Municipal utilities in the United States demonstrate the lowest price sensitivity due to EPA-mandated upgrade cycles, while small commercial operators in India exhibit the highest.
Supply Chain Analysis
Specialized chemical engineering talent shortages in Japan's Chubu region and Osaka prefecture are constraining interfacial polymerization capacity expansion despite robust order backlogs. Manufacturing concentrates in Japan, the United States, and South Korea, with thin-film composite fabrication anchored in legacy chemical conglomerates. Aromatic polyamide precursors draw from benzene and toluene feedstocks, while solvent chemistries hinge on petrochemical derivatives. Single-source vulnerability persists for high-purity interfacial polymerization reagents. Distribution runs through direct technical service networks for large desalination operators and regional distributors for municipal replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reverse osmosis films market functions as a regulatory compounder where successive EPA Lead and Copper Rule revisions and emerging PFAS mandates create ratcheting demand for enhanced rejection specifications that membrane chemistry must continuously satisfy.
For Market Incumbents: Anchor defensive positioning by deepening captive supply of aromatic polyamide precursors to offset petrochemical feedstock volatility, and accelerate aqueous-based synthesis route development to preempt ECHA compliance cost escalation. Threat substitution from graphene oxide interlayer architectures demands surface modification capability investment. Certification investment in SFDA and EPA drinking water contact approvals remains the critical lever for premium tier access. For New Entrants and Emerging Players: Capture white-space opportunity in India's Gujarat and Rajasthan brackish water belt where low-pressure system demand runs ahead of established supplier technical service coverage. The residential compact segment presents the most penetrable application, with hollow fiber geometries enabling appliance distributor channel partnerships that bypass incumbent direct-sales infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized surface modification technology holders positioned for PFAS rejection specification capture. Long-term viability over the projection horizon favors membrane-specialized engineering firms with proven interfacial polymerization expertise over diversified chemical conglomerates where water treatment divisions compete for capital allocation. Watch EPA enforcement intensity around Lead and Copper Rule implementation timelines as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Synthesis Route Development | ECHA REACH solvent restrictions are eliminating N-methyl-2-pyrrolidone chemistries, forcing costly reformulation. |
| Subscription Contract Bundling | Saudi Arabia's independent water and power projects are transferring technical risk to suppliers through multi-year service agreements. |
| Surface Modification R&D Investment | Graphene oxide interlayers are consolidating next-generation positioning for high-fouling secondary effluent applications. |
| Technical Service Network Expansion | Asian municipal procurement channels require localized support for membrane replacement scheduling and troubleshooting. |
| Backward Integration into Polymer Precursors | Benzene and toluene price volatility compresses margins for non-integrated thin-film composite manufacturers. |
Research Approach
Direct dialogue with desalination plant operators, municipal utility procurement managers, membrane fabrication engineers, and EPC contractors combined with secondary validation from EPA enforcement databases, ECHA regulatory filings, SEC 10-K disclosures from chemical conglomerates, and customs trade data for aromatic polyamide precursor flows. Bottom-up and top-down triangulation cross-checked replacement volume estimates against installed base calculations and capacity utilization disclosures.
Bottom-up modeling segmented the market across polymer chemistry tiers, application pressure specifications, end-user procurement structures, and module geometry formats across the analysis window. CAGRs derived from replacement cycle acceleration rates tied to regulatory milestone timing and drought intensity indices. Forecast inputs incorporated MIIT industrial water reuse mandate implementation pace and SFDA drinking water contact approval timelines.
Petrochemical feedstock volatility, ECHA solvent restriction enforcement intensity, and PFAS regulatory standard finalization are the dominant revision risks to projection assumptions. Practitioners should monitor EPA Lead and Copper Rule implementation pace and Middle Eastern drought severity indices for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Membranes Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Membrane Separation Materials Market