
 Global Gas Separation Membranes Market | 2026-2036
Global Gas Separation Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Separation Membranes Market Foresight
Polyimide is pivoting toward polydimethylsiloxane blends in biogas upgrading modules, cutting permeate loss by half while preserving selectivity for carbon dioxide over methane. Honeywell International Inc. leverages its UOP heritage to dominate hydrogen recovery retrofits at North American refineries. Linde Plc anchors large-scale air separation contracts through captive membrane manufacturing in Europe. Evonik Industries AG specializes in thin-film composite hollow fibers for high-pressure natural gas conditioning.
Gas separation membranes are semipermeable barriers engineered from polymeric, ceramic, or mixed-matrix materials that selectively permeate specific gas molecules based on size, solubility, or diffusivity differentials, typically operating at pressures between 5 and 80 bar and temperatures up to 150 degrees Celsius depending on material stability. These systems purify, recover, or fractionate industrial gas streams without phase change, displacing energy-intensive cryogenic or absorption alternatives in carbon capture and hydrogen purification duties. Polymeric membranes occupy the volume mainstream due to mature manufacturing scalability and module standardization, though mixed-matrix formats are capturing margin pools as silica-zeolite loadings improve CO2-N2 selectivity beyond neat polymer limits. Hollow fiber configurations lead in natural gas processing for their high surface-area-to-volume ratio, while spiral-wound elements dominate smaller-scale biogas upgrading where capital constraints shape procurement.
EPA New Source Performance Standards and EU F-Gas Regulation are tightening permissible venting rates from gas processing equipment, directly expanding addressable demand for membrane-based vapor recovery and carbon capture retrofits. REACH compliance in Europe and OSHA process safety mandates in the United States further constrain material choices and module certification pathways, favoring suppliers with established regulatory dossiers. Stakeholders must weigh membrane replacement cycles against emerging sorbent-metal-organic-framework hybrids that threaten to displace polymer systems in select hydrogen applications.
Market Dynamics
Refinery hydrogen recovery retrofits are compressing membrane replacement cycles as EPA New Source Performance Standards force continuous venting reductions, while polyimide-to-polydimethylsiloxane blend transitions concentrate technical capability among European material suppliers.
Growth Catalysts
- EPA emissions mandates:New Source Performance Standards tighten permissible venting rates from gas processing equipment, compelling North American refiners to deploy membrane-based vapor recovery systems ahead of compliance deadlines.
- Hydrogen purification demand:German chemical manufacturers anchor procurement volumes for onsite nitrogen generation and hydrogen conditioning systems, sustaining polymeric membrane deployment.
- Biogas upgrading:Polydimethylsiloxane blend formulations cut permeate loss by half in carbon dioxide-methane separation, accelerating adoption at agricultural anaerobic digestion facilities.
Market Restraints
- Silica-zeolite loading costs:Mixed-matrix membrane raw materials carry 40-60% premia over neat polymers, constraining adoption outside premium carbon capture applications.
- European supply concentration:Thin-film composite hollow fiber manufacturing clusters in Germany and Austria create single-source vulnerability for high-pressure natural gas conditioning modules.
- Metal-organic framework substitution:Emerging sorbent-MOF hybrids threaten displacement of polymer systems in select hydrogen purification duties where selectivity requirements exceed membrane limits.
Strategic Opportunities
- India biogas corridor:Agricultural waste-to-energy projects under the PLI scheme create demand for spiral-wound biogas upgrading elements where capital constraints dominate procurement.
- EU Green Deal carbon-neutrality timelines:Industrial operator retrofit obligations expand addressable demand for membrane-based carbon capture retrofits across cement and steel installations.
- Ceramic-polymer convergence:Mixed-matrix formats combining polyimide matrices with ceramic nanofillers enable temperature excursions beyond 150°C, opening high-temperature refinery applications.
Industry Challenges
- REACH dossier completion:European module certification pathways demand 18-24 month regulatory timelines, favoring incumbent suppliers with established material safety registrations.
- Legacy absorption system integration:Cryogenic and amine-based displacement requires reconfiguration of existing compressor trains and control systems, extending project commissioning cycles.
- Hollow fiber spinning talent scarcity:Specialized polymer rheology and phase-inversion expertise concentrates among aging technical workforces in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Separation Membranes Market |
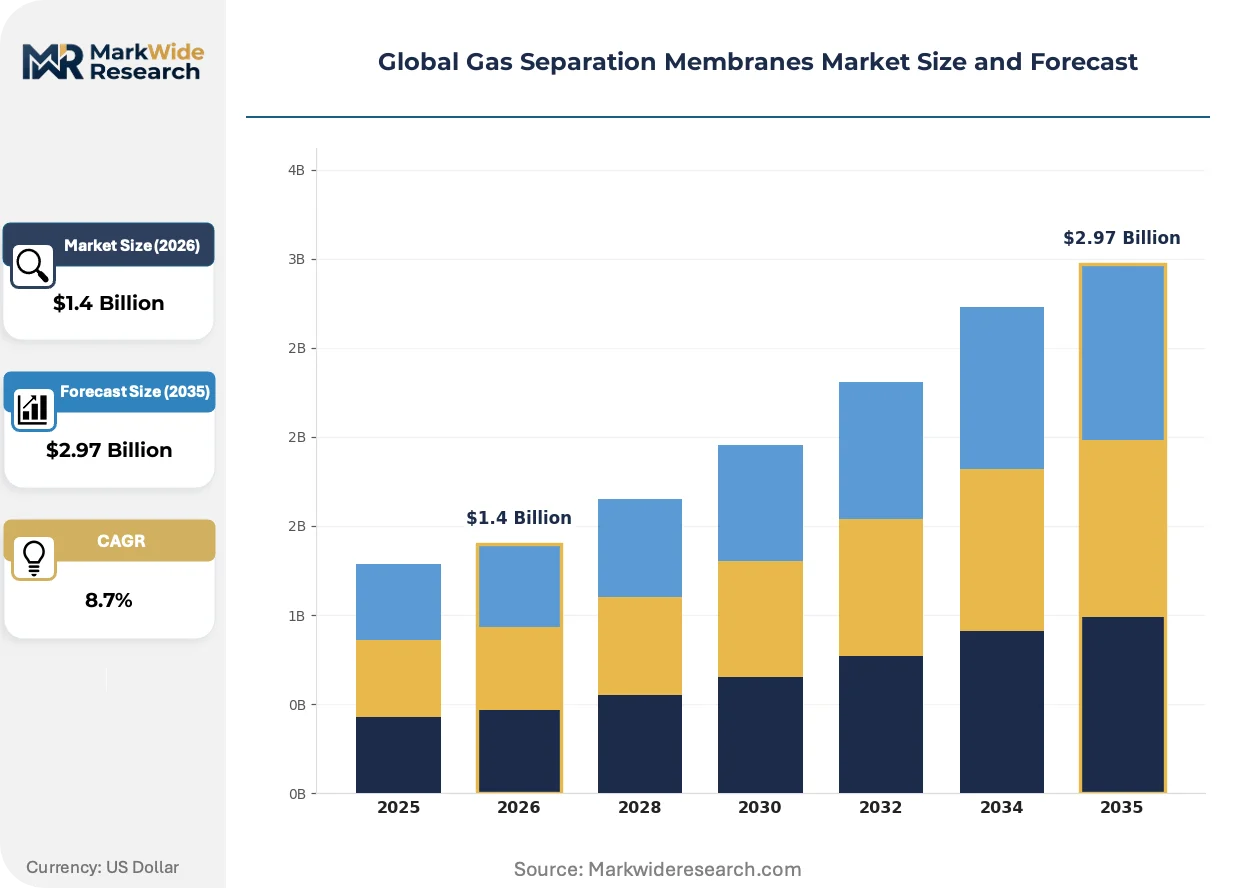
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membrane Type: Polymeric, Inorganic, Mixed Matrix, Hollow Fiber, Spiral Wound Technology: Pressure Swing Adsorption, Cryogenic Distillation, Absorption, Permeation, Vacuum Swing Adsorption Application: Natural Gas Processing, Biogas Upgrading, Hydrogen Recovery, Carbon Capture, Air Separation End User: Oil & Gas Producers, Chemical Manufacturers, Power Generation Companies, Gas Distributors, Research Laboratories |
| Companies Covered | Honeywell International Inc., Schlumberger Limited, Linde Plc, Fujifilm Holdings Corporation, Parker Hannifin Corporation, Air Products and Chemicals Inc., UBE Corporation, Evonik Industries AG, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Separation Membranes Market Shifts & Advancements
Material science advances and regulatory compression are rewriting competitive advantage in gas separation, as membrane formats displace thermal separation economics and procurement patterns shift toward performance-guaranteed supply contracts.
Polydimethylsiloxane-polyimide interpenetrating networks are rewriting biogas upgrading economics by halving methane slip while preserving mechanical integrity under cyclic pressure loading. Agricultural digester operators in Denmark and the Netherlands are adopting these modules on 3-5 year replacement cycles rather than conventional 7-10 year intervals. The technology is compressing unit economics for sub-500 Nm³/hour installations that previously favored amine scrubbing.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cryogenic separation retrofits at industrial gas facilities across Belgium and France. Operators face 2027-2030 compliance cliffs that expand membrane pre-qualification activity. Air separation units in the Rhine-Ruhr chemical cluster are prioritizing hollow fiber membrane trains for nitrogen generation to avoid refrigerant handling complexity.
Performance-based membrane supply contracts are displacing capital purchase models at North American hydrogen recovery installations. Refinery operators in Texas and Louisiana now procure permeate purity guarantees rather than module hardware, transferring technical risk to membrane suppliers. The shift concentrates procurement authority among engineering-procurement-construction firms with integrated membrane system capabilities.
Global Gas Separation Membranes Market Segmentation
Membrane format selection dictates replacement-cycle economics and retrofit feasibility across refinery and biogas installations. Procurement patterns diverge sharply between high-pressure hydrogen recovery duties and lower-pressure agricultural digester applications.
Membrane Type:
Upgrade timelines and module replacement frequencies vary dramatically by material stability and mechanical resilience under cyclic loading.
- Polymeric:Polyimide and polydimethylsiloxane blends dominate volume procurement due to mature phase-inversion manufacturing and standardized hollow-fiber spinning. Refinery operators in Texas and Louisiana specify these for hydrogen recovery retrofits where 5-7 year replacement cycles align with turnaround schedules.
- Mixed Matrix:Silica-zeolite loadings in polyimide matrices push CO2-N2 selectivity beyond neat polymer limits, commanding 40-60% raw material premia. Carbon capture installations in Germany and the Netherlands absorb these costs for compliance with EU Green Deal timelines.
- Inorganic:Ceramic membranes tolerate temperature excursions above 150°C, enabling high-temperature refinery applications where polymer stability fails.
- Hollow Fiber:High surface-area-to-volume configurations anchor natural gas conditioning contracts across North American shale plays.
- Spiral Wound:Lower capital intensity suits sub-500 Nm³/hour biogas upgrading at agricultural digesters in Denmark and India.
Volume placements concentrate in Polymeric; the faster expansion belongs to Mixed Matrix.
Technology:
Process selection hinges on scale economics, energy intensity, and regulatory pressure on venting rates.
- Permeation:Membrane-based gas separation operates without phase change, displacing thermal alternatives in hydrogen purification and carbon capture duties. EPA New Source Performance Standards accelerate deployment at U.S. refineries facing continuous venting reduction mandates.
- Absorption:Amine-based systems retain share in large-scale natural gas sweetening where membrane selectivity limits exclude single-stage solutions.
- Pressure Swing Adsorption:Cyclic regeneration suits high-purity hydrogen production at German chemical manufacturing clusters.
- Cryogenic Distillation:Energy-intensive refrigeration faces EU F-Gas Regulation phase-down pressures across Belgian and French industrial gas facilities.
- Vacuum Swing Adsorption:Lower pressure ratios reduce compression costs in nitrogen generation for electronics manufacturing.
Permeation claims the steepest expansion trajectory as membrane materials advance; Absorption retains residual share in legacy infrastructure.
Application:
End-use requirements shape membrane format selection, pressure rating, and purity specification.
- Hydrogen Recovery:Refinery purge gas upgrading demands high-pressure hollow-fiber modules with H2-CO2 selectivity exceeding 50. Installations in Texas, Louisiana, and Rotterdam compress replacement cycles to 3-5 years under tightening emissions mandates.
- Carbon Capture:Post-combustion CO2-N2 separation drives mixed-matrix adoption as silica-zeolite loadings improve selectivity. Cement and steel retrofits across Germany, Poland, and Belgium expand addressable demand under EU Green Deal compliance cliffs.
- Natural Gas Processing:Acid gas removal and dehydration duties favor spiral-wound configurations in North American shale basins.
- Biogas Upgrading:Polydimethylsiloxane-polyimide interpenetrating networks halve methane slip at Danish and Dutch agricultural digesters.
- Air Separation:Nitrogen generation for chemical manufacturing clusters in the Rhine-Ruhr region prioritizes membrane trains over refrigerant-dependent cryogenic units.
Procurement volumes concentrate in Hydrogen Recovery; Carbon Capture is climbing the fastest as industrial retrofit obligations intensify.
End User:
Customer scale and technical sophistication determine contract structure, from capital purchase to performance-guaranteed supply.
- Oil & Gas Producers:Integrated majors and shale operators deploy membranes across upstream conditioning and downstream hydrogen recovery. Performance-based contracts now dominate Texas and Louisiana procurement, transferring permeate purity risk to suppliers.
- Chemical Manufacturers:German producers anchor polymeric membrane demand for onsite nitrogen generation and hydrogen conditioning, sustaining thin-film composite hollow-fiber procurement.
- Power Generation Companies:Carbon capture retrofits at combined-cycle plants drive preliminary membrane qualification activity.
- Gas Distributors:Biogas injection specifications require upgrading at agricultural digestion facilities across Denmark, the Netherlands, and India.
- Research Laboratories:Pilot-scale mixed-matrix validation supports technology transfer to commercial production.
Contract value concentrates with Oil & Gas Producers; Chemical Manufacturers are gaining share fastest through captive membrane integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volumes for gas separation membranes concentrate in industrial clusters where refinery hydrogen recovery and biogas upgrading obligations intersect with tightening emissions mandates.
United States
Refinery operators along the Gulf Coast deploy hollow-fiber modules for hydrogen recovery retrofits under EPA New Source Performance Standards. The Texas-Louisiana chemical corridor compresses membrane replacement cycles to 3-5 years as continuous venting reduction mandates take effect. Performance-based supply contracts now dominate procurement, transferring permeate purity risk to engineering-procurement-construction firms.
Germany
Chemical manufacturers in the Rhine-Ruhr region anchor European demand for thin-film composite hollow fibers used in onsite nitrogen generation. EU Green Deal carbon-neutrality timelines drive preliminary qualification of mixed-matrix membranes for cement and steel carbon capture retrofits. REACH compliance requirements favor incumbent suppliers with established material safety dossiers.
China
Dual carbon goals under the national climate commitment accelerate membrane deployment at coal-to-chemical facilities and refinery complexes. The country's national environmental regulator tightens permissible venting rates from gas processing equipment. Shandong Peninsula industrial clusters pilot ceramic-polymer mixed-matrix formats for high-temperature refinery applications beyond polymer stability limits.
India
Agricultural waste-to-energy projects under the PLI scheme create demand for spiral-wound biogas upgrading elements where capital constraints shape procurement. The Bureau of Indian Standards develops module certification pathways for high-pressure natural gas conditioning. Gujarat and Maharashtra anchor early deployment at anaerobic digestion facilities seeking grid injection compliance.
Netherlands
Biogas upgrading installations at Danish and Dutch agricultural digesters adopt polydimethylsiloxane-polyimide interpenetrating networks on shortened 3-5 year replacement cycles. EU F-Gas Regulation phase-down schedules force refrigerant-dependent cryogenic separation retrofits at industrial gas facilities. Rotterdam refinery operators evaluate membrane trains for hydrogen recovery alongside carbon capture integration.
Global Gas Separation Membranes Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers scale hollow-fiber spinning operations to meet compressed replacement cycles in refinery applications. The vendor base organizes around three archetypes: diversified industrial gas majors with captive membrane manufacturing, specialized polymer material suppliers with phase-inversion expertise, and engineering-procurement-construction firms integrating third-party modules into performance-guaranteed systems. Strategic partnerships and technology licensing represent the dominant competitive vectors, with raw material premia for mixed-matrix formats pushing selective vertical integration into silica-zeolite supply.
Among diversified industrial conglomerates, Honeywell International Inc. and Linde Plc occupy positions that exemplify the captive-manufacturing archetype, while Evonik Industries AG represents specialized material science capability in thin-film composite formats. These three entities anchor distinct competitive positions: Honeywell leverages refinery process heritage, Linde secures large-scale air separation contracts through European manufacturing, and Evonik concentrates high-pressure hollow-fiber expertise.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Schlumberger Limited |
| Linde Plc |
| Fujifilm Holdings Corporation |
| Parker Hannifin Corporation |
| Air Products and Chemicals Inc. |
| UBE Corporation |
| Evonik Industries AG |
| Air Liquide |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap hollow-fiber specialists in Germany and Japan anchor supply-side discipline, compressing procurement timelines for refinery operators while extracting stability premiums through captive phase-inversion expertise and REACH-certified material dossiers.
Pricing Analysis
Volume procurement of polyimide hollow-fiber modules commands thin margins at Texas and Louisiana refineries, while mixed-matrix formats with silica-zeolite loadings sustain 40-60% raw material premia at German carbon capture installations. Price differentiation hinges on certification tier—REACH-compliant thin-film composites trade at structural premiums over uncertified alternatives—and volume scale, with agricultural digester operators in India and Denmark facing acute capital constraints. Cost compression in standard polymeric tiers is intensifying because Chinese coal-to-chemical facilities are scaling captive membrane manufacturing. Chemical manufacturers in the Rhine-Ruhr region show least price sensitivity due to performance-guaranteed contract structures, while Indian biogas project developers under the PLI scheme exhibit highest sensitivity, prioritizing spiral-wound capital efficiency over lifecycle cost.
Supply Chain Analysis
Direct-to-refinery channels handle North American hydrogen recovery demand, while EPC-integrated sourcing dominates European carbon capture retrofits. Hollow-fiber spinning capacity concentrates in Germany, Austria, and Japan, with ceramic nanofiller supply drawing from Chinese and American specialty chemical producers. Raw material dependencies span polyimide resin, polydimethylsiloxane precursor, and silica-zeolite nanoparticles. Single-source vulnerability pervades high-pressure natural gas conditioning modules, where thin-film composite manufacturing clusters in Central Europe create concentrated supply risk. Distribution runs through engineering-procurement-construction firms with integrated membrane system capabilities, particularly for performance-based contracts transferring permeate purity risk to suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane supplier consolidation is accelerating as REACH compliance timelines and hollow-fiber spinning talent scarcity force sub-scale material suppliers toward exit or acquisition, compressing the vendor base around diversified industrial gas majors and specialized polymer science firms.
For Market Incumbents: Anticipate displacement pressure from sorbent-metal-organic-framework hybrids in select hydrogen purification duties by deepening captive silica-zeolite supply chains and accelerating ceramic-polymer mixed-matrix validation for high-temperature refinery applications above polymer stability limits. Prioritize backward integration into ceramic nanofiller production to defend margin position against raw material premia erosion. For New Entrants and Emerging Players: Begin with agricultural waste-to-energy installations under India's PLI scheme, where capital-constrained procurement favors spiral-wound biogas upgrading elements and incumbent presence remains thin. Target performance-guaranteed supply contracts rather than capital sales, leveraging third-party membrane integration to transfer technical risk while building operational track records. For Investors and Strategic Acquirers: Distressed-cycle entries favor hollow-fiber spinning specialists with established REACH dossiers in Germany and Austria, where regulatory barriers protect incumbent value and replacement-cycle compression at refineries sustains recurring revenue visibility. Watch for inflection in EU F-Gas Regulation enforcement intensity across Belgian and French industrial gas facilities, as compliance cliffs accelerate membrane pre-qualification activity and expand addressable retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica-Zeolite Supply | Captive nanofiller production defends mixed-matrix margins against 40-60% raw material premia at German carbon capture installations. |
| Ceramic-Polymer Mixed-Matrix Scale-Up | Temperature tolerance beyond 150°C opens high-temperature refinery applications where polyimide stability fails at Shandong Peninsula clusters. |
| Performance-Guaranteed Contract Expansion | Permeate purity risk transfer to EPC firms concentrates procurement authority among integrated system suppliers in Texas and Louisiana. |
| Hollow-Fiber Spinning Capacity Addition | Compressed 3-5 year replacement cycles at Gulf Coast refineries demand expanded phase-inversion output to match turnaround schedules. |
| REACH Dossier Completion Acceleration | 18-24 month regulatory timelines favor incumbent suppliers with established material safety registrations for European module certification. |
Research Methodology
Document review covered EPA New Source Performance Standards filings, EU F-Gas Regulation implementation guidance, and SEC 10-K disclosures from diversified industrial gas majors, complemented by interviews with refinery process engineers, hollow-fiber manufacturing technical directors, EPC procurement leads, and chemical manufacturer plant managers. Secondary validation drew from customs trade data, REACH registration databases, and national environmental regulator permitting records. Bottom-up membrane deployment estimates triangulated against top-down industrial gas processing capacity assessments.
Segment-level value outputs trace from material-grade procurement patterns through application-specific replacement-cycle frequencies across the projection horizon. The analytical framework models membrane type, technology, application, and end-user dimensions, with regional regulatory cluster and performance-tier contract structure as industry-specific overlays. CAGRs derive from vintage deployment tracking and compliance-mandated retrofit obligation quantification, incorporating silica-zeolite loading cost trajectories and hollow-fiber spinning capacity expansion announcements as key forecast inputs.
Underlying measurement precision varies by segment; polymeric membrane volumes carry tighter precision than emerging mixed-matrix placements where commercial deployment remains nascent. Forecasts reflect assumptions around EPA enforcement intensity, EU Green Deal timeline adherence, and ceramic-polymer convergence technical maturation. Periodic stress-testing of base assumptions is recommended against regulatory delay risk, substitute technology performance breakthroughs, and commodity polymer price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membranes Market
Membrane Materials
Breather Membranes Market