
 Functional Cosmetic Ingredients Market | 2026-2036
Functional Cosmetic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Cosmetic Ingredients Market Foresight
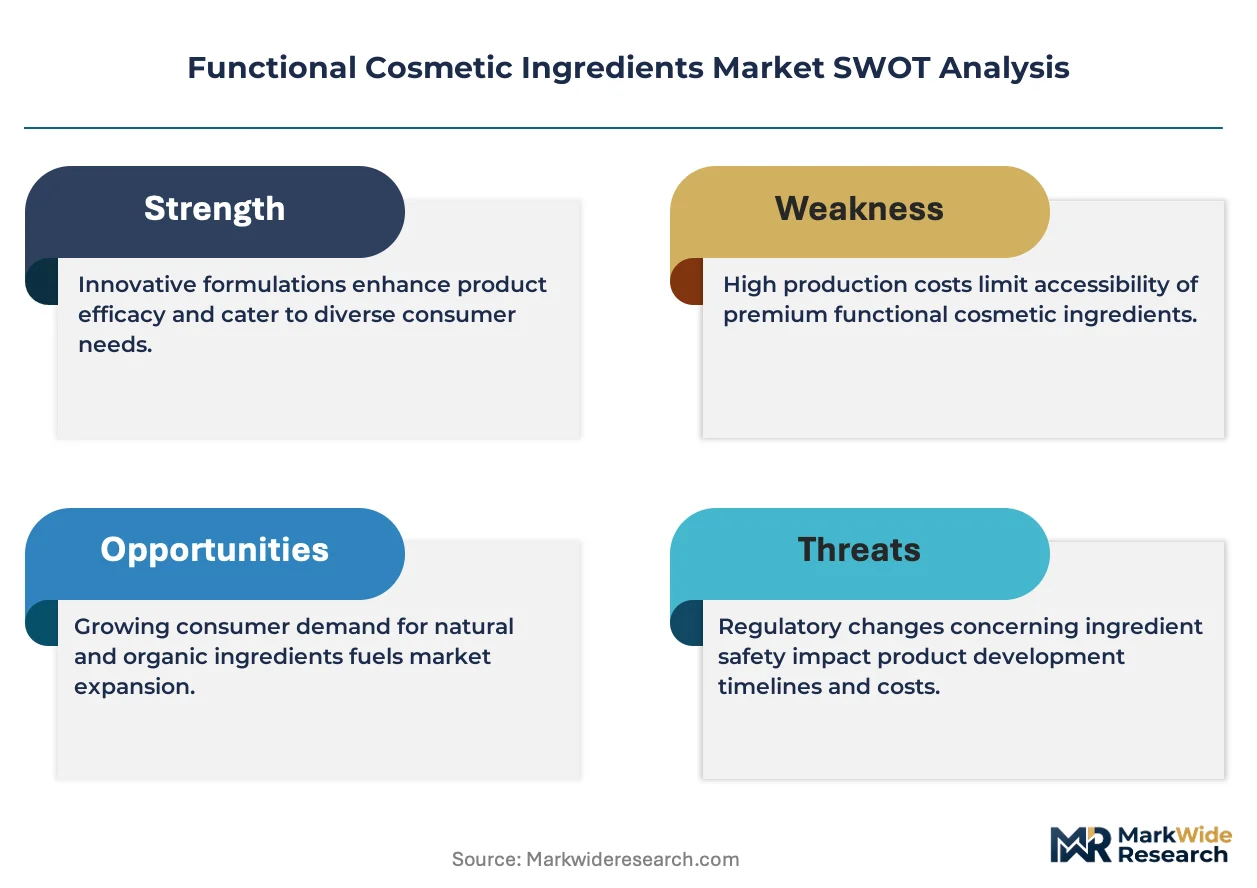
Buyer concentration among indie skincare labels is expanding as direct-to-consumer brands multiply and fragment procurement volumes. BASF SE leverages its integrated biotechnology platform to supply fermented actives at scale. Croda International Plc anchors its position through lipid-specialized emollients derived from plant-based feedstocks. Evonik Industries AG differentiates via peptide-based functional ingredients targeting dermal barrier repair.
Functional cosmetic ingredients comprise biologically active compounds engineered to deliver measurable skin or hair benefits beyond basic aesthetic coverage, including specified concentrations of niacinamide, hyaluronic acid derivatives, or ceramide complexes manufactured through fermentation or enzymatic synthesis. Their primary commercial purpose centers on substantiating product claims with clinical performance data demanded by informed consumers. Emollients and humectants dominate current ingredient-type revenue as staple moisturizing agents across mass and prestige tiers. Biotechnology-derived formulations represent the fastest-expanding formulation category as enzymatic processes replace petrochemical routes. Skin care applications capture the deepest margin pools due to premium pricing on anti-aging and barrier-repair actives.
REACH registration requirements and the EU Green Deal's chemical sustainability targets compel reformulation toward biodegradable, non-toxic ingredient profiles across European supply chains. The US FDA maintains active oversight of cosmetic safety substantiation while state-level legislation in California advances stricter ingredient disclosure mandates. China's NMPA and GB standards govern imported cosmetic raw materials with escalating documentation demands for novel biotech-derived actives. Stakeholders must monitor regulatory divergence between jurisdictions when prioritizing R&D investment and regional manufacturing placement.
Market Dynamics
Biotechnology fermentation platforms are displacing solvent-based extraction across active ingredient manufacturing, compressing batch-to-batch variability while elevating purity thresholds demanded by clinical claim substantiation. This substrate shift rewires capital allocation, supplier qualification timelines, and raw material sourcing geography across the value chain.
Growth Catalysts
- REACH registration tiers:The EU Green Deal's chemical sustainability targets accelerate biodegradable emollient adoption, forcing formulators to retire petrochemical-derived humectants ahead of compliance deadlines.
- Peptide synthesis automation:Solid-phase manufacturing advances cut production cycles for barrier-repair actives, enabling mid-tier skincare brands to access previously cost-prohibitive dermal therapeutics.
- South Korean clinical validation infrastructure:Seoul-based dermatology research institutes supply efficacy data that satisfies MFDS documentation requirements for novel biotech-derived materials entering Asian markets.
Market Restraints
- Plant oil feedstock volatility:Specialty lipid prices fluctuate with Brazilian soybean and Malaysian palm harvest cycles, squeezing emollient margins without pass-through mechanisms in fixed-price supply agreements.
- Fermentation capacity concentration:Commercial-scale bioreactor networks cluster in Germany and Switzerland, creating geographic single-source vulnerability for brands dependent on enzymatically synthesized ceramides.
- Preservative system incompatibility:Clean-label formulations excluding parabens and formaldehyde releasers face microbial stability failures that shelf-life testing protocols struggle to predict.
Strategic Opportunities
- India's PLI scheme for biotechnology:Central government production-linked incentives attract contract fermentation capacity for export-oriented active ingredient manufacturing at cost structures below European baselines.
- Scalp microbiome applications:Hair care brands seek sebum-regulating postbiotics that transfer technical capabilities developed for facial barrier repair into underserved follicular health positioning.
- Direct-to-consumer sampling integration:Indie skincare labels embed single-use active concentrate pouches into subscription boxes, bypassing traditional distributor markups while capturing consumption data for formulation refinement.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates among veterans of pharmaceutical biologics manufacturing, forcing cosmetic ingredient producers to compete for compensation packages against vaccine sector employers.
- Novel food-cosmetic regulatory divergence:Ingredients with dual-use potential—such as certain algae-derived antioxidants—face conflicting safety dossier requirements between EFSA food additive pathways and ECHA REACH cosmetic registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Cosmetic Ingredients Market |
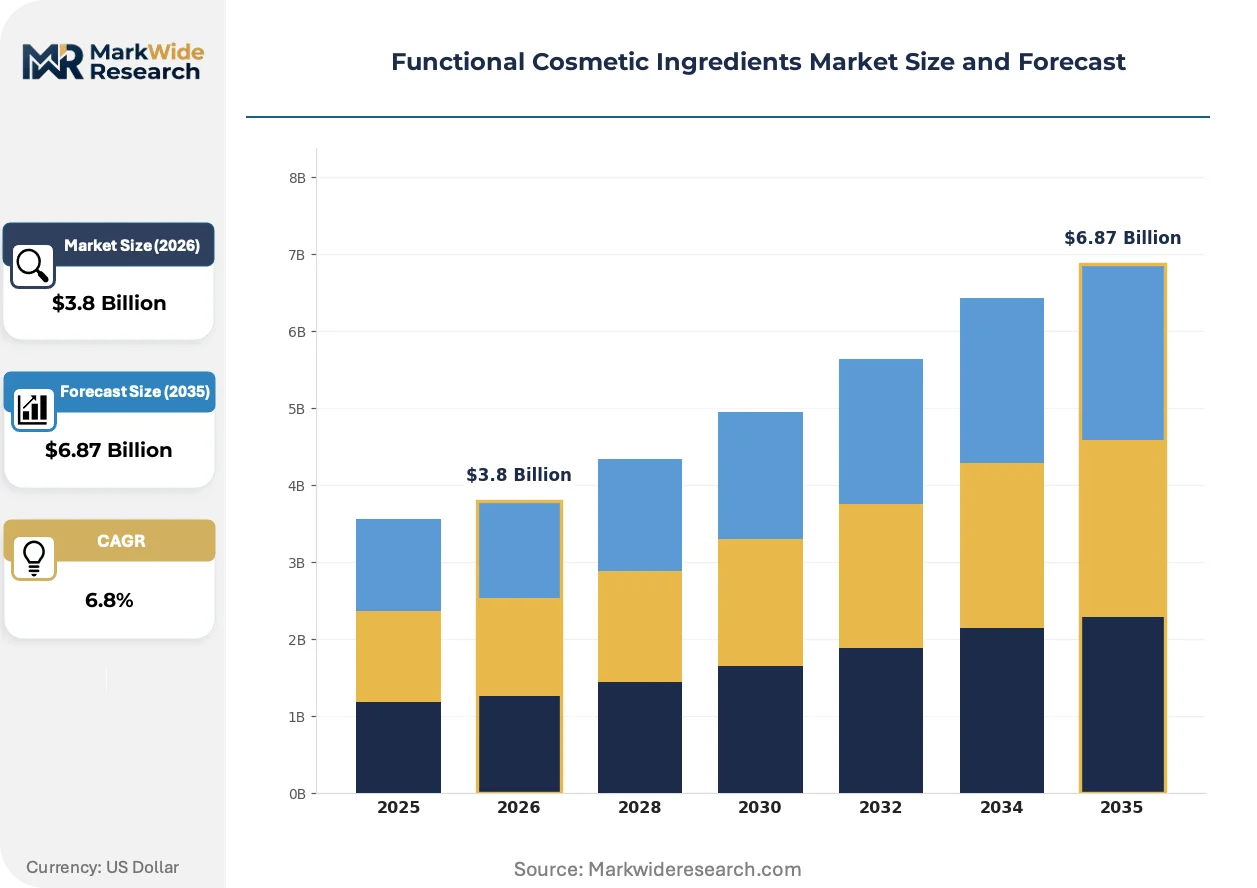
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Emollients, Humectants, Emulsifiers, Preservatives Application: Skin Care, Hair Care, Makeup, Fragrance Formulation Category: Organic, Natural, Synthetic, Biotechnology End User: Manufacturers, Distributors, Retailers, Professionals |
| Companies Covered | BASF SE, Dow Inc., Croda International Plc, Evonik Industries AG, Clariant AG, Ashland Global Holdings Inc., Solvay SA, Lonza Group Ltd., Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Cosmetic Ingredients Market Shifts & Advancements
Fermentation-derived actives are compressing the cost-performance frontier for clinically validated cosmetic ingredients, while regulatory documentation requirements harden technical barriers to market entry. These forces reward incumbent biotechnology platforms with established quality systems and punish speculative formulators lacking analytical infrastructure.
Cell-free enzymatic synthesis bypasses whole-cell fermentation constraints, enabling precise glycosylation patterns on hyaluronic acid variants that match dermal penetration specifications. Prestige skincare brands in France and South Korea adopt these materials for premium anti-aging lines despite 40% raw material cost premiums over conventional fermentation grades. The technology is expanding into mass-market niacinamide production as enzyme immobilization techniques cut catalyst replacement frequency.
China's NMPA intensifies documentation demands for novel biotech-derived cosmetic raw materials, requiring extended toxicological dossiers that delay market entry by 18-24 months compared to conventional chemical registrations. Domestic Chinese ingredient suppliers exploit this friction by accelerating GB standard compliance for established fermentation platforms before foreign competitors complete novel substance filings. Multinational formulators now pre-position manufacturing partnerships with NMPA-registered Chinese biotech firms to circumvent direct import authorization delays.
Clean-label preferences compress ingredient lists to five-to-seven declared components, eliminating multifunctional synthetic polymers that previously delivered texture, stability, and sensorial benefits simultaneously. Indie skincare labels in Germany and California respond by sourcing single-function natural alternatives—separate emollients, separate rheology modifiers, separate preservation systems—accepting higher formulation complexity and per-unit input costs. This specification cascade elevates supplier qualification burdens as brands audit upstream agricultural practices for pesticide residues and labor compliance.
Functional Cosmetic Ingredients Market Segmentation
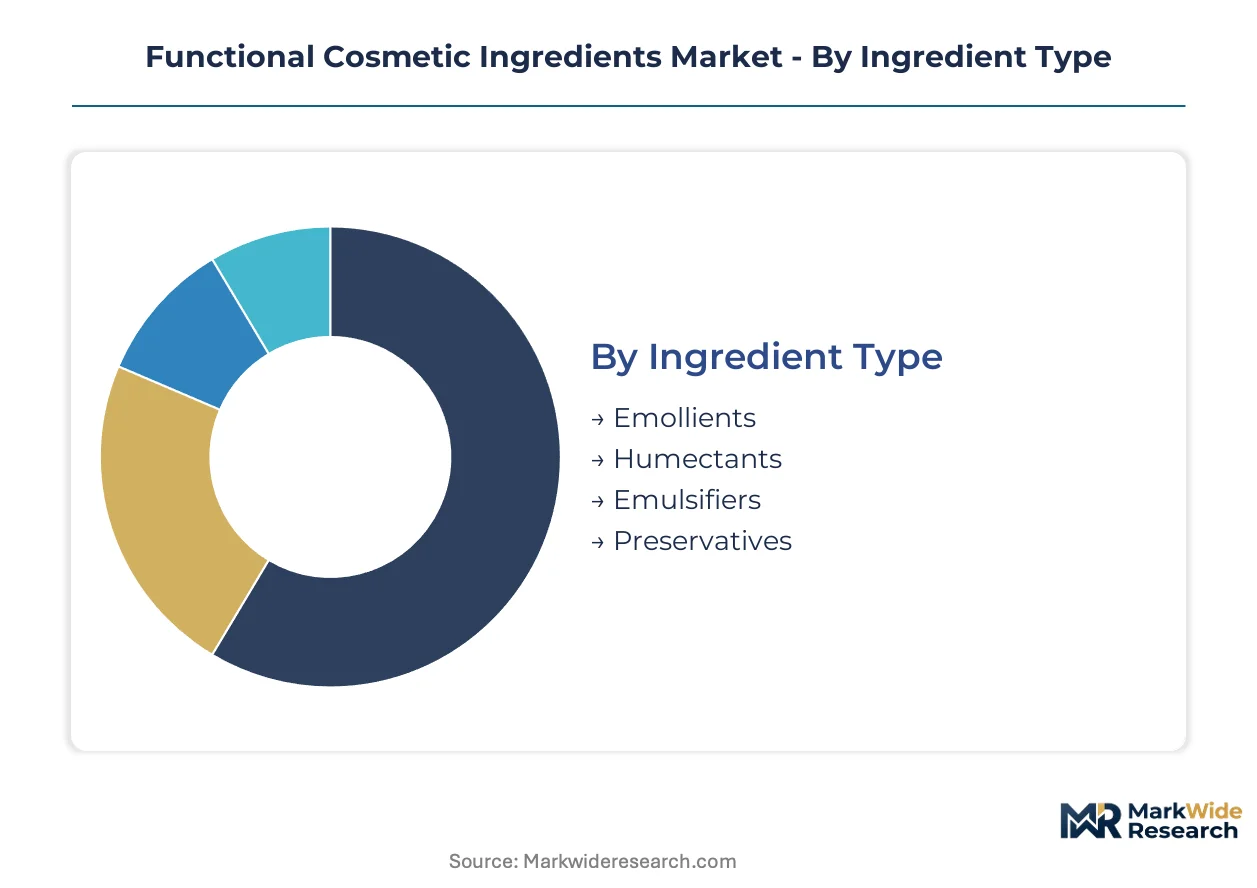
Ingredient classification determines procurement strategy, regulatory pathway, and margin structure across cosmetic supply chains. Formulators select segments based on clinical validation requirements, clean-label positioning, and compatibility with target market regulations.
Ingredient Type:
Upgrade cycles accelerate as brands retire petrochemical-derived staples in favor of biotech alternatives that satisfy tightening documentation standards.
- Emollients:Lipid-based compounds including esters, fatty alcohols, and plant-derived oils that restore skin barrier function and enhance spreadability. Demand clusters in prestige skincare lines from Germany and South Korea where consumers prioritize sensorial texture alongside clinical efficacy. REACH registration deadlines for petrochemical alternatives compress adoption timelines for biodegradable substitutes.
- Humectants:Hygroscopic molecules—principally glycerin variants, hyaluronic acid derivatives, and sugar alcohols—that bind atmospheric moisture to stratum corneum. Mass-market moisturizers in France and California drive volume procurement, though supply agreements increasingly specify fermentation-derived grades to preempt clean-label criticism. Water activity management limits substitution flexibility in anhydrous formulations.
- Emulsifiers:Surfactant systems stabilizing oil-water interfaces in cream and lotion matrices.
- Preservatives:Antimicrobial compounds ensuring microbiological stability through shelf life.
Volume placements concentrate in Emollients; the faster expansion belongs to Humectants as hydration-focused claims multiply across tiered price points.
Application:
Margin capture varies sharply by end-use, with dermal therapeutics commanding price premiums over rinse-off or decorative categories.
- Skin Care:Leave-on facial and body treatments incorporating active concentrations for barrier repair, photodamage mitigation, and sebum regulation. Anti-aging serums from Seoul-based brands and microbiome-focused creams from German indie labels concentrate demand for peptide complexes and postbiotic ferments. Clinical validation infrastructure in South Korea accelerates novel active adoption.
- Hair Care:Scalp treatments and conditioning systems leveraging ceramide technology originally developed for facial applications. French salon brands and direct-to-consumer labels in California drive procurement of scalp microbiome actives as follicular health positioning gains traction. Rinse-off formats tolerate lower active concentrations than leave-on skin products.
- Makeup:Color cosmetics incorporating skincare benefits through hybrid formulation architectures.
- Fragrance:Fine fragrance and functional perfumery utilizing encapsulated or bound active delivery systems.
Revenue pools deepen in Skin Care; Hair Care is climbing the fastest as technical capabilities transfer across application domains.
Formulation Category:
Raw material sourcing geography and capital intensity diverge substantially across production methodologies, with biotechnology platforms requiring dedicated fermentation infrastructure.
- Biotechnology:Enzymatically synthesized or fermented actives including ceramides, peptides, and hyaluronic acid variants manufactured in controlled bioreactor environments. German and Swiss contract manufacturers dominate commercial-scale supply, though India's PLI scheme attracts greenfield capacity investment. Cell-free enzymatic synthesis enables precise molecular tailoring for premium positioning.
- Natural:Botanically extracted compounds from cultivated or wild-harvested feedstocks subject to agricultural variability and pesticide residue auditing.
- Organic:Certified cultivation and processing chains meeting ECOCERT or USDA NOP standards with restricted synthetic input allowances.
- Synthetic:Petrochemical-derived molecules facing reformulation pressure under EU Green Deal chemical sustainability targets.
Manufacturing investment flows toward Biotechnology; Organic certification requirements are gaining share fastest in German and French clean-label segments.
End User:
Procurement scale and technical sophistication fragment sharply across buyer types, with implications for supplier qualification protocols and pricing architecture.
- Manufacturers:Finished goods producers—multinational houses, contract manufacturers, and indie formulators—specifying raw materials against stability, efficacy, and regulatory dossier requirements. Direct relationships with fermentation specialists in Germany and Switzerland secure supply priority for novel biotech actives. Volume commitments and exclusivity clauses structure pricing tiers.
- Distributors:Regional and specialty chemical traders aggregating fragmented demand from smaller formulators.
- Retailers:Private-label skincare lines from pharmacy chains and specialty beauty retailers sourcing finished actives or concentrate blends.
- Professionals:Salon, spa, and medical aesthetic channels utilizing professional-grade concentrations with treatment-protocol specificity.
Contract concentration favors Manufacturers; Retailer private-label expansion is expanding most quickly as vertical integration displaces traditional brand intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, France, and South Korea as formulators prioritize clinically validated active compounds. These markets anchor procurement volumes for biotechnology-derived emollients and peptide complexes.
Germany
Prestige skincare manufacturers in Hamburg and Düsseldorf drive demand for fermented ceramides and barrier-repair actives. REACH registration tiers and the EU Green Deal's chemical sustainability targets compel rapid reformulation away from petrochemical-derived humectants. Bavaria hosts commercial-scale bioreactor networks supplying enzymatically synthesized hyaluronic acid variants to European formulators.
France
Paris-based luxury houses and indie skincare labels in Provence prioritize sensorial emollients with ECOCERT-compliant sourcing credentials. ANSM enforces stringent cosmetic safety substantiation requirements that elevate documentation burdens for novel biotech actives. The Auvergne-Rhône-Alpes corridor clusters lipid-specialized manufacturers serving clean-label formulation demand.
South Korea
Seoul-based dermatology research institutes supply efficacy data satisfying MFDS documentation requirements for novel biotech-derived materials. Anti-aging serums and microbiome-focused creams from domestic brands concentrate demand for peptide complexes and postbiotic ferments. The Seoul Capital Area anchors clinical validation infrastructure that accelerates novel active adoption across Asian markets.
United States
California's direct-to-consumer skincare brands and New York Metro contract manufacturers fragment procurement volumes across indie formulators. The FDA maintains active oversight of cosmetic safety substantiation while state-level legislation advances stricter ingredient disclosure mandates. The Pacific Northwest clusters natural extraction specialists serving clean-label positioning requirements.
China
Shanghai and Beijing-based formulators face escalating NMPA documentation demands for novel biotech-derived cosmetic raw materials. Domestic ingredient suppliers accelerate GB standard compliance for established fermentation platforms ahead of foreign competitors. The Yangtze River Delta concentrates manufacturing partnerships that circumvent direct import authorization delays for multinational brands.
Functional Cosmetic Ingredients Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cell-free enzymatic synthesis and scalp microbiome applications. The market structures around biotechnology platforms with integrated fermentation infrastructure, lipid-specialized emollient suppliers, and peptide synthesis specialists. Three archetypes dominate: integrated chemical conglomerates with biotech divisions, dedicated cosmetic ingredient houses with plant-based feedstock expertise, and contract manufacturers scaling novel active production. Competitive moves center on capacity expansion in India's PLI-attracted fermentation zones and strategic partnerships with NMPA-registered Chinese biotech firms.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes leveraging biotechnology platforms for active ingredient supply. Croda International Plc occupies a position among lipid-specialized houses with plant-derived emollient capabilities. These anchors represent divergent strategic postures: fermentation-scale advantages versus feedstock-specialized positioning versus peptide-based functional differentiation.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Croda International Plc |
| Evonik Industries AG |
| Clariant AG |
| Ashland Global Holdings Inc. |
| Solvay SA |
| Lonza Group Ltd. |
| Givaudan SA |
| Others |
Supply & Pricing Matrix
Fermentation-grade hyaluronic acid feedstock costs cascade through three distinct pricing tiers as bioreactor capacity in Bavaria and Basel anchors supply for European formulators while Indian PLI-attracted facilities undercut baseline economics for export-oriented procurement. REACH registration deadlines compress substitution timelines for petrochemical-derived emollients, forcing mid-tier brands to absorb cost premiums or reformulate around biodegradable alternatives.
Pricing Analysis
Volume procurement of mass-market glycerin humectants operates on thin margins, while peptide complexes and cell-free enzymatic synthesis variants capture premium positioning through clinical validation dossiers. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived ceramides with MFDS documentation from conventional grades and unvalidated natural extracts. Pricing pressure stems from Brazilian soybean and Malaysian palm oil volatility squeezing emollient margins without contractual pass-through mechanisms. Indie skincare labels in California exhibit highest price sensitivity, whereas Seoul-based prestige houses absorb premiums for barrier-repair actives with substantiated efficacy claims.
Supply Chain Analysis
China's NMPA documentation mandates for novel biotech-derived materials are forcing multinational brands to pre-position manufacturing partnerships with GB-registered domestic suppliers, circumventing direct import authorization delays. Commercial-scale bioreactor networks concentrate in Germany, Switzerland, and increasingly India, drawing from enzymatic synthesis platforms and plant-based lipid feedstocks. Single-source vulnerability pervades the ceramide supply chain as geographic concentration of fermentation expertise creates bottleneck risk. Distribution runs through direct relationships between biotech specialists and finished goods manufacturers, bypassing traditional chemical distributors for novel actives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic synthesis platforms are displacing solvent-based extraction across active ingredient manufacturing, compressing batch-to-batch variability while elevating purity thresholds. This substrate transition rewards incumbents with established quality systems and analytical infrastructure.
For Market Incumbents: Hedge against fermentation capacity concentration by securing dual-source agreements with Indian PLI-attracted contract manufacturers alongside German and Swiss bioreactor networks. Deepen backward integration into plant oil feedstocks to buffer Brazilian and Malaysian harvest volatility. Prioritize REACH pre-registration for biodegradable emollient portfolios ahead of EU Green Deal compliance deadlines. For New Entrants and Emerging Players: Direct-to-consumer sampling integration offers bypass around traditional distributor markups while capturing consumption data for formulation refinement. Scalp microbiome applications represent the most penetrable white-space as hair care brands seek sebum-regulating postbiotics transferring facial barrier-repair capabilities. Target NMPA-registered Chinese biotech partnerships to circumvent documentation delays for novel actives entering Asian markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor lipid-specialized emollient suppliers with ECOCERT-compliant sourcing credentials in France and Germany as clean-label mandates accelerate. Long-term viability hinges on biotechnology platform ownership rather than extraction-based feedstock dependence. Watch for MFDS approval velocity as the inflection indicator for novel active adoption rates across Asian dermatology research institutes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant Oil Feedstocks | Secures supply of Brazilian soybean and Malaysian palm derivatives against harvest volatility squeezing emollient margins. |
| Cell-Free Enzymatic Synthesis Scale-Up | Enables precise glycosylation patterns on hyaluronic acid variants matching dermal penetration specifications for premium lines. |
| NMPA-Registered Chinese Partnership | Circumvents 18-24 month documentation delays for novel biotech-derived materials entering domestic formulation channels. |
| Scalp Microbiome Active Development | Transfers facial barrier-repair technical capabilities into underserved follicular health positioning for hair care brands. |
| India PLI Scheme Capacity Investment | Attracts contract fermentation infrastructure at cost structures below European baselines for export-oriented manufacturing. |
Research Methodology
Independent corroboration across fermentation technology specialists, cosmetic formulators, and regulatory affairs directors underwrites the qualitative findings in this study. Primary interviews with bioprocess engineers at German and Swiss bioreactor facilities, procurement leads at Seoul-based skincare manufacturers, and REACH registration consultants were validated against secondary sources including ECHA substance dossiers, MFDS cosmetic raw material guidelines, and NMPA GB standard compliance records. Bottom-up volume estimates from ingredient-type procurement patterns were triangulated with top-down market sizing across application segments.
Comparable-period anchoring to historical fermentation capacity expansion and clean-label adoption curves structured the projection methodology across the analysis window. Segmentation modeling incorporated ingredient type, application, formulation category, and end-user archetype dimensions with regional regulatory cluster overlays. CAGRs were derived from growth rate convergence analysis across biotechnology-derived and conventional synthetic platforms, with inputs from enzymatic synthesis yield improvements and documentation timeline compressions.
Inputs from NMPA filing databases and ECHA registration portals were available through the study window; gaps in real-time capacity utilization rates at Indian PLI facilities introduce uncertainty bands around fermentation scale-up assumptions. Forecasts reflect documented substitution elasticities between petrochemical and biotech-derived alternatives. Regulatory divergence between REACH tiers and MFDS documentation requirements could revise adoption timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Anti-Aging Products Market