
 Membrane Polymers Market | 2026-2036
Membrane Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Polymers Market Analytics
The price-performance gap between fluoropolymer membranes and commodity polyamide variants is hardening as end-users segment procurement by application criticality. DuPont leverages its fluoropolymer heritage to command positions in high-purity pharmaceutical and semiconductor water systems. LG Chem Ltd. anchors volume supply for municipal desalination projects across the Middle East and Asia-Pacific. Evonik Industries AG differentiates through specialized polyethersulfone formulations targeting biotechnology separations.
Membrane polymers are synthetic materials engineered into selective barriers, typically 0.1 to 100 micrometers in active layer thickness, that permit targeted molecule or ion transport while blocking contaminants based on size, charge, or solubility parameters. These materials serve primarily to purify, concentrate, or separate process streams across industrial, municipal, and medical applications. Polymeric membranes dominate installed base economics due to scalable solution-casting and phase-inversion manufacturing, though composite membranes capture expanding share in high-pressure reverse osmosis where thin-film polyamide chemistry atop polysulfone support delivers superior salt rejection. Ceramic membranes occupy premium niches in food and beverage sterilization where thermal and chemical stability justify elevated capital outlay.
EPA drinking water standards and the EU Green Deal's zero-pollution ambition for industrial effluent are tightening discharge limits and accelerating membrane replacement cycles in North American and European treatment infrastructure. REACH compliance for per- and polyfluoroalkyl substance content is forcing reformulation of certain fluoropolymer membrane chemistries, creating product registration barriers for non-compliant suppliers. Stakeholders must monitor evolving PFAS regulatory thresholds and assess backward integration into specialized polymer resin production to secure formulation flexibility and cost control.
Market Dynamics
Fluoropolymer chemistry innovations are compressing replacement cycles for reverse osmosis modules as water treatment utilities in arid climates face stricter effluent mandates. DuPont and Chemours advances in fouling resistance are redrawing competitive boundaries between premium and standard membrane tiers.
Growth Catalysts
- Desalination infrastructure:Saudi Arabia's national water authority is executing massive expansion programs that pull fluoropolymer membrane volumes into utility-scale projects.
- REACH compliance pressure:Reformulation requirements for per- and polyfluoroalkyl substance content are accelerating replacement demand as non-compliant suppliers exit European markets.
- Semiconductor water purity:High-purity pharmaceutical and electronics manufacturing specifications are segmenting procurement toward specialized polyethersulfone and fluoropolymer formulations.
Market Restraints
- Specialized resin supply concentration:Backward integration into fluoropolymer resin production is limited to a handful of chemical conglomerates, constraining formulation flexibility for mid-tier membrane fabricators.
- PFAS regulatory thresholds:Evolving per- and polyfluoroalkyl substance limits under EPA and ECHA frameworks are forcing costly product re-registration and reformulation cycles.
- Ceramic membrane substitution:Alumina and titania membranes capture premium food and beverage sterilization applications where thermal stability justifies elevated capital outlay over polymeric alternatives.
Strategic Opportunities
- Biotechnology separations:Specialized polyethersulfone formulations for cell culture media and protein purification represent underpenetrated demand within pharmaceutical downstream processing.
- EU Green Deal tailwind:Zero-pollution ambition for industrial effluent is tightening discharge limits and accelerating membrane replacement cycles in European treatment infrastructure.
- Thin-film composite convergence:Integration of polyamide chemistry atop polysulfone support layers is opening high-pressure reverse osmosis applications previously closed to single-material membranes.
Industry Challenges
- Phase-inversion process expertise:Solution-casting and controlled precipitation know-how remains concentrated among veteran membrane fabricators, creating talent bottlenecks for capacity expansion.
- Multi-layer lamination complexity:Integrating active layers with support substrates and protective coatings requires precision equipment that extends certification timelines for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Polymers Market |
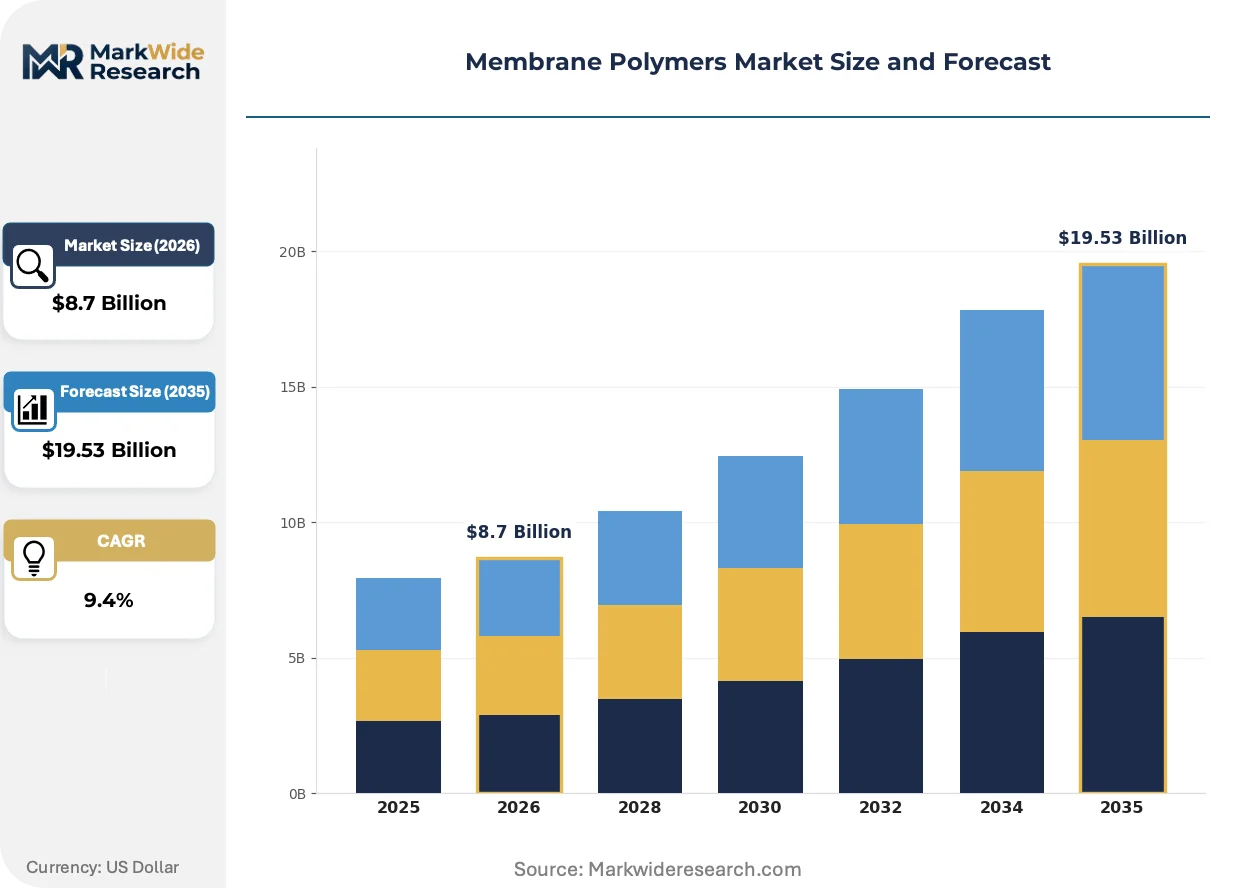
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Membranes, Ceramic Membranes, Composite Membranes, Microfiltration Membranes Application: Water Treatment, Gas Separation, Fuel Cells, Desalination End User: Oil & Gas, Pharmaceutical, Food & Beverage, Chemical Technology: Reverse Osmosis, Ultrafiltration, Nanofiltration, Electrodialysis |
| Companies Covered | Toray Industries, Inc., DuPont, Evonik Industries AG, The Chemours Company, Pall Corporation, Nitto Denko Corporation, LG Chem Ltd., Asahi Kasei Corporation, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Polymers Market Evolving Landscape
Membrane polymer innovation is pivoting from incremental permeability gains toward fouling resistance and chemical durability as end-users prioritize total cost of ownership over initial module price. Manufacturing scale and formulation control are becoming the decisive competitive variables.
Thin-film composite architectures are overtaking homogeneous polymeric membranes in high-pressure reverse osmosis applications. Municipal desalination operators in the Middle East and Asia-Pacific are adopting these structures for superior salt rejection. The technology is compressing market space for single-layer polyamide modules in utility-scale projects.
REACH per- and polyfluoroalkyl substance restrictions are forcing reformulation of certain fluoropolymer membrane chemistries. Product registration barriers are rising for suppliers without compliant resin supply chains. European treatment infrastructure buyers are accelerating qualification of alternative materials to preempt supply disruption.
Utility procurement teams are unbundling membrane module supply from long-term service contracts. Municipal water authorities in Saudi Arabia and Singapore are separating capital equipment purchasing from aftermarket technical support. This pattern is compressing margins for integrated solution providers while opening channel space for specialized fabricators.
Membrane Polymers Market Segmentation
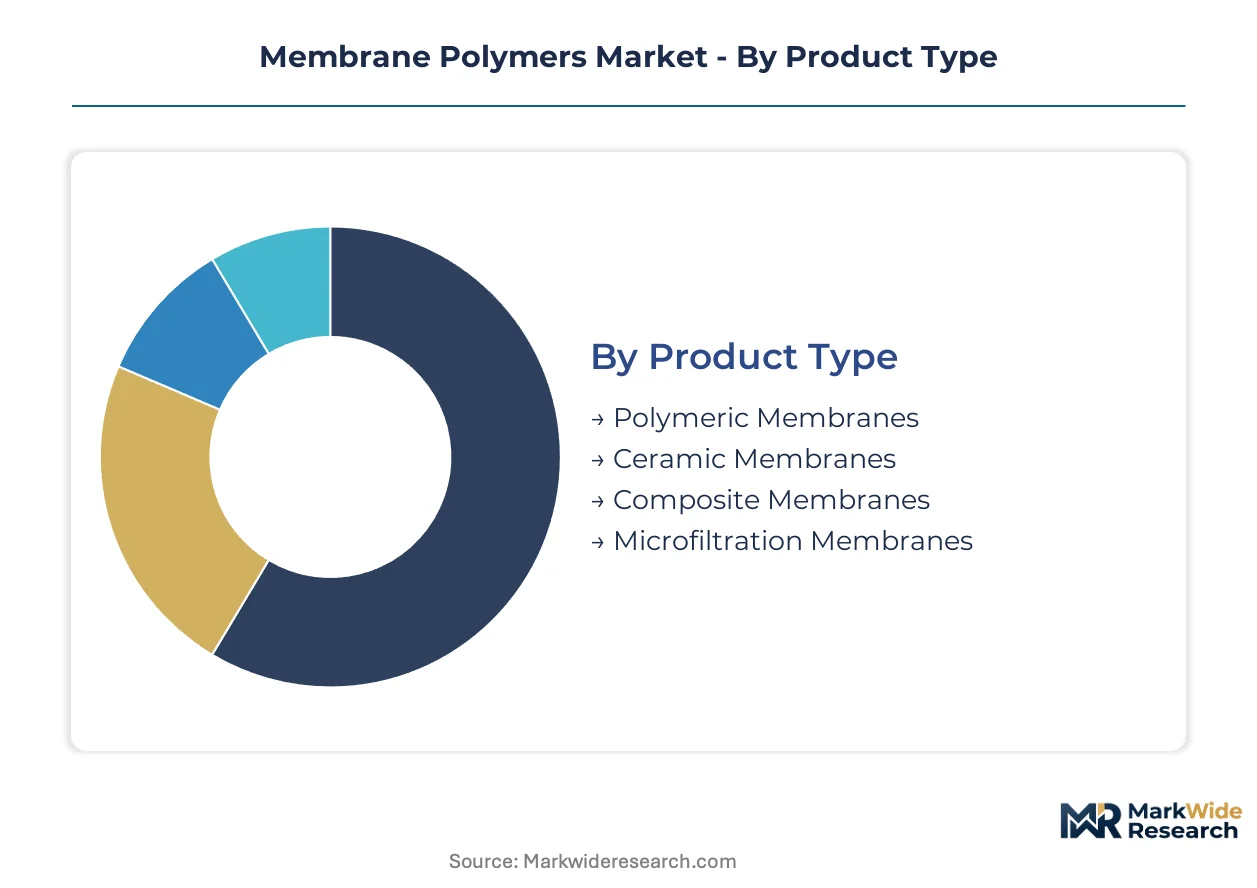
Membrane polymer procurement splits sharply by performance requirements and capital intensity. Buyers in semiconductor water systems demand fundamentally different specifications than municipal desalination operators, creating parallel demand tracks that rarely intersect.
Product Type:
Cost tier separates buyers in this category — premium formulations for critical applications versus commodity volumes for utility-scale projects.
- Polymeric Membranes:Phase-inversion manufacturing of polysulfone, polyethersulfone, and polyamide materials dominates installed base economics. Municipal desalination utilities in Saudi Arabia and Singapore anchor procurement volumes for standard-grade variants.
- Composite Membranes:Thin-film polyamide chemistry atop polysulfone support delivers superior salt rejection in high-pressure reverse osmosis. Semiconductor fabrication plants in South Korea and Taiwan concentrate demand for ultra-high-purity specifications.
- Ceramic Membranes:Alumina and titania structures command thermal stability premiums in food sterilization.
- Microfiltration Membranes:Larger pore structures serve clarification and pre-treatment stages.
Volume sits with polymeric membranes; growth tilts toward composite membranes.
Application:
Application maturity determines whether buyers prioritize replacement cycles or greenfield installation economics.
- Water Treatment:Municipal and industrial effluent systems constitute the foundational demand layer. EPA drinking water standards and EU Green Deal zero-pollution mandates are accelerating replacement cycles across North American and European infrastructure.
- Desalination:Utility-scale projects in arid climates drive fluoropolymer membrane volumes. Saudi Arabia's national water authority expansion programs pull specialized formulations into megaproject procurement.
- Gas Separation:Hydrogen recovery and carbon capture applications are gaining technical traction.
- Fuel Cells:Proton exchange membrane demand tracks electric vehicle and stationary power deployment.
Revenue concentrates in water treatment; steepest expansion trajectory belongs to desalination.
End User:
Customer type dictates specification stringency and contract structure — integrated service agreements versus unbundled module procurement.
- Pharmaceutical:Cell culture media and protein purification demand specialized polyethersulfone formulations with validated extractables profiles. Biotechnology separations represent underpenetrated downstream processing demand.
- Oil & Gas:Produced water treatment and enhanced oil recovery applications tolerate higher fouling rates in exchange for chemical resistance.
- Food & Beverage:Thermal sterilization requirements justify ceramic membrane premiums in dairy and brewing applications.
- Chemical:Solvent-resistant formulations serve process stream concentration and purification.
Pharmaceutical buyers command highest margins; chemical sector procurement is expanding most quickly.
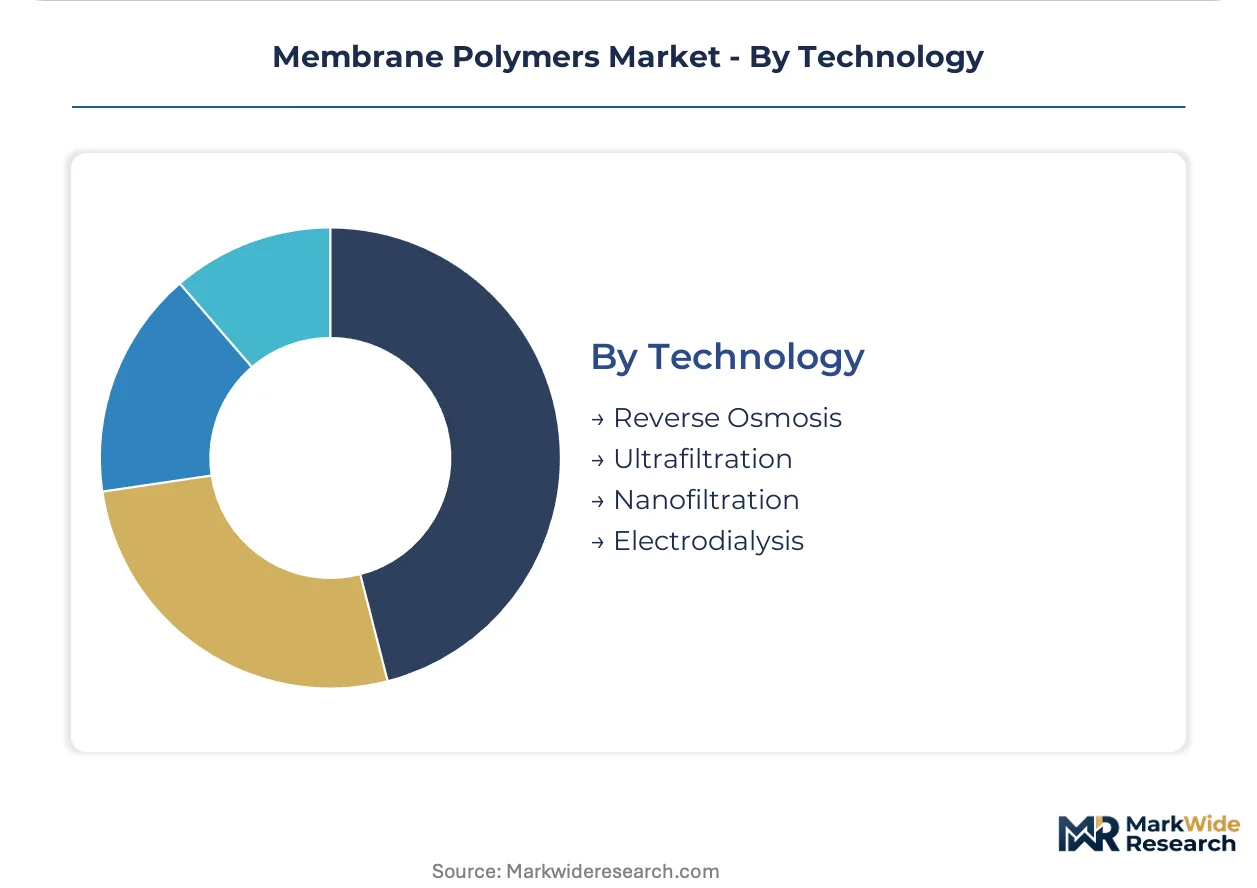
Technology:
Operating pressure and selectivity requirements segment fabricators by manufacturing capability and certification depth.
- Reverse Osmosis:High-pressure operation demands thin-film composite architectures with precise active layer thickness control. REACH PFAS compliance pressures are forcing reformulation of certain fluoropolymer chemistries in European-qualified supply chains.
- Ultrafiltration:Moderate-pressure protein and colloid separation serves pharmaceutical and food processing. Polyethersulfone hollow-fiber configurations dominate biotechnology applications.
- Nanofiltration:Divalent ion selectivity targets water softening and selective salt removal.
- Electrodialysis:Electric field-driven ion transport serves niche brackish water and industrial effluent applications.
Reverse osmosis captures dominant share; nanofiltration is gaining share fastest in selective separation niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors the largest concentration of membrane polymer demand worldwide, hosting Saudi Aramco's water treatment complexes and the kingdom's expanding desalination infrastructure. The regional map tracks arid-zone water stress, semiconductor manufacturing corridors, and tightening effluent regulations across five strategic markets.
Saudi Arabia
Saudi Arabia's national water authority is executing massive desalination expansion programs that pull fluoropolymer membrane volumes into utility-scale projects. The country's national regulator enforces stringent effluent standards that accelerate replacement cycles for reverse osmosis modules. Jubail and Yanbu industrial cities concentrate procurement for petrochemical process water and municipal desalination.
United States
Semiconductor fabrication plants in Arizona and Texas drive demand for ultra-high-purity water systems using specialized polyethersulfone formulations. EPA drinking water standards and emerging PFAS thresholds force reformulation of certain fluoropolymer membrane chemistries. The Southwest water corridor from Phoenix to San Diego anchors municipal membrane replacement programs.
Germany
REACH compliance for per- and polyfluoroalkyl substance content is forcing reformulation of fluoropolymer membrane chemistries and creating product registration barriers. ECHA frameworks accelerate qualification of alternative materials among European treatment infrastructure buyers. The Rhine-Ruhr industrial belt concentrates biotechnology separations demand for specialized polyethersulfone formulations.
China
Municipal desalination operators across Shandong and Tianjin are adopting thin-film composite architectures for superior salt rejection in high-pressure reverse osmosis. The country's environmental ministry enforces dual carbon goals that tighten industrial effluent discharge limits. The Yangtze River Delta semiconductor cluster pulls premium membrane volumes for electronics-grade water systems.
Singapore
NEWater facilities and integrated water management systems anchor Southeast Asia's most advanced membrane polymer procurement patterns. The national water agency unbundles membrane module supply from long-term service contracts, compressing margins for integrated solution providers. Tuas Nexus and Changi water reclamation plants concentrate next-generation desalination technology deployment.
Membrane Polymers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and application criticality, with the price-performance gap hardening as end-users segment procurement by use case. The vendor base organizes into three tiers: integrated chemical conglomerates with captive fluoropolymer resin supply, specialized membrane fabricators with phase-inversion process expertise, and regional assemblers serving price-sensitive municipal projects. Dominant competitive moves include backward integration into specialized polymer resin production and geographic expansion into Middle Eastern desalination corridors.
Within the integrated chemical tier, Toray Industries, Inc. and DuPont exemplify archetypes with formulation control and manufacturing scale. DuPont leverages its fluoropolymer heritage to command positions in high-purity pharmaceutical and semiconductor water systems, while Toray represents Japanese industrial conglomerate positioning across multiple membrane polymer categories. LG Chem Ltd. anchors Korean chemical group participation in volume supply for municipal desalination projects.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| DuPont |
| Evonik Industries AG |
| The Chemours Company |
| Pall Corporation |
| Nitto Denko Corporation |
| LG Chem Ltd. |
| Asahi Kasei Corporation |
| Parker Hannifin Corporation |
| Others |
Value Network & Pricing Analysis
Thin-film composite manufacturing convergence is simultaneously compressing unit economics for high-pressure reverse osmosis modules and consolidating formulation expertise among integrated chemical conglomerates with captive fluoropolymer resin production. Saudi Arabia's national water authority unbundles membrane procurement from service contracts, forcing fabricators to absorb margin pressure while specialty resin supply concentrates in Japan, the United States, and Germany.
Pricing Analysis
Yield-guarantee contracts anchor value-based pricing for semiconductor water systems, where uptime penalties exceed module replacement costs. Three-tier pricing structure across premium, standard, and economy levels segments procurement by application criticality, with pharmaceutical and electronics buyers least price-sensitive and municipal desalination operators driving hardest volume discounts. Cost compression in standard-grade polyamide modules intensifies because Middle Eastern utilities separate capital equipment purchasing from aftermarket technical support.
Supply Chain Analysis
Direct-to-utility channels handle megaproject demand in Saudi Arabia and Singapore, while distributor networks serve fragmented municipal operators across Europe and North America. Fluoropolymer resin production concentrates in the United States, Japan, and Germany, with phase-inversion membrane fabrication drawing from specialized polysulfone and polyethersulfone feedstocks. Single-source vulnerability in perfluorinated precursor chemicals threatens European-qualified supply chains as REACH PFAS restrictions tighten. Distribution runs through regional system integrators for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoropolymer resin supply scarcity props pricing power for integrated chemical conglomerates, constraining capacity expansion for mid-tier membrane fabricators without backward integration into specialized polymer production.
For Market Incumbents: Hedge against ceramic membrane substitution in food sterilization by accelerating polyethersulfone formulation development for biotechnology separations. Secure captive resin supply through upstream partnerships in Japan or the United States to preempt REACH-driven supply disruption. Defend margin position in semiconductor water systems by embedding yield-guarantee service contracts that lock out unbundled module competitors.
For New Entrants and Emerging Players: Capture biotechnology downstream processing demand for specialized polyethersulfone hollow-fiber configurations, a segment where validated extractables profiles create qualification barriers for commodity suppliers. Target European treatment infrastructure buyers accelerating alternative material qualification to preempt PFAS-driven supply gaps. Pursue toll-manufacturing partnerships with established phase-inversion fabricators to bypass multi-year certification timelines for new production lines.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking membrane fabrication capabilities. Long-term viability favors fabricators with demonstrated phase-inversion process expertise and established pharmaceutical validation records. Watch ECHA PFAS regulatory threshold announcements as the critical signal for accelerated replacement demand and supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive supply of perfluorinated precursors insulates against REACH-driven reformulation costs and registration barriers. |
| Biotechnology Separation Formulation Development | Specialized polyethersulfone for cell culture media penetrates underdeveloped pharmaceutical downstream processing demand. |
| Thin-Film Composite Capacity Expansion | Polyamide-on-polysulfone architectures displace single-layer modules in Saudi utility-scale desalination procurement. |
| Yield-Guarantee Service Contract Bundling | Uptime penalties in semiconductor water systems lock out unbundled competitors and sustain premium pricing tiers. |
| European Alternative Material Qualification | Preemptive certification of PFAS-compliant chemistries captures replacement cycles as non-compliant suppliers exit. |
Research Methodology
Independent corroboration across plant managers at membrane fabrication facilities, procurement leads at Saudi and Singapore water authorities, technical R&D directors at integrated chemical groups, and distributor channel partners underwrites the qualitative findings. Primary interview data triangulates against customs and trade flow records, SEC and TSE filings from disclosed membrane polymer producers, European Chemicals Agency regulatory announcements, and desalination project development databases. Bottom-up demand modeling from end-use application volumes converges with top-down chemical industry capacity assessments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span product architecture (polymeric, composite, ceramic), application criticality (pharmaceutical, semiconductor, municipal desalination, industrial effluent), technology pressure regime (reverse osmosis, ultrafiltration, nanofiltration), and regional regulatory cluster (REACH-compliant Europe, EPA-governed United States, MEE-regulated China). CAGRs derive from installed base replacement cycle analysis and greenfield capacity announcements. Forecast inputs incorporate fluoropolymer resin supply constraints and evolving PFAS threshold trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA regulatory enforcement timing and ceramic membrane cost-competitiveness advances. Projections reflect assumptions regarding phase-inversion process expertise concentration and Saudi desalination program execution pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Nafion Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
North America Transparent Conductive Films Market