
 Inorganic Ion Exchange Materials Market | 2026-2036
Inorganic Ion Exchange Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Ion Exchange Materials Market Outlook
Aftermarket service revenue for resin regeneration and spent media replacement is tilting toward specialized chemical service providers rather than equipment OEMs. LANXESS anchors its position through captive regeneration facilities across the Rhine-Ruhr industrial corridor. Mitsubishi Chemical Corporation leverages its synthetic zeolite expertise to dominate high-purity pharmaceutical applications. BASF SE competes on manufacturing scale, sustaining cost advantages in bulk cation exchange resins for municipal water treatment.
Inorganic ion exchange materials are crystalline or amorphous solids with fixed charged sites that selectively bind and release ions from aqueous solutions, typically manufactured through hydrothermal synthesis, sol-gel processing, or controlled precipitation to achieve specific pore architectures and exchange capacities. Their primary commercial purpose centers on separating dissolved contaminants, recovering valuable metals, and conditioning process water across industrial systems. Strong acid cation resins occupy the largest volume position due to entrenched deployment in boiler feedwater softening and demineralization trains. Powder-form materials represent the fastest-growing configuration, driven by direct integration into batch chemical processing and slurry-phase metal recovery circuits. Membrane-form ion exchangers command premium pricing, reflecting specialized fabrication requirements and concentrated demand from pharmaceutical-grade water systems.
The EPA enforces discharge limits under the Clean Water Act that mandate heavy metal removal, directly stimulating resin consumption at US industrial facilities. ECHA administers REACH registration requirements that restrict leachable organics from polymer-based exchangers, elevating compliance costs for suppliers serving European pharmaceutical and food processing end users. China's MEE enforces dual carbon goals that tighten water reuse targets at chemical parks, reshaping procurement specifications for high-capacity anion resins. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations, as emerging limits on PFAS in effluent streams could displace conventional ion exchange with hybrid treatment trains or trigger resin reformulation cycles.
Market Dynamics
Water treatment utilities are consolidating procurement around full-service regeneration contracts rather than spot resin purchases, compressing supplier margins while locking in volume commitments through multi-year framework agreements.
Growth Catalysts
- REACH Purity Mandates:ECHA's tightening leachable organics standards for pharmaceutical-grade ion exchange media force incumbent polymer suppliers toward inorganic alternatives, opening substitution windows for crystalline zeolite and layered double hydroxide formulations.
- China's Dual Carbon Goals:MEE enforcement of water reuse targets at Yangtze River Delta chemical parks mandates closed-loop demineralization systems, driving procurement of high-capacity anion resins with extended regeneration cycles.
- PFAS Effluent Limits:Emerging EPA discharge restrictions on per- and polyfluoroalkyl substances in industrial wastewater trigger pilot deployments of hybrid ion exchange-adsorption trains, creating specification demand for selective fluoride-binding materials.
Market Restraints
- Lithium Hydroxide Feedstock Volatility:Synthetic zeolite synthesis depends on lithium carbonate and sodium aluminate pricing, with 2022-2024 supply disruptions from Chilean and Australian concentrate markets compressing manufacturer margins by double-digit percentages.
- Rhine-Ruhr Supply Concentration:Captive regeneration infrastructure clusters along Germany's industrial corridor concentrate service provider leverage, raising switching costs for Dutch and Belgian water utilities seeking alternative chemical service partners.
- Membrane Bioreactor Substitution:Advanced MBR systems with integrated nutrient recovery are capturing municipal wastewater treatment capex that previously flowed to ion exchange polishing stages, particularly in Scandinavian markets with stringent phosphorus discharge limits.
Strategic Opportunities
- India's Pharmaceutical Water Systems:CDSCO's alignment with USP and EP water quality standards for injectable manufacturing creates specification pull for membrane-form ion exchangers in Hyderabad and Ahmedabad bulk drug production clusters.
- Electrochemical Regeneration Convergence:Pairing conventional resin beds with electrodeionization modules enables continuous operation without chemical regenerants, appealing to semiconductor fabs in Taiwan and South Korea seeking zero-liquid-discharge compliance.
- Brazil's Mining Tailings Recovery:ANVISA and IBAMA joint enforcement of heavy metal containment at iron ore and lithium extraction sites generates demand for mobile ion exchange skids treating acid mine drainage before discharge to Amazon tributaries.
Industry Challenges
- Hydrothermal Synthesis Expertise Gap:Commercial production of engineered zeolites with controlled Si/Al ratios and mesopore architectures requires crystallization chemists and high-pressure reactor operators in short supply across North American and European manufacturing bases.
- Legacy Control System Integration:Brownfield water treatment plants with 1990s-era SCADA infrastructure face communication protocol mismatches when retrofitting smart resin monitoring sensors, delaying automation upgrades at US municipal utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Ion Exchange Materials Market |
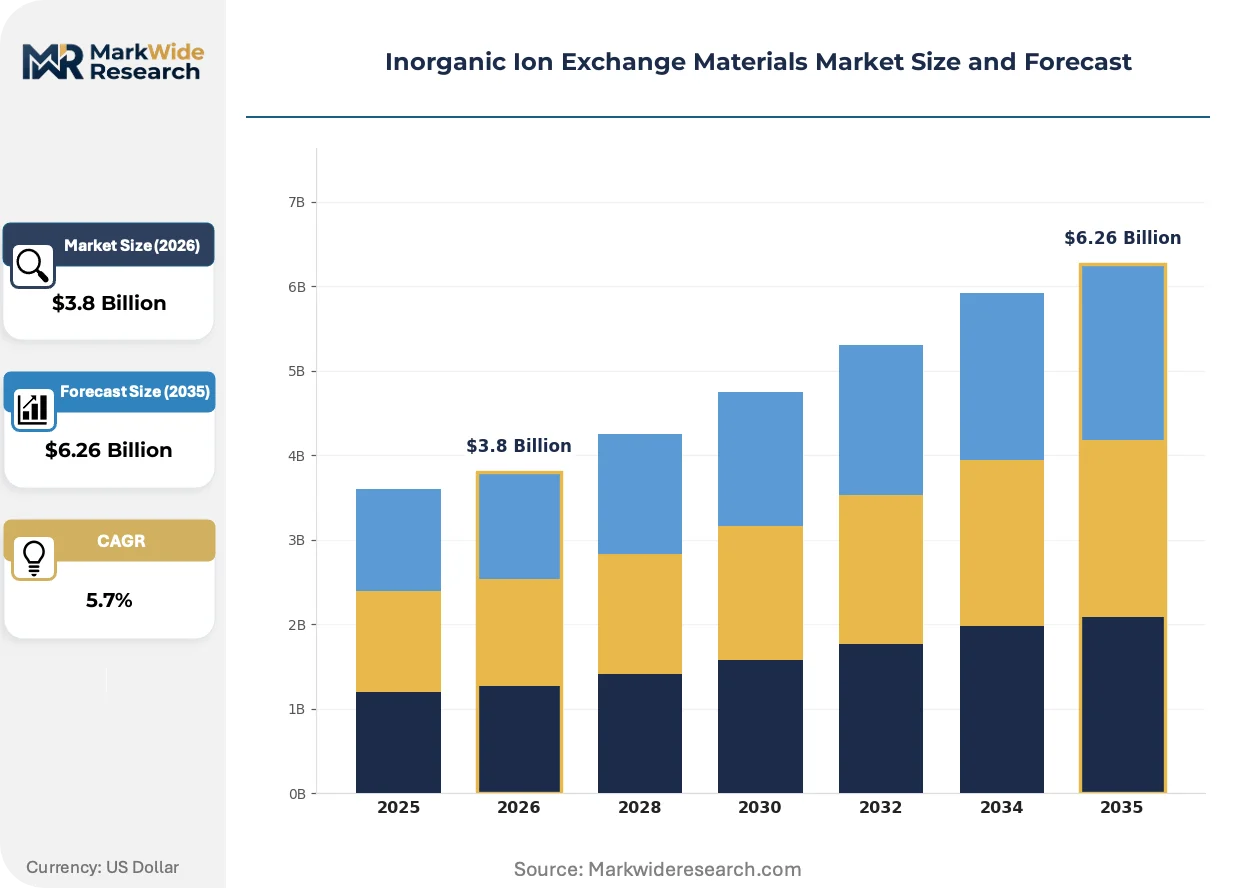
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strong Acid Cation, Weak Acid Cation, Strong Base Anion, Weak Base Anion End Use Industry: Water Treatment, Pharmaceuticals, Food Processing, Chemical Processing Form: Granular, Bead, Powder, Membrane Application: Metal Recovery, Wastewater Treatment, Ion Separation, Desalination |
| Companies Covered | Honeywell International Inc., Mitsubishi Chemical Corporation, LANXESS, Tosoh Corporation, Merck KGaA, Repligen Corporation, Calgon Carbon Corporation, BASF SE, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Ion Exchange Materials Market Strategic Shifts
Digital twin technology and predictive regeneration algorithms are compressing maintenance cycles and redefining service revenue models across industrial water treatment operations.
Layered double hydroxide nanocomposites with tunable interlayer anion selectivity are virtualizing conventional resin performance benchmarks. Pharmaceutical manufacturers in Switzerland and Germany are piloting these materials for selective fluoride and phosphate removal from high-purity water loops. The technology is virtualizing equipment footprints by enabling higher volumetric throughput in existing vessel geometries, reducing capex for facility expansions.
EPA's forthcoming PFAS National Primary Drinking Water Regulation is mandating detection limits below four parts per trillion for PFOA and PFOS. Municipal utilities in Michigan and North Carolina are pre-positioning granular activated carbon-ion exchange hybrid systems to avoid consent decree exposure. The rule is accelerating specification divergence between US and European treatment trains, as ECHA has not yet harmonized PFAS limits under the Drinking Water Directive.
Aftermarket service unbundling is fragmenting long-term chemical supply contracts. Industrial buyers in Japan's Kansai chemical corridor are separating resin procurement from regeneration services, awarding the latter to specialized logistics providers with distributed satellite facilities. This pattern is most visible in electronics manufacturing, where just-in-time water quality requirements favor localized regeneration over centralized OEM service depots.
Inorganic Ion Exchange Materials Market Segmentation
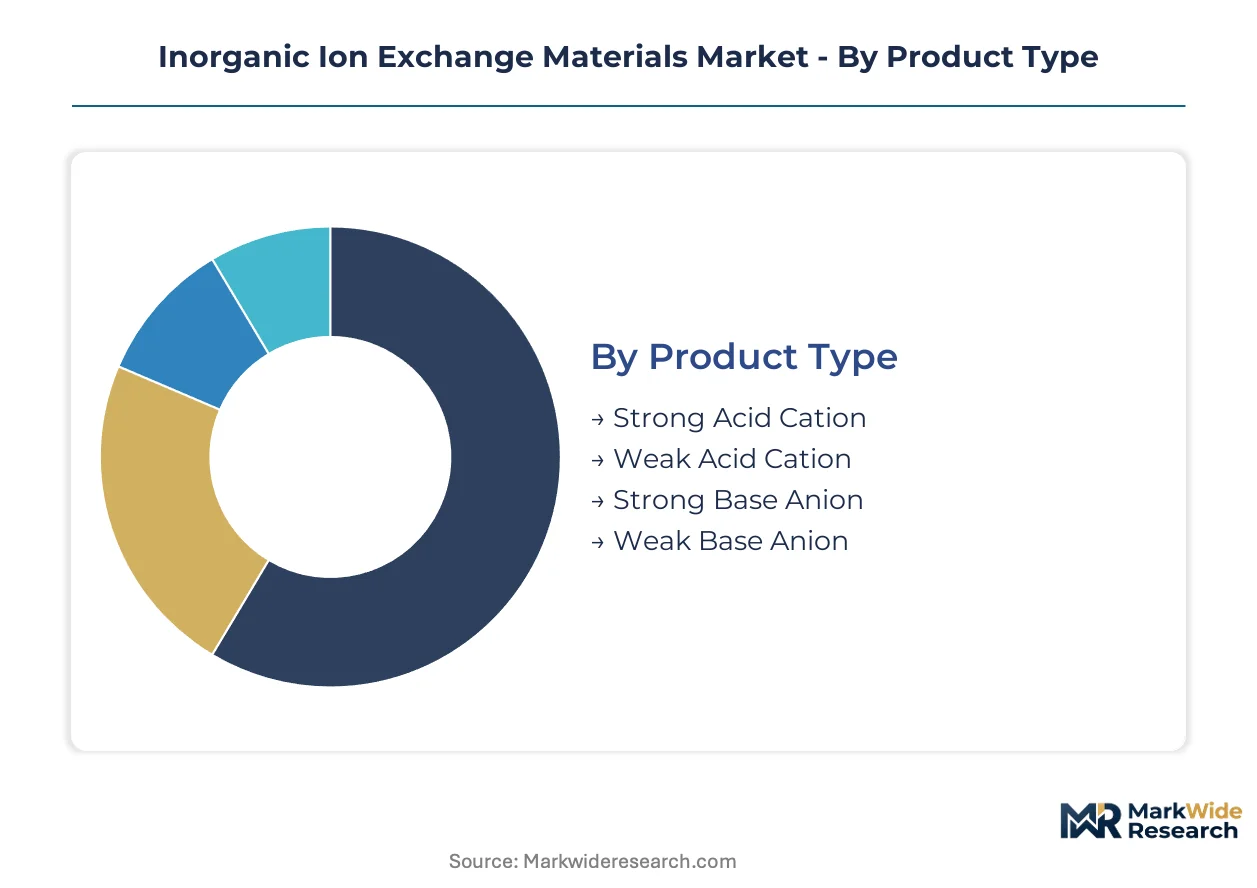
Segmentation in inorganic ion exchange materials reveals how crystalline structure, physical form, and application chemistry dictate procurement patterns across industrial water systems. Manufacturers configure synthesis parameters—Si/Al ratios, pore architectures, surface charge density—to match specific contaminant binding requirements rather than offering universal solutions.
Product Type:
Use-case spectrum spans boiler feedwater softening, pharmaceutical-grade demineralization, selective heavy metal capture, and acid gas scrubbing, with each resin class optimized for pH tolerance and regeneration chemistry.
- Strong Acid Cation:Sulfonic acid functional groups on styrene-divinylbenzene matrices deliver high exchange capacity across pH 0-14. Demand concentrates in German municipal utilities where boiler feedwater standards under DVGW guidelines mandate consistent calcium and magnesium removal.
- Weak Acid Cation:Carboxylic acid functionality achieves high regeneration efficiency with mineral acids rather than strong bases. Food processing facilities in Netherlands and Belgium favor these resins for dealkalization where carbon dioxide removal precedes reverse osmosis polishing.
- Strong Base Anion:Quaternary ammonium sites enable complete anion removal including silica and weak acids. Chemical processing clusters along China's Yangtze River deploy these for ultrapure water production in semiconductor precursor manufacturing.
- Weak Base Anion:Primary, secondary, and tertiary amine groups provide selective acid absorption with lower chemical consumption. Steel mill effluent treatment in India's Odisha and Jharkhand states applies these for hydrochloric acid recovery from pickling lines.
Established volume favors Strong Acid Cation; emerging adoption favors Weak Base Anion.
End Use Industry:
Margin structure varies sharply: pharmaceutical validation requirements command 40-60% price premiums over municipal water contracts, while food-grade certification adds compliance layers that specialized suppliers exploit.
- Water Treatment:Municipal utilities and industrial demineralization plants represent the foundational demand base. EPA discharge limits under the Clean Water Act drive resin consumption at US power generation and manufacturing facilities.
- Pharmaceuticals:USP and EP water quality standards for WFI and sterile manufacturing create specification pull for validated resin systems. Hyderabad and Ahmedabad bulk drug clusters in India are expanding membrane-form ion exchanger procurement as CDSCO tightens alignment with international pharmacopeia.
- Food Processing:Sugar decolorization, beverage clarification, and dairy demineralization require food-grade certifications. EFSA migration limits on leachable organics from polymer-based media elevate inorganic zeolite alternatives in European juice concentration facilities.
- Chemical Processing:Catalysis, acid recovery, and product purification applications demand thermal and chemical stability. BASF's Ludwigshafen complex and LANXESS's Leverkusen operations anchor captive consumption of high-capacity resins for internal process loops.
Pharmaceutical-grade contracts yield highest unit margins; water treatment utilities lock in longest volume commitments.
Form:
Physical configuration determines handling infrastructure, pressure drop characteristics, and integration flexibility with existing vessel geometries.
- Granular:Irregular particle shapes from crushed natural zeolites suit fixed-bed gravity flow systems. Australian and Turkish natural zeolite deposits supply agricultural ammonia recovery and odor control applications.
- Bead:Spherical polymer-gel or macroporous structures optimize packed-bed hydraulics and minimize channeling. Bead-form resins dominate German and Dutch industrial softening installations where automated regeneration skids require predictable pressure-drop behavior.
- Powder:Fine particulate enables direct integration into batch chemical processing and slurry-phase metal recovery. Powder-form materials are climbing fastest, driven by lithium extraction circuits at Chilean and Argentine salares where resin-in-pulp configurations replace conventional solvent extraction.
- Membrane:Thin-film composite or homogeneous ion exchange layers enable continuous electrodialysis and electrodeionization. Taiwan and South Korea semiconductor fabs specify membrane-form exchangers for zero-liquid-discharge compliance in advanced node manufacturing.
Bead form captures largest installed base; powder configuration gains share fastest in battery material supply chains.
Application:
Technical performance requirements range from bulk contaminant removal to selective ion separation at parts-per-billion precision.
- Metal Recovery:Selective binding of copper, nickel, cobalt, and rare earth elements from hydrometallurgical streams. Vale's nickel operations in Brazil and First Quantum's Zambian copper mines deploy mobile ion exchange skids for pregnant leach solution upgrading.
- Wastewater Treatment:Heavy metal removal from industrial effluent prior to discharge. Michigan and North Carolina utilities are pre-positioning hybrid GAC-ion exchange systems ahead of EPA's finalized PFAS discharge limits.
- Ion Separation:Fractionation of chemically similar ions such as lithium/magnesium or cesium/rubidium. Direct lithium extraction ventures in Argentina's Cauchari-Olaroz and Germany's Upper Rhine Valley specify engineered zeolites with tuned selectivity coefficients.
- Desalination:Polishing stage after reverse osmosis or thermal distillation for boron and bromide removal. Middle Eastern desalination complexes in Saudi Arabia and UAE integrate weak base anion resins for final boron reduction below 0.5 mg/L.
Wastewater treatment commands broadest geographic deployment; ion separation applications attract highest R&D intensity for selectivity engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany and Japan absorb premium pricing for validated pharmaceutical-grade systems, while municipal utilities in India and Brazil prioritize procurement cost over performance specifications.
Germany
Industrial water reuse mandates under DVGW guidelines and REACH-aligned purity standards drive specification demand. ECHA's leachable organics restrictions force polymer suppliers toward inorganic alternatives. The Rhine-Ruhr corridor concentrates captive regeneration infrastructure, with LANXESS and BASF SE anchoring service provider leverage.
United States
EPA discharge limits under the Clean Water Act mandate heavy metal removal at power generation and manufacturing facilities. The forthcoming PFAS National Primary Drinking Water Regulation mandates detection below four parts per trillion. Michigan and North Carolina utilities pre-position hybrid GAC-ion exchange systems ahead of finalized rules.
China
MEE enforcement of dual carbon goals tightens water reuse targets at Yangtze River Delta chemical parks. GB standards for ultrapure water production in semiconductor precursor manufacturing drive high-capacity anion resin procurement. Shanghai and Jiangsu province clusters specify extended regeneration cycles for closed-loop demineralization.
India
CDSCO alignment with USP and EP water quality standards for injectable manufacturing creates specification pull. CDSCO's tightening pharmacopeia compliance drives membrane-form ion exchanger procurement. Hyderabad and Ahmedabad bulk drug production clusters expand validated resin system adoption.
Japan
METI guidance on industrial water efficiency and semiconductor manufacturing water intensity drives zero-liquid-discharge compliance demand. JIS standards for high-purity process water elevate membrane-form specifications. Kansai chemical corridor buyers unbundle resin procurement from regeneration services, awarding logistics to specialized satellite providers.
Inorganic Ion Exchange Materials Market Competitive Environment
Capability concentration sits with specialized crystalline material developers; scale advantage sits with diversified chemical conglomerates. The vendor base spans three tiers: integrated chemical majors with captive resin production, focused ion exchange specialists with proprietary synthesis IP, and regional fabricators serving spot replacement demand. Strategic moves center on regeneration service network expansion and selective capacity additions for pharmaceutical-grade certification.
Among diversified chemical conglomerates, Honeywell International Inc., Mitsubishi Chemical Corporation, and BASF SE occupy positions where manufacturing scale intersects with process industry relationships. These entities exemplify archetypes that anchor supply security for municipal and industrial demineralization contracts through backward integration into raw material streams and captive regeneration infrastructure.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Mitsubishi Chemical Corporation |
| LANXESS |
| Tosoh Corporation |
| Merck KGaA |
| Repligen Corporation |
| Calgon Carbon Corporation |
| BASF SE |
| DuPont de Nemours, Inc. |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate feedstock volatility determines both margin compression patterns and supplier consolidation trajectories across synthetic zeolite manufacturing. ECHA REACH compliance costs and China's dual carbon enforcement create divergent pricing tier spreads between pharmaceutical-grade membrane systems and bulk municipal resins.
Pricing Analysis
Aftermarket regeneration service contracts drive lifetime value capture more than initial resin sales. Three-tier pricing structure across pharmaceutical-validated, industrial-certified, and economy bulk grades reflects USP/EP certification premiums versus DVGW-aligned municipal specifications. Cost compression in economy cation resins intensifies because Chinese manufacturers are scaling high-capacity anion production for Yangtze River Delta chemical parks. Municipal utilities in India and Brazil exhibit highest price sensitivity; semiconductor fabs in Taiwan and South Korea accept premium membrane-form pricing for zero-liquid-discharge compliance.
Supply Chain Analysis
Extended payment terms from German chemical conglomerates strain smaller crystalline material specialists competing for Rhine-Ruhr regeneration contracts. Manufacturing concentrates in Germany, China, and Japan, with lithium carbonate from Chile and Australia, sodium aluminate from US bauxite refining, and specialized reactor vessels from South Korean fabricators. Single-source vulnerability sits with Chilean lithium concentrate supply following 2022-2024 export disruptions. Distribution runs through captive regeneration facilities anchored by LANXESS across the Rhine-Ruhr corridor and satellite logistics providers in Japan's Kansai chemical corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated water treatment utilities unbundling resin procurement from regeneration services, fragmenting long-term chemical supply contracts that previously locked in volume commitments.
For Market Incumbents: Insulate margin position by deepening captive regeneration infrastructure in Germany's Rhine-Ruhr corridor and securing pharmaceutical-grade certification investments ahead of CDSCO's USP/EP alignment enforcement. Membrane bioreactor substitution in Scandinavian municipal wastewater markets and lithium hydroxide feedstock volatility represent dual threats requiring backward integration into sodium aluminate supply streams. For New Entrants and Emerging Players: Mobile ion exchange skids for Brazil's mining tailings recovery at ANVISA/IBAMA-enforced iron ore and lithium extraction sites represent the most penetrable entry point. India's pharmaceutical water systems in Hyderabad and Ahmedabad bulk drug clusters offer secondary white-space as CDSCO tightens pharmacopeia compliance. Partner with specialized logistics providers for distributed satellite regeneration rather than competing against centralized OEM service depots. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors crystalline material developers with proprietary hydrothermal synthesis IP over diversified chemical conglomerates dependent on commodity resin volumes. Acquisition targets should demonstrate controlled Si/Al ratio engineering capability and existing pharmaceutical-grade validation. Watch ECHA's PFAS harmonization timeline under the Drinking Water Directive as the signal for hybrid ion exchange-adsorption specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Regeneration Network Expansion | LANXESS and BASF SE anchor service provider leverage across Germany's Rhine-Ruhr industrial corridor. |
| Pharmaceutical-Grade Certification Investment | CDSCO's USP/EP alignment for Indian injectable manufacturing creates specification pull for validated membrane systems. |
| Layered Double Hydroxide Nanocomposite Development | Swiss and German pharmaceutical manufacturers pilot tunable interlayer anion selectivity for fluoride removal. |
| Electrochemical Regeneration Convergence | Taiwan and South Korea semiconductor fabs pair resin beds with electrodeionization for zero-liquid-discharge compliance. |
| Mobile Skid Deployment for Mining Tailings | ANVISA and IBAMA joint enforcement in Brazil generates demand for acid mine drainage treatment before Amazon tributary discharge. |
Study Parameters
A standing panel of plant managers at German chemical parks, procurement leads at Indian pharmaceutical bulk drug facilities, distribution channel partners in Japan's Kansai corridor, and technical R&D directors at synthetic zeolite manufacturers provided ongoing calibration. Primary fieldwork combined with secondary validation from ECHA REACH registration databases, EPA Clean Water Act discharge filings, MEE dual carbon enforcement notices, CDSCO pharmacopeia alignment circulars, and customs/trade data for lithium carbonate and sodium aluminate flows. Bottom-up resin volume modeling and top-down water treatment capex triangulation anchored value estimates.
Scenario-bracketing around regulatory enforcement intensity and feedstock disruption probability shaped projections across the analysis window. Segmentation dimensions spanned product type, end-use industry, physical form, and application chemistry, with regional regulatory clusters as an overlay. CAGRs derived from installed base turnover rates, replacement cycle compression from predictive regeneration algorithms, and specification upgrade trajectories in pharmaceutical and semiconductor water systems. Lithium extraction resin-in-pulp adoption and PFAS hybrid treatment train pilot deployments served as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing, Rhine-Ruhr energy costs, or Chinese chemical park water reuse enforcement would shift the trajectory. Forecasts reflect documented assumptions about ECHA PFAS harmonization timing, CDSCO validation acceleration, and MEE dual carbon goal implementation pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
PTFE Membrane Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Bitumen Membrane Sheets Market