
 Global Microfiltration Membranes Market | 2026-2036
Global Microfiltration Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microfiltration Membranes Market Foresight
Germany's membrane manufacturing corridor is narrowing the gap between laboratory-grade and industrial-scale production capacity. Merck KGaA leverages its integrated polymer synthesis capabilities to supply high-purity membranes for pharmaceutical sterile filtration. Sartorius AG anchors its position through intensive R&D spending on single-use filtration systems for bioprocessing. Pall Corporation differentiates via proprietary pleating technologies that extend filter lifetime in high-solids water treatment applications.
Microfiltration membranes are porous barriers, typically 0.1 to 10 micrometers in pore size, fabricated from polymeric materials such as polyvinylidene fluoride or polypropylene through phase inversion or track-etching processes, designed to remove suspended particles, bacteria, and colloids from liquid streams. Polyvinylidene fluoride dominates material selection due to its chemical resistance and mechanical durability in aggressive process environments, while cellulose acetate retains share in cost-sensitive laboratory applications. Water treatment represents the most mature application segment with established specification standards, whereas biotechnology applications command premium pricing through validated sterile filtration protocols.
EPA regulations under the Safe Drinking Water Act and the EU Drinking Water Directive collectively mandate pathogen removal thresholds that only membrane systems consistently achieve, forcing municipal utilities to upgrade conventional treatment trains. China's Ministry of Ecology and Environment enforces increasingly stringent industrial wastewater discharge limits that require microfiltration as pretreatment for reverse osmosis systems. Stakeholders must monitor how evolving pharmaceutical manufacturing standards from FDA and EMA reshape validation requirements for single-use filtration assemblies.
Market Dynamics
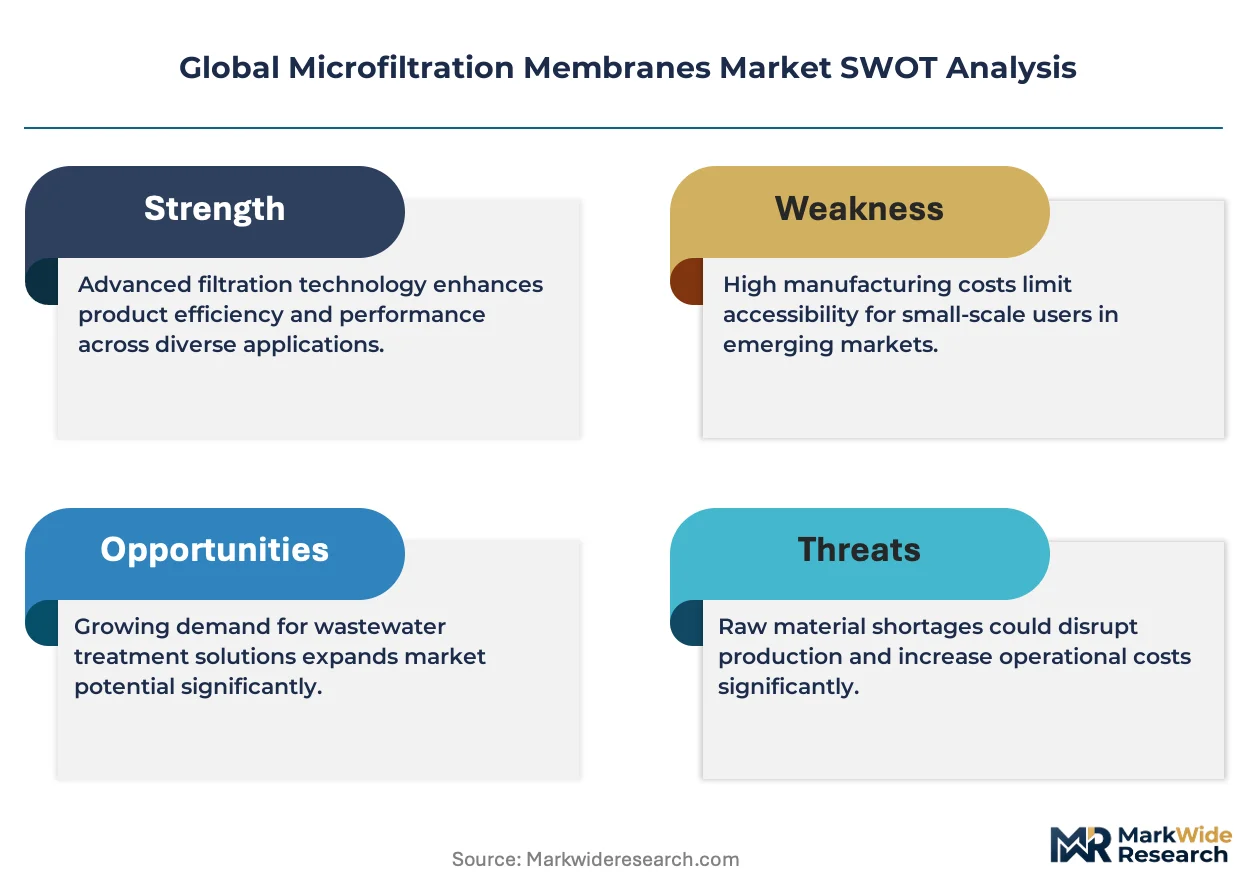
Stringent pathogen removal mandates from EPA and EU Drinking Water Directive revisions are forcing municipal utilities to replace conventional sand filtration with membrane trains, compressing upgrade cycles and reshaping supplier-procurement relationships.
Growth Catalysts
- EU Drinking Water Directive revision:The updated directive mandates tighter microbiological limits that conventional coagulation-sedimentation cannot achieve, accelerating membrane retrofit programs across German, French, and Italian municipal systems.
- Industrial cluster concentration:China's Yangtze River Delta petrochemical corridor is deploying microfiltration as mandatory pretreatment for zero-liquid-discharge reverse osmosis systems under MEE discharge rules.
- Single-use bioprocessing:Cell therapy manufacturing is shifting from stainless-steel reusable trains to disposable membrane assemblies, validating sterile filtration protocols for commercial-scale gene therapy production.
Market Restraints
- PVDF resin supply concentration:Polyvinylidene fluoride precursor production clusters in China's Shandong and Zhejiang provinces, exposing membrane fabricators to feedstock volatility and geopolitical logistics friction.
- Energy intensity of operation:Cross-flow microfiltration systems require sustained pumping energy that municipal utilities in Germany and Japan struggle to justify against gravity-fed sand filter alternatives.
- Ultrafiltration substitution:Tighter pore-size membranes are capturing applications historically served by microfiltration, particularly in pharmaceutical protein concentration steps.
Strategic Opportunities
- India's Ganga rejuvenation program:The Namami Gange initiative is funding membrane-based sewage treatment plants across Uttar Pradesh and Bihar, opening procurement channels for international module suppliers.
- Cellulose acetate cost positioning:Laboratory-scale applications in academic research settings retain preference for cellulose-based membranes, creating a defensible niche against fluoropolymer dominance.
- Digital twin integration:IoT-enabled membrane performance monitoring is virtualizing predictive maintenance contracts, allowing suppliers to capture recurring revenue from water treatment operators.
Industry Challenges
- Validation timeline compression:FDA and EMA are tightening change-control requirements for single-use assemblies, extending qualification periods for new membrane formats in commercial biologics manufacturing.
- Skilled commissioning shortage:Specialized technicians for membrane train startup and optimization remain scarce in Brazil's expanding industrial water reuse sector, delaying project handovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microfiltration Membranes Market |
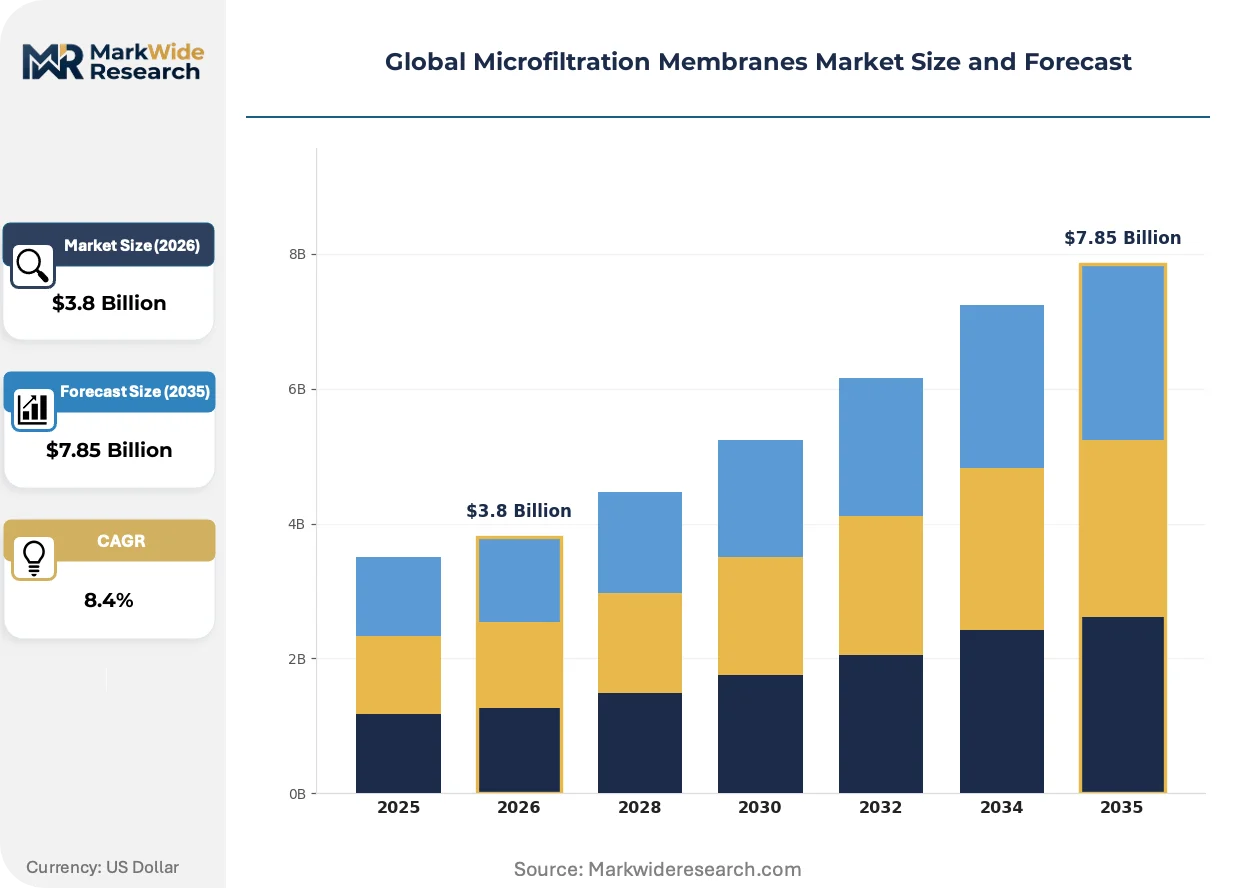
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polytetrafluoroethylene, Polyvinylidene Fluoride, Cellulose Acetate Application: Water Treatment, Food & Beverage Processing, Pharmaceutical Filtration, Biotechnology End User: Municipal Utilities, Chemical Manufacturers, Laboratories, Beverage Producers Installation: Inline, Crossflow, Dead-End, Tangential Flow |
| Companies Covered | Merck KGaA, Sartorius AG, Pall Corporation, 3M Company, TORAY INDUSTRIES, INC., Alfa Laval, Koch Membrane Systems, Pentair, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microfiltration Membranes Market Shifts & Advancements
Membrane manufacturing is converging with advanced polymer synthesis and digital process control, enabling precision-tuned pore structures that match application-specific separation requirements without over-engineering.
Track-etched polycarbonate membranes are virtualizing quality control protocols in pharmaceutical sterile filtration. Merck KGaA and Sartorius AG have integrated laser-based pore verification into continuous production lines. Biologics manufacturers are adopting these formats for mycoplasma retention validation, collapsing the gap between laboratory analytical methods and production-scale assurance.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluoropolymer alternatives research across European membrane fabricators. The ECHA proposal to classify PVDF as a substance of very high concern is forcing suppliers to document polymer degradation pathways. German industrial wastewater operators are piloting ceramic microfiltration modules to preempt regulatory exposure.
Consolidated procurement by multinational water utilities is compressing supplier margins and favoring framework agreements over spot purchasing. Suez and Veolia are centralizing membrane sourcing across their European and Latin American operating companies. Chinese engineering procurement construction firms are demanding ten-year total-cost-of-ownership guarantees, shifting risk from operators to membrane suppliers.
Global Microfiltration Membranes Market Segmentation
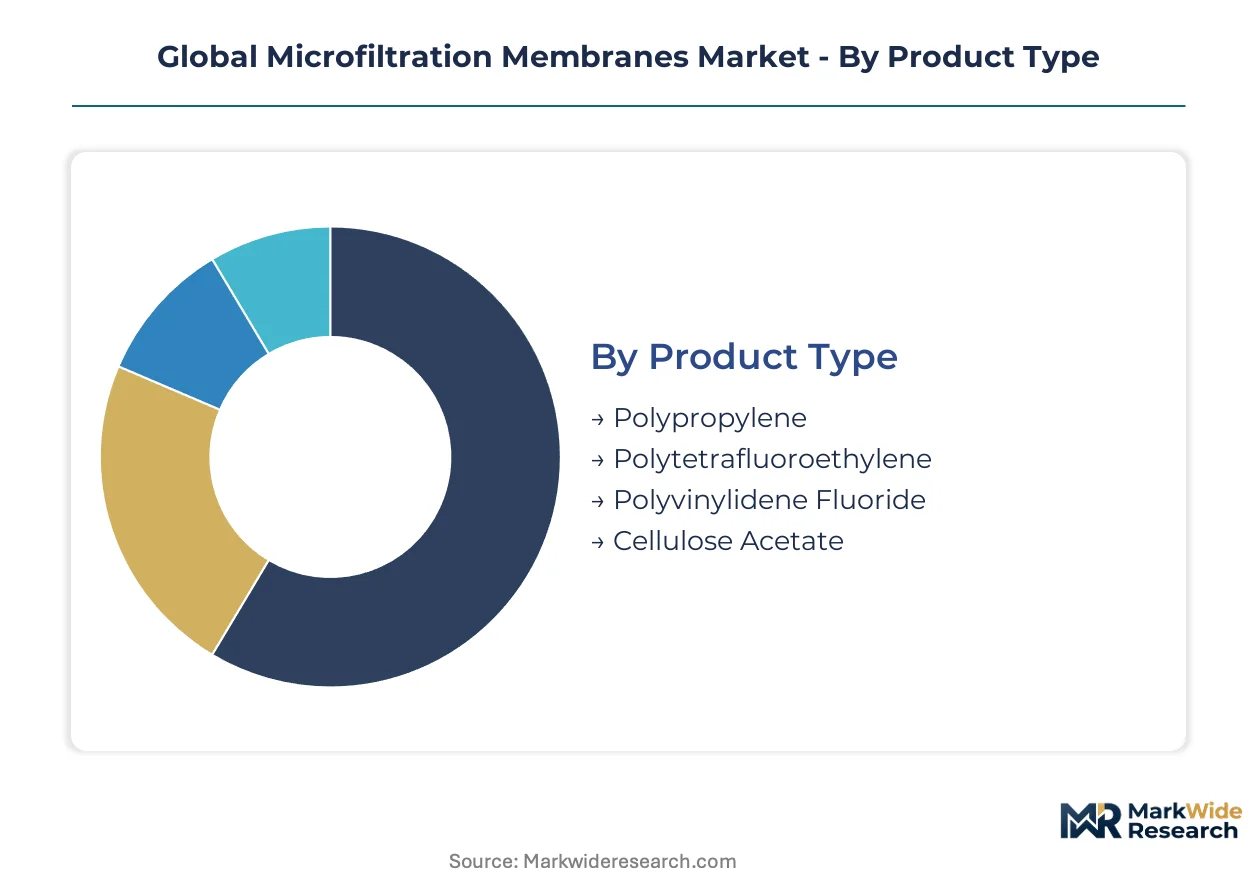
Microfiltration membrane demand fragments across material chemistry, process configuration, and end-use validation requirements. Suppliers must align product portfolios with divergent technical specifications and procurement cycles across water utilities, pharmaceutical manufacturers, and research institutions.
Product Type:
Material selection spans fluoropolymer dominance to cost-engineered cellulosics, each occupying distinct positions in the performance-cost spectrum.
- Polyvinylidene Fluoride:Engineered through phase inversion or track-etching, PVDF delivers chemical resistance against chlorine and aggressive cleaning protocols. Municipal utilities in Germany's Rhine-Ruhr industrial cluster specify PVDF for high-solids wastewater pretreatment under tightening MEE-aligned discharge standards.
- Polypropylene:Thermally induced phase separation yields isotropic pore structures optimized for depth filtration applications. Beverage producers in China's Yangtze River Delta favor polypropylene for cost-sensitive bottled water clarification where thermal stability requirements are moderate.
- Polytetrafluoroethylene:Expanded PTFE membranes achieve hydrophobic barrier properties through biaxial stretching processes, serving specialized venting and gas filtration roles in pharmaceutical lyophilization equipment.
- Cellulose Acetate:Laboratory-scale academic research retains preference for this hydrophilic, biocompatible format despite limited chemical tolerance, particularly in protein binding studies where fluoropolymer adsorption interferes with analytical integrity.
The dominant share belongs to Polyvinylidene Fluoride, while Polypropylene is closing the gap fastest.
Application:
End-use maturity ranges from standardized municipal specifications to validated bioprocessing protocols commanding premium pricing tiers.
- Water Treatment:Surface water and tertiary wastewater applications deploy microfiltration as barrier technology against Giardia and Cryptosporidium, with EPA Long Term 2 Enhanced Surface Water Treatment Rule mandating 4-log virus removal credits that only membrane systems consistently achieve.
- Biotechnology:Single-use sterile filtration for cell therapy manufacturing requires validated bacterial retention and endotoxin control, with FDA process validation guidelines driving adoption of disposable membrane assemblies over reusable stainless-steel trains.
- Pharmaceutical Filtration:Parenteral drug manufacturing employs microfiltration as final sterile barrier, with EMA Annex 1 revision tightening requirements for filter integrity testing and redundant filtration architectures.
- Food & Beverage Processing:Wine and beer clarification applications leverage cross-flow microfiltration to replace diatomaceous earth filtration, though sensory validation requirements slow substitution rates in traditional European brewing regions.
Water Treatment commands the largest installed base, though Biotechnology is expanding most quickly as gene therapy manufacturing scales.
End User:
Procurement sophistication varies from consolidated utility frameworks to fragmented laboratory spot purchasing.
- Municipal Utilities:Suez and Veolia centralize membrane sourcing across European and Latin American operating companies, compressing supplier margins through multi-year framework agreements with total-cost-of-ownership guarantees.
- Chemical Manufacturers:China's petrochemical corridor around Shanghai and Ningbo deploys microfiltration as mandatory pretreatment for zero-liquid-discharge reverse osmosis systems under Ministry of Ecology and Environment enforcement.
- Beverage Producers:Multinational bottled water brands specify membrane performance through centralized technical standards, though regional bottlers retain procurement autonomy in emerging markets.
- Laboratories:Academic and contract research organizations purchase through distributor channels with minimal volume commitment, favoring cellulose acetate for cost-sensitive filtration tasks.
Municipal Utilities anchor procurement volume, while Chemical Manufacturers are gaining share fastest on industrial wastewater retrofit cycles.
Installation:
Flow configuration determines energy intensity, fouling management, and module replacement economics.
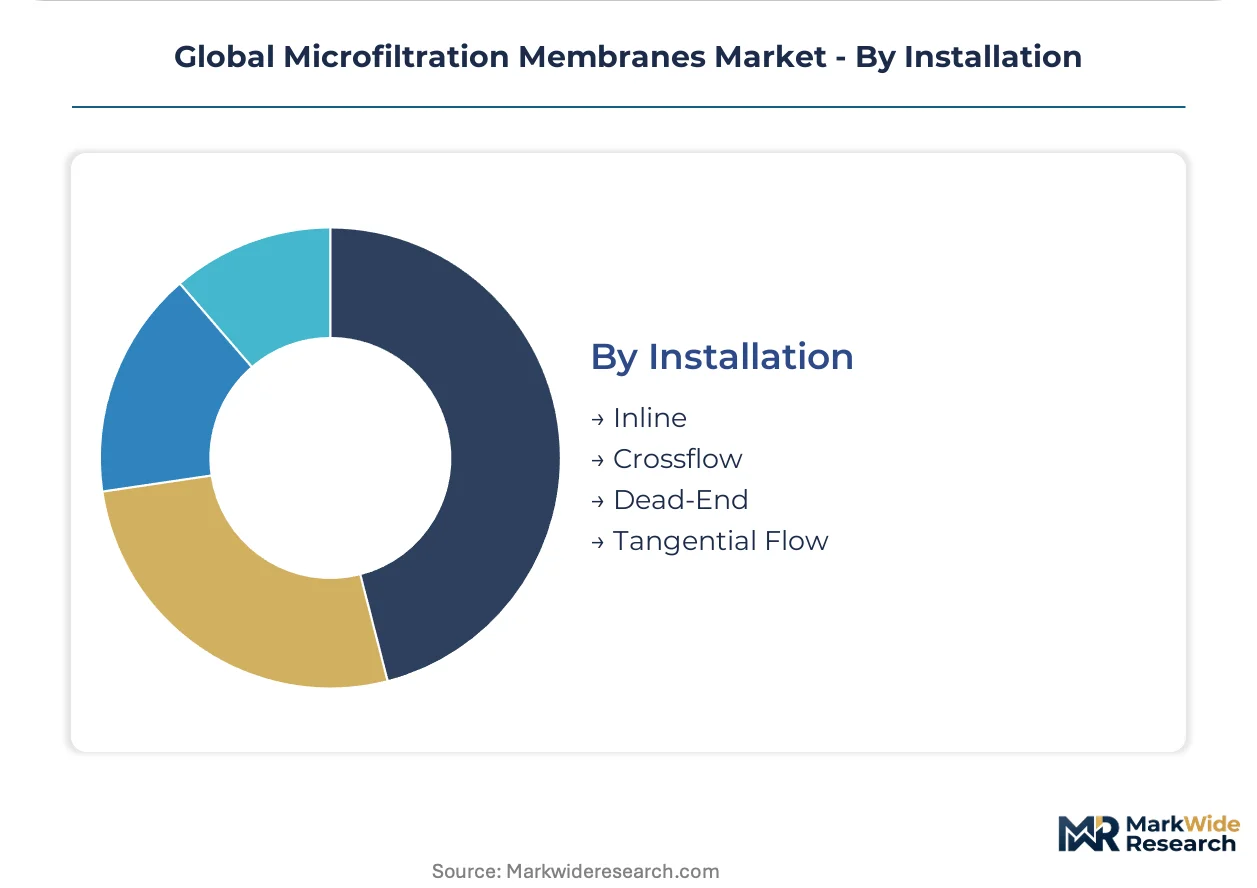
- Crossflow:Tangential velocity across the membrane surface limits cake layer accumulation, enabling sustained flux in high-solids industrial wastewater applications where German operators struggle to justify pumping energy against gravity-fed alternatives.
- Dead-End:Direct-perpendicular flow maximizes recovery in low-solids potable water treatment, with module replacement scheduled on pressure differential triggers rather than cleaning-in-place protocols.
- Tangential Flow:Bioprocessing applications employ this variant for protein concentration and diafiltration, with single-use cassette formats eliminating cleaning validation burdens in multi-product facilities.
- Inline:Compact cartridge installations serve point-of-use filtration in beverage bottling lines and pharmaceutical filling operations where space constraints override flux optimization.
Crossflow retains the dominant installed capacity, while Tangential Flow is climbing the fastest on single-use bioprocessing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PVDF precursor production clusters in China's Shandong and Zhejiang provinces, exposing membrane fabricators to feedstock volatility. Municipal utilities across Germany, China, the United States, Japan, and India are retrofitting conventional filtration trains under tightening pathogen removal mandates.
Germany
The Rhine-Ruhr industrial corridor drives demand for high-solids wastewater pretreatment membranes. ECHA's proposal to classify PVDF as a substance of very high concern is forcing operators to pilot ceramic alternatives. Merck KGaA and Sartorius AG anchor manufacturing capacity in the Darmstadt-Göttingen corridor.
China
MEE discharge rules mandate microfiltration pretreatment for zero-liquid-discharge reverse osmosis systems. The Yangtze River Delta petrochemical corridor around Shanghai and Ningbo deploys membrane trains at scale. Domestic fabricators source PVDF resin from captive Shandong and Zhejiang production bases.
United States
EPA Long Term 2 Enhanced Surface Water Treatment Rule mandates 4-log virus removal credits achievable only through membrane barriers. Municipal utilities in the Ohio River Valley and Great Lakes states compress upgrade cycles. Pall Corporation supplies pleated formats for high-solids applications.
Japan
METI efficiency standards strain cross-flow system economics against gravity-fed alternatives. Osaka-Kobe industrial wastewater operators balance fouling management with pumping energy constraints. Asahi Kasei Corporation represents domestic fluoropolymer membrane fabrication.
India
The Namami Gange initiative funds membrane-based sewage treatment plants across Uttar Pradesh and Bihar. Central Pollution Control Board enforcement tightens industrial discharge limits for tannery clusters. International module suppliers penetrate procurement channels for state-level water utilities.
Global Microfiltration Membranes Market Competitive Landscape
Integrated chemical conglomerates and specialized filtration fabricators split the market between captive polymer supply and application-specific engineering. Tiering concentrates in the premium validated-biopharma segment and the cost-optimized municipal water tier. German and Japanese conglomerates anchor the integrated-materials archetype, while mid-cap specialists occupy single-use bioprocessing niches. Competitive moves center on backward integration into polymer synthesis and long-term framework contracting with consolidated water utilities.
Within the integrated-materials tier, Merck KGaA and Sartorius AG exemplify European conglomerates leveraging in-house polymer capabilities to supply high-purity formats. Pall Corporation occupies a distinct position among North American fabricators with proprietary pleating expertise. These three anchors represent divergent strategic postures: chemical synthesis integration, intensive R&D positioning, and process-engineering differentiation.
| Leading Market Players |
|---|
| Merck KGaA |
| Sartorius AG |
| Pall Corporation |
| 3M Company |
| TORAY INDUSTRIES, INC. |
| Alfa Laval |
| Koch Membrane Systems |
| Pentair |
| Asahi Kasei Corporation |
| Others |
Supply & Pricing Matrix
PVDF resin supply concentration in China's Shandong and Zhejiang provinces compresses both pricing tier spreads and supply chain configuration, forcing membrane fabricators to absorb feedstock volatility or pass costs through to municipal utilities locked into long-term framework agreements.
Pricing Analysis
EU Drinking Water Directive revision dictates the pricing tier structure across the membrane market. Three-tier pricing separates validated biopharma formats from industrial wastewater grades and cost-optimized laboratory supplies. Price differentiation rests on FDA/EMA certification tiers and volume scale commitments from consolidated water utilities. Cost compression in municipal segments intensifies because Suez and Veolia centralize procurement across operating companies. Chemical manufacturers in China's Yangtze River Delta exhibit least price sensitivity due to zero-liquid-discharge compliance mandates.
Supply Chain Analysis
Contract manufacturing capacity for track-etched polycarbonate membranes concentrates with Merck KGaA and Sartorius AG in Germany's Darmstadt-Göttingen corridor. PVDF precursor production draws from captive Chinese bases, while polypropylene membrane fabrication sources from South Korean and Japanese polymer specialists. Single-source vulnerability runs through Shandong province resin supply exposed to MEE enforcement disruptions. Distribution runs through direct sales teams for municipal utilities and distributor channels for fragmented laboratory end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing scale-up represents a high-growth disruption, with FDA process validation guidelines forcing stainless-to-disposable conversion across cell therapy production lines.
For Market Incumbents: Insulate polymer supply positions through backward integration into PVDF precursor production or long-term offtake agreements with Shandong-based resin suppliers. ECHA's substance-of-very-high-concern proposal for PVDF threatens regulatory exposure that ceramic membrane alternatives could exploit. Capacity addition in ceramic microfiltration modules for German industrial wastewater operators neutralizes this substitution risk. For New Entrants and Emerging Players: Pursue India's Namami Gange procurement channels for membrane-based sewage treatment plants across Uttar Pradesh and Bihar. Academic research laboratories in Western Europe retain preference for cellulose acetate formats, creating a defensible niche against fluoropolymer incumbents. Direct technical sales engagement with state-level water utilities bypasses consolidated Suez-Veolia procurement barriers. For Investors and Strategic Acquirers: Single-use bioprocessing specialists with validated sterile filtration protocols command premium positioning as gene therapy manufacturing scales. Long-term viability over a multi-year horizon hinges on FDA and EMA change-control compliance capabilities rather than commodity membrane production. Quarterly review of MEE discharge enforcement intensity and ECHA PVDF classification timelines is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVDF Precursor Supply | Captive resin production in Shandong province neutralizes feedstock volatility for membrane fabricators. |
| Ceramic Microfiltration Module Development | German industrial wastewater operators pilot non-fluoropolymer formats to preempt ECHA regulatory exposure. |
| IoT-Enabled Predictive Maintenance Contracts | Digital twin integration allows suppliers to capture recurring revenue from water treatment operators. |
| Single-Use Bioprocessing Assembly Validation | FDA process validation guidelines drive adoption of disposable membrane trains over stainless-steel systems. |
| Long-Term Framework Agreements with Utilities | Suez and Veolia centralize membrane sourcing across European and Latin American operating companies. |
Research Methodology
Cross-validation between primary interviews with membrane plant managers, municipal utility procurement leads, pharmaceutical regulatory affairs directors, and bioprocessing engineers anchors the qualitative findings. Secondary validation draws from EPA Safe Drinking Water Act filings, EMA Annex 1 revision drafts, MEE discharge enforcement records, and customs data tracking PVDF resin trade flows. Bottom-up and top-down triangulation reconciles module shipment volumes with utility capex disclosures.
Calibration against historical upgrade cycles across Germany's Rhine-Ruhr corridor and China's Yangtze River Delta petrochemical cluster informs the analytical framework across the analysis window. Segmentation dimensions span material chemistry, process configuration, application maturity, and end-user procurement sophistication. CAGRs derive from installed base replacement rates and greenfield project pipelines. Forecast inputs incorporate ECHA regulatory timeline probabilities and MEE enforcement intensity indices.
Sensitivities concentrate around ECHA PVDF classification outcomes, MEE discharge limit revisions, and FDA single-use validation guideline updates. Forecasts reflect assumptions on regulatory implementation timelines and technology substitution elasticities. Quarterly review of ECHA substance evaluation progress and MEE regional enforcement audits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Nafion Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Global Vapor Permeability Films Market