
 Vapor Barrier Films Market | 2026-2036
Vapor Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Barrier Films Market Analytics
Buyer concentration among large-scale commercial builders and national construction aggregators is restructuring procurement patterns for vapor barrier films. DuPont de Nemours, Inc. leverages its Tyvek brand heritage and building science expertise to sustain specification pull with architectural firms. Berry Global Inc. anchors North American supply through extrusion scale and distributor relationships. BASF SE competes on polymer chemistry leadership, supplying engineered resins that improve moisture vapor transmission rate performance.
Vapor barrier films are engineered polymer membranes or composite sheets designed to impede moisture vapor diffusion, typically specified by water vapor transmission rate below one perm and manufactured through blown film extrusion, cast film, or multilayer lamination processes. Their primary purpose is to prevent condensation damage within wall assemblies, protect sensitive electronics from humidity, and extend packaged food shelf life by blocking moisture ingress. Polyethylene formulations dominate construction applications due to cost position and ease of installation, while PVDC and multilayer nylon structures command premium positions in food packaging where oxygen and moisture barrier performance determines margin pools. Flexible membrane formats lead volume across building wraps and agricultural greenhouse covers, whereas rigid sheet and composite materials capture higher unit economics in electronics cleanroom and semiconductor shipping applications.
EPA Energy Star and ICC building codes in the United States mandate continuous air and moisture barriers, directly expanding addressable demand for compliant film specifications. REACH restrictions on phthalate plasticizers and EU Green Deal carbon accounting rules are forcing reformulation of conventional polyethylene and polypropylene barriers toward bio-based or recycled content alternatives. ECHA substance evaluations further tighten acceptable chemistries for construction-grade membranes sold across European member states. Stakeholders must monitor evolving code harmonization between ASHRAE standards and state-level stretch codes to anticipate specification shifts before they compress incumbent product lines.
Market Dynamics
Building code harmonization across ASHRAE standards and state-level stretch codes is compressing specification cycles for incumbent polyethylene formulations while accelerating qualification of high-performance alternatives.
Growth Catalysts
- Retrofit incentive programs:The US Inflation Reduction Act directs capital toward deep energy retrofits, shortening membrane replacement intervals in existing building stock.
- REACH substance restrictions:ECHA evaluations on phthalate plasticizers force reformulation toward compliant chemistries, creating specification windows for qualified suppliers.
- Semiconductor cleanroom demand:Advanced packaging facilities in Taiwan and South Korea specify ultra-low MVTR rigid composites for wafer shipping containers.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs track naphtha and natural gas liquids, compressing margin stability for commodity-grade film converters.
- Regional supply concentration:Blown film extrusion capacity clusters in the US Gulf Coast and German chemical corridors, exposing buyers to weather-related disruption.
- Permeability-performance tradeoff:Bio-based alternatives struggle to achieve sub-one-perm ratings without multilayer lamination that raises unit costs.
Strategic Opportunities
- Indian building code modernization:Bureau of Indian Standards updates to envelope performance standards create first-mover positioning for compliant membrane suppliers.
- Agricultural controlled-environment expansion:Greenhouse film demand in Spain and the Netherlands shifts toward diffused-light vapor barriers with integrated thermal properties.
- Digital specification platforms:Building information modeling integration allows manufacturers to embed performance data directly into architectural design workflows.
Industry Challenges
- Multilayer coextrusion expertise:Seven-layer and nine-layer barrier film production requires process engineers with rare polymer rheology specializations.
- Extended certification timelines:NFPA 285 fire propagation testing for wall assemblies adds 12-18 months to new product commercialization.
- Legacy inventory reconciliation:Distributors face SKU complexity managing pre-REACH and post-reformulation product lines simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Barrier Films Market |
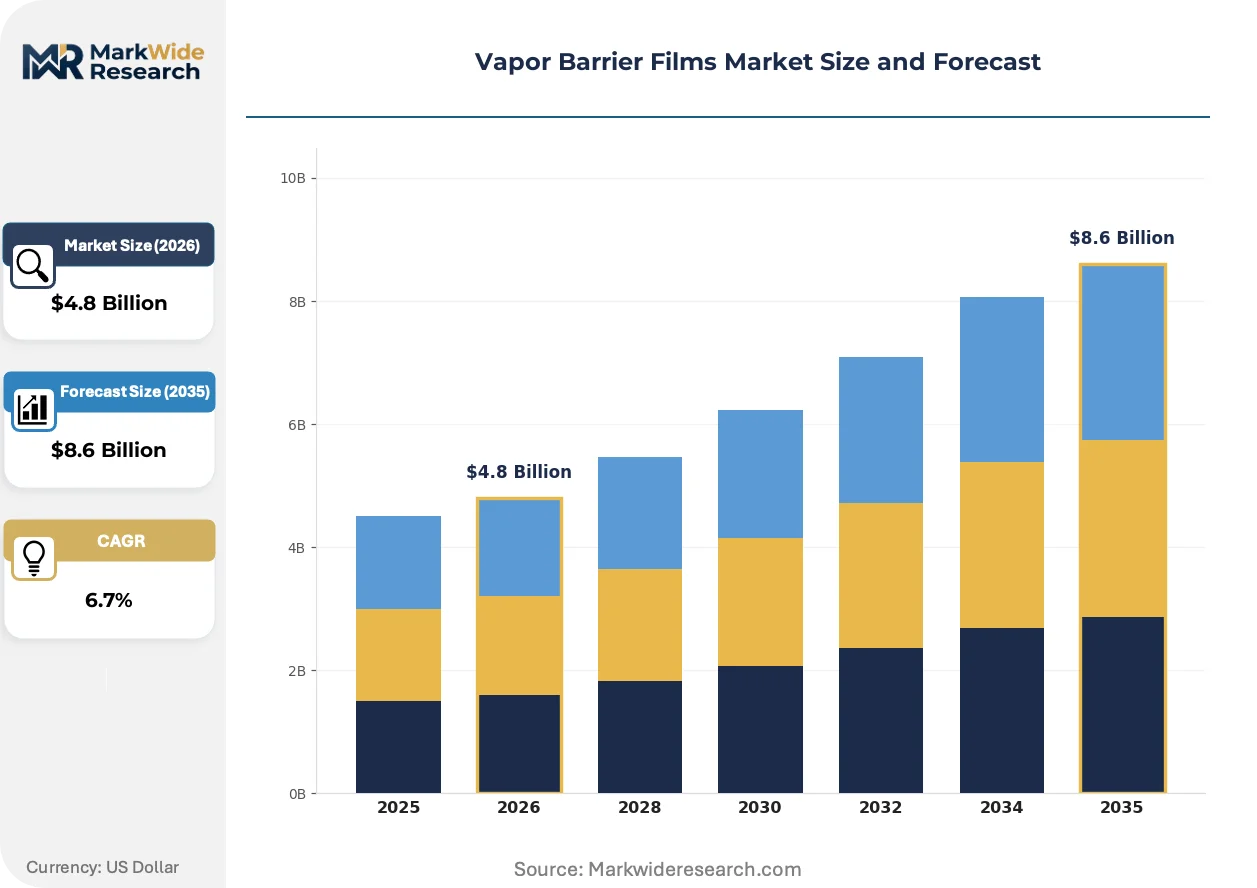
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVDC, Nylon Application: Construction, Food Packaging, Electronics, Agriculture Material: Flexible Membrane, Rigid Sheet, Composite, Coating End User: Builders, Food Manufacturers, Electronics OEMs, Agriculture Producers |
| Companies Covered | DuPont de Nemours, Inc., BASF SE, Berry Global Inc., Amcor Plc, 3M Company, Cosmo Films Ltd., Carlisle Companies Incorporated, Polyguard Products, Inc., Raven Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Barrier Films Market Evolving Landscape
Active barrier technologies and digital manufacturing controls are displacing static film specifications across construction and packaging end-uses. Material science advances now enable tunable moisture transmission rather than fixed permeability ratings.
Multilayer coextrusion with nanoclay interlayers is automating quality consistency in high-barrier agricultural films. European greenhouse operators in the Netherlands and Belgium adopt these structures for 4-5 season crop cycles. The technology is automating defect detection through inline spectroscopy, reducing field failure rates.
EU Green Deal carbon accounting rules now mandate embodied carbon disclosure for construction membranes sold across member states. Manufacturers must document cradle-to-gate emissions or face de-listing from public procurement frameworks. German and French building aggregators have accelerated supplier qualification to meet 2027 reporting deadlines.
Specification authority is migrating from general contractors to national construction aggregators with centralized procurement platforms. These buyers unbundle material selection from installation, forcing film suppliers to demonstrate standalone performance data. The United States exhibits this pattern most visibly, where top-ten homebuilders now control membrane selection for franchise operations.
Vapor Barrier Films Market Segmentation
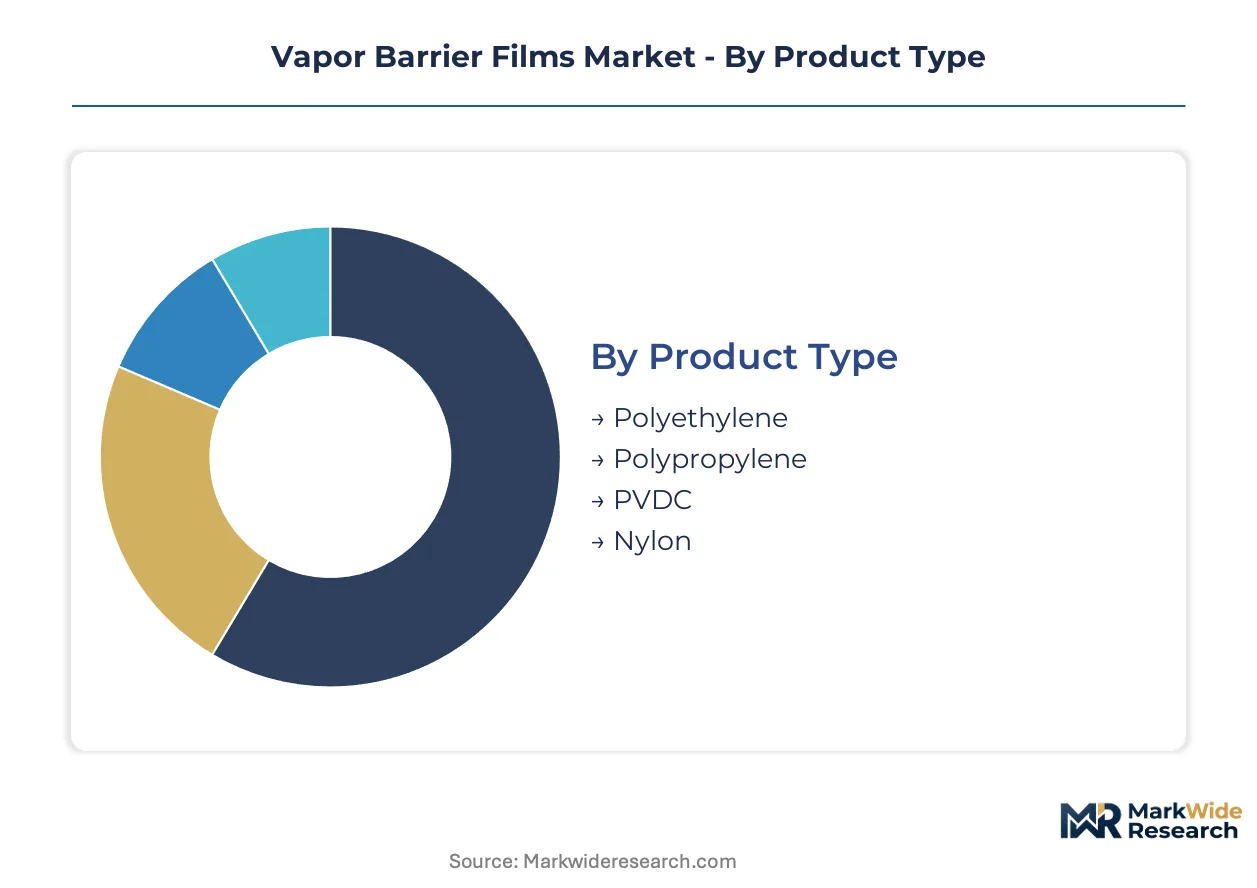
Vapor barrier film specifications diverge sharply across end-use environments, from sub-one-perm construction membranes to ultra-low MVTR electronics shipping materials. Procurement decisions hinge on permeability ratings, fire code compliance, and installation labor economics rather than resin cost alone.
Product Type:
Resin selection determines permeability floor, thermal stability, and compatibility with multilayer lamination processes.
- Polyethylene:Blown film extrusion of LDPE and LLDPE formulations delivers sub-one-perm ratings at commodity cost positions. Demand concentrates among US residential builders retrofitting existing stock under Inflation Reduction Act incentives, though REACH phthalate restrictions are forcing reformulation cycles.
- PVDC:Vinylidene chloride copolymers achieve the lowest moisture vapor transmission rates available in flexible formats. Electronics OEMs in Taiwan and South Korea specify PVDC interlayers for wafer shipping containers where humidity protection determines yield economics.
- Polypropylene:Cast film PP offers higher temperature resistance than polyethylene for agricultural greenhouse applications. BOPP structures dominate diffused-light thermal films in Spain and the Netherlands.
- Nylon:Multilayer coextrusions with nylon 6 or nylon 66 provide puncture resistance and oxygen barrier synergy. Food manufacturers specify these for modified atmosphere packaging of moisture-sensitive products.
Volume sits with polyethylene; growth tilts toward PVDC.
Application:
End-use environments dictate performance thresholds, certification requirements, and replacement cycle frequency.
- Construction:Building wraps, under-slab membranes, and cavity barriers must satisfy ICC and ASHRAE code harmonization. US homebuilders centralizing procurement through national aggregators are compressing specification windows for compliant products.
- Electronics:Cleanroom environments and semiconductor shipping containers demand rigid composites with MVTR below 0.1 perm. Advanced packaging facility construction in Taiwan accelerates qualification of ultra-high-barrier specifications.
- Food Packaging:Extended shelf life requirements drive multilayer structures with integrated oxygen and moisture barriers. EFSA compliance for food contact layers adds formulation complexity.
- Agriculture:Controlled-environment greenhouse films require thermal retention plus vapor barrier performance. Dutch and Belgian operators are adopting nanoclay interlayer technologies for 4-5 season durability.
Construction commands installed volume; electronics posts the steepest expansion trajectory.
Material:
Format selection balances permeability performance against handling economics and field installation constraints.
- Flexible Membrane:Roll-format films dominate building envelope and agricultural applications where labor crews prioritize rapid deployment. US Gulf Coast extrusion clusters supply commodity polyethylene membranes at scale.
- Rigid Sheet:Thermoformed or compression-molded formats capture wafer shipping trays and electronics cleanroom panels. Composite rigid structures achieve the lowest MVTR ratings through embedded barrier layers.
- Composite:Multilayer laminates combining polymer films with aluminum foil or metallized substrates serve premium packaging and military specifications. Coextrusion expertise scarcity limits qualified supplier pools.
- Coating:Liquid-applied vapor barriers penetrate retrofit markets where sheet membrane access is constrained. Spray polyurethane and bituminous coatings compete on complex geometry coverage.
Flexible membrane formats lead volume; composite materials gain share fastest in premium segments.
End User:
Procurement authority is migrating toward centralized platforms that unbundle material specification from installation labor.
- Builders:National construction aggregators and top-ten US homebuilders now control membrane selection for franchise operations. Digital specification platforms embedding performance data into BIM workflows are restructuring supplier access.
- Food Manufacturers:Packaging engineers specify barrier structures based on shelf life targets and distribution climate exposure. Modified atmosphere packaging lines require film compatibility with heat-sealing equipment.
- Electronics OEMs:Semiconductor fabricators and advanced packaging facilities mandate cleanroom-grade materials with documented particulate and outgassing performance. Wafer shipping container specifications are tightening as node sizes shrink.
- Agriculture Producers:Greenhouse operators in the Netherlands and Spain select films based on light diffusion spectra and thermal retention coefficients. Multi-season durability requirements favor higher-unit-cost nanoclay structures.
Builders represent the largest addressable base; electronics OEMs drive specification intensity upward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vapor barrier films concentrates in construction-intensive economies where energy code enforcement and retrofit incentives synchronize. Procurement authority is migrating toward national aggregators in the United States, while European REACH compliance deadlines reshape supplier qualification pools.
United States
Residential and commercial builders drive specification of high-performance moisture control systems under ICC and ASHRAE code harmonization. The Inflation Reduction Act directs capital toward deep energy retrofits, shortening membrane replacement intervals in existing building stock. Blown film extrusion capacity clusters along the US Gulf Coast supply commodity polyethylene membranes at scale.
Germany
EU Green Deal carbon accounting rules mandate embodied carbon disclosure for construction membranes sold across member states. ECHA substance evaluations on phthalate plasticizers force reformulation toward compliant chemistries, creating specification windows for qualified suppliers. Industrial concentration in the German chemical corridor exposes buyers to weather-related disruption risks.
China
Semiconductor cleanroom demand from advanced packaging facilities accelerates qualification of ultra-high-barrier rigid composites. The country's dual carbon goals pressure conventional polyethylene and polypropylene barriers toward bio-based or recycled content alternatives. Manufacturing gravity centers on Yangtze River Delta extrusion clusters serving domestic electronics OEMs.
India
Bureau of Indian Standards updates to envelope performance standards create first-mover positioning for compliant membrane suppliers. Building code modernization in Maharashtra and Gujarat drives specification pull from commercial construction aggregators. National construction aggregators are centralizing procurement platforms that unbundle material selection from installation labor.
Netherlands
Greenhouse operators adopt nanoclay interlayer technologies for 4-5 season crop cycles requiring diffused-light vapor barriers with integrated thermal properties. REACH restrictions on conventional polymer formulations accelerate supplier qualification timelines for Dutch and Belgian agricultural markets. Eindhoven Region fabrication clusters specialize in multilayer coextrusion for controlled-environment applications.
Vapor Barrier Films Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based formulations and digital specification platforms. The vendor base stratifies across three tiers: multinational chemical conglomerates with polymer science depth, specialized film converters with regional extrusion scale, and niche composite fabricators serving electronics cleanroom specifications. Two strategic archetypes dominate competitive positioning—specification-driven building science specialists and cost-optimized commodity converters. M&A activity concentrates on acquiring multilayer coextrusion expertise, while capacity expansion targets US Gulf Coast and German chemical corridor clusters.
Among diversified chemical conglomerates, DuPont de Nemours, Inc. and BASF SE exemplify the polymer chemistry leadership archetype, anchoring competitive positioning through engineered resin supply and building science expertise. Berry Global Inc. represents the scale-driven converter tier with North American extrusion capacity and distributor relationship depth. These three entities illustrate how competitive advantage splits between upstream material science control and downstream specification access.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| BASF SE |
| Berry Global Inc. |
| Amcor Plc |
| 3M Company |
| Cosmo Films Ltd. |
| Carlisle Companies Incorporated |
| Polyguard Products, Inc. |
| Raven Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between NFPA 285-compliant multilayer membranes and commodity polyethylene sheeting manifests in both margin structures and sourcing configurations. Premium tiers command specification authority through extended fire-testing timelines while commodity converters compete on resin cost exposure and Gulf Coast logistics access.
Pricing Analysis
Volume concentrates in blown film polyethylene at commodity margin profiles while rigid composite and nanoclay-interlayer formats capture premium economics. Price differentiation separates ICC-certified building wraps from uncertified agricultural films, with REACH-compliant reformulations adding formulation cost premiums. Pricing pressure intensifies in polyethylene tiers as ethylene feedstock volatility compresses converter margins. National construction aggregators exhibit lowest price sensitivity given unbundled procurement platforms, whereas independent residential builders in retrofit markets remain most cost-responsive.
Supply Chain Analysis
Reverse-logistics flows for rigid electronics shipping containers create secondary material streams through refurbishment and remanufacturing channels in Taiwan and South Korea. Blown film capacity clusters in the United States, Germany, and China, with extrusion lines drawing from naphtha and natural gas liquids feedstocks. Single-source vulnerability concentrates in multilayer coextrusion equipment suppliers, where seven-layer and nine-layer line manufacturers anchor global availability. Distribution runs through national construction aggregators and specialized film distributors serving regional greenhouse and electronics OEM clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multilayer coextrusion expertise scarcity props pricing across premium barrier segments, constraining qualified supplier pools and sustaining margin capture for incumbent compounders.
For Market Incumbents: Cement specification lock-in through embedded BIM platform partnerships with national construction aggregators. Deepen backward integration into engineered resin supply to offset ethylene feedstock volatility. Defend against bio-based entrants by accelerating REACH-compliant reformulation cycles ahead of 2027 carbon disclosure deadlines. For New Entrants and Emerging Players: The mid-tier price gap between DuPont Tyvek-specified building wraps and commodity polyethylene offers white-space positioning for digitally-enabled specification platforms. Target Indian commercial construction aggregators ahead of Bureau of Indian Standards enforcement windows. Pursue agricultural greenhouse operators in Spain with diffused-light thermal film bundles. For Investors and Strategic Acquirers: Re-rating potential sits with multilayer coextrusion specialists given semiconductor cleanroom demand acceleration across Taiwan and South Korea. Long-term viability favors targets with captive nanoclay interlayer technology and established NFPA 285 certification pathways. Watch for inflection in Indian building code enforcement velocity as procurement centralization signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Seven-layer and nine-layer lines address electronics cleanroom MVTR requirements in Taiwan fabrication clusters. |
| Backward Integration into Engineered Resins | Captive polymer chemistry control insulates margin compression from naphtha and natural gas liquids volatility. |
| BIM Platform Specification Partnerships | Embedded performance data in architectural workflows secures aggregator procurement centralization in United States residential construction. |
| REACH-Compliant Reformulation Program | Phthalate-free polyethylene alternatives maintain European market access under ECHA substance evaluations. |
| Indian Market First-Mover Qualification | Bureau of Indian Standards compliance ahead of enforcement creates franchise positioning with commercial aggregators in Maharashtra and Gujarat. |
Research Methodology
Trade association filings, customs and resin import records, and building code regulatory databases formed the secondary backbone for this analysis. Primary interviews with blown film plant managers, procurement leads at national construction aggregators, distribution channel partners, and technical R&D directors at polymer compounders combined with secondary validation. Bottom-up triangulation across resin consumption volumes and top-down cross-check against end-use installation rates anchored market sizing.
Historical trendline analysis of polyethylene resin pricing, multilayer film production capacity, and specification adoption curves informed projection frameworks across the analysis window. Segmentation modeling incorporated resin type, application environment, material format, and end-user procurement authority. CAGRs derived from elasticity-adjusted demand curves for construction retrofit cycles and semiconductor capital expenditure patterns.
Underlying measurement precision varies by segment; electronics cleanroom specifications carry tighter precision than agricultural greenhouse estimates given documented MVTR testing protocols. Forecasts reflect assumptions on building code harmonization velocity, REACH enforcement intensity, and feedstock cost trajectories. Material deviation in Indian regulatory enforcement timing or Gulf Coast weather disruption patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Bitumen Membranes Market