
 Fuel Cell Gas Diffusion Layer Market | 2026-2036
Fuel Cell Gas Diffusion Layer Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Gas Diffusion Layer Market Analysis
Heavy-duty fleet operators are redrawing procurement priorities for fuel cell gas diffusion layers as passenger vehicle OEMs cede near-term volume leadership. Toray Industries leverages its carbon fiber dominance to anchor supply security for woven substrate backbones. SGL Carbon competes through specialized graphitization capacity that sustains thermal conductivity benchmarks. Freudenberg Performance Materials differentiates via hydrophobic coating integration that controls water management in high-current-density stacks.
A fuel cell gas diffusion layer is a porous electrode component, typically carbon paper or carbon cloth with polytetrafluoroethylene treatment, engineered to transport reactant gases, conduct electrical current, and remove product water while maintaining mechanical integrity under compression. Its primary purpose is enabling uniform gas distribution and efficient mass transfer at the catalyst layer interface in proton exchange membrane fuel cells. PEM deployment occupies the dominant revenue position due to automotive traction and established membrane-electrode-assembly supply chains. Stationary installations represent the fastest-growing deployment category as data centers and grid-scale storage projects adopt megawatt-class systems. Carbon material formulations command the deepest margin pools because substrate manufacturing requires specialized graphitization furnaces with limited global capacity.
The US Inflation Reduction Act production tax credits and Japan's METI hydrogen supply chain targets are reshaping qualification requirements for gas diffusion layer suppliers seeking market access. REACH compliance in Europe and China's GB/T fuel cell standards impose divergent testing protocols for PTFE content and electrical resistivity that fragment certification pathways. Stakeholders must monitor how regional content rules for clean hydrogen subsidies redefine acceptable supplier geographies and material provenance documentation.
Market Dynamics
Heavy-duty trucking fleets are redrawing procurement priorities for fuel cell gas diffusion layers as passenger vehicle OEMs cede near-term volume leadership. Toray Industries leverages its carbon fiber dominance to anchor supply security for woven substrate backbones. SGL Carbon competes through specialized graphitization capacity that sustains thermal conductivity benchmarks. Freudenberg Performance Materials differentiates via hydrophobic coating integration that controls water management in high-current-density stacks.
Growth Catalysts
- US IRA production tax credits:Heavy-duty fleet operators are accelerating hydrogen fuel cell procurement as the Inflation Reduction Act lowers total cost of ownership for zero-emission trucking.
- Japan's METI hydrogen roadmap:Clustered fuel cell manufacturing around Nagoya is concentrating demand for high-performance gas diffusion layers in East Asian supply chains.
- Data center power demand:Stationary installations are expanding as megawatt-class fuel cell systems displace diesel backup generators for grid-scale storage projects.
Market Restraints
- Graphitization furnace scarcity:Specialized high-temperature carbon processing capacity concentrates in Germany and Japan, creating input bottlenecks for substrate manufacturers.
- PTFE supply chain concentration:Fluoropolymer feedstock dependence on limited chemical producers exposes gas diffusion layer makers to raw material volatility.
- Divergent certification pathways:REACH compliance in Europe and China's GB/T fuel cell standards impose conflicting testing protocols for electrical resistivity that fragment market access.
Strategic Opportunities
- Stationary power in Germany:The EU Green Deal hydrogen mandates are opening procurement channels for megawatt-scale proton exchange membrane systems in industrial parks.
- Carbon cloth convergence:Woven substrate technology is merging with flexible electrode manufacturing to enable roll-to-roll production for next-generation membrane-electrode-assemblies.
- South Korean electrolyzer demand:The country's hydrogen economy roadmap is creating adjacent demand for gas diffusion layers in alkaline and PEM electrolysis stacks.
Industry Challenges
- Graphitization engineering talent:The specialized furnace operation and carbon microstructure control expertise required for substrate production remains scarce across manufacturing regions.
- Regional content documentation:Clean hydrogen subsidy programs are imposing material provenance tracking requirements that strain existing supply chain audit capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Gas Diffusion Layer Market |
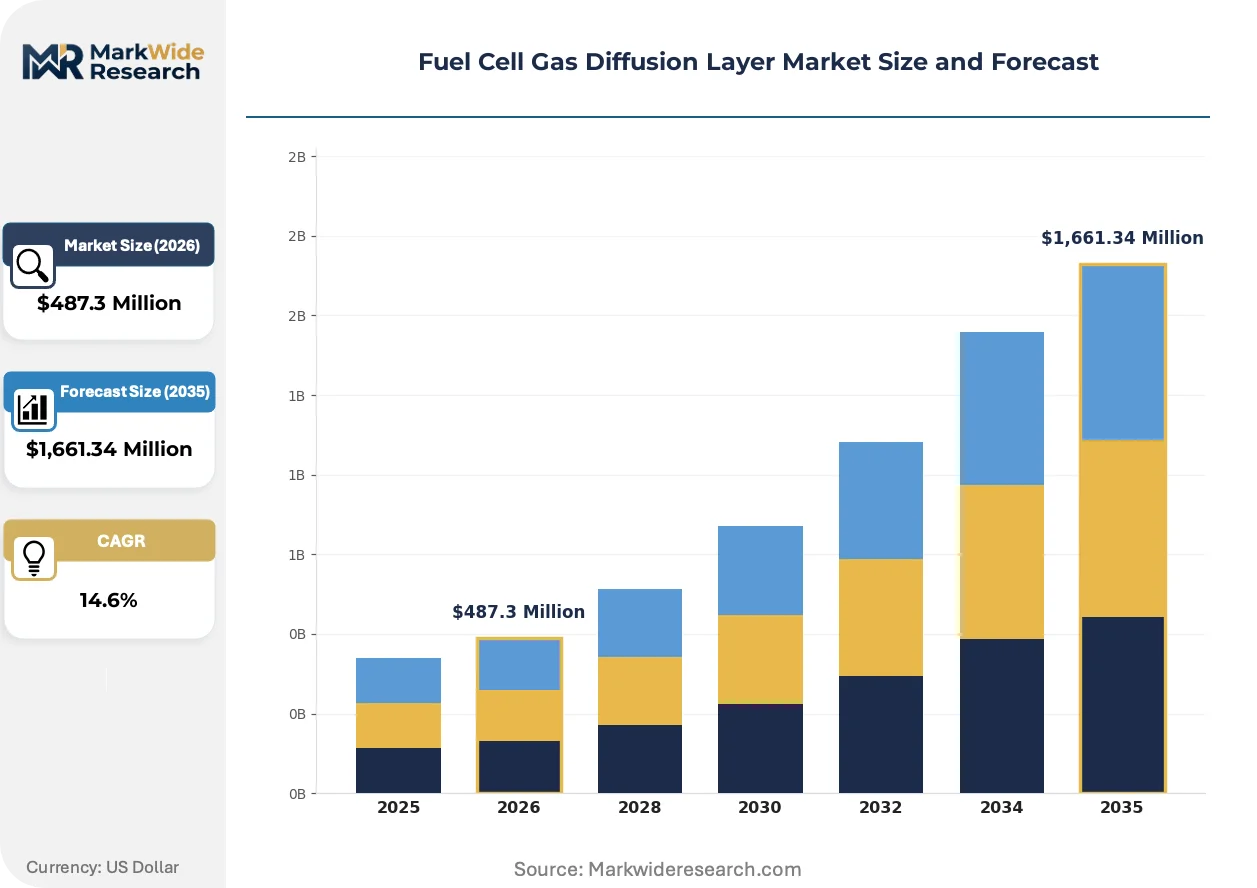
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEM, AEM, DMFC, SOFC End User: Automotive, Industrial, Commercial, Residential Material: Carbon, Teflon, Nylon, Aluminum Deployment: Onboard, Stationary, Portable, Others |
| Companies Covered | The Chemours Company, Teijin, Toray Industries, Ballard Power Systems, AvCarb Material Solutions, SGL Carbon, Mitsubishi Chemical Corporation, DuPont, Freudenberg Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Gas Diffusion Layer Market Emerging Trajectories
Carbon material formulations are commanding the deepest margin pools as substrate manufacturing requires specialized graphitization furnaces with limited global capacity. Three interconnected developments are reshaping how gas diffusion layers are engineered, qualified, and procured across automotive and stationary applications.
Multi-layer gradient porosity structures are decomposing the traditional single-substrate design paradigm. Tier 1 stack assemblers are adopting these architectures to optimize gas transport and water removal simultaneously. The technology is compressing qualification timelines as integrated coating and lamination processes replace sequential assembly steps.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic coatings in European supply chains. The regulation is driving investment in alternative fluoropolymer chemistries and plasma treatment processes. PEM fuel cell manufacturers serving EU markets are accelerating supplier audits to verify PTFE content compliance ahead of enforcement deadlines.
Fleet operators are consolidating procurement decisions at the system level rather than component level, compressing the traditional multi-tier supplier hierarchy. Direct relationships between heavy-duty truck OEMs and gas diffusion layer specialists are displacing membrane-electrode-assembly intermediaries in North American supply chains. This pattern is most visible in California where CARB zero-emission mandates concentrate early commercial deployment.
Fuel Cell Gas Diffusion Layer Market Segmentation
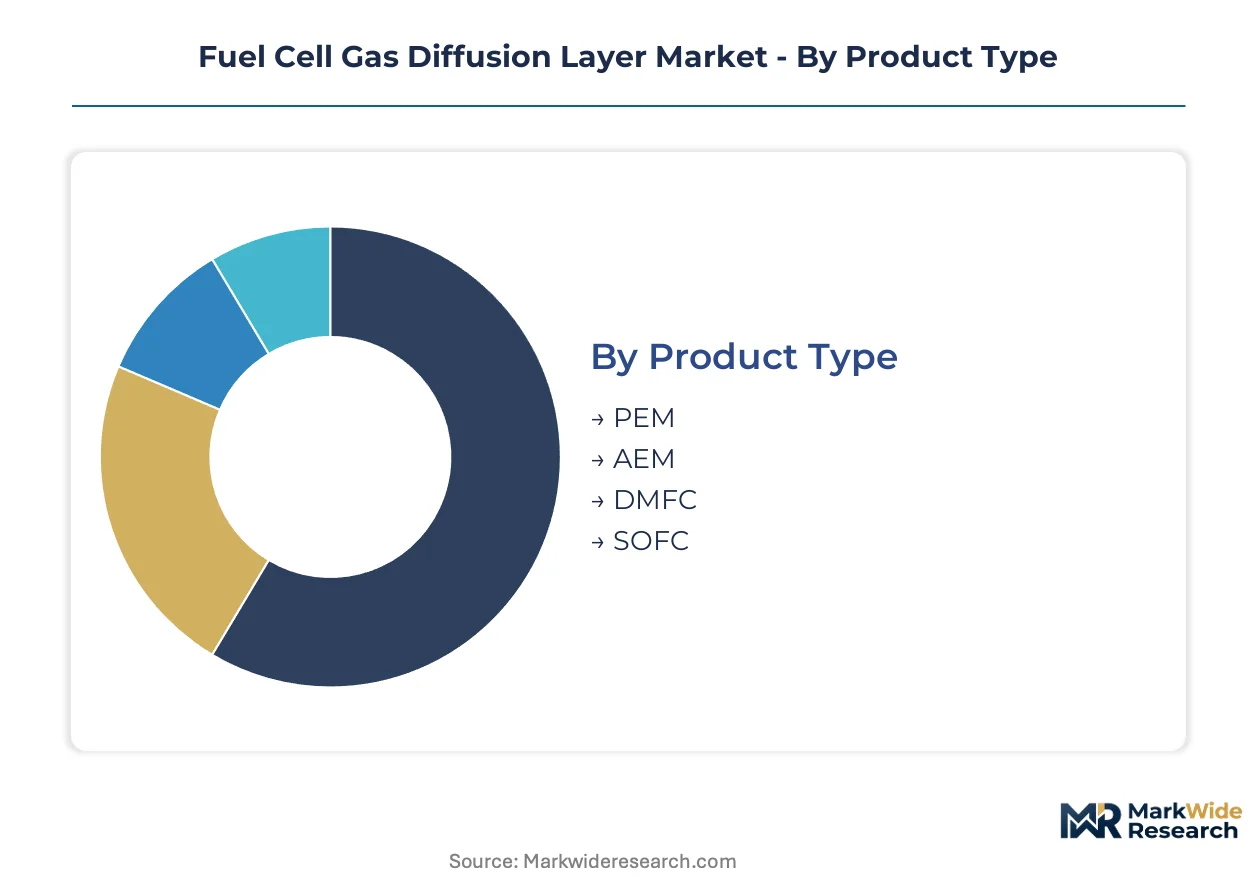
Segmentation in the fuel cell gas diffusion layer market reveals how technical specifications, material choices, and deployment contexts fragment procurement requirements across automotive OEMs, stationary power developers, and industrial hydrogen adopters. Understanding these divisions exposes where margin pools concentrate and which qualification pathways dominate supplier access.
Product Type:
PEM dominates export-heavy supply chains serving automotive and stationary applications, while AEM and DMFC retain more localized, pilot-scale demand profiles.
- PEM:Proton exchange membrane gas diffusion layers use carbon fiber substrates with PTFE hydrophobic treatment to manage high current densities in automotive stacks. Demand concentrates in heavy-duty trucking fleets across California, Germany, and Japan where IRA production tax credits and EU Green Deal hydrogen mandates accelerate fleet procurement.
- AEM:Anion exchange membrane variants employ non-fluorinated ionomers that reduce platinum catalyst loading and enable alkaline chemistry compatibility. Development clusters in South Korean and Dutch research consortia pursuing cost parity with PEM systems for stationary power.
- DMFC:Direct methanol fuel cell gas diffusion layers handle liquid fuel crossover challenges through specialized anode hydrophobicity gradients. Portable electronics and military applications in Japan and Germany sustain niche demand.
- SOFC:Solid oxide fuel cell variants require ceramic-metallic composite structures operating at elevated temperatures. Stationary cogeneration installations in Germany and Japan drive qualification programs for high-temperature substrate stability.
PEM holds the largest share; momentum sits with AEM as non-fluorinated chemistry research advances toward commercial scale.
End User:
Cost tier differentiation separates premium qualification requirements in automotive from volume-driven industrial procurement and price-sensitive residential segments.
- Automotive:OEMs impose stringent thermal cycling durability and compression set specifications for membrane-electrode-assembly integration. Heavy-duty truck manufacturers in the US and Japan consolidate direct supplier relationships to secure substrate capacity ahead of IRA-driven fleet expansion.
- Industrial:Megawatt-scale stationary systems for data centers and chemical plants prioritize electrical conductivity and water management over automotive cycling durability. German industrial parks and South Korean steel complexes anchor procurement concentration.
- Commercial:Forklift fleets and backup power systems balance capital cost constraints with operational uptime requirements. Distribution centers in California and logistics hubs in Japan drive replacement demand cycles.
- Residential:Combined heat and power micro-cogeneration units in Japan and Germany emphasize system integration simplicity over peak performance metrics.
Automotive commands premium pricing; industrial applications are climbing the fastest as megawatt-scale deployments multiply.
Material:
Supply concentration in carbon fiber precursors and fluoropolymer feedstocks shapes regional material availability and cost structures.
- Carbon:Woven carbon fiber and carbon paper substrates dominate through Toray Industries' PAN precursor supply and SGL Carbon's graphitization capacity. Japanese and German furnace operations constrain global substrate output.
- Teflon:PTFE hydrophobic coatings control water removal in high-current-density stacks. REACH substance restrictions in Europe force reformulation investment ahead of perfluoroalkyl enforcement deadlines.
- Nylon:Alternative polymer binders emerge in cost-optimized applications where fluoropolymer content faces regulatory pressure.
- Aluminum:Metallic mesh substrates serve specialized SOFC and AEM architectures requiring thermal expansion matching.
Carbon substrates absorb the largest procurement spend; Teflon alternatives are gaining share fastest under European chemical regulation.
Deployment:
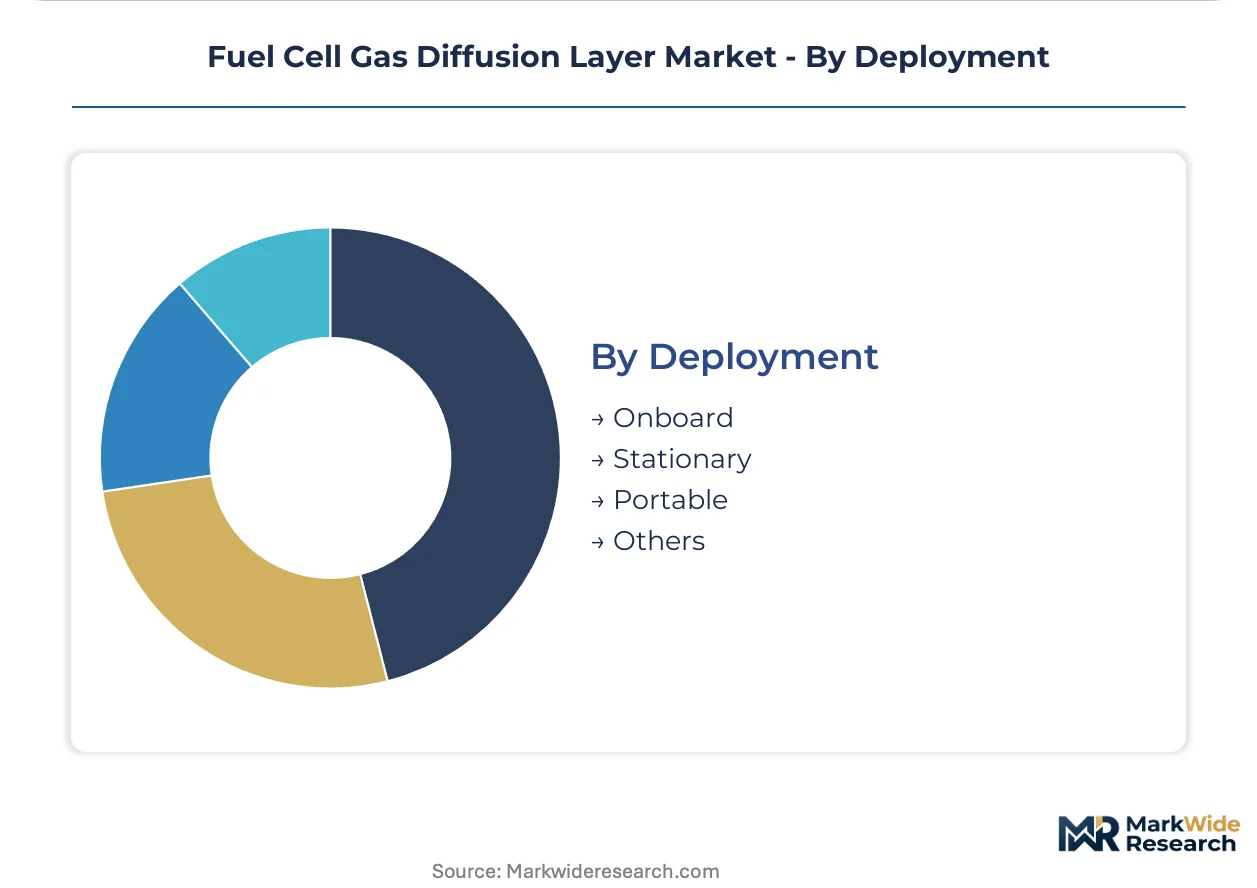
Volume scale separates onboard automotive manufacturing from stationary project-based procurement and portable system batch production.
- Onboard:Vehicle-integrated fuel cell stacks demand vibration-resistant substrate laminates with automotive-grade quality systems. US and Japanese OEMs qualify suppliers against SAE and JIS durability protocols.
- Stationary:Grid-scale and backup power installations specify larger active areas with relaxed mechanical stress requirements. German data center operators and South Korean utility projects drive megawatt-class membrane-electrode-assembly demand.
- Portable:Small-format systems for recreational and emergency power prioritize packaging density over efficiency optimization.
- Others:Maritime and aviation prototype applications impose specialized salt spray and altitude pressure specifications.
Onboard deployment leads absolute volume; stationary systems are expanding most quickly as diesel displacement accelerates in critical power infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized graphitization furnace capacity concentrates in Germany and Japan, constraining substrate supply for gas diffusion layer manufacturers worldwide. This bottleneck shapes regional competitive positioning as qualification requirements diverge across automotive and stationary power markets.
United States
Heavy-duty trucking fleets in California and Texas are scaling fuel cell procurement as IRA production tax credits compress total cost of ownership. EPA and NHTSA emissions rules tighten diesel restrictions through 2027. The Port of Long Beach anchors zero-emission drayage pilot programs that concentrate early GDL demand.
Germany
Industrial parks in North Rhine-Westphalia and Bavaria are deploying megawatt-class stationary systems under EU Green Deal hydrogen mandates. REACH substance restrictions on perfluoroalkyl compounds force coating reformulation ahead of enforcement deadlines. The ECHA regulatory framework fragments certification pathways for PTFE content documentation.
Japan
Clustered fuel cell manufacturing around Nagoya and Tokyo concentrates demand for high-performance woven substrates. METI hydrogen roadmap targets concentrate supply chain investment in Chubu region. Toray Industries' carbon fiber precursor operations anchor domestic substrate security for automotive OEM qualification programs.
South Korea
Steel complexes and data center operators in Busan-Ulsan and Seoul Capital Area are procuring megawatt-scale PEM systems under national hydrogen economy targets. The MFDS and KATS standards bodies align testing protocols with automotive durability requirements. Daegu-Gyeongbuk electrolyzer manufacturing creates adjacent GDL demand for alkaline and PEM stacks.
China
Fuel cell vehicle deployment in Beijing-Tianjin-Hebei and the Yangtze River Delta drives carbon paper qualification against GB/T standards. MIIT industrial policy concentrates membrane-electrode-assembly capacity in Shanghai and Guangzhou. SAMR enforcement of dual carbon goals accelerates diesel displacement in port logistics and urban freight corridors.
Fuel Cell Gas Diffusion Layer Market Vendor Landscape
Concentration sits with integrated carbon fiber-to-substrate manufacturers possessing captive graphitization capacity. The competitive structure stratifies between PAN precursor producers, specialized furnace operators, and coating integration specialists. Three archetypes dominate: upstream carbon fiber suppliers controlling substrate backbones, independent graphitization houses serving second-source qualification needs, and membrane-electrode-assembly integrators backward-integrating into GDL production. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs consolidate direct supplier relationships.
Within the integrated substrate tier, Toray Industries and SGL Carbon exemplify divergent geographic anchoring strategies for furnace capacity deployment. Freudenberg Performance Materials occupies a position bridging hydrophobic coating specialization with roll-to-roll manufacturing scale. These three entities represent the archetype spectrum from upstream carbon control through downstream integration, with each facing distinct qualification pressures from divergent regional certification pathways.
| Leading Market Players |
|---|
| The Chemours Company |
| Teijin |
| Toray Industries |
| Ballard Power Systems |
| AvCarb Material Solutions |
| SGL Carbon |
| Mitsubishi Chemical Corporation |
| DuPont |
| Freudenberg Performance Materials |
| Others |
Supply Flow & Price Mechanics
Ninety-to-one-hundred-day substrate lead times concentrate pricing power with Japanese and German furnace operators who anchor carbon fiber supply security. This interval between order and delivery compresses buyer negotiation leverage while amplifying margin capture for integrated precursor-to-substrate manufacturers serving IRA-qualified heavy-duty fleet programs.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European supply chains. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade PTFE-compliant substrates from industrial stationary systems and cost-optimized commercial units. Cost compression in the economy tier is intensifying because alternative fluoropolymer R&D drains working capital ahead of enforcement deadlines. Commercial forklift operators exhibit the sharpest price sensitivity, while automotive OEMs absorb premium tiers to secure membrane-electrode-assembly qualification slots.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains just-in-time delivery for woven carbon fiber precursors. Manufacturing gravity centers on Japan, Germany, and South Korea where Toray Industries, SGL Carbon, and domestic furnace operators feed from polyacrylonitrile fiber and specialized graphitization capacity. Single-source vulnerability concentrates in PTFE resin supply where Chemours and Daikin anchor global fluoropolymer output. Distribution runs through membrane-electrode-assembly integrators in California, Bavaria, and Chubu region who consolidate tier-2 qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell gas diffusion layers sit in early-cycle expansion as IRA production tax credits compress heavy-duty fleet total cost of ownership below diesel parity. This policy tailwind accelerates procurement timelines beyond substrate capacity expansion rates.
For Market Incumbents: Consolidate graphitization furnace capacity in Nagoya and North Rhine-Westphalia to defend against South Korean electrolyzer entrants backward-integrating into carbon substrate production. Lock long-term PAN precursor supply with Toray Industries before chemical fiber allocation shifts toward aerospace demand recovery. Prioritize REACH-compliant coating R&D to preserve European market access against regulatory forfeiture risk. For New Entrants and Emerging Players: Lead with AEM-compatible non-fluorinated substrate development targeting South Korean and Dutch research consortia pursuing cost parity with PEM systems. Stationary power in German industrial parks offers the most penetrable white-space as EU Green Deal hydrogen mandates outrun incumbent qualification bandwidth. Pursue direct OEM relationships in California CARB jurisdictions where fleet operators consolidate procurement above membrane-electrode-assembly intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive carbon fiber operations but stranded fuel cell commercialization assets. Five-to-ten-year viability hinges on furnace capacity scarcity persisting against electrolyzer demand convergence. Watch South Korean electrolyzer manufacturing scale as the inflection signal for alkaline GDL demand crossover.| Strategic Initiative | Industry Significance |
|---|---|
| Graphitization Capacity Expansion | Captive furnace investment in Chubu region secures substrate supply for METI-qualified automotive programs. |
| Backward Integration into PAN Precursor | Upstream control over polyacrylonitrile fiber reduces exposure to aerospace demand cyclicality. |
| REACH-Compliant Coating Development | Alternative fluoropolymer chemistry preserves EU market access ahead of perfluoroalkyl enforcement deadlines. |
| Direct OEM Supply Agreements | California fleet procurement consolidation displaces membrane-electrode-assembly intermediaries in North American channels. |
| Electrolyzer GDL Qualification | South Korean alkaline and PEM stack demand creates adjacent revenue pool beyond fuel cell deployment. |
Methodological Framework
Operator-level perspectives from fuel cell stack engineering directors, carbon fiber procurement leads at automotive OEMs, graphitization furnace operations managers, and membrane-electrode-assembly integrators anchored the qualitative base. Primary interviews triangulated against secondary validation from EPA IRA guidance documents, METI hydrogen roadmap publications, ECHA REACH substance restriction filings, and customs trade data on carbon fiber precursor flows. Bottom-up substrate capacity modeling and top-down fleet deployment projections converged across the analysis window.
Sensitivity analysis tested forecast robustness against IRA credit extension scenarios and REACH enforcement timeline acceleration. Segmentation dimensions modeled include fuel cell chemistry type, deployment context, material formulation, and end-use durability tier. CAGRs derived from installed base accumulation curves and replacement cycle assumptions. Industry-specific inputs incorporated graphitization furnace utilization rates and PTFE coating line throughput constraints.
The analysis sits within stated boundaries; outcomes outside sustained IRA credit availability or accelerated fluoropolymer substitution timelines would require recalibration. Forecasts reflect assumptions on furnace capacity expansion rates, regulatory enforcement schedules, and fleet operator procurement consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Breather Membranes Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Global Ion Exchange Membrane Market