
 Microporous Materials Market | 2026-2036
Microporous Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Microporous Materials Market Foresight
Multi-source procurement for specialty zeolites and carbon molecular sieves is shifting as buyers seek supply security after recent raw material disruptions. BASF SE leverages its integrated petrochemical feedstock position to control precursor costs for synthetic zeolite production. Zeolyst International anchors North American supply through its dedicated catalyst manufacturing complex in Kansas. Honeywell International Inc. (UOP) dominates licensing technology for refinery-grade molecular sieve units worldwide.
Microporous materials are solids containing interconnected pores with diameters below two nanometers, typically synthesized via hydrothermal crystallization, sol-gel processing, or chemical vapor deposition to achieve precise pore size distributions for selective molecular separation. Their primary commercial purpose centers on adsorption, ion exchange, and catalytic conversion across energy, environmental, and healthcare systems. Zeolites command the largest installed base in petroleum refining and detergent builders, while metal-organic frameworks represent the fastest-expanding category due to designer pore functionality for hydrogen storage and carbon capture. Carbon-based microporous structures concentrate margin pools in medical oxygen concentrators and battery electrode additives where ultra-high surface area commands technical premiums.
EPA emissions standards for volatile organic compounds and the EU F-Gas Regulation on fluorinated greenhouse gases are tightening specifications for adsorbent materials used in industrial air purification and refrigerant recovery systems. REACH registration requirements in Europe and China's GB standards on air quality monitoring equipment are forcing reformulation of silica gel desiccants and synthetic zeolite powders to eliminate hazardous impurities. FDA guidance on inhalation drug products is reshaping qualification protocols for pharmaceutical-grade molecular sieves in pulmonary delivery devices. Stakeholders must monitor evolving chemical safety dossiers across multiple jurisdictions to sustain product registration and avoid supply exclusion.
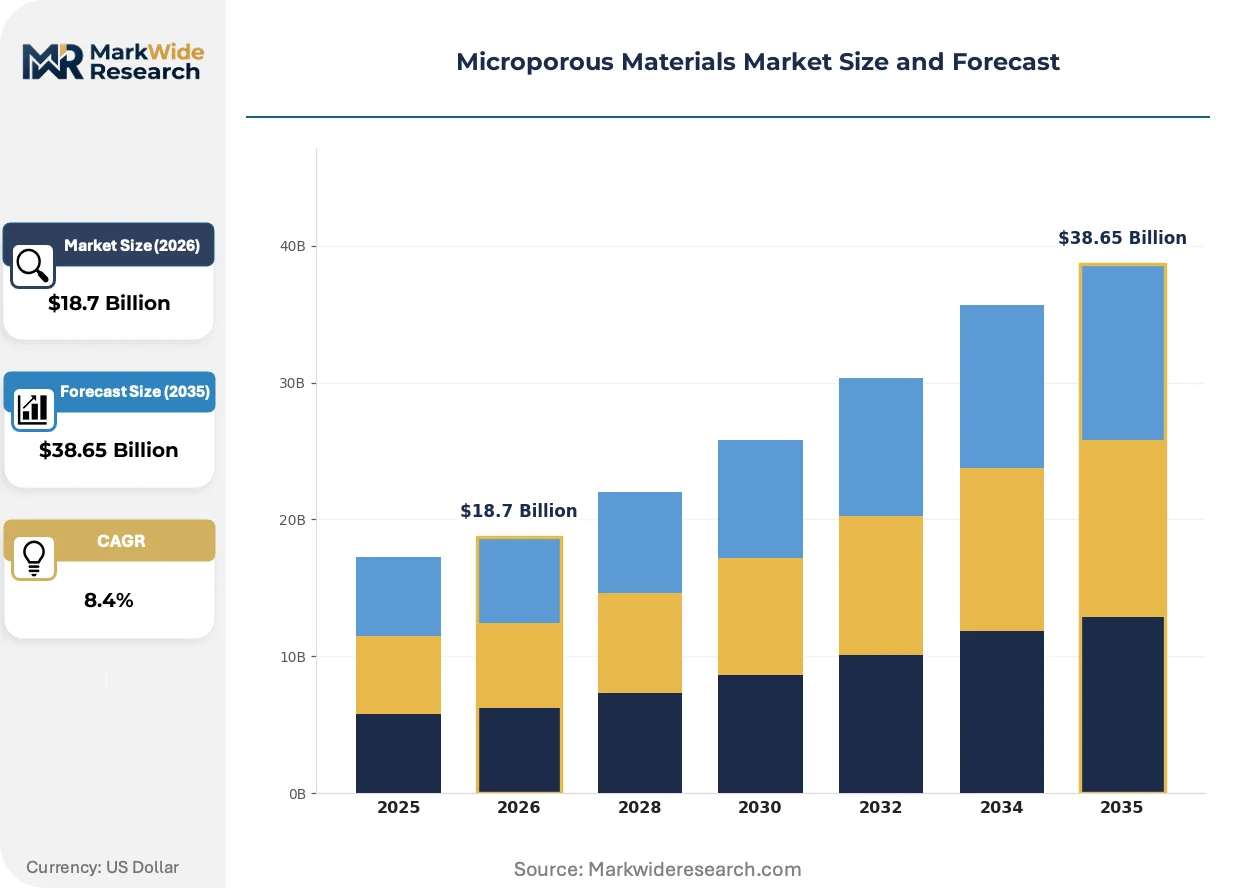
Market Dynamics
The microporous materials sector is restructuring around feedstock security and precision synthesis capabilities as pharmaceutical and hydrogen storage applications impose stricter pore architecture specifications. Metal-organic framework production is concentrating among integrated chemical conglomerates with captive precursor supply.
Growth Catalysts
- EPA VOC Emissions Standards:Industrial air purification mandates in the United States are expanding demand for high-selectivity zeolite adsorbents in solvent recovery and paint booth applications.
- Carbon Capture Infrastructure:Metal-organic frameworks with tunable pore sizes are capturing investment for post-combustion CO2 separation as national decarbonization targets harden.
- China:GB standards on air quality monitoring equipment are accelerating domestic production of synthetic zeolite sensors and calibration-grade molecular sieves.
Market Restraints
- Aluminosilicate Precursor Volatility:Bauxite and kaolin supply disruptions have destabilized synthetic zeolite cost structures, compressing margins for non-integrated producers.
- Specialty Zeolite Concentration:Germany and the Netherlands host the majority of pharmaceutical-grade molecular sieve capacity, creating single-point failure exposure.
- Silica Gel Substitution:Advanced polymer desiccants are displacing traditional silica gel in electronics packaging, eroding volume in commodity moisture control.
Strategic Opportunities
- India:CDSCO's tightening bioequivalence protocols for inhaled generics are opening demand for pharmaceutical-grade zeolites in pulmonary drug delivery devices.
- Hydrogen Storage Systems:Metal-organic frameworks with cryogenic stability are enabling high-density hydrogen carriers for heavy transport applications.
- Direct-to-Device Supply:Medical oxygen concentrator manufacturers are bypassing distributors to secure carbon molecular sieve contracts with guaranteed purity certification.
Industry Challenges
- REACH Dossier Complexity:ECHA's evolving requirements for synthetic zeolite safety data are extending product registration timelines by 18-24 months.
- MOF Scale-Up Engineering:Translating laboratory metal-organic framework formulations to continuous production requires specialized crystallization reactor design expertise that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microporous Materials Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon-based, Zeolites, Metal-organic Frameworks, Silica Gels Application: Gas Storage, Catalysis, Drug Delivery, Water Treatment End User: Chemical Industry, Pharmaceutical Sector, Environmental Sector, Food and Beverage Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | BASF SE, Axens, Zeolyst International, Solvay, AGC Chemicals, Kuraray Co., Ltd., Cabot Corporation, Honeywell International Inc. (UOP), Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microporous Materials Market Shifts & Advancements
Computational materials design is collapsing development cycles for pore-engineered structures while regulatory chemistry is forcing reformulation of legacy adsorbent grades. Buyers are consolidating supplier relationships around certified quality systems.
Metal-organic framework synthesis is modularizing through automated ligand exchange protocols that enable rapid pore size adjustment without full batch redesign. Hydrogen storage system developers in Germany and Japan are adopting these platforms to accelerate prototype iteration. The technology is modularizing what was previously a bespoke materials engineering service into a catalog-configurable product line.
REACH registration requirements are eliminating hazardous impurities from silica gel desiccants used in pharmaceutical and food packaging across Europe. ECHA's updated dossier standards are forcing reformulation of legacy grades containing trace heavy metals. Medical device manufacturers are responding by qualifying alternative synthetic zeolite sources with pre-validated compliance packages.
Specification-driven procurement is compressing supplier qualification cycles as pharmaceutical and aerospace buyers consolidate around ISO-certified molecular sieve vendors. Distributor intermediaries are losing share to direct manufacturer relationships with embedded technical service. This concentration is most visible in the United States, where FDA inhalation drug guidance has made batch-to-batch consistency a non-negotiable selection criterion.
Microporous Materials Market Segmentation
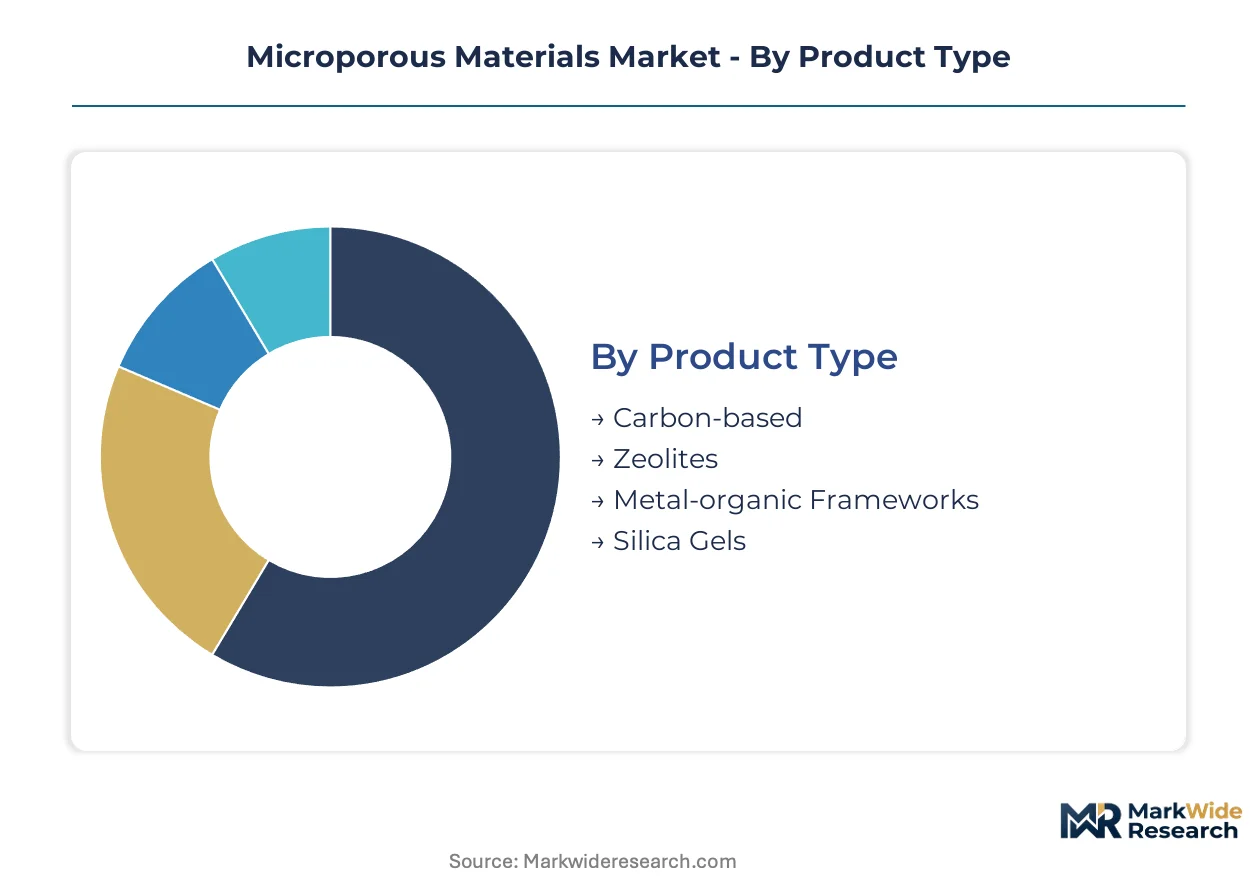
Microporous materials command divergent pricing architectures across product categories due to synthesis complexity and certification requirements. Segmentation reveals how supply concentration in synthetic zeolites and emerging metal-organic frameworks creates distinct competitive dynamics for procurement strategy.
Product Type:
Supply concentration varies sharply across synthesis routes, with hydrothermal crystallization facilities clustering near petrochemical feedstock hubs while metal-organic framework production requires specialized ligand chemistry expertise.
- Zeolites:Aluminosilicate frameworks with tunable pore apertures between 0.3 and 2 nanometers dominate petroleum refining catalysts and detergent builders. BASF SE and Honeywell UOP control the majority of synthetic zeolite capacity in Germany and the United States, leveraging integrated bauxite refining positions to manage precursor cost volatility.
- Metal-organic Frameworks:Crystalline coordination networks built from metal nodes and organic linkers enable designer pore functionality for hydrogen storage and carbon capture. Research partnerships between German chemical conglomerates and Japanese hydrogen infrastructure developers are accelerating MOF commercialization beyond laboratory scale.
- Carbon-based:Activated carbons and carbon molecular sieves concentrate in medical oxygen concentrators and battery electrode additives where ultra-high surface area commands technical premiums.
- Silica Gels:Amorphous silicon dioxide desiccants face displacement from advanced polymer alternatives in electronics packaging applications.
Zeolites absorb the bulk of installed capacity; metal-organic frameworks are expanding most quickly.
Application:
Cost tiers stratify sharply between commodity-scale industrial processes and precision-regulated pharmaceutical systems requiring batch certification.
- Catalysis:Zeolite catalysts in fluid catalytic cracking and hydrocracking units process over 90 million barrels of crude daily worldwide. Refinery operators in the United States and China specify pore architectures optimized for heavy sour crude processing, driving demand for ultra-stable Y-zeolite variants.
- Drug Delivery:Pharmaceutical-grade molecular sieves enable controlled release in pulmonary inhalers and implantable devices. FDA guidance on inhalation drug products and EMA bioequivalence standards are tightening qualification protocols, consolidating procurement around ISO-certified suppliers with pre-validated compliance packages.
- Gas Storage:Hydrogen and methane storage applications favor metal-organic frameworks with cryogenic stability for heavy transport fuel systems.
- Water Treatment:Ion-exchange zeolites remove heavy metals and ammonium from municipal and industrial wastewater streams.
Catalysis commands the dominant share of volume throughput; drug delivery generates the steepest margin expansion trajectory.
End User:
Customer type determines certification burden and contract structure, with pharmaceutical and environmental sectors imposing divergent technical service requirements.
- Chemical Industry:Petrochemical and specialty chemical producers purchase zeolite catalysts through long-term supply agreements with embedded technical service. Refinery-grade molecular sieve procurement in the United States concentrates around direct manufacturer relationships as Honeywell UOP dominates licensing technology worldwide.
- Pharmaceutical Sector:CDSCO's tightening bioequivalence protocols for inhaled generics in India are opening demand for pharmaceutical-grade zeolites in pulmonary drug delivery devices. Medical device manufacturers bypass distributors to secure carbon molecular sieve contracts with guaranteed purity certification.
- Environmental Sector:EPA VOC emissions standards and EU F-Gas Regulation are expanding demand for high-selectivity zeolite adsorbents in industrial air purification and refrigerant recovery systems.
- Food and Beverage:REACH registration requirements are eliminating hazardous impurities from silica gel desiccants used in pharmaceutical and food packaging across Europe.
Chemical industry offtake dominates absolute volume; pharmaceutical sector procurement is climbing the fastest on value terms.
Distribution Channel:
Channel selection reflects buyer sophistication and certification requirements, with specification-driven procurement compressing intermediary roles.
- Direct Sales:Medical oxygen concentrator manufacturers and refinery operators negotiate directly with molecular sieve producers to secure batch-to-batch consistency guarantees. FDA inhalation drug guidance has made direct manufacturer relationships non-negotiable for pharmaceutical-grade procurement in the United States.
- Distributors:Wholesale chemical distributors retain relevance in commodity zeolite sales to smaller detergent and water treatment operators lacking technical qualification capabilities.
- Online Retail:Laboratory-scale metal-organic framework samples and specialty silica gels move through digital channels serving research institutions.
- Wholesale:Bulk activated carbon for environmental remediation projects flows through regional wholesale networks.
Direct sales capture the majority of high-value contracts; distributor intermediaries are losing share fastest to manufacturer-direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for microporous materials concentrates in industrial clusters with integrated petrochemical infrastructure and stringent environmental enforcement, with procurement patterns diverging sharply between refinery-grade catalyst buyers and pharmaceutical-grade molecular sieve purchasers.
United States
Refinery operators in the Gulf Coast corridor drive zeolite catalyst consumption for heavy sour crude processing, with EPA VOC emissions standards expanding adsorbent procurement for solvent recovery systems. FDA guidance on inhalation drug products tightens qualification protocols for pharmaceutical-grade molecular sieves, consolidating procurement around direct manufacturer relationships in Kansas and Louisiana production zones.
Germany
Industrial air purification mandates under EU F-Gas Regulation accelerate demand for high-selectivity zeolite adsorbents in refrigerant recovery applications. ECHA's evolving REACH dossier requirements extend synthetic zeolite registration timelines, concentrating pharmaceutical-grade molecular sieve capacity in the Rhine-Ruhr chemical corridor where integrated producers manage precursor cost volatility.
China
GB standards on air quality monitoring equipment accelerate domestic production of synthetic zeolite sensors and calibration-grade molecular sieves. Dual carbon goals drive investment in metal-organic frameworks for post-combustion CO2 separation, with Yangtze River Delta chemical conglomerates capturing ligand chemistry expertise for hydrogen storage applications.
Japan
METI-backed hydrogen infrastructure programs channel R&D partnerships toward metal-organic frameworks with cryogenic stability for heavy transport fuel systems. Kansai region chemical producers collaborate with German conglomerates on modular ligand exchange protocols, accelerating prototype iteration for high-density hydrogen carriers.
India
CDSCO's tightening bioequivalence protocols for inhaled generics open demand for pharmaceutical-grade zeolites in pulmonary drug delivery devices. Gujarat and Maharashtra pharmaceutical clusters bypass distributors to secure carbon molecular sieve contracts with guaranteed purity certification, mirroring direct-to-device procurement patterns emerging in developed markets.
Microporous Materials Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated chemical conglomerates defend feedstock positions against specialty material challengers. The vendor base stratifies between petrochemical-backed zeolite producers with captive bauxite refining and emerging metal-organic framework specialists dependent on external ligand supply. Three archetypes occupy distinct competitive terrain: integrated petrochemical conglomerates controlling precursor costs, dedicated catalyst manufacturers anchoring regional supply security, and materials science innovators commercializing designer pore architectures. M&A activity concentrates on precursor asset acquisition, while technology licensing agreements proliferate for refinery-grade molecular sieve unit deployment.
Within the integrated conglomerate tier, BASF SE and Honeywell International Inc. exemplify scale-driven positions anchored by petrochemical feedstock control and global licensing networks respectively. Zeolyst International occupies a specialist position as a dedicated North American catalyst manufacturer. These three entities represent the structural concentration in synthetic zeolite supply, with their geographic footprints and business model differentiation shaping procurement options for refinery operators and pharmaceutical device manufacturers seeking batch-to-batch consistency guarantees.
| Leading Market Players |
|---|
| BASF SE |
| Axens |
| Zeolyst International |
| Solvay |
| AGC Chemicals |
| Kuraray Co., Ltd. |
| Cabot Corporation |
| Honeywell International Inc. (UOP) |
| Arkema |
| Others |
Supply & Pricing Matrix
Crystallization reactor engineering talent clustering in Germany's Rhine-Ruhr corridor and Japan's Kansai region feeds directly into labor-cost spreads between premium MOF synthesis and commodity zeolite production tiers.
Pricing Analysis
Warranty and technical service bundling separates pharmaceutical-grade molecular sieve contracts from unbundled commodity zeolite sales to detergent builders. Three-tier pricing structure across pharmaceutical-certified, industrial-grade, and economy detergent-builder levels tracks FDA/EMA certification status and batch-to-batch consistency guarantees. Cost compression in industrial zeolites intensifies as bauxite precursor volatility squeezes non-integrated producers. Detergent manufacturers exhibit highest price sensitivity; medical device OEMs prioritize certification over unit cost.
Supply Chain Analysis
Direct-to-refinery channels handle Gulf Coast petrochemical demand while distributor networks serve smaller water treatment operators. Supply concentrates in Germany, the United States, and China, with precursor refining anchored near bauxite processing hubs. Synthetic zeolite production draws from aluminosilicate precursors, organic ligands for MOFs, and petrochemical feedstocks. Single-source vulnerability in pharmaceutical-grade molecular sieves concentrates capacity in Germany and the Netherlands. Distribution runs through long-term supply agreements with embedded technical service for catalyst buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive bauxite refining and ligand chemistry capabilities determine margin capture across synthetic zeolite and MOF production tiers.
For Market Incumbents: Extend precursor control through backward integration into bauxite refining positions or captive ligand synthesis capacity. BASF SE and Honeywell UOP demonstrate how integrated feedstock positions defend against aluminosilicate cost volatility. Add pharmaceutical-grade certification capacity in Kansas or Louisiana production zones to capture FDA inhalation drug guidance demand. Channel control through direct manufacturer relationships marginalizes distributor intermediaries.
For New Entrants and Emerging Players: Capture CDSCO bioequivalence protocol demand in India's Gujarat and Maharashtra pharmaceutical clusters for pulmonary drug delivery zeolites. Hydrogen storage MOF supply to German and Japanese heavy transport developers offers penetrable white-space as METI-backed programs accelerate. Pursue direct-to-device supply contracts with medical oxygen concentrator manufacturers, bypassing wholesale networks entirely.
For Investors and Strategic Acquirers: Re-rating potential sits with MOF specialists possessing cryogenic stability IP given METI and EU hydrogen infrastructure commitments. Long-term viability favors crystallization reactor engineering capabilities and REACH-compliant formulation expertise. Watch ECHA dossier timeline compression as an inflection signal for synthetic zeolite registration cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Bauxite refining control insulates BASF SE from aluminosilicate cost volatility in synthetic zeolite production. |
| Pharmaceutical-Grade Certification Investment | FDA inhalation drug guidance makes batch-to-batch consistency guarantees mandatory for pulmonary device suppliers. |
| MOF Crystallization Reactor Scale-Up | Automated ligand exchange protocols modularize what was bespoke materials engineering into catalog-configurable products. |
| Direct-to-Device Supply Contracts | Medical oxygen concentrator manufacturers bypass distributors to secure carbon molecular sieve purity certification. |
| REACH Dossier Pre-Validation | ECHA's evolving requirements extend synthetic zeolite registration timelines, favoring producers with pre-validated compliance packages. |
Research Methodology
Multi-period observation of EPA VOC enforcement patterns, EMA bioequivalence protocol revisions, and METI hydrogen infrastructure commitments anchored the trend analysis, supplemented by interviews with refinery catalyst procurement managers, pharmaceutical device manufacturing directors, and MOF R&D leads. Secondary validation drew from ECHA REACH registration databases, FDA inhalation drug guidance documents, and customs trade data for aluminosilicate precursor flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
The input-output matrix framework mapped hydrothermal crystallization capacity, ligand chemistry expertise, and certification-grade production assets against refinery, pharmaceutical, and hydrogen storage demand clusters across the projection horizon. Segmentation dimensions included product type, application, end-user industry, and distribution channel. CAGRs derived from trend extrapolation of regulatory enforcement intensity and technology adoption curves. Forecast inputs incorporated EPA emissions standard tightening trajectories and CDSCO protocol implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA dossier evolution, bauxite supply disruption frequency, and MOF scale-up engineering bottlenecks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Europe Gas Barrier Membrane Market