
 Saudi Arabia PVC Pipes Market | 2026-2036
Saudi Arabia PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia PVC Pipes Market Intelligence
Municipal water distribution is hardening as the dominant demand vertical for PVC pipes in Saudi Arabia. SABIC leverages its petrochemical feedstock position to supply resin at scale to domestic extruders. SAPPCO anchors its market presence through specialized irrigation and plumbing product lines. National Pipe Company competes on large-diameter pressure pipe contracts for desalination and wastewater networks.
PVC pipes are thermoplastic conduit products manufactured from polyvinyl chloride resin compounded with stabilizers and plasticizers, extruded into hollow cylindrical profiles with standardized pressure ratings and dimensional tolerances for fluid conveyance and protective casing. Rigid PVC pipes dominate municipal and building applications where structural strength and chemical resistance are required, while flexible PVC pipes serve agricultural drip irrigation systems that demand bending radius adaptability in uneven terrain. PVC-O pipes represent the fastest-expanding product category due to their biaxial orientation process yielding higher tensile strength and hydraulic efficiency per unit weight.
SASO mandates conformity assessment for all plastic piping systems under its technical regulations, while the Saudi Building Code specifies material grades and jointing methods for pressure and non-pressure applications. MOHAP and the National Water Company influence procurement standards through infrastructure tender specifications that favor certified manufacturers. Stakeholders must monitor evolving green building mandates and recycled content thresholds that will reshape supplier qualification criteria and capital allocation decisions.
Market Dynamics
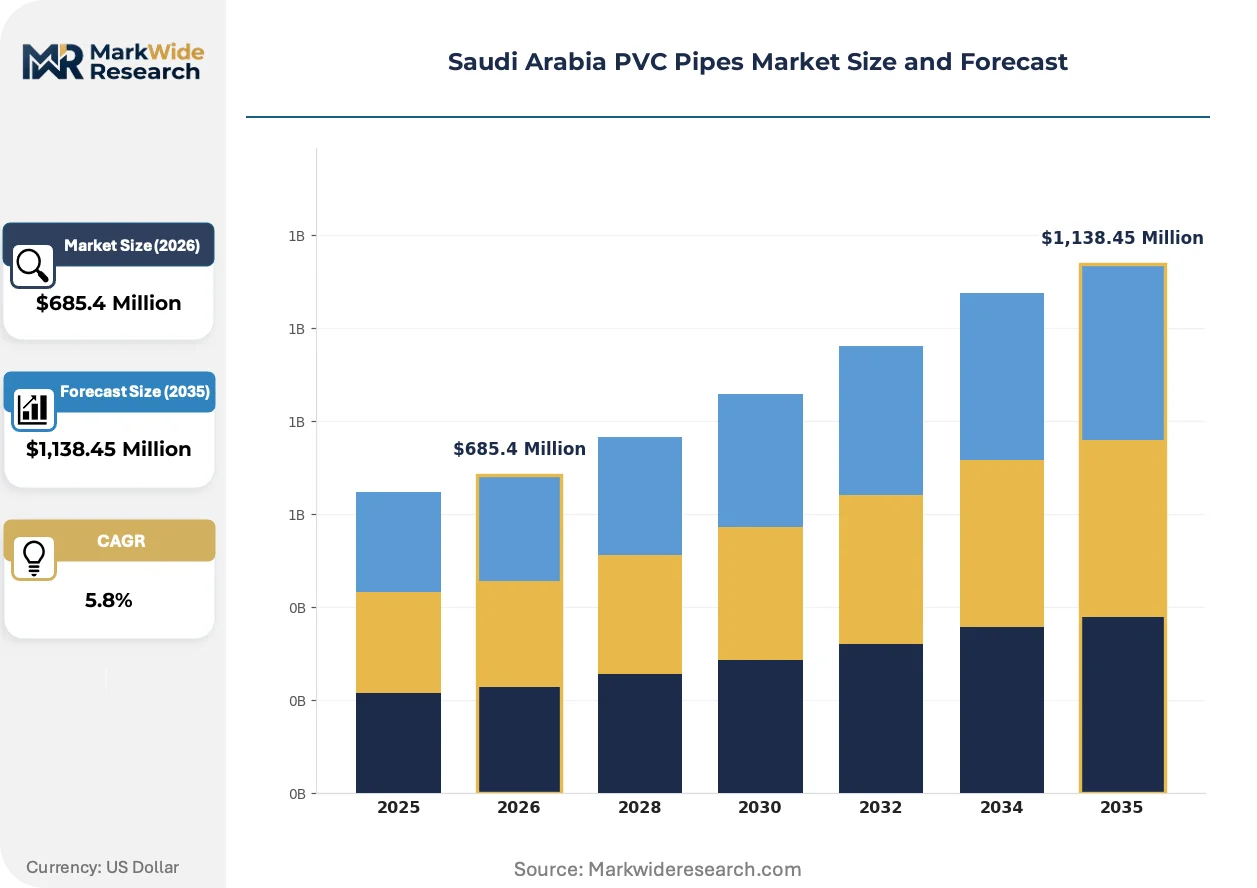
The Saudi Arabia PVC Pipes Market is experiencing a structural compression between petrochemical feedstock abundance and tightening material certification mandates under SASO technical regulations. This tension is reshaping supplier qualification criteria and procurement patterns across municipal and building sectors.
Growth Catalysts
- Desalination infrastructure expansion:National Water Company tenders for large-diameter pressure pipes are accelerating procurement volumes for seawater intake and brine discharge networks along the Eastern Province coastline.
- Saudi Building Code enforcement:Mandatory material grade specifications for pressure and non-pressure applications are standardizing quality thresholds and consolidating demand toward certified domestic manufacturers.
- Agricultural modernization:Drip irrigation system deployment in Qassim and Asir regions is driving flexible PVC pipe consumption for water-efficient crop management in uneven terrain.
Market Restraints
- Ethylene feedstock volatility:Crude oil price fluctuations directly impact PVC resin production economics at SABIC and other petrochemical complexes in Jubail Industrial City.
- Import dependency for specialty additives:Stabilizer and plasticizer supply concentrates in Asian manufacturing hubs, exposing extruders to shipping cost variability and lead time uncertainty.
- Thermal performance limitations:PVC's maximum service temperature of 60°C restricts deployment in high-temperature industrial process piping where metal alternatives dominate.
Strategic Opportunities
- Neom and Red Sea Project pipelines:Megaproject construction zones present concentrated demand for certified piping systems with accelerated delivery timelines and performance guarantees.
- Recycled content mandates:Anticipated green building regulations will create first-mover advantages for extruders developing post-consumer PVC reprocessing capabilities ahead of compliance deadlines.
- Smart infrastructure integration:Convergence of sensor-embedded leak detection systems with pressure-rated PVC-O distribution networks offers value-added differentiation in municipal tenders.
Industry Challenges
- Certification timeline compression:SASO conformity assessment procedures for new product variants require 4-6 month validation cycles that delay market entry for innovative pipe formulations.
- Specialized welding technician scarcity:Socket fusion and electrofusion jointing expertise for large-diameter pressure applications remains concentrated among experienced contractor crews in Riyadh and Dammam.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia PVC Pipes Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC Pipes, Flexible PVC Pipes, PVC-O Pipes, PVC-U Pipes Application: Irrigation, Drainage, Plumbing, Electrical Conduit End User: Construction, Agricultural, Industrial, Municipal Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | Saudi Basic Industries Corporation (SABIC), AL Watanya For Plastic Industry, Saudi Plastic Products Company Ltd. (SAPPCO), Fabco Plastic Factory Co. Ltd., National Pipe Company Ltd. (NPC), National Factory for Plastic Ind. (NFP), Saudi Arabian Amiantit Company, Saudi Industries for Pipe Co., New Products Industries Co Ltd. (Neproplast), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia PVC Pipes Market Strategic Shifts & Innovations
Material science advances and procurement digitization are compressing traditional specification cycles in the Saudi Arabia PVC Pipes Market. Three distinct vectors are reshaping competitive positioning and buyer-supplier relationships.
Bi-axially oriented PVC-O pipe manufacturing is unifying hydraulic efficiency with material economy through molecular chain alignment in two perpendicular directions. Municipal water authorities in Riyadh and Jeddah are specifying PVC-O for trunk mains where pressure ratings exceed 16 bar. This orientation process is unifying thinner wall designs with higher burst strength, reducing resin consumption per meter while extending service life projections.
SASO's updated technical regulation for plastic piping systems is mandating third-party laboratory testing for long-term hydrostatic strength and impact resistance. Extruders must maintain continuous production audits to retain conformity mark eligibility. Small-scale manufacturers in peripheral industrial zones face disproportionate compliance burden relative to integrated producers with captive testing facilities.
Consolidated procurement through the National Water Company's e-tendering platform is compressing supplier evaluation cycles and standardizing bid documentation requirements. Regional distributors in the Eastern Province are losing intermediation value as direct manufacturer-contractor relationships deepen. This channel compression is most visible in desalination plant expansion projects where single-source accountability reduces interface risk.
Saudi Arabia PVC Pipes Market Segmentation
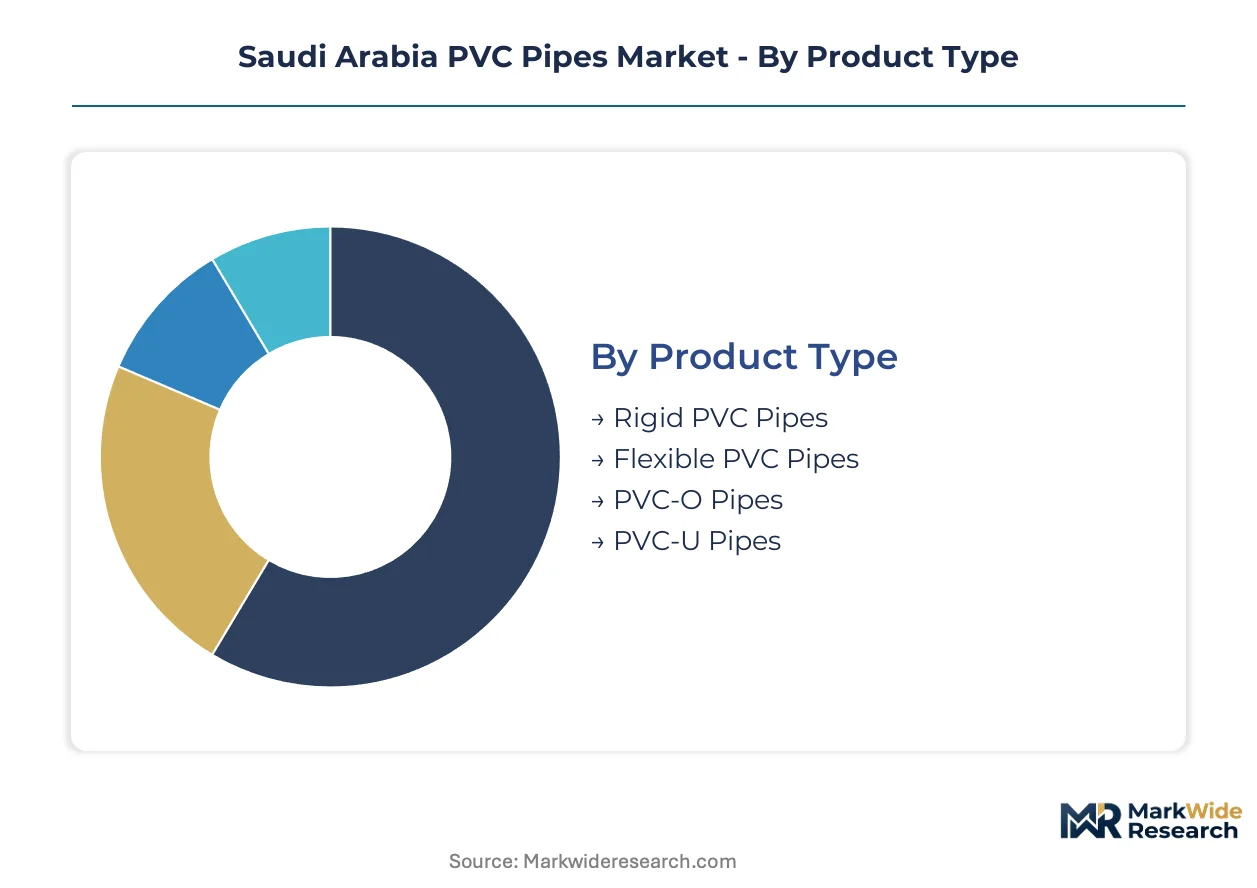
Saudi Arabia's PVC pipes market fragments across four distinct dimensions that shape procurement patterns and margin structures. Product type determines performance specifications for pressure ratings and installation methods. Application and end-user categories align with megaproject construction timelines and agricultural modernization programs. Distribution channel selection reflects project scale and certification requirements.
Product Type:
Volume concentrates in commodity-grade extrusions while premium tiers capture specification-intensive infrastructure contracts.
- Rigid PVC Pipes:Unplasticized formulations deliver structural rigidity and chemical resistance for buried municipal water mains and building drainage systems. Demand clusters in Riyadh and the Eastern Province where SASO-certified pressure ratings are mandatory for National Water Company tenders.
- PVC-O Pipes:Biaxial orientation aligns molecular chains perpendicular to flow direction, yielding 50% higher tensile strength than conventional grades. Municipal trunk main specifications in Jeddah and Dammam increasingly require PVC-O for its thinner wall profiles and extended hydraulic service life.
- Flexible PVC Pipes:Plasticized compounds enable tight bending radii for drip irrigation laterals in Qassim's center-pivot systems.
- PVC-U Pipes:Unplasticized formulations serve non-pressure drainage and electrical conduit applications in residential construction.
Today's leader: Rigid PVC Pipes. Tomorrow's challenger: PVC-O Pipes.
Application:
Specification intensity varies sharply between pressure-rated infrastructure and non-pressure building systems.
- Irrigation:Center-pivot and drip systems in Asir and Qassim regions consume flexible PVC for water-efficient crop management on uneven terrain.
- Drainage:Gravity-flow sanitary and stormwater networks require corrosion-resistant rigid formulations for buried service.
- Plumbing:Potable water distribution inside buildings demands SASO-certified lead-free stabilizer formulations meeting Saudi Building Code pressure specifications. Residential tower construction in Riyadh and Jeddah drives consistent procurement volumes for certified domestic extruders.
- Electrical Conduit:Flame-retardant rigid PVC protects low-voltage cabling in commercial and industrial installations across Jubail Industrial City.
Plumbing commands the largest revenue pool. Irrigation offers the steepest expansion trajectory.
End User:
Procurement scale and certification burden separate institutional buyers from fragmented agricultural purchasers.
- Construction:General contractors bundle pipe procurement with MEP packages for residential and commercial developments. Saudi Vision 2030 giga-projects in Neom and the Red Sea coast specify certified manufacturers with bonded inventory commitments.
- Agricultural:Farm cooperatives and individual operators purchase through distributor networks with seasonal demand peaks before planting cycles.
- Industrial:Process plants in Jubail and Yanbu specify chemical-resistant formulations for secondary containment and cooling water circuits.
- Municipal:National Water Company and regional municipalities tender large-diameter pressure pipe contracts with multi-year performance guarantees and SASO conformity mark requirements.
Construction absorbs the highest absolute volume. Municipal contracts deliver the most favorable payment terms.
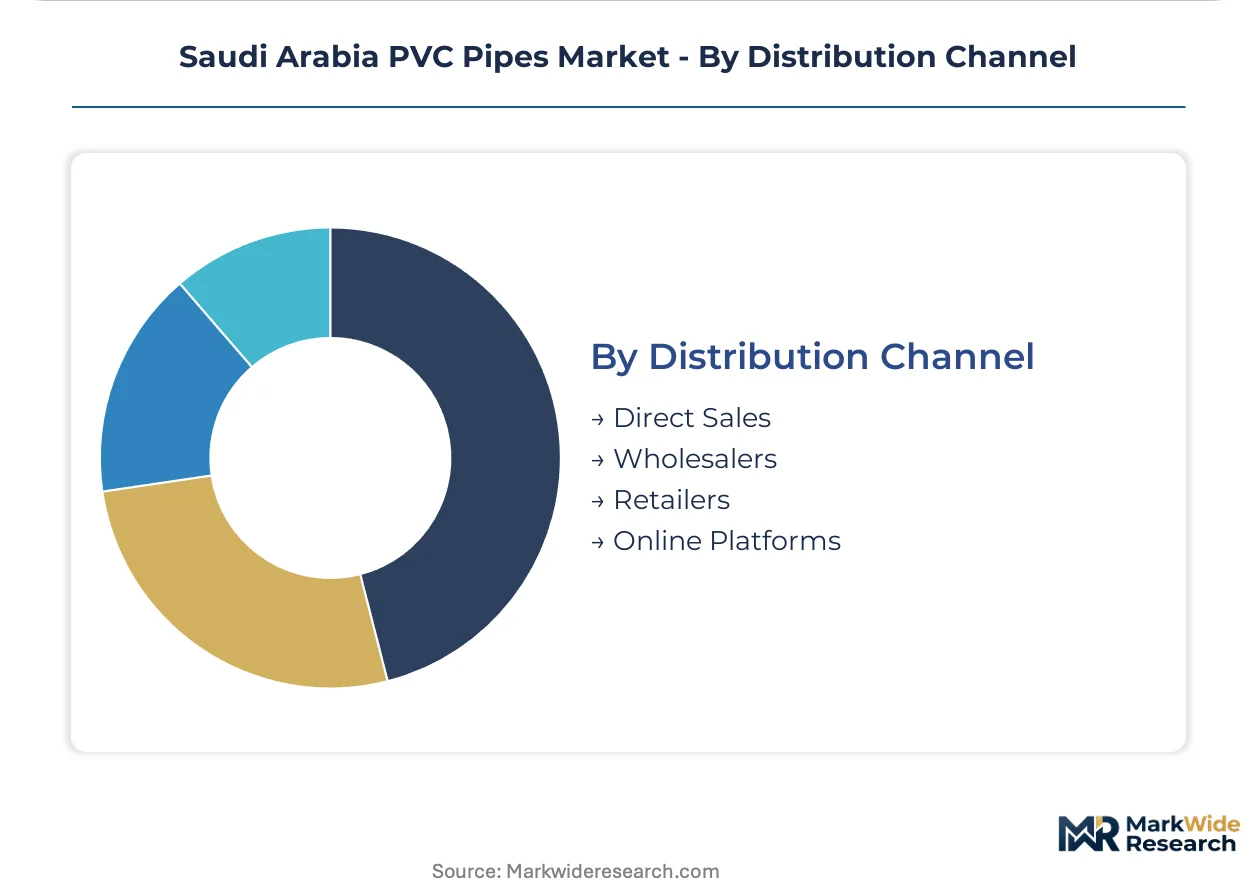
Distribution Channel:
Channel selection tracks project scale and the buyer's technical specification capability.
- Direct Sales:Manufacturers maintain dedicated account teams for National Water Company tenders and giga-project EPC contractors. Direct relationships reduce interface risk on desalination plant expansions where single-source accountability is mandatory.
- Wholesalers:Regional distributors in Dammam and Riyadh aggregate demand from smaller contractors and maintain SASO-certified inventory buffers.
- Retailers:Hardware chains serve residential plumbing repair and small-scale agricultural replacement demand.
- Online Platforms:Emerging digital procurement channels target standardized commodity grades with transparent pricing for contractor convenience.
Direct Sales dominates infrastructure value. Wholesalers retain agricultural and mid-market construction access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is concentrating PVC pipe manufacturing in Saudi Arabia's integrated petrochemical zones, where SABIC's captive resin supply and streamlined SASO certification pathways offset regulatory burdens faced by importers.
Riyadh
Residential tower construction and National Water Company trunk main replacements dominate procurement volumes. SASO's building code enforcement mandates certified lead-free stabilizer formulations for all potable water applications. The Riyadh-based extrusion cluster serves central Saudi Arabia with bonded inventory commitments for Vision 2030 giga-projects.
Eastern Province
Desalination plant expansions along the Arabian Gulf coastline accelerate large-diameter pressure pipe demand for seawater intake and brine discharge networks. Jubail Industrial City's petrochemical complexes supply resin feedstock to adjacent extrusion facilities. Dammam anchors distribution logistics for municipal tenders requiring multi-year performance guarantees.
Western Region
Jeddah's commercial construction pipeline and religious tourism infrastructure sustain consistent plumbing-grade PVC consumption. The Saudi Building Code's material grade specifications for high-rise buildings consolidate demand toward domestic certified manufacturers. Red Sea Project construction zones are specifying PVC-O trunk mains for their hydraulic efficiency.
Qassim
Center-pivot and drip irrigation modernization programs drive flexible PVC pipe consumption for water-efficient agriculture. Farm cooperative procurement concentrates through regional distributors with seasonal peaks before planting cycles. Buraidah's distribution hub aggregates demand from surrounding agricultural zones.
NEOM Northwest
The linear city's infrastructure buildout presents concentrated demand for certified piping systems with accelerated delivery timelines. Direct manufacturer-contractor relationships are displacing traditional distributor channels for single-source accountability. Specialized pressure-rated formulations are specified for the region's water reuse networks.
Saudi Arabia PVC Pipes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical producers commanding resin supply leverage while independent extruders compete on application-specific formulations. The vendor base concentrates around three archetypes: captive resin-integrated producers, specialized irrigation and plumbing fabricators, and large-diameter pressure pipe contractors. Capacity expansion and SASO certification upgrading represent the dominant competitive moves, as extruders invest in captive testing facilities to compress conformity assessment timelines.
Within the resin-integrated tier, Saudi Basic Industries Corporation anchors supply-side positioning through its Jubail petrochemical complex feedstock dominance. Specialized fabricators Saudi Plastic Products Company Ltd. and National Pipe Company Ltd. exemplify the certification-intensive infrastructure contracting segment, occupying positions where SASO conformity mark eligibility and bonded inventory capabilities determine tender eligibility. AL Watanya For Plastic Industry represents the independent extrusion archetype competing on agricultural and building application flexibility.
| Leading Market Players |
|---|
| Saudi Basic Industries Corporation (SABIC) |
| AL Watanya For Plastic Industry |
| Saudi Plastic Products Company Ltd. (SAPPCO) |
| Fabco Plastic Factory Co. Ltd. |
| National Pipe Company Ltd. (NPC) |
| National Factory for Plastic Ind. (NFP) |
| Saudi Arabian Amiantit Company |
| Saudi Industries for Pipe Co. |
| New Products Industries Co Ltd. (Neproplast) |
| Others |
Cost & Logistics Intelligence
National Water Company procurement concentration in Saudi Arabia enforces project-based long-term offtake pricing with volume-scaled discounts and SASO certification premiums. This buyer archetype's tender aggregation compresses distributor margins while rewarding bonded inventory commitments from certified domestic extruders.
Pricing Analysis
Distributor margins in the Eastern Province wholesale tier compress under direct manufacturer-contractor relationships for desalination plant contracts. Three-tier pricing structure across SASO-certified premium, standard-grade domestic, and uncertified import tiers separates municipal infrastructure from agricultural applications. Price differentiation hinges on hydrostatic pressure ratings and lead-free stabilizer compliance. Cost compression in the standard tier intensifies as SABIC resin supply fluctuations pass through to extruder quotations. Agricultural cooperatives in Qassim exhibit highest price sensitivity, while National Water Company tenders prioritize performance guarantees over unit cost.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Dammam and Riyadh regional centers to construction zones and agricultural hubs. Manufacturing concentrates in Saudi Arabia's Jubail Industrial City, with specialty additive sourcing from China and South Korea. Raw material dependencies encompass PVC resin from SABIC petrochemical complexes, calcium-zinc stabilizers, and plasticizer compounds. Single-source vulnerability concentrates in Asian stabilizer supply channels exposed to shipping cost variability. Distribution runs through manufacturer-direct channels for infrastructure projects and wholesaler networks for agricultural replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
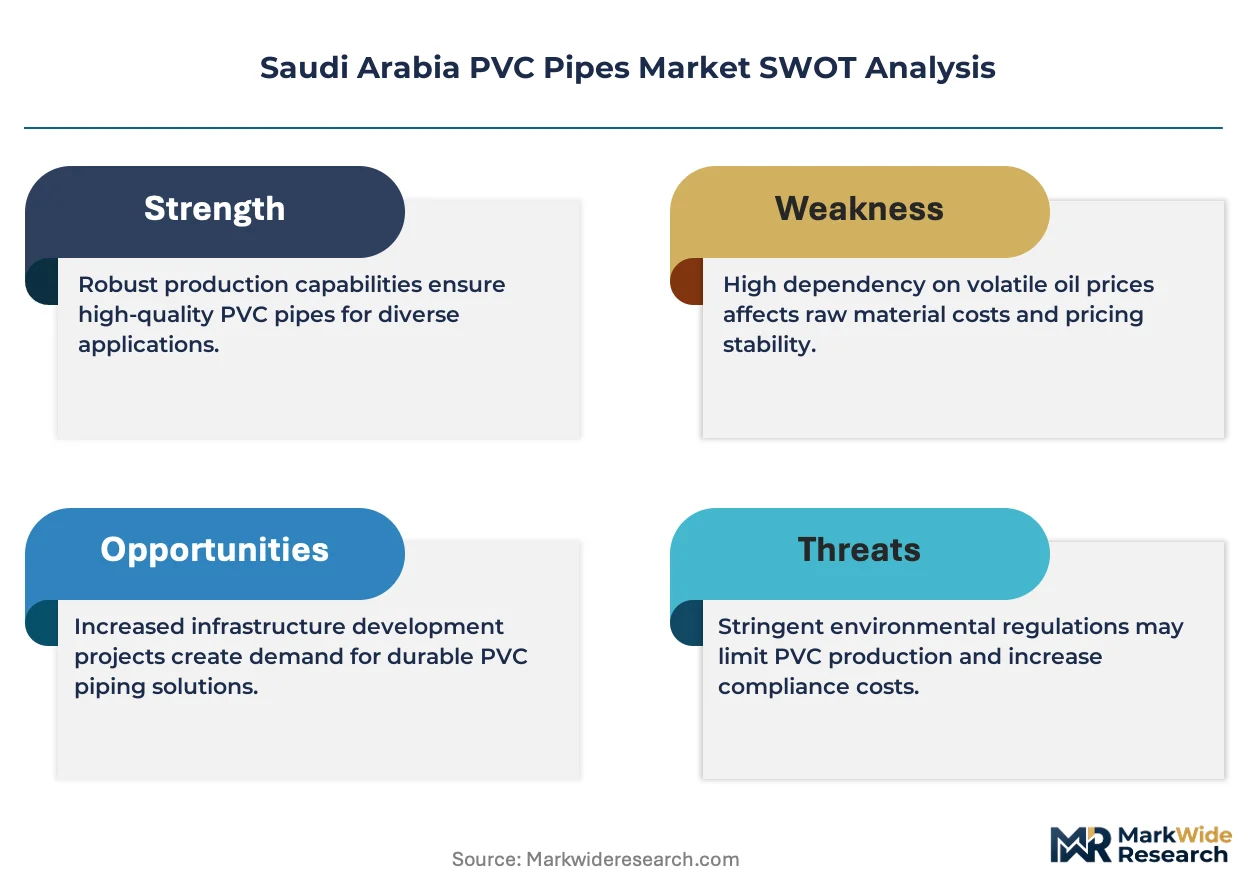
Saudi Arabia's PVC pipes market represents a late-cycle quality story as SASO certification mandates and green building regulations shift procurement toward premium-grade formulations with extended performance guarantees.
For Market Incumbents: Lock in certification moats by investing in captive SASO testing facilities that compress conformity assessment timelines for PVC-O product variants. Deepen upstream control over specialty additive inventories to buffer Asian supply chain volatility. Defend against import competition by securing bonded warehouse commitments for National Water Company trunk main tenders. For New Entrants and Emerging Players: Anticipated recycled content mandates in Saudi Arabia's green building regulations open a window for post-consumer PVC reprocessing capabilities ahead of compliance deadlines. Target agricultural drip irrigation segments in Asir and Qassim where distributor relationships remain penetrable. Pursue white-label manufacturing partnerships with established extruders lacking flexible pipe production lines. For Investors and Strategic Acquirers: Petrochemical conglomerates seeking downstream integration are the most active acquirer in this space, valuing SASO-certified extrusion assets for infrastructure market access. The long-term viability window favors targets with PVC-O manufacturing capabilities and municipal tender track records. Monitor National Water Company e-tendering platform participation rates as an inflection indicator for channel consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | SABIC feedstock proximity in Jubail Industrial City secures margin insulation against crude price volatility. |
| Captive SASO Testing Facility Investment | In-house hydrostatic strength validation compresses 4-6 month certification cycles for innovative pipe grades. |
| Post-Consumer PVC Reprocessing Buildout | Recycled content capabilities anticipate green building mandates and create first-mover qualification advantages. |
| Direct Manufacturer-Contractor Relationships | Single-source accountability for Neom and Red Sea Project pipelines displaces traditional distributor intermediation. |
| Sensor-Embedded Smart Pipe Development | Leak detection integration with PVC-O distribution networks differentiates municipal tender submissions in Riyadh and Jeddah. |
Research Approach
Bottom-up municipal and agricultural demand modeling reconciled against top-down petrochemical feedstock tracking forms the analytical core. Primary interviews with extrusion plant managers, National Water Company procurement officers, SASO certification auditors, and agricultural cooperative buyers combined with secondary validation from customs trade records, SASO technical regulation filings, and SABIC production disclosures. Triangulation across these sources anchored volume estimates and pricing tier differentials.
Historical trendline analysis of resin cost pass-through patterns and infrastructure tender award cycles informed projection frameworks. Segmentation modeling spanned product type, application, end-user category, and distribution channel dimensions across the projection horizon. CAGRs derived from weighted average of demand elasticity coefficients and megaproject construction timelines. Forecast inputs incorporated Saudi Vision 2030 giga-project pipeline announcements and anticipated recycled content regulatory thresholds.
Revisions become necessary when crude oil price volatility exceeds modeled bands, SASO certification procedures undergo procedural amendments, or green building mandate implementation timelines accelerate. Forecasts reflect documented assumptions regarding resin supply continuity and municipal infrastructure budget allocations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market