
 Global Membrane Water and Wastewater Treatment Market | 2026-2036
Global Membrane Water and Wastewater Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Membrane Water and Wastewater Treatment Market Foresight
A shortage of certified membrane process engineers is unwinding project timelines across the desalination and industrial reuse sectors. DuPont leverages its polymer science heritage to sustain leadership in high-rejection reverse osmosis chemistries. Hydranautics anchors its position through specialized seawater membrane manufacturing in Japan and California. Suez competes by extending service capabilities that bundle membrane replacement with digital monitoring.
Membrane water and wastewater treatment employs semi-permeable barriers with pore sizes ranging from 0.1 nanometers in reverse osmosis to 10 micrometers in microfiltration, fabricated from polyamide thin-film composites or ceramic alumina substrates to separate contaminants under applied pressure or electric potential. Reverse osmosis dominates value capture in desalination plants where energy recovery and boron rejection specifications determine project economics, while ultrafiltration leads growth in municipal water pre-treatment as utilities replace conventional coagulation-sedimentation trains. Modular unit configurations are gaining share among semiconductor fabricators seeking rapid capacity scaling without civil construction delays.
The EPA's Clean Water Act enforcement and China's MEE discharge standards for heavy metals are tightening effluent quality thresholds that membrane systems must achieve. ISO 9001 and NSF/ANSI 61 certifications function as mandatory gatekeepers for municipal procurement in North America and European water utilities. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance regulations reshape membrane material specifications and replacement cycles.
Market Dynamics
The zero-liquid-discharge mandate cascade from China's Ministry of Ecology and Environment is compressing project timelines and forcing membrane technology upgrades across heavy manufacturing clusters.
Growth Catalysts
- REACH chemical compliance:European manufacturers must eliminate legacy coagulation chemicals, accelerating thin-film composite membrane replacement cycles in Germany and France.
- Semiconductor fabs:Taiwan and South Korea chip manufacturers deploy modular ultrafiltration skids to bypass civil construction delays during capacity ramps.
- EPA Clean Water Act enforcement:Stricter effluent limits for boron and heavy metals in California and Texas desalination projects drive high-rejection reverse osmosis specifications.
Market Restraints
- Polyamide precursor concentration:Specialty aromatic polymer supply chains cluster in Japan and the US Gulf Coast, exposing membrane fabricators to single-source risk.
- Energy cost volatility:Reverse osmosis operations remain electricity-intensive; tariff fluctuations in Germany and industrial power pricing in China directly hit plant operating economics.
- PFAS material bans:Emerging restrictions on fluorinated compounds threaten incumbent membrane chemistries before replacement materials achieve equivalent rejection performance.
Strategic Opportunities
- India's industrial corridor expansion:Gujarat and Tamil Nadu textile clusters lack centralized treatment infrastructure, creating first-mover advantage for containerized membrane units.
- Digital twin integration:Predictive fouling models combining operational data with computational fluid dynamics reduce chemical cleaning frequency by half in Singapore desalination pilots.
- NSF/ANSI 61 certification gaps:Municipal utilities in the US Midwest face replacement backlogs where incumbent suppliers lack current certification, opening procurement windows.
Industry Challenges
- Certified process engineer scarcity:Desalination and industrial reuse projects stall as qualified membrane system designers remain concentrated in California, Spain, and Singapore.
- Legacy coagulation integration:Municipal utilities in the US Northeast struggle to sequence membrane installation without disrupting existing sedimentation basins serving combined sewer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
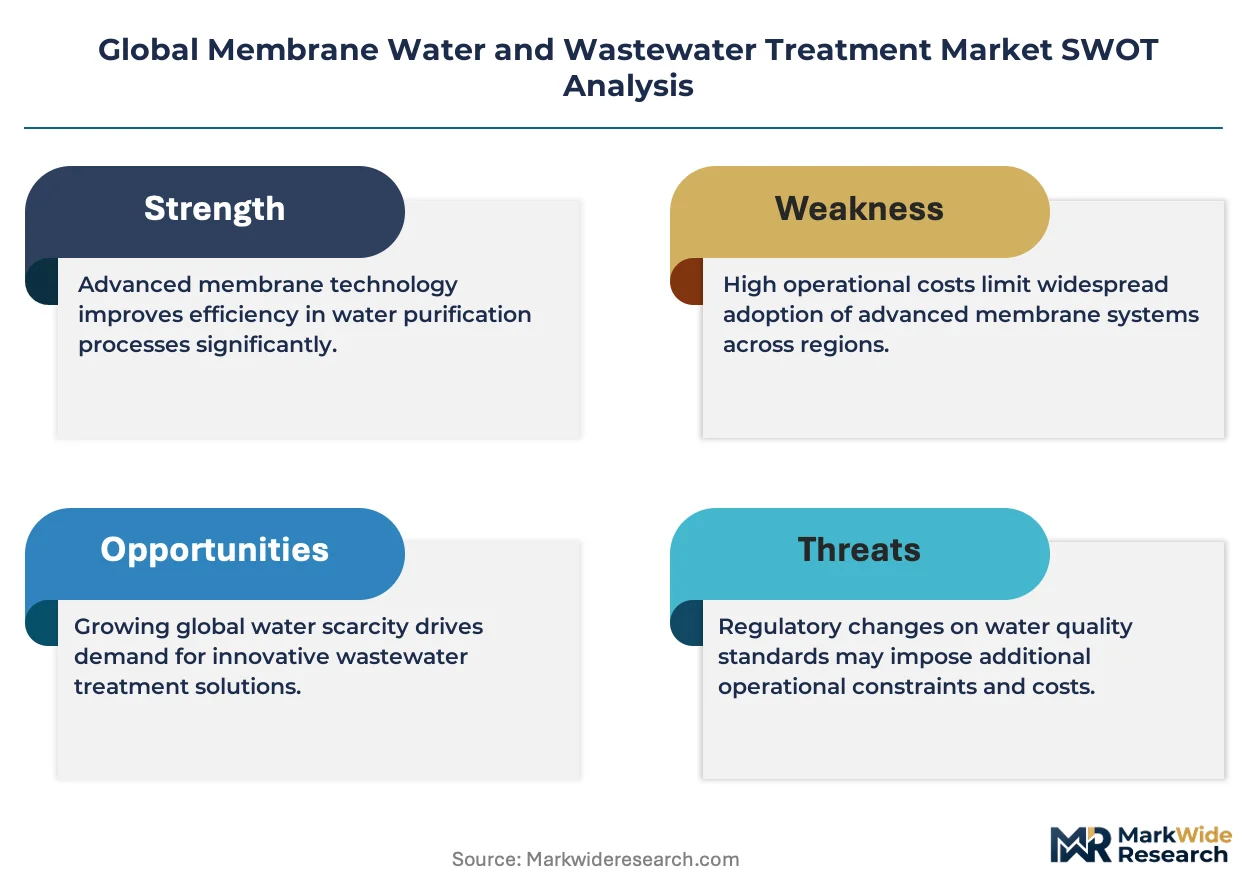
| Report Title | Global Membrane Water and Wastewater Treatment Market |
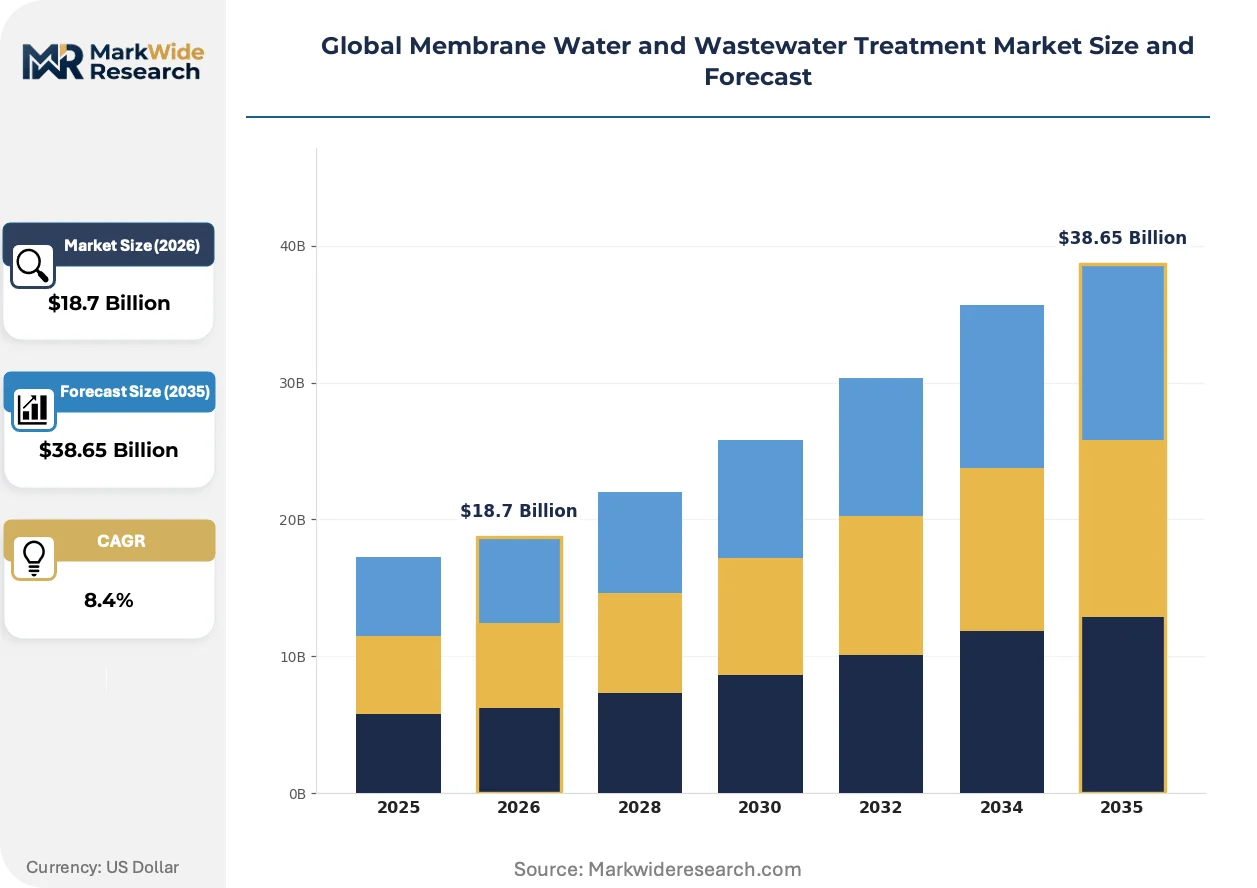
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Membrane Type: Reverse Osmosis, Ultrafiltration, Microfiltration, Nanofiltration, Electrodialysis Application: Municipal Water, Industrial Process Water, Agricultural Irrigation, Desalination Plants, Landfill Leachate End User: Water Utilities, Chemical Manufacturers, Food & Beverage Producers, Pulp & Paper Facilities, Semiconductor Fabricators System Configuration: Batch Systems, Continuous Flow, Modular Units, Compact Systems, Mobile Treatment Plants |
| Companies Covered | Veolia, DuPont, TORAY INDUSTRIES, INC., Hydranautics, Suez, Pall Corporation, Xylem, Evoqua Water Technologies, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Membrane Water and Wastewater Treatment Market Shifts & Advancements
Membrane technology is compressing footprint requirements while regulatory chemistry mandates and procurement model fragmentation reshape competitive positioning across water treatment verticals.
Forward osmosis draw-solute systems are miniaturizing brine concentration operations for offshore oil platforms and remote mining camps. Suncor and Rio Tinto deploy containerized units in Alberta and Western Australia to eliminate deep-well injection liabilities. The technology is miniaturizing what previously required multi-acre evaporative ponds into standard shipping footprints.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing membrane material reformulations across European industrial markets. German chemical manufacturers face 2025 compliance deadlines for process water systems. Ceramic alumina substrates gain share where polyamide thin-film composites face substitution pressure.
Performance-based service contracting is displacing capital purchase models among North American municipal utilities. Suez and Veolia bundle membrane replacement with guaranteed output quality in Ohio and Arizona. The shift transfers fouling risk to vendors while compressing procurement cycles from eighteen months to ninety days.
Global Membrane Water and Wastewater Treatment Market Segmentation
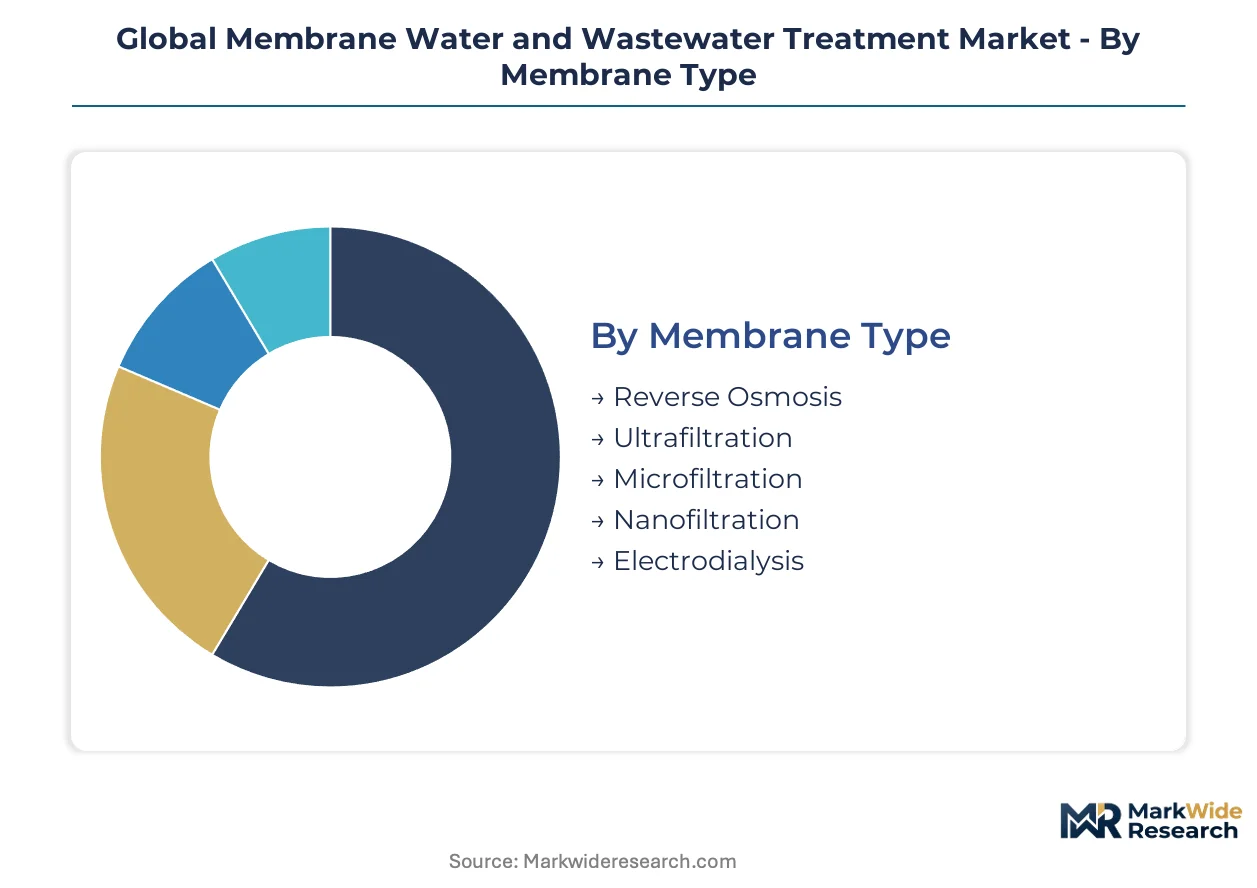
Membrane water and wastewater treatment technology fragments across multiple technical and commercial dimensions. Each segmentation axis reveals distinct margin architectures and deployment constraints that shape vendor strategy and procurement behavior.
Membrane Type:
Margin pools concentrate in high-rejection chemistries where energy recovery specifications and boron removal thresholds command premium positioning.
- Reverse Osmosis:Polyamide thin-film composite barriers operating at 0.1 nanometer pore scales dominate desalination economics. Saudi Arabia's Saline Water Conversion Corporation and Israel's national water utility anchor demand through megaproject specifications that prioritize energy recovery device integration.
- Ultrafiltration:Hollow-fiber configurations with 0.01 micrometer retention thresholds displace conventional coagulation-sedimentation trains in municipal pre-treatment. Singapore's Public Utilities Board and California's Orange County Water District drive specifications for low-fouling hydrophilic membrane surfaces.
- Microfiltration:Ceramic alumina or polymeric substrates at 0.1 micrometer cutoffs serve dairy pasteurization and brewery clarification where thermal tolerance matters.
- Nanofiltration:Divalent ion-selective layers target water softening and selective salt rejection in Florida's phosphate mining belt and textile dyehouse recovery loops.
- Electrodialysis:Ion-exchange membrane stacks concentrate brines for zero-liquid-discharge compliance in China's coal-to-chemical corridor and Chilean lithium extraction ponds.
Reverse Osmosis holds installed capacity across desalination basins. Ultrafiltration is rotating up the share rankings as municipal utilities accelerate membrane-based pre-treatment retrofits.
Application:
Volume concentration tracks regulatory enforcement intensity, with discharge limit stringency determining technology upgrade velocity by vertical.
- Municipal Water:Potable reuse schemes in California, Singapore, and Israel deploy multi-barrier membrane trains to meet drinking water quality standards. EPA Clean Water Act enforcement and WHO water reuse guidelines compress procurement timelines for advanced treatment expansion.
- Industrial Process Water:Zero-liquid-discharge mandates from China's Ministry of Ecology and Environment force membrane upgrades across steel, petrochemical, and electronics manufacturing clusters in Jiangsu and Guangdong provinces.
- Agricultural Irrigation:Brackish water desalination for greenhouse operations in Spain's Almería province and Israel's Negev desert relies on low-energy nanofiltration configurations.
- Desalination Plants:Seawater reverse osmosis dominates new capacity in Saudi Arabia, UAE, and Australia where energy recovery device efficiency determines project returns.
- Landfill Leachate:Membrane bioreactor and reverse osmosis combinations treat high-organic-strength effluent from municipal waste sites in Germany and the United Kingdom under strict landfill directive compliance.
Municipal Water commands the largest installed base. Industrial Process Water is expanding most quickly as manufacturing jurisdictions tighten discharge thresholds.
End User:
Customer type determines service model preferences, with asset ownership structures shaping whether vendors pursue capital equipment sales or performance-based contracting.
- Water Utilities:Municipal procurement in North America and Europe favors NSF/ANSI 61 certified membranes with guaranteed output quality contracts displacing traditional capital purchase models.
- Chemical Manufacturers:BASF and Dow facilities in Germany and the US Gulf Coast specify corrosion-resistant ceramic membranes for aggressive process streams under REACH chemical compliance deadlines.
- Food & Beverage Producers:Nestlé and Danone operations prioritize hygienic design membranes with CIP-automated cleaning protocols for dairy and beverage concentration applications.
- Pulp & Paper Facilities:Scandinavian and Brazilian mills deploy membrane bioreactors for bleach plant effluent closure and water loop recycling.
- Semiconductor Fabricators:TSMC and Samsung foundries in Taiwan and South Korea specify ultrapure water systems with sub-ppb total organic carbon requirements for wafer cleaning operations.
Water Utilities retain the deepest installed membrane base. Semiconductor Fabricators are climbing the fastest as chip capacity expansion drives ultrapure water infrastructure investment.
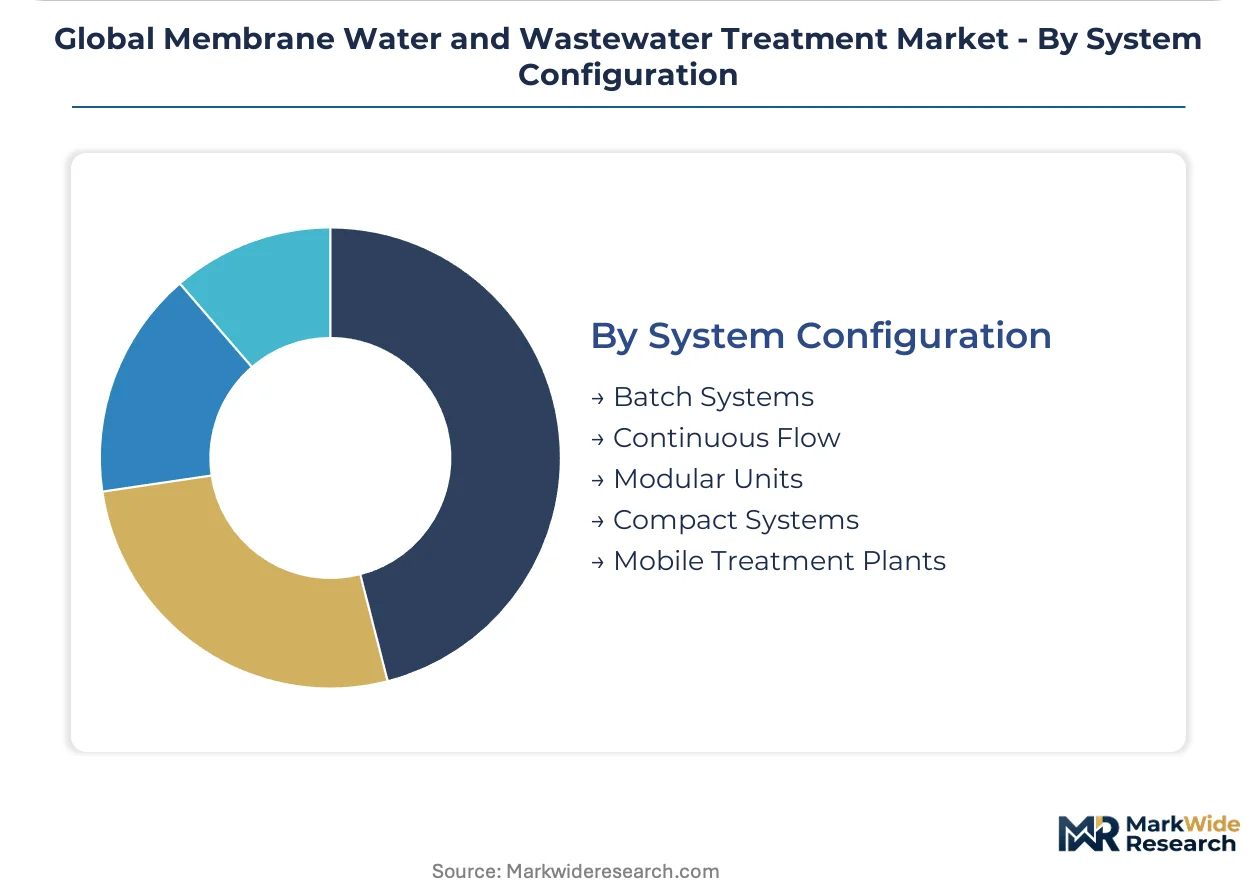
System Configuration:
Deployment flexibility requirements are fragmenting procurement patterns, with civil construction constraints and footprint limitations driving format selection.
- Batch Systems:Cyclic operation modes suit pharmaceutical water-for-injection production and laboratory-scale testing where flexibility trumps throughput.
- Continuous Flow:Steady-state operation dominates municipal and large industrial installations where membrane replacement scheduling integrates with maintenance windows.
- Modular Units:Containerized skids enable rapid capacity scaling for semiconductor fabricators in Taiwan and Arizona bypassing eighteen-month civil construction timelines.
- Compact Systems:Footprint-optimized configurations serve offshore oil platforms and remote mining camps in Western Australia and Alberta where space and logistics constraints apply.
- Mobile Treatment Plants:Trailer-mounted reverse osmosis units deploy for emergency response and temporary construction dewatering in disaster zones and infrastructure projects.
Continuous Flow retains dominant installed capacity. Modular Units are gaining share fastest as industrial end-users prioritize deployment velocity over permanent infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Saudi Arabia and Israel prioritize energy recovery in seawater desalination, while Germany and China focus on industrial zero-liquid-discharge compliance. The United States splits between municipal potable reuse in water-stressed states and semiconductor ultrapure water demand.
United States
California's Orange County Water District and Texas utilities drive municipal potable reuse membrane adoption. EPA Clean Water Act enforcement tightens boron and heavy metals discharge limits for desalination projects. Arizona semiconductor fabricators deploy modular ultrafiltration skids to bypass lengthy civil construction timelines.
China
Jiangsu and Guangdong industrial corridors face compressed project timelines under Ministry of Ecology and Environment zero-liquid-discharge mandates. GB standards for heavy metals discharge force membrane technology upgrades across steel and petrochemical clusters. Coal-to-chemical facilities in Ningxia deploy electrodialysis systems for brine concentration compliance.
Germany
Chemical manufacturers including BASF facilities face REACH Annex XVII compliance deadlines eliminating legacy coagulation chemicals. ECHA restrictions on per- and polyfluoroalkyl substances force membrane material reformulations by 2025. North Rhine-Westphalia's industrial water users accelerate ceramic alumina membrane substitution where polyamide composites face regulatory pressure.
Saudi Arabia
Saline Water Conversion Corporation megaprojects anchor global demand for high-rejection reverse osmosis with integrated energy recovery devices. The national water utility's specifications prioritize boron rejection thresholds that determine project economics. Red Sea coastal desalination plants concentrate demand for advanced membrane chemistries.
Singapore
Public Utilities Board drives specifications for low-fouling hydrophilic ultrafiltration surfaces in municipal pre-treatment. Digital twin integration pilots combining operational data with computational fluid dynamics reduce chemical cleaning frequency. The national water agency's NEWater advanced treatment expansion compresses procurement timelines for multi-barrier membrane trains.
Global Membrane Water and Wastewater Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive architecture. The upper tier combines polymer science heritage with global service networks, while specialists concentrate on seawater membrane manufacturing or digital monitoring bundling. Three archetypes define positioning: integrated chemical-materials players, specialized membrane fabricators, and service-forward water utilities. Consolidation pressure operates through technology licensing partnerships and geographic expansion into India's industrial corridor markets.
Among integrated chemical-materials players, DuPont leverages polymer science heritage to sustain positioning in high-rejection reverse osmosis chemistries. Hydranautics occupies a specialist fabricator role through concentrated seawater membrane manufacturing operations. Suez exemplifies the service-forward utility archetype by bundling membrane replacement with digital monitoring capabilities. These three anchors represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| Veolia |
| DuPont |
| TORAY INDUSTRIES, INC. |
| Hydranautics |
| Suez |
| Pall Corporation |
| Xylem |
| Evoqua Water Technologies |
| Alfa Laval |
| Others |
Supply & Pricing Matrix
Capacity utilization at Japanese polyamide thin-film composite plants runs above 85 percent, compressing margins for membrane fabricators unable to secure long-term offtake agreements while elevating price floors for high-rejection reverse osmosis chemistries. This scale concentration grants incumbent polymer science heritage players durable pricing power in desalination megaprojects where boron rejection specifications determine project economics.
Pricing Analysis
Long-term performance-based service contracts displace capital purchase models among North American municipal utilities, with Suez and Veolia bundling membrane replacement with guaranteed output quality. Pricing stratifies across premium certified tiers (NSF/ANSI 61, ISO 9001), standard industrial specifications, and economy unbranded alternatives where Indian textile clusters drive volume. Cost compression in the economy tier intensifies because Chinese fabricators are adding ceramic alumina capacity for zero-liquid-discharge compliance. Semiconductor fabricators in Taiwan and Arizona exhibit lowest price sensitivity given sub-ppb total organic carbon requirements, while Midwest municipal utilities facing replacement backlogs show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Strategic stockpiling of aromatic polymer precursors dominates procurement behavior among membrane fabricators exposed to Japan and US Gulf Coast supply concentration. Specialty polyamide feedstock draws from Mitsui Chemicals operations in Osaka and Huntsman facilities along the Texas coast, while ceramic alumina substrates source from German and Chinese refractory manufacturers. Single-source vulnerability concentrates in high-purity monomer supply chains where pharmaceutical-grade specifications limit qualified suppliers. Distribution runs through authorized service networks rather than direct OEM sales, with Hydranautics and DuPont maintaining captive technical service teams for membrane replacement scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified membrane process engineers remain concentrated in California, Spain, and Singapore, creating deployment bottlenecks that unwind project timelines across desalination and industrial reuse sectors. This talent scarcity elevates vendor capabilities in digital monitoring and remote technical support as competitive differentiators.
For Market Incumbents: Shield market position by deepening backward integration into polyamide precursor production to offset Japan and US Gulf Coast supply concentration, while accelerating NSF/ANSI 61 certification maintenance to exploit Midwest municipal replacement backlogs where incumbent suppliers have lapsed compliance. Ceramic alumina membrane R&D represents the priority defensive investment given REACH Annex XVII fluorinated compound restrictions threatening incumbent thin-film composite chemistries. For New Entrants and Emerging Players: NSF/ANSI 61 fast-track certification unlocks procurement windows among US Midwest water utilities where legacy suppliers lack current compliance, creating first-mover advantage in a segment historically sealed by incumbent relationships. Gujarat and Tamil Nadu textile clusters in India present penetrable white-space demand given absent centralized treatment infrastructure and zero-liquid-discharge mandate enforcement. Containerized membrane unit go-to-market positioning bypasses the certified engineer scarcity constraining permanent installation vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-forward water utilities bundling membrane replacement with digital monitoring, compressing procurement cycles from eighteen months to ninety days and transferring fouling risk from end-users to vendors. Long-term viability over the next decade favors acquisition targets combining ceramic alumina substrate capabilities with European regulatory compliance positioning ahead of 2025 REACH deadlines. The signal to monitor is Ministry of Ecology and Environment enforcement intensity across China's Jiangsu and Guangdong industrial corridors, where accelerated zero-liquid-discharge compliance timelines would trigger membrane upgrade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Precursors | Mitsui Chemicals and Huntsman supply concentration creates margin vulnerability for fabricators without captive monomer access. |
| Ceramic Alumina Capacity Expansion | REACH Annex XVII compliance deadlines in Germany force material substitution away from fluorinated thin-film composites. |
| Performance-Based Service Contracting | Suez and Veolia bundling models transfer fouling risk while compressing municipal procurement cycles dramatically. |
| NSF/ANSI 61 Certification Fast-Track | Midwest utility replacement backlogs open procurement windows where incumbent suppliers lack current compliance status. |
| Digital Twin Integration Development | Singapore Public Utilities Board pilots combining operational data with computational fluid dynamics halve chemical cleaning frequency. |
Research Methodology
Desk research of trade customs data, EPA enforcement records, and ECHA regulatory filings preceded structured interviews with membrane system design engineers, municipal procurement officers, semiconductor fab facilities managers, and ceramic substrate manufacturing heads. Primary fieldwork across California desalination projects, Singapore NEWater facilities, and Germany's North Rhine-Westphalia chemical corridor validated secondary intelligence on technology upgrade velocities. Bottom-up installation capacity estimates triangulated against top-down market value reconstructions derived from disclosed megaproject contract values.
Variance decomposition across membrane type, application vertical, end-user archetype, and system configuration dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints. Forecast inputs incorporated Ministry of Ecology and Environment enforcement intensity indices for China's industrial corridors and semiconductor fab capacity expansion timelines from Taiwan and South Korea.
Underlying assumptions cover sustained REACH chemical compliance deadlines, EPA Clean Water Act enforcement continuity, and polyamide precursor supply chain stability, with deviation risk concentrated in per- and polyfluoroalkyl substance regulatory acceleration or energy cost volatility in German and Chinese power markets. Revision becomes warranted when zero-liquid-discharge mandate enforcement intensity crosses thresholds that compress project timelines beyond current membrane fabrication lead times.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Oxygen Barrier Materials Market