
 Global Tubular Membranes Market | 2026-2036
Global Tubular Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tubular Membranes Market Intelligence
Predictive maintenance contracts, often bundled with remote monitoring services, is realigning the traditional transactional model for industrial filtration systems. Pentair leverages its extensive distribution network to offer integrated water treatment solutions for municipal and industrial clients. Kovalus Separation Solutions specializes in high-solids separation for challenging industrial waste streams, particularly in food and beverage. MICRODYN-NADIR differentiates through its broad portfolio of membrane chemistries and module designs.
Tubular membranes are filtration elements configured within a porous support tube, designed for cross-flow filtration of high-solids liquids. Their construction often utilizes robust materials like Polyvinylidene Fluoride (PVDF) to withstand harsh chemical cleaning and high pressures. While water treatment applications command the largest volume, the food & beverage processing segment offers significant margin potential. Multi-tube modules are standard for large-scale industrial plants due to their packing density and operational efficiency.
Regulations governing industrial effluent and water quality are critical demand drivers. The US EPA sets stringent limits on contaminants in drinking water, while the EU's REACH regulation controls chemicals used in membrane manufacturing. In China, national GB standards for water reuse push industries toward advanced filtration technologies. Future competitive advantage will hinge on developing membranes with higher flux, lower fouling propensity, and greater chemical resistance for emerging contaminant removal.
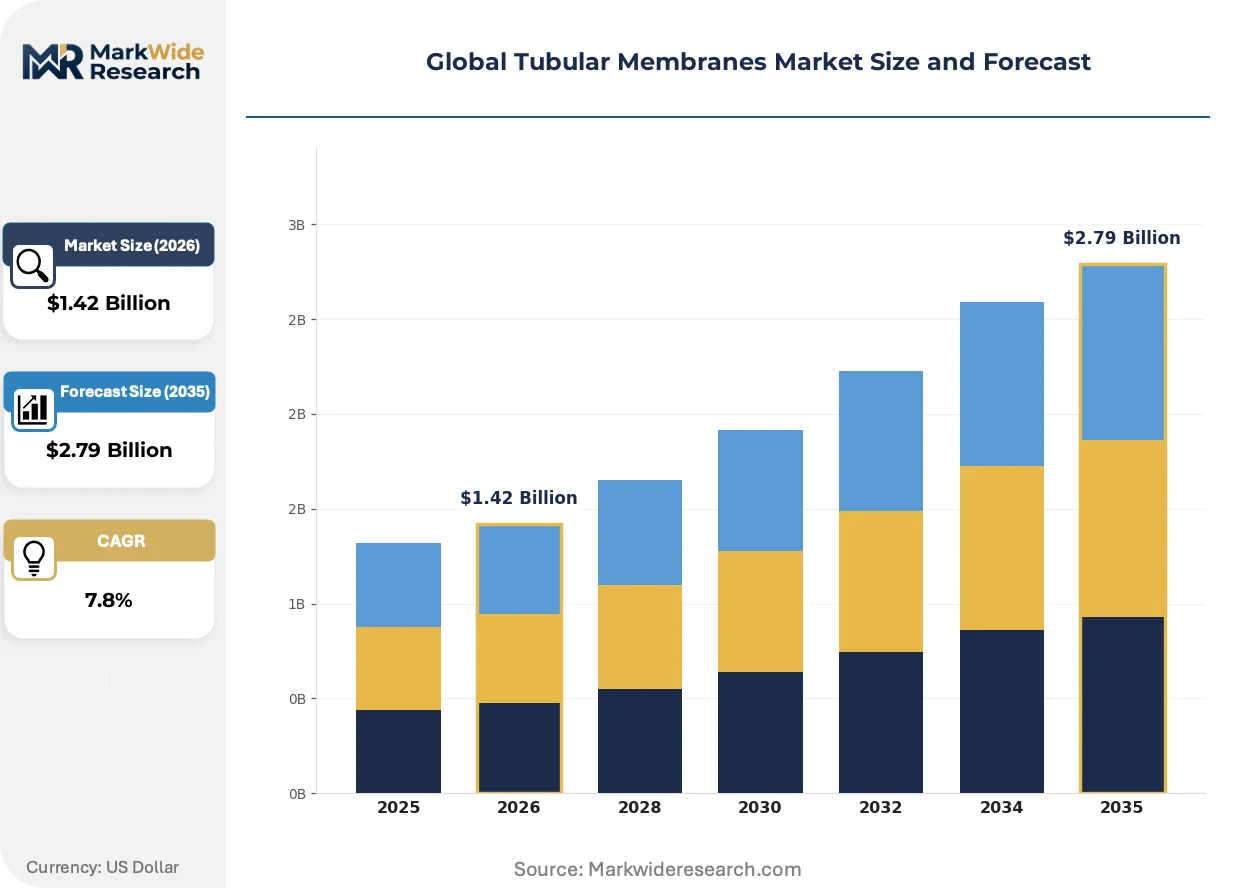
Market Dynamics
The market's central dynamic is the tension between high-volume, lower-margin municipal water treatment applications and the technically demanding, higher-margin opportunities in industrial sectors like food and beverage or chemical processing. This bifurcation shapes investment in R&D and go-to-market strategies for all participants.
Growth Catalysts
- Water Reuse Mandates:National policies, such as China's GB standards for water reuse, compel industrial parks and municipalities to invest in advanced filtration like tubular membranes to meet stringent quality targets for discharge and recycling.
- Food & Beverage Processing:The need for high-solids concentration in applications like juice clarification, dairy processing, and wine filtration provides a significant demand stream, valued for its ability to improve yield and product quality.
- Stringent Effluent Regulations:Directives like the EU's Urban Wastewater Treatment Directive and contaminant limits set by the US EPA are forcing utilities to upgrade from conventional treatment to more effective membrane-based systems.
Market Restraints
- High Capital Outlay:The significant upfront investment required for large-scale, multi-tube module installations can be a substantial barrier for smaller industrial facilities and municipalities with constrained budgets, delaying adoption.
- Polymer Price Volatility:The cost of essential membrane materials like Polyvinylidene Fluoride (PVDF) is subject to fluctuations in the petrochemical market, creating pricing uncertainty and margin pressure for manufacturers.
- Competition from Alternative Technologies:For wastewater streams with lower suspended solids, alternative filtration methods such as spiral-wound membranes or moving bed biofilm reactors can offer a more cost-effective solution, limiting the addressable market.
Strategic Opportunities
- Emerging Contaminant Removal:Developing membranes specifically designed to remove challenging micropollutants like PFAS and other endocrine disruptors from water sources opens a high-value market driven by new health advisories and regulations.
- Biopharmaceutical Applications:Targeting niche, high-purity applications in downstream bioprocessing, such as cell harvesting and protein concentration, represents an opportunity to enter a segment with less price sensitivity and high performance requirements.
- Industrial Growth in Southeast Asia:Rapid industrialization in countries including Vietnam and Thailand creates new demand for robust wastewater treatment solutions as local environmental enforcement strengthens, particularly in textiles and food processing.
Industry Challenges
- Membrane Fouling Mitigation:Managing and reducing membrane fouling in real-world, variable feedstock conditions remains a primary operational challenge for end-users, impacting flux rates, operational costs, and membrane lifespan.
- System Integration Complexity:Successfully integrating tubular membrane systems with a plant's existing automation and control architecture, like SCADA systems, demands specialized engineering expertise that can be a project bottleneck.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tubular Membranes Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyvinylidene Fluoride, Polyethersulfone, Cellulose Acetate, Polysulfone, Polyamide, Polypropylene Application: Water Treatment, Food & Beverage Processing, Pharmaceuticals, Chemical Processing, Pulp & Paper, Petrochemical Refining End User Industry: Municipal Water Authorities, Food Manufacturers, Pharma Companies, Chemical Plants, Paper Mills, Oil Refineries Module Type: Single-Tube, Multi-Tube, Hollow Fiber, Spiral Wound, Plate & Frame |
| Companies Covered | Kovalus Separation Solutions, Duraflow LLC, Pentair, Lenntech B.V., Dynatec Systems Inc., PCI Membranes, Porex, MICRODYN-NADIR, Berghof Membrane Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tubular Membranes Market Strategic Shifts & Innovations
Material science advancements and a pivot toward service-oriented business models are defining the next generation of tubular membrane systems. The focus is shifting from pure filtration performance to total cost of ownership, operational intelligence, and resilience against new environmental pressures.
Ceramic membranes, constructed from materials like alumina or silicon carbide, offer exceptional thermal stability and chemical resistance. Industries such as chemical processing and oil and gas are adopting these for treating aggressive waste streams under harsh conditions. The superior durability and extended operational life of ceramic modules is overtaking polymeric options in applications involving high temperatures or organic solvents.
The European Union's REACH regulation places strict controls on chemicals used in manufacturing, including those for membrane production. This is compelling manufacturers to innovate with greener solvents and alternative polymers, reducing the environmental footprint of their products. European producers are leading this shift, turning compliance into a competitive differentiator for market access in other regulated regions.
A notable shift from capital equipment sales toward service-based contracts is altering procurement patterns. Industrial customers increasingly favor agreements that bundle membrane supply with remote monitoring, maintenance, and performance guarantees for a fixed operational fee. This trend is most visible within the North American food and beverage sector, where it helps convert large capital investments into predictable operating expenses.
Global Tubular Membranes Market Segmentation
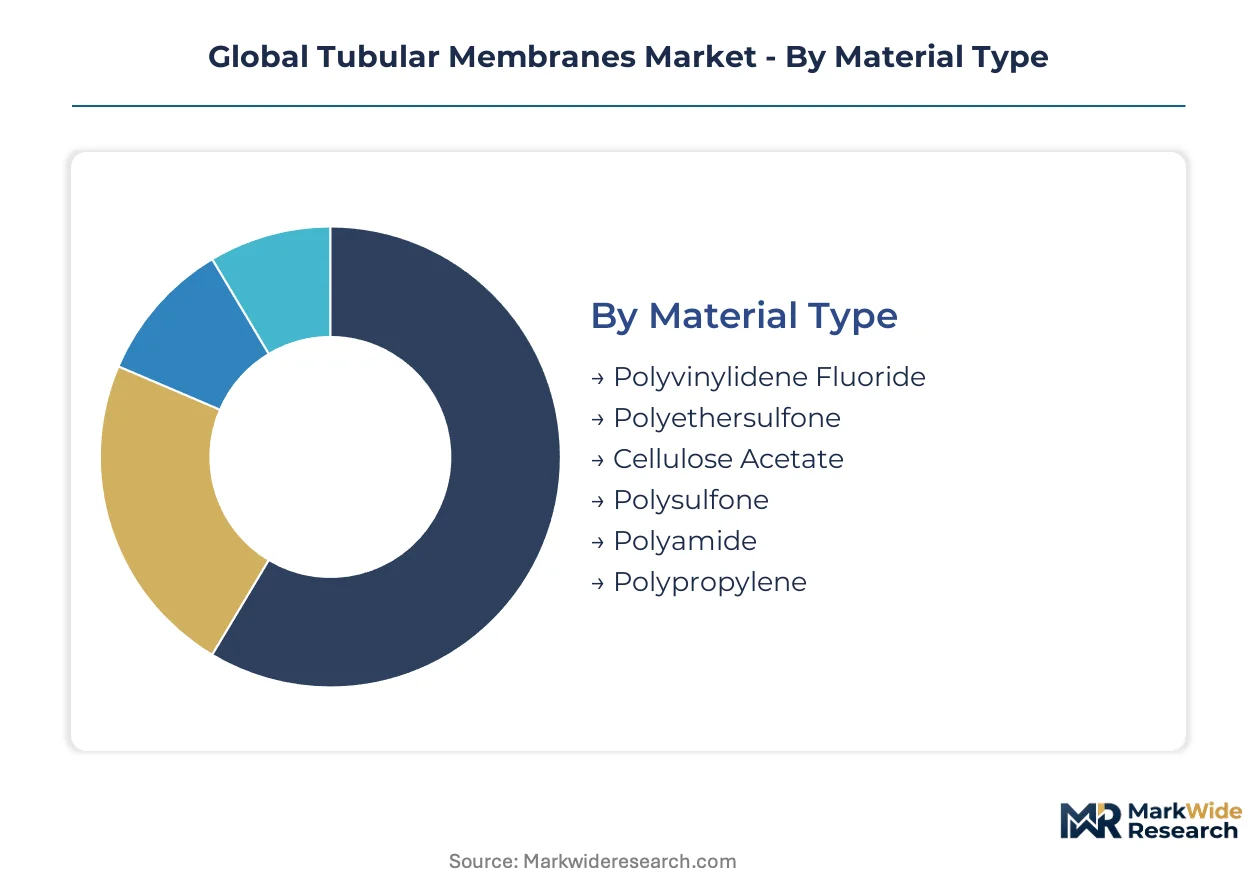
The segmentation analysis provides a granular view of the Global Tubular Membranes Market, dissecting its components to reveal underlying demand patterns and value drivers. Understanding these distinct segments is essential for identifying strategic growth areas and tailoring product development efforts. This detailed breakdown highlights where investment and innovation are most concentrated.
Material Type:
The material type segment showcases the tension between high-volume, cost-effective polymers and specialized, higher-performance options.
- Polyvinylidene Fluoride:This robust polymer offers excellent chemical resistance and mechanical strength, making it suitable for aggressive cleaning regimes and high-pressure applications. Demand concentrates in industrial wastewater treatment, where its durability withstands harsh operating conditions.
- Polyethersulfone:Known for its broad pH tolerance and good fouling resistance, polyethersulfone membranes are widely used in various filtration processes. Water treatment applications, particularly for municipal and industrial effluents, drive significant adoption due to its reliable performance.
- Cellulose Acetate:This material finds application in processes requiring good hydrophilicity and lower operating pressures, often in food and beverage clarification.
- Polysulfone:Polysulfone offers strong mechanical properties and thermal stability, serving a range of industrial separation tasks.
- Polyamide:Polyamide membranes are utilized for their chemical resistance and performance in specific solvent filtration scenarios.
- Polypropylene:Polypropylene is a cost-effective option for less demanding filtration, particularly in pre-treatment stages.
Today's leader: Polyvinylidene Fluoride. Tomorrow's challenger: Polyethersulfone.
Application:
Different applications for tubular membranes demonstrate a varied mix of volume requirements and technical specifications, impacting market value.
- Water Treatment:This application commands the largest volume due to stringent regulations and the need for high-turbidity water purification in municipal and industrial settings. Demand is particularly strong in China, driven by national water scarcity and reuse initiatives.
- Food & Beverage Processing:The food and beverage sector offers significant margin potential, utilizing tubular membranes for high-solids concentration, juice clarification, and dairy processing. This improves yield and product quality for manufacturers.
- Pharmaceuticals:Pharmaceutical applications require high purity and sterility for downstream bioprocessing and active ingredient separation.
- Chemical Processing:Chemical processing uses tubular membranes for aggressive waste streams and solvent recovery due to their robust construction.
- Pulp & Paper:The pulp and paper industry employs these membranes for wastewater treatment and process water recycling.
- Petrochemical Refining:Petrochemical refining utilizes tubular membranes for treating oily wastewater and separating valuable components.
Water Treatment applications hold the largest share, while Food & Beverage Processing exhibits the steepest expansion trajectory.
End User Industry:
The end-user industry segment reveals distinct procurement patterns and operational demands for tubular membrane systems.
- Municipal Water Authorities:These entities are major purchasers, driven by public health mandates and directives like the EU's Urban Wastewater Treatment Directive. They require reliable, high-volume systems for municipal water and wastewater purification.
- Food Manufacturers:Food manufacturers invest in tubular membranes to enhance product quality, concentrate ingredients, and manage process wastewater effectively. This segment values systems that improve operational efficiency and meet hygiene standards.
- Pharma Companies:Pharma companies demand high-purity filtration solutions for drug manufacturing and bioprocessing applications.
- Chemical Plants:Chemical plants deploy robust membrane systems for effluent treatment and resource recovery from complex waste streams.
- Paper Mills:Paper mills use tubular membranes for water reuse and reducing discharge volumes, aligning with environmental regulations.
- Oil Refineries:Oil refineries utilize these systems for treating produced water and managing process wastewater.
Municipal Water Authorities represent the primary volume driver, with Food Manufacturers increasingly adopting advanced solutions.
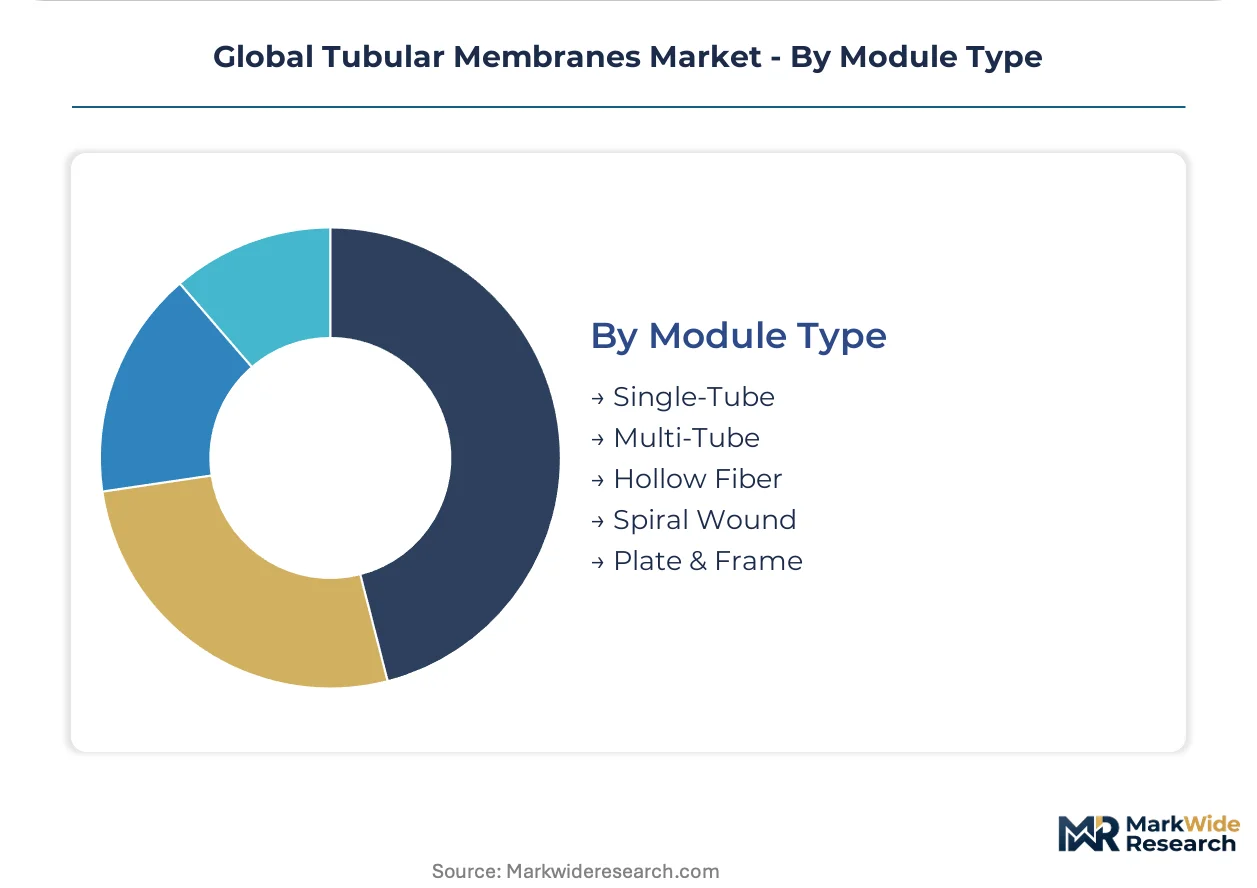
Module Type:
Module types illustrate the engineering solutions designed to optimize packing density, operational efficiency, and scalability for diverse filtration needs.
- Multi-Tube:Multi-tube modules are standard for large-scale industrial plants, offering high packing density and operational efficiency for high-volume applications. Their design facilitates easy cleaning and robust performance in challenging environments.
- Single-Tube:Single-tube modules provide flexibility for smaller-scale operations or specific applications requiring precise control and easier maintenance. They are often favored for pilot plants or specialized process streams.
- Hollow Fiber:Hollow fiber modules offer a high surface area to volume ratio, suitable for various filtration tasks including water purification.
- Spiral Wound:Spiral wound membranes are widely used for reverse osmosis and nanofiltration, offering compact design for lower suspended solids applications.
- Plate & Frame:Plate and frame modules are employed in applications requiring easy access for cleaning and handling of high-solids suspensions.
Multi-Tube modules dominate large-scale installations, while Single-Tube configurations offer flexibility for specialized uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's aggressive water reuse mandates drive significant demand for tubular membranes, the United States focuses on upgrading municipal infrastructure to meet stringent drinking water quality standards. These distinct national priorities shape investment patterns and technology adoption across different regions. Other industrialized and emerging economies also present unique market characteristics.
China
China's industrial expansion and severe water scarcity drive strong demand for tubular membranes in wastewater treatment. National GB standards for water reuse compel industries to adopt advanced filtration systems. Industrial parks within the Yangtze River Delta region are significant implementers of these technologies to meet stringent discharge targets.
United States
The United States market is propelled by the need for robust municipal water treatment and adherence to industrial effluent limits. The US EPA's stringent contaminant limits for drinking water necessitate advanced filtration solutions. Municipalities in the Great Lakes region are actively investing in these systems for high-turbidity applications.
Germany
Germany exhibits demand for tubular membranes in high-value industrial processing and stringent environmental compliance. The EU's Urban Wastewater Treatment Directive compels utilities to upgrade filtration systems. Chemical processing clusters in Bavaria are early adopters of ceramic membranes for aggressive waste streams.
Vietnam
Vietnam's rapid industrialization generates demand for robust wastewater treatment solutions, particularly in textiles and food processing. Strengthening local environmental enforcement drives industries to invest in advanced filtration technologies. Manufacturing hubs near Ho Chi Minh City are implementing tubular membrane systems to manage industrial effluent.
India
India's expanding industrial base and focus on water quality improvement create a substantial market for tubular membranes. The Central Pollution Control Board (CPCB) mandates stricter industrial discharge norms, accelerating technology adoption. Industrial zones in Gujarat are increasingly deploying these systems for process water recycling.
Global Tubular Membranes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market demands and customer preferences. The market for tubular membranes exhibits a tiered structure, with established global players alongside niche technology providers. Strategic archetypes include integrated solution providers, material science innovators, and regional specialists focusing on specific industrial applications. Companies often pursue geographic expansion and portfolio diversification to capture new opportunities and enhance their competitive positioning.
Specialists in high-solids separation for challenging industrial waste streams, such as Kovalus Separation Solutions, exemplify a focus on niche, high-margin applications. Pentair, a global entity, represents an integrated water treatment solutions provider leveraging an extensive distribution network for municipal and industrial clients. MICRODYN-NADIR differentiates through a broad portfolio of membrane chemistries and module designs, sitting within the material science innovator archetype. These companies anchor different segments of the market based on their core competencies and strategic positioning.
| Leading Market Players |
|---|
| Kovalus Separation Solutions |
| Duraflow LLC |
| Pentair |
| Lenntech B.V. |
| Dynatec Systems Inc. |
| PCI Membranes |
| Porex |
| MICRODYN-NADIR |
| Berghof Membrane Technology GmbH |
| Others |
Cost & Logistics Intelligence
Specialized membrane manufacturing expertise in Germany creates a labor-cost differential, directly influencing the higher pricing tiers for ceramic and advanced polymeric tubular membranes. This cost structure differentiates European-produced systems from those sourced from lower-cost regions.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity polymeric tubular membranes, particularly PVDF. The dominant pricing model remains per-unit transactional, with long-term contracts common for large municipal projects. Price differentiation stems from membrane material quality grades and after-sales service bundles. Pricing softness reflects polymer price volatility, especially for PVDF, making Municipal Water Authorities the most price-sensitive buyers.
Supply Chain Analysis
Reverse logistics for tubular membranes often involves specialized cleaning and re-certification services, extending operational life and reducing waste. Supply chain concentration for polymeric membranes centers on China for PVDF and polypropylene, with Germany specializing in high-performance polymers and ceramics. The supply chain draws from key raw materials like PVDF, alumina, and silicon carbide. Commodity polymer price volatility represents a structural risk, while distribution runs through direct sales channels for large projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tubular membranes market presents a geographic-arbitrage play, as lower manufacturing costs in Southeast Asia contrast with stringent environmental compliance requirements in the European Union. This differential creates distinct opportunities for market participants.
For Market Incumbents: Lock in long-term service contracts with municipal authorities to secure predictable revenue streams against high capital outlay. Invest in R&D for advanced membrane materials that target emerging contaminants like PFAS, countering the threat from alternative filtration technologies. Deepen channel partnerships in rapidly industrializing regions like Southeast Asia.
For New Entrants and Emerging Players: Specialized engineering firms represent a key channel for market entry, particularly in industrial sectors. Target the food and beverage processing segment in Southeast Asia, which offers high-margin opportunities and less established competition. Offer outcome-based service models that convert capital expenditure into predictable operational expenses for smaller facilities.
For Investors and Strategic Acquirers: Integrated water treatment solution providers are the most active acquirers in this space, seeking to broaden technology portfolios. The market offers long-term viability for niche players specializing in challenging industrial waste streams or emerging contaminant removal. Target acquisition archetypes include material science innovators with patented membrane chemistries. The signal to watch is the introduction of new national or regional regulatory mandates for micropollutant removal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This move lowers production costs for polymeric membranes, enhancing price competitiveness in emerging markets. |
| R&D in PFAS-resistant Membranes | Developing new membrane chemistries addresses a critical environmental challenge, opening high-value market segments. |
| Long-term Service Contract Bundling | Offering comprehensive service agreements secures recurring revenue and strengthens customer loyalty for suppliers like Pentair. |
| Joint Ventures for Ceramic Membrane Production | Collaborations accelerate the adoption of durable ceramic membranes for aggressive industrial waste streams in Germany. |
| Digital Integration with SCADA Systems | Integrating membrane systems with plant automation improves operational efficiency and reduces manual intervention for end-users. |
Research Approach
Direct dialogue with plant managers, R&D directors, procurement leads, and environmental regulators provided primary market insights. This qualitative grounding was validated through secondary sources, including US EPA reports, EU Urban Wastewater Treatment Directives, China's national GB standards, and company filings. The analysis employed both bottom-up market sizing and top-down validation to ensure data integrity.
Volume and value forecasts were generated across the analysis window, segmented by material type, application, end-user industry, and module type. Regional adoption patterns were integrated into the model, with Compound Annual Growth Rates derived from historical trends and projected demand drivers. Industrialization rates and water scarcity indices served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving environmental regulations and polymer price fluctuations. Forecasts reflect documented assumptions regarding technology adoption and economic growth. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Polysulfone Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
SBS Modified Bitumen Membrane Market