
 Caustic Potash Market | 2026-2036
Caustic Potash Market Size, Share, and Industry Trends Forecast 2026-2036
Caustic Potash Market Intelligence
Food-grade and pharmaceutical-grade specification tiers is reorganizing competitive dynamics in caustic potash. Occidental Chemical Corporation leverages integrated chloralkali infrastructure across the US Gulf Coast to sustain cost-advantaged liquid production. Tata Chemicals anchors South Asian supply through dedicated flake and pellet lines serving agrochemical formulators. Evonik Industries differentiates via high-purity grades for European pharmaceutical and personal care markets.
Caustic potash, or potassium hydroxide (KOH), is an inorganic compound produced primarily through electrolysis of potassium chloride brine in membrane or mercury cells, yielding a strongly alkaline material with typical industrial concentrations of 45–50% liquid or 90% flake solid. Its primary industrial purpose centers on pH regulation, saponification in soap and detergent manufacturing, and as a reagent in potassium salt production across chemical synthesis. Liquid formulations dominate volume flows into chemical manufacturing and agriculture where bulk handling infrastructure exists, while flake and pellet grades command premium positioning in food processing and pharmaceuticals where dissolution control and storage stability determine procurement decisions. Granular formats occupy a narrowing mid-tier niche as end-users consolidate around liquid bulk for scale operations and pellets for precision dosing applications.
EPA effluent guidelines and OSHA process safety management requirements shape US manufacturing compliance costs for chloralkali producers, while REACH registration and the EU Green Deal carbon border adjustments constrain European import competitiveness and favor lower-carbon membrane cell output. India's BIS quality certification and CDSCO pharmaceutical-grade standards create dual compliance thresholds for suppliers targeting food processing and active pharmaceutical ingredient synthesis segments. Stakeholders must monitor regulatory divergence between EPA mercury cell phase-out timelines and developing economy enforcement capacity as this tension reshapes trade flows and regional sourcing strategies.
Market Dynamics
Membrane cell technology upgrades are compressing mercury-based production economics while FDA purity standards tighten pharmaceutical-grade specifications, forcing asset reconfiguration across chloralkali manufacturing bases.
Growth Catalysts
- Membrane cell adoption:EPA mercury cell phase-out timelines accelerate capital redeployment toward lower-energy electrolysis configurations. Food-grade certification expansion under FSSAI protocols opens processed food pH regulation applications.
- Potassium salt demand:Specialty fertilizer formulators in India drive captive consumption for chloride-free crop nutrient blends. CDSCO pharmaceutical-grade standards strengthen active ingredient synthesis requirements.
- REACH registration compliance:EU Green Deal carbon border adjustments favor lower-carbon membrane output, redirecting import flows toward certified low-emission supply sources.
Market Restraints
- Potassium chloride feedstock volatility:Mined KCl supply concentrates in Saskatchewan and Belarus, exposing margins to extraction cost swings and trade route disruptions.
- Mercury cell stranded assets:OSHA process safety management requirements compound compliance burdens for legacy installations facing accelerated retirement deadlines.
- Sodium hydroxide substitution:Caustic soda displaces KOH in non-critical pH adjustment applications where potassium ion presence lacks formulation value.
Strategic Opportunities
- Biopharma-grade expansion:EMA GMP certification for injectable-grade KOH creates premium positioning in European active pharmaceutical ingredient synthesis.
- Personal care formulation:Solid pellet formats penetrate cosmetic alkali applications where dissolution control and storage stability command price premiums.
- Renewable diesel catalysts:Biodiesel producers adopt KOH transesterification catalysts as renewable fuel mandates tighten under EU Green Deal implementation.
Industry Challenges
- Electrolyzer engineering scarcity:Specialized membrane cell design expertise concentrates among retired chloralkali engineering cohorts, constraining brownfield upgrade execution.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and CDSCO pharmaceutical-grade approvals extend product qualification cycles for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caustic Potash Market |
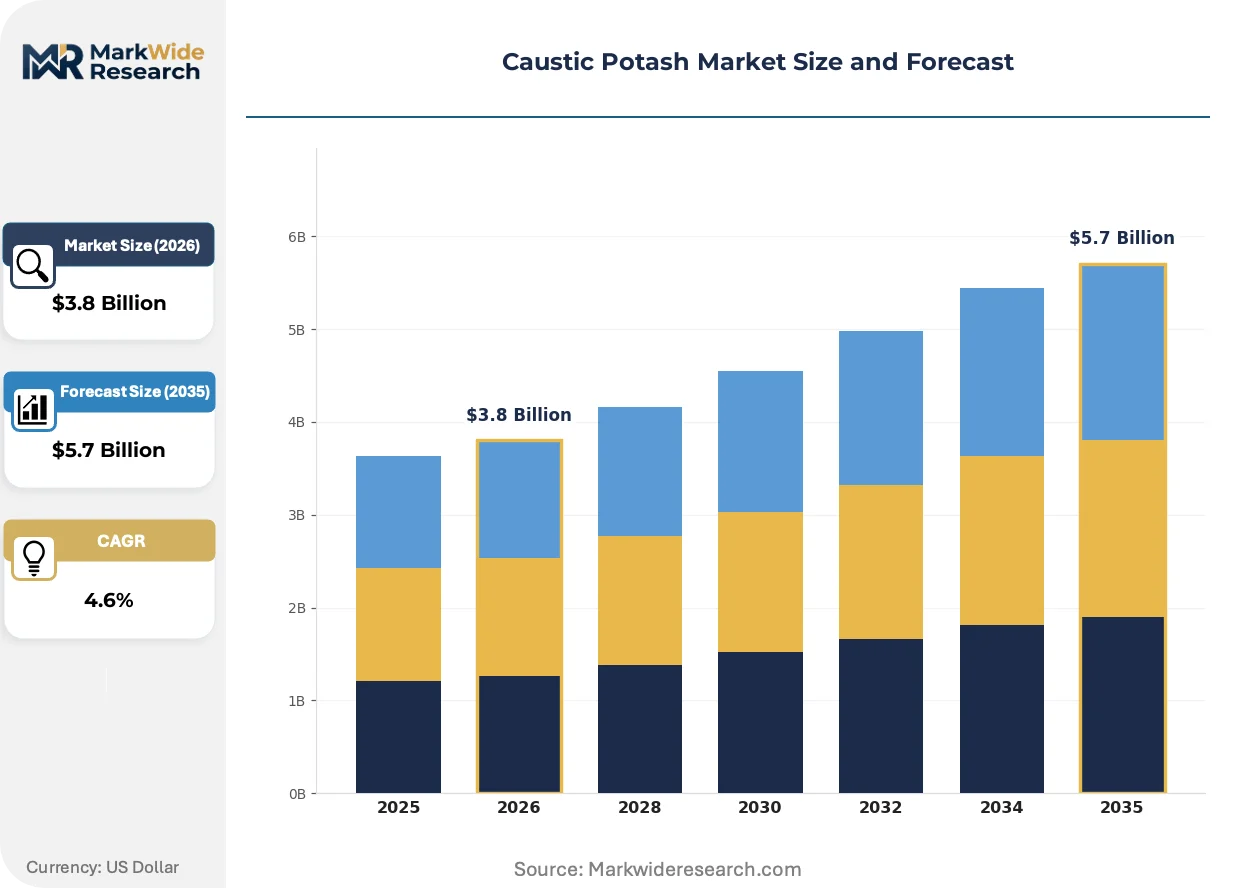
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Liquid, Granular, Pellets End Use Industry: Chemical Manufacturing, Agriculture, Pharmaceuticals, Food Processing Packaging Type: Bags, Drums, Totes, Bulk Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | The Mosaic Company, Evonik Industries, Occidental Chemical Corporation, Tata Chemicals, ICL Fertilizers, FMC Corporation, Olin Corporation, ERCO Worldwide, Tessenderlo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caustic Potash Market Strategic Shifts & Innovations
Electrolysis technology substitution, regulatory carbon accounting, and procurement consolidation are compressing legacy supply configurations while opening premium-grade positioning for certified low-carbon output.
Membrane cell electrolysis is displacing mercury-based chloralkali production across major manufacturing bases. Pharmaceutical manufacturers and food processors are adopting membrane-derived KOH to meet tightening purity specifications and carbon disclosure requirements. This technology shift is enabling facility consolidation and compressing the viable supplier base to integrated chloralkali operators with capital resources for membrane upgrades.
REACH registration and EU Green Deal carbon border adjustments are constraining European import competitiveness. The carbon intensity differential between membrane and mercury cell output now factors into procurement decisions under Scope 3 emission accounting protocols. Pharmaceutical and personal care formulators in Germany and France are prioritizing certified low-carbon supply sources, redirecting trade flows toward membrane-equipped production clusters.
Buyer concentration among agrochemical formulators and pharmaceutical manufacturers is compressing spot market liquidity. Large-scale consumers are negotiating direct supply agreements with integrated producers, bypassing traditional distributor channels for liquid bulk deliveries. This procurement consolidation is most visible in India, where Tata Chemicals and regional fertilizer cooperatives are securing captive caustic potash volumes through dedicated offtake contracts.
Caustic Potash Market Segmentation
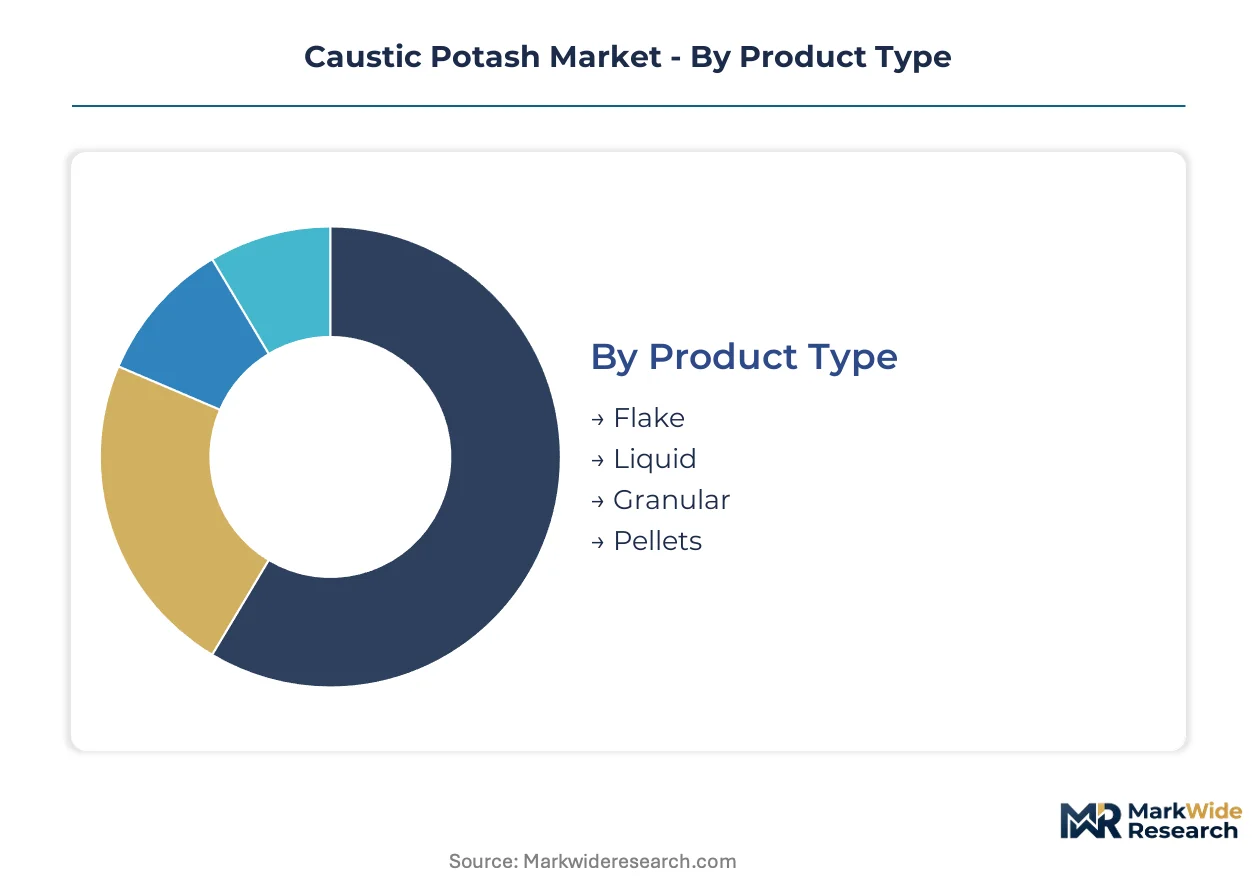
Caustic potash procurement patterns diverge sharply across physical forms and end-use specifications, with substitution pressures from caustic soda reshaping volume allocation. Segmentation clarity determines margin capture for producers navigating membrane cell upgrade cycles and pharmaceutical-grade certification requirements.
Product Type:
Liquid formulations face the most intense substitution threat from sodium hydroxide in bulk chemical applications, while solid grades defend position through dissolution control and storage stability premiums.
- Liquid:Aqueous solutions at 45–50% concentration dominate volume flows into chemical manufacturing and agriculture where bulk handling infrastructure exists. Demand concentrates in India where Tata Chemicals and regional fertilizer cooperatives expand captive consumption for specialty crop nutrients, though caustic soda displacement pressures intensify in non-critical pH adjustment.
- Flake:Solid formulations at 90% purity command premium positioning in food processing and pharmaceutical synthesis where dissolution control determines procurement decisions. FDA purity standards tighten active ingredient synthesis requirements, compressing mercury-derived supply and favoring membrane cell output for certified applications.
- Granular:Intermediate particle size occupies a narrowing mid-tier niche as end-users consolidate around liquid bulk for scale operations and pellets for precision dosing.
- Pellets:Dense spherical format penetrates cosmetic alkali and precision agriculture applications where metering accuracy and storage stability justify price premiums over flake alternatives.
Liquid anchors the volume base while pellets gain share at the steepest rate through personal care formulation expansion.
End Use Industry:
Cost tier stratification separates commodity chemical applications from certified pharmaceutical and food-grade segments where compliance burden creates pricing power.
- Chemical Manufacturing:Potassium salt production and pH regulation drive baseline consumption across industrial synthesis operations. Membrane cell technology upgrades displace mercury-based chloralkali production across major manufacturing bases, reshaping supplier economics.
- Agriculture:Specialty fertilizer formulators in India drive captive consumption for chloride-free crop nutrient blends. CDSCO pharmaceutical-grade standards create dual compliance thresholds for suppliers targeting active ingredient synthesis segments.
- Pharmaceuticals:EMA GMP certification for injectable-grade KOH creates premium positioning in European active pharmaceutical ingredient synthesis. REACH registration and EU Green Deal carbon border adjustments favor lower-carbon membrane output.
- Food Processing:FSSAI food-grade certification expansion opens processed food pH regulation applications. EPA effluent guidelines and OSHA process safety management requirements shape US manufacturing compliance costs for chloralkali producers serving this segment.
Chemical manufacturing anchors the volume base while pharmaceuticals climbs the fastest on tightening purity specifications and carbon disclosure requirements.
Packaging Type:
Volume scale determines packaging economics, with bulk infrastructure investments concentrating among integrated producers and large-scale agrochemical formulators.
- Bags:Multi-wall paper or polyethylene containers serve flake and pellet grades for mid-scale chemical and agricultural processors.
- Drums:Steel or fiber containers handle liquid and solid shipments where intermediate volumes preclude bulk tank access.
- Totes:Intermediate bulk containers bridge drum and bulk economies for specialty chemical and food-grade applications.
- Bulk:Tank truck and railcar deliveries dominate liquid flows to chemical manufacturing and agriculture where dedicated handling infrastructure exists. Buyer concentration among agrochemical formulators compresses spot market liquidity.
Bulk anchors the volume base while totes expand most quickly through mid-tier processor consolidation.
Distribution Channel:
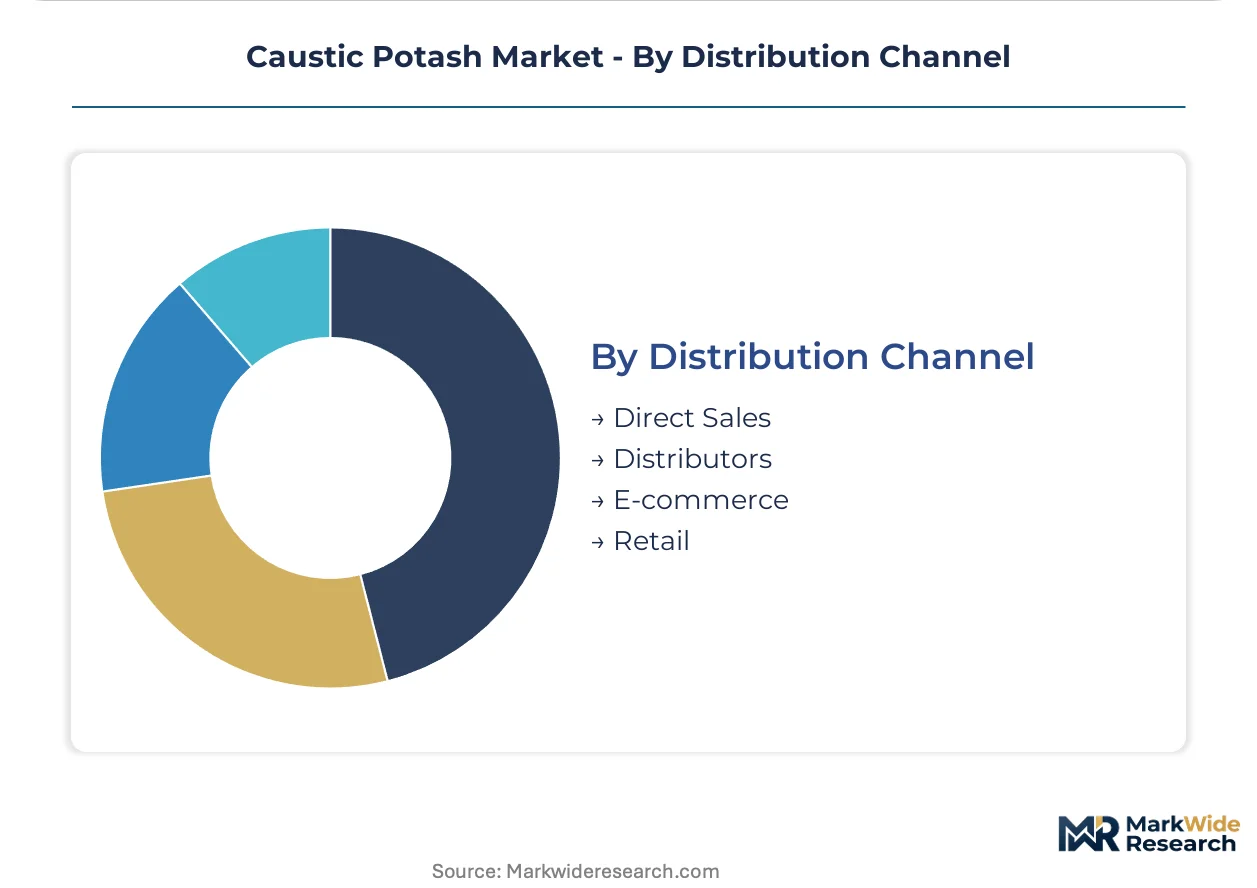
Customer type fragmentation separates direct procurement by large manufacturers from distributor-mediated access for smaller volume users.
- Direct Sales:Integrated chloralkali operators negotiate dedicated offtake contracts with Tata Chemicals and pharmaceutical manufacturers, bypassing traditional channels for liquid bulk deliveries.
- Distributors:Regional chemical distributors serve fragmented food processing and small-scale chemical manufacturing demand.
- E-commerce:Digital procurement platforms penetrate laboratory and small-batch industrial chemical segments.
- Retail:Limited presence in consumer-facing drain cleaner and specialty soap applications.
Direct sales anchors the volume base while e-commerce gains share at the steepest rate through procurement digitization in laboratory segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major producing regions, with membrane cell capacity expansion in North America and Asia reshaping traditional trade corridors while European imports face carbon border adjustment pressures.
United States
Integrated chloralkali operators along the US Gulf Coast supply liquid bulk to domestic chemical manufacturers and agriculture formulators. EPA mercury cell phase-out timelines accelerate asset reconfiguration toward membrane configurations. The Texas-Louisiana chemical corridor concentrates upgraded electrolysis capacity serving pharmaceutical and food-grade export demand.
Germany
REACH registration requirements and EU Green Deal carbon border adjustments constrain import competitiveness for mercury-derived material. EMA GMP certification standards tighten pharmaceutical-grade specifications for active ingredient synthesis. The Rhine-Ruhr industrial cluster anchors membrane-equipped production serving continental personal care and biopharma formulators.
India
Tata Chemicals and regional fertilizer cooperatives expand captive caustic potash consumption for specialty crop nutrient blends. CDSCO pharmaceutical-grade standards and FSSAI food-grade certification create dual compliance thresholds for suppliers. The Gujarat chemical belt concentrates flake and pellet production capacity serving domestic agrochemical formulators and export markets.
China
Dual carbon goals and MEE environmental enforcement accelerate mercury cell retirement across chloralkali manufacturing bases. NMPA pharmaceutical-grade standards and GB quality certification align with tightening international purity requirements. The Yangtze River Delta membrane cell clusters supply domestic potassium salt production and regional chemical synthesis operations.
Brazil
ANVISA pharmaceutical-grade import standards and agricultural nutrient demand drive procurement consolidation among specialty fertilizer formulators. The São Paulo industrial corridor concentrates distributor-mediated access for food processing and chemical manufacturing segments. Regional chloralkali capacity expansion remains constrained by potassium chloride feedstock import dependence.
Caustic Potash Market Key Industry Players
Concentration sits with integrated chloralkali operators possessing capital resources for membrane cell upgrades and multi-jurisdiction certification capabilities. The supplier base compresses toward asset-heavy producers with captive potassium chloride sourcing and dedicated pharmaceutical-grade production lines. Three archetypes dominate: integrated chemical conglomerates with chloralkali infrastructure, regional fertilizer cooperatives with captive consumption models, and specialty chemical distributors serving fragmented processor demand. Competitive moves center on electrolyzer technology licensing partnerships and direct offtake contract negotiations with large-scale agrochemical formulators.
Among integrated chemical operators, Occidental Chemical Corporation and Tata Chemicals exemplify scale-driven positioning through membrane-equipped production infrastructure. Evonik Industries occupies a specialist tier focused on high-purity grades for pharmaceutical and personal care applications. These three anchors represent divergent strategic vectors: Gulf Coast liquid bulk dominance, South Asian captive supply integration, and European premium-grade certification leadership.
| Leading Market Players |
|---|
| The Mosaic Company |
| Evonik Industries |
| Occidental Chemical Corporation |
| Tata Chemicals |
| ICL Fertilizers |
| FMC Corporation |
| Olin Corporation |
| ERCO Worldwide |
| Tessenderlo Group |
| Others |
Cost & Logistics Intelligence
REACH registration and EU Green Deal carbon border adjustments gate both supply qualification and price differentiation simultaneously, compressing mercury-derived material margins while rewarding membrane cell operators with certified low-carbon output premiums. Pharmaceutical and food-grade certification tiers now separate commodity liquid bulk from flake and pellet formats commanding dissolution control premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across liquid bulk procurement, with pharmaceutical manufacturers accepting value-based premiums for EMA GMP and FDA-certified grades. Price differentiation rests on certification level and volume scale, with spot market liquidity compressing as Tata Chemicals and agrochemical formulators negotiate direct supply agreements. Cost compression in standard-grade liquid intensifies as caustic soda substitutes erode non-critical pH adjustment applications. Small-scale food processors exhibit highest price sensitivity, while injectable-grade pharmaceutical buyers demonstrate lowest elasticity due to synthesis purity requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical and agricultural procurement, with membrane cell output securing preferential allocation over mercury-derived material facing stranded asset risk. Geographic supply concentrates in the United States, India, and China, with potassium chloride feedstock drawing from Saskatchewan and Belarus extraction. Raw material dependencies center on mined KCl supply, membrane electrolyzer engineering expertise, and carbon-intensive energy inputs. Single-source vulnerability runs through Belarus trade route disruptions. Distribution runs through integrated chloralkali operators negotiating dedicated offtake contracts with large-scale formulators, bypassing traditional distributor channels for liquid bulk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane cell technology substitution fragments competitive positioning across certification tiers, creating white-space opportunities for specialized operators as pharmaceutical purity specifications tighten and carbon disclosure requirements proliferate.
For Market Incumbents: Compound membrane cell capacity advantages through backward integration into potassium chloride sourcing and dedicated pharmaceutical-grade production line investments. Defend margin position against caustic soda substitution by locking long-term offtake contracts with Tata Chemicals and regional fertilizer cooperatives. Prioritize EMA GMP and FDA dual certification to capture biopharma-grade expansion premiums as mercury cell retirements accelerate. For New Entrants and Emerging Players: Service-layer gaps in small-batch pharmaceutical synthesis and precision agriculture pellet dosing create entry vectors where incumbents under-serve fragmented demand. Target laboratory and cosmetic alkali segments through e-commerce procurement platforms, bypassing capital-intensive bulk infrastructure requirements. Pursue toll manufacturing partnerships with existing membrane cell operators to qualify CDSCO and FSSAI certifications without greenfield electrolyzer investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional chloralkali operators holding mercury cell installations facing accelerated EPA phase-out deadlines. Long-term viability favors membrane-equipped production clusters with captive KCl sourcing and multi-jurisdiction certification capabilities. Watch membrane electrolyzer engineering scarcity as inflection indicator for brownfield upgrade execution risk and stranded asset exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Capacity Expansion | EPA mercury phase-out timelines force asset reconfiguration toward lower-carbon electrolysis configurations. |
| Backward Integration into Potassium Chloride | Saskatchewan and Belarus supply concentration exposes margins to extraction cost volatility and trade disruption. |
| Pharmaceutical-Grade Certification Investment | EMA GMP and FDA dual qualification opens injectable-grade KOH premium positioning in active ingredient synthesis. |
| Long-term Supply Agreement Negotiation | Direct offtake contracts with Tata Chemicals and agrochemical formulators compress spot market liquidity. |
| Joint Venture for Regional Market Access | Gujarat chemical belt partnerships enable India domestic production serving FSSAI and CDSCO compliance thresholds. |
Research Approach
The analysis maps liquid bulk, flake, pellet, and granular sub-sectors, each validated through chloralkali plant managers, downstream agrochemical procurement leads, pharmaceutical regulatory affairs directors, and distribution channel partners. Primary interview insights triangulate against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and BIS quality certification databases. Bottom-up electrolyzer capacity assessments and top-down end-use consumption estimates converge through cross-referencing.
Consistency checks validate volume and value outputs against membrane cell adoption benchmarks and pharmaceutical-grade pricing premiums reported across regional production clusters. Segmentation dimensions span physical form, end-use industry, packaging type, and distribution channel, with CAGRs derived from electrolyzer deployment timelines and purity specification tightening trajectories. Forecast inputs incorporate EPA mercury phase-out enforcement capacity, EU Green Deal carbon border adjustment implementation, and CDSCO pharmaceutical-grade standard adoption rates.
Forecasts assume regulatory continuity in EPA, REACH, and CDSCO regimes; material policy shifts would require re-modeling. Potassium chloride feedstock volatility, mercury cell stranded asset acceleration, and caustic soda substitution penetration represent primary revision triggers. Revision becomes warranted when membrane cell upgrade execution delays or trade route disruptions cross material supply security thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Global Concentrated Nitric Acid Market