
 Polytetrafluoroethylene (PTFE) Filter Membranes Market | 2026-2036
Polytetrafluoroethylene (PTFE) Filter Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Polytetrafluoroethylene (PTFE) Filter Membranes Market Analytics
Asset-light leasing models for membrane filtration systems is narrowing the competitive field to firms with balance-sheet depth. W. L. Gore & Associates leverages its fluoropolymer vertical integration to command premium positioning in pharmaceutical venting applications. Donaldson Company anchors its position through aftermarket service contracts that lock in replacement membrane revenue streams. Pall Corporation competes by dominating bioprocessing validation protocols that downstream customers cannot easily switch.
Polytetrafluoroethylene filter membranes are thin, porous fluoropolymer barriers manufactured by stretching or phase-inversion processes, with pore sizes ranging from 0.1 to 10 micrometers, engineered to separate particles while resisting aggressive chemicals and temperatures up to 260°C. These membranes serve critical separation duties in corrosive fluid processing, sterile air filtration, and ultrapure water generation where thermal and chemical stability outweigh cost considerations. Microfiltration technology leads in installed base across water treatment utilities due to mature operating protocols and lower energy draw, while nanofiltration commands the fastest growth trajectory in pharmaceutical active ingredient recovery where selectivity premiums justify higher capital outlays. Rolls format dominates industrial procurement channels for large-scale plant retrofits, whereas disc configurations concentrate in analytical laboratory settings where batch-scale precision commands margin premiums.
EPA effluent limitation guidelines and FDA sterilization validation requirements shape product development priorities for US-facing suppliers, while REACH chemical restriction frameworks in Europe constrain perfluorinated precursor availability and manufacturing site certification. China's MEE wastewater discharge standards are accelerating domestic membrane substitution programs that favor local producers with GB-standard compliance pathways. Stakeholders must monitor regulatory divergence between jurisdictions that fragments certification requirements and inflates compliance overhead for multi-region suppliers.
Market Dynamics
Membrane bioreactor retrofits at municipal wastewater facilities are compressing replacement cycles and forcing suppliers to prioritize hydrophobic surface modification capabilities over legacy product lines.
Growth Catalysts
- MEE Wastewater Standards:China's Ministry of Ecology and Environment discharge rules are accelerating membrane substitution programs across chemical manufacturing corridors in Jiangsu and Zhejiang provinces.
- Pharmaceutical Venting:Sterile air filtration demand from biologics manufacturing is pulling PTFE membranes into single-use process skids with validated sterilization protocols.
- Petrochemical Cluster Expansion:US Gulf Coast ethylene crackers and derivatives complexes are specifying corrosion-resistant filtration for acid gas treatment and catalyst recovery loops.
Market Restraints
- Fluoropolymer Precursor Constraints:REACH chemical restriction frameworks in Europe are constraining perfluorinated compound availability and inflating raw material qualification timelines for membrane producers.
- Energy-Intensive Manufacturing:Sintering and stretching processes require sustained thermal inputs above 320°C, exposing producers to natural gas price volatility and carbon border adjustment exposure.
- PVDF Substitution in Water Treatment:Polyvinylidene fluoride membranes are capturing share in lower-temperature municipal applications where chemical resistance requirements moderate.
Strategic Opportunities
- Semiconductor Ultrapure Water:Advanced node fabrication facilities in Taiwan and South Korea are specifying PTFE for hot DI water loops where metallic contamination controls tighten at 3nm and below.
- Leasing Model Penetration:Asset-light filtration-as-a-service contracts are opening procurement access to mid-scale chemical processors previously priced out of membrane bioreactor ownership.
- Hydrogen Electrolyzer Cathode Protection:Alkaline and PEM electrolysis stacks are specifying PTFE gas diffusion barriers to manage KOH carryover and extend stack life in gigawatt-scale projects.
Industry Challenges
- Fouling Mitigation Expertise:Operators lack personnel trained in transmembrane pressure optimization and chemical cleaning-in-place sequencing for hydrophobic membranes in high-solids applications.
- Validation Documentation Burden:FDA sterilization validation requirements and extractables testing protocols are extending qualification timelines for pharmaceutical-grade membrane lots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polytetrafluoroethylene (PTFE) Filter Membranes Market |
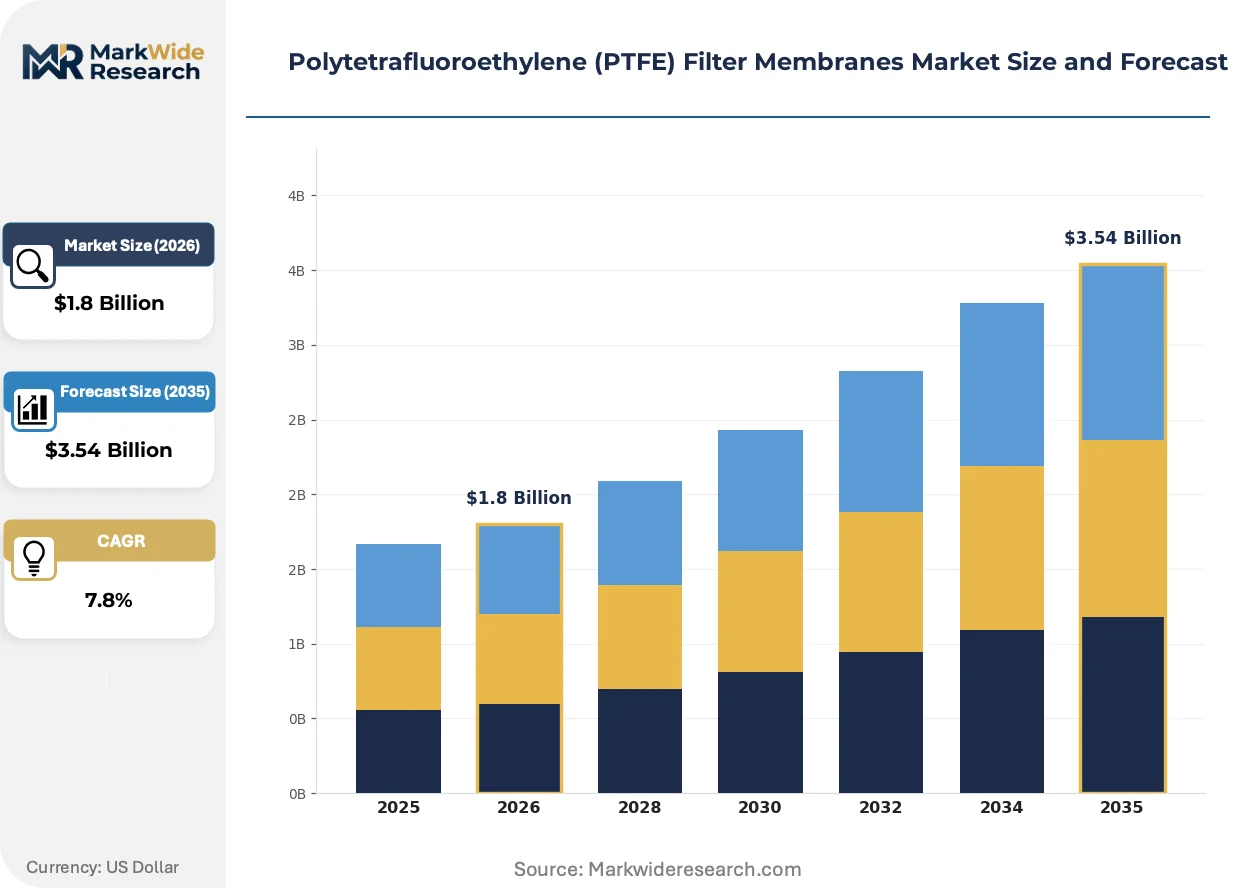
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buttons, Discs, Sheets, Rolls Technology: Membrane Filtration, Microfiltration, Ultrafiltration, Nanofiltration Application: Water Treatment, Chemical Processing, Food & Beverage, Pharmaceuticals End User: Healthcare, Manufacturing, Energy, Environmental |
| Companies Covered | W. L. Gore & Associates, Inc., Donaldson Company, Inc., Corning Incorporated, GVS S.p.A., Pall Corporation, Sartorius AG, Merck KGaA, Suzhou Unique New Material Science & Technology Co., Ltd., Hyundai Micro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polytetrafluoroethylene (PTFE) Filter Membranes Market Evolving Landscape
Surface engineering breakthroughs and regulatory chemistry restrictions are compressing traditional membrane architectures while opening adjacent application verticals previously served by metallic or ceramic alternatives.
Expanded PTFE (ePTFE) membrane fabrication with controlled fibrillation is collapsing the performance gap between cast and stretched fluoropolymer barriers. Semiconductor fabs in Taiwan are adopting these structures for aggressive chemical filtration at 180°C process temperatures. The technology is collapsing capital requirements for sub-0.2 micron rating production, enabling regional membrane converters to challenge incumbent suppliers.
REACH perfluorinated substance restrictions are forcing European membrane producers to requalify precursor supply chains and accelerate non-fluorinated alternative development programs. The regulation is redirecting R&D budgets toward hybrid organic-inorganic surface coatings that replicate PTFE's hydrophobicity without perfluorooctanoic acid content. German wastewater equipment OEMs are most exposed, with membrane substitution timelines compressed to 18-month validation windows.
Aftermarket service unbundling is fragmenting procurement authority between plant engineering departments and centralized corporate procurement functions. Large chemical processors are separating membrane replacement decisions from original system vendor tie-ins, opening direct sourcing channels for commodity-rated rolls. The shift is most visible in East China's private chemical manufacturing sector, where purchasing managers now negotiate membrane lots independently of bioreactor OEM service contracts.
Polytetrafluoroethylene (PTFE) Filter Membranes Market Segmentation
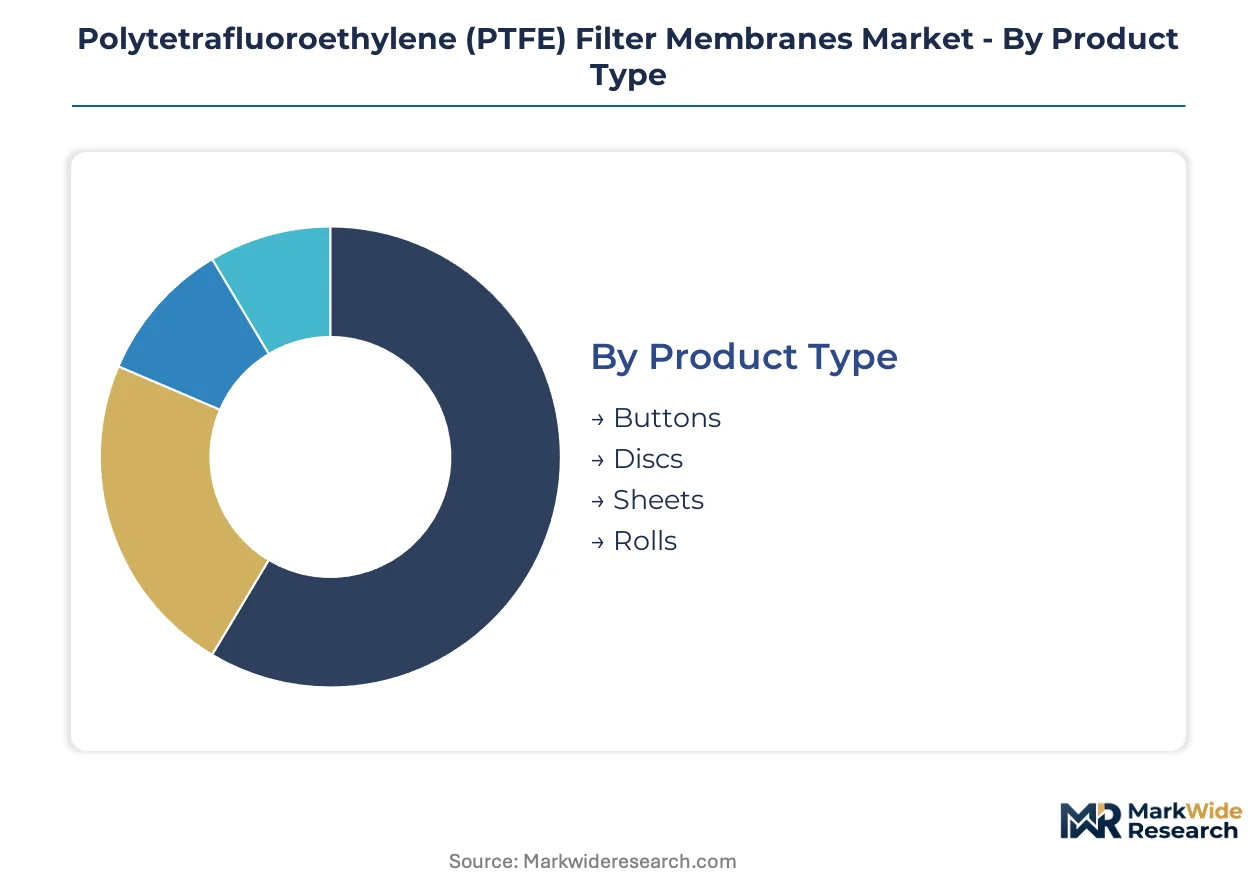
PTFE membrane buyers segment procurement by mechanical format, separation precision, and regulatory exposure. Each dimension shapes supplier qualification requirements and replacement cycle economics differently across water utilities and pharmaceutical cleanrooms.
Product Type:
Format selection tracks installation scale and labor cost tradeoffs across municipal retrofits versus laboratory batch operations.
- Rolls:Continuous-format membranes enable rapid surface-area deployment across large-scale membrane bioreactor retrofits. Demand concentrates at US Gulf Coast petrochemical complexes and East China's chemical manufacturing corridor where single-facility membrane area requirements exceed 10,000 square meters annually.
- Discs:Precision-cut circular configurations serve analytical laboratories and pharmaceutical sterilization skids requiring validated batch-scale filtration. German wastewater equipment OEMs specify disc formats for pilot-scale membrane bioreactor testing prior to full plant deployment.
- Sheets:Flat-sheet geometries support plate-and-frame module architectures common in corrosive chemical processing loops.
- Buttons:Compact radial-seal formats integrate into portable filtration devices and point-of-use venting applications.
The dominant share belongs to rolls, while discs are closing the gap fastest on pharmaceutical venting demand.
Technology:
Precision thresholds separate mature utility applications from emerging high-value recovery processes.
- Microfiltration:0.1-10 micron rating membranes dominate installed base across water treatment utilities due to mature operating protocols and lower transmembrane pressure requirements. China's MEE wastewater discharge standards are accelerating microfiltration substitution programs across Jiangsu and Zhejiang chemical manufacturing corridors.
- Nanofiltration:Sub-nanometer selectivity barriers command premium positioning in pharmaceutical active ingredient recovery where separation precision justifies higher capital outlays. Taiwan semiconductor fabs specify nanofiltration for hot DI water loops at advanced nodes below 3nm where metallic contamination controls tighten.
- Ultrafiltration:Intermediate precision membranes serve protein concentration and virus removal in bioprocessing applications.
- Membrane Filtration:Generic category encompassing hybrid and unclassified separation architectures.
Microfiltration retains volume leadership, though nanofiltration is expanding most quickly on pharmaceutical and electronics purity demands.
Application:
End-use chemistry and temperature exposure dictate material specification and replacement frequency.
- Water Treatment:Municipal and industrial wastewater applications specify PTFE for membrane bioreactor durability in high-solids environments. Germany's tightening effluent rules are compressing replacement cycles at Rhine-Ruhr basin treatment facilities.
- Pharmaceuticals:Sterile air filtration and venting applications require FDA-validated sterilization protocols and extractables documentation. Single-use process skid adoption is pulling PTFE membranes into biologics manufacturing with validated gamma-irradiation compatibility.
- Chemical Processing:Acid gas treatment and catalyst recovery loops at US Gulf Coast ethylene crackers demand corrosion resistance above 180°C.
- Food & Beverage:Steam-in-place sterilization compatibility supports aseptic processing applications with aggressive cleaning protocols.
Water treatment commands the largest installed base, while pharmaceuticals is gaining share fastest on single-use system adoption.
End User:
Procurement authority and technical specification depth vary sharply across regulated versus industrial buyers.
- Environmental:Municipal wastewater utilities and industrial effluent treatment operators drive volume procurement through membrane bioreactor retrofits. China's private chemical manufacturing sector is unbundling aftermarket decisions from OEM service contracts, opening direct membrane sourcing channels.
- Healthcare:Hospital sterilization departments and pharmaceutical manufacturers impose validation documentation burdens that extend qualification timelines. FDA sterilization validation requirements and extractables testing protocols favor suppliers with established pharmaceutical-grade membrane lots.
- Manufacturing:Chemical processors and electronics fabricators specify PTFE for aggressive fluid handling and ultrapure water generation.
- Energy:Hydrogen electrolyzer projects are specifying PTFE gas diffusion barriers for alkaline and PEM stack cathode protection.
Environmental end users hold the dominant procurement volume, though healthcare is expanding most quickly on biologics manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of PTFE membrane precursors from China and Germany currently exceed import volumes by substantial margins, though US Gulf Coast petrochemical clusters are narrowing this gap through captive fluoropolymer production expansion. Trade balances are shifting as REACH restrictions in Europe constrain precursor availability while China's MEE standards accelerate domestic membrane substitution programs.
United States
US Gulf Coast ethylene crackers and derivatives complexes specify PTFE membranes for acid gas treatment and catalyst recovery loops above 180°C. EPA effluent limitation guidelines shape product development priorities for domestic suppliers facing multi-jurisdiction compliance overhead. Houston-Baytown petrochemical corridor facilities drive concentrated demand for corrosion-resistant filtration in expanding ethylene capacity.
Germany
Rhine-Ruhr basin wastewater treatment facilities compress replacement cycles under tightening effluent rules that mandate membrane bioreactor retrofits. ECHA REACH chemical restriction frameworks constrain perfluorinated compound availability and inflate raw material qualification timelines for membrane producers. German wastewater equipment OEMs in North Rhine-Westphalia face compressed 18-month validation windows for membrane substitution programs.
China
Jiangsu and Zhejiang chemical manufacturing corridors accelerate membrane substitution programs under MEE wastewater discharge standards that favor local producers with GB-standard compliance pathways. SAMR certification requirements and dual carbon goals redirect capital toward domestic membrane fabrication capacity. Yangtze River Delta chemical processors unbundle aftermarket decisions from OEM service contracts, opening direct membrane sourcing channels.
Japan
Biologics manufacturing facilities in Kanto and Kansai regions pull PTFE membranes into single-use process skids with validated gamma-irradiation compatibility. PMDA sterilization validation requirements extend qualification timelines for pharmaceutical-grade membrane lots. Osaka-Tokyo pharmaceutical corridor concentrates demand for sterile air filtration and venting applications with extractables documentation.
South Korea
Advanced node fabrication facilities in Seoul Capital Area and Busan-Ulsan specify PTFE membranes for hot DI water loops where metallic contamination controls tighten at 3nm and below. METI-aligned industrial policy supports domestic membrane qualification for semiconductor ultrapure water systems. Samsung and SK Hynix supply chain localization programs accelerate Korean membrane converter market entry.
Polytetrafluoroethylene (PTFE) Filter Membranes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precursor and membrane fabrication. The vendor base stratifies across three tiers: fluoropolymer-integrated material suppliers, membrane converters with format specialization, and filtration system OEMs with service contract lock-in. Consolidation pressure concentrates at the converter tier where ePTFE technology collapses capital barriers. Dominant competitive moves include backward integration into fluoropolymer resin production and geographic expansion through local certification partnerships.
Among US-based material science specialists, W. L. Gore & Associates, Inc. and Donaldson Company, Inc. occupy positions anchored by fluoropolymer vertical integration and aftermarket service infrastructure respectively. Pall Corporation exemplifies the validation-heavy pharmaceutical tier through bioprocessing protocol dominance. German and Japanese entrants including Sartorius AG and Merck KGaA represent European pharmaceutical-grade membrane archetypes with extractables documentation capabilities. Chinese fabricators such as Suzhou Unique New Material Science & Technology Co., Ltd. sit within the regional converter tier capitalizing on GB-standard compliance pathways and East China chemical corridor proximity.
| Leading Market Players |
|---|
| W. L. Gore & Associates, Inc. |
| Donaldson Company, Inc. |
| Corning Incorporated |
| GVS S.p.A. |
| Pall Corporation |
| Sartorius AG |
| Merck KGaA |
| Suzhou Unique New Material Science & Technology Co., Ltd. |
| Hyundai Micro |
| Others |
Value Network & Pricing Analysis
Fluoropolymer resin production concentrates in China and the United States, concentrating margin capture with integrated material suppliers who command premium positioning in pharmaceutical-grade membrane tiers while regional converters compete on commodity-rated rolls for water treatment retrofits.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates FDA-validated pharmaceutical lots with extractables documentation from GB-standard municipal grades and unbranded commodity rolls. Cost compression in the converter tier is intensifying because ePTFE technology collapses capital barriers for sub-0.2 micron production. Municipal wastewater utilities exhibit the highest price sensitivity due to budget-constrained procurement cycles, while semiconductor fabs and biologics manufacturers show lowest sensitivity given contamination control premiums.
Supply Chain Analysis
Perfluorinated precursor supply draws from Chinese chemical manufacturing corridors, US Gulf Coast petrochemical clusters, and German specialty chemical producers. Raw material dependencies include PTFE resin pellets, fluoropolymer stretching equipment, and gamma-irradiation sterilization services. Single-source vulnerability concentrates in REACH-restricted European precursor channels where requalification timelines extend to eighteen months. Distribution runs through membrane bioreactor OEM service contracts, direct procurement channels for large chemical processors, and regional converter networks serving mid-scale facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as East China's private chemical manufacturers unbundle membrane replacement decisions from original equipment vendor tie-ins, fragmenting procurement authority and opening direct sourcing channels that bypass traditional system integrators.
For Market Incumbents: Pre-empt PVDF substitution in lower-temperature municipal applications by accelerating hydrophobic surface modification R&D and locking in aftermarket service contracts with performance-based replacement guarantees. Capture backward integration into fluoropolymer resin production to defend margin position against Chinese converters exploiting GB-standard compliance pathways. For New Entrants and Emerging Players: Build out hydrogen electrolyzer gas diffusion barrier capabilities as alkaline and PEM stack deployments scale, targeting Korean and Taiwanese gigawatt-scale projects with localized certification partnerships. Penetrate the semiconductor ultrapure water segment through direct qualification with Taiwan foundries where metallic contamination controls tighten at advanced nodes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed membrane converters lacking fluoropolymer integration who face margin compression from ePTFE technology diffusion. Five-to-ten year viability hinges on regulatory divergence between EPA effluent guidelines and REACH precursor restrictions. Monitor SAMR certification acceleration in China as the inflection signal for domestic producer market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captures margin pools concentrated with Chinese and US material suppliers while insulating against REACH precursor constraints. |
| Hydrophobic Surface Modification R&D Investment | Addresses fouling mitigation gaps that compress replacement cycles at German and Chinese membrane bioreactor facilities. |
| Localized GB-Standard Certification Partnerships | Unlocks procurement access to Jiangsu and Zhejiang chemical corridors under MEE wastewater discharge acceleration. |
| Aftermarket Service Contract Expansion | Locks in replacement membrane revenue streams as East Chinese buyers unbundle decisions from OEM tie-ins. |
| Hydrogen Electrolyzer Gas Diffusion Barrier Development | Captures emerging demand from Korean and Taiwanese gigawatt-scale alkaline and PEM stack deployments. |
Research Methodology
Initial hypotheses were tested against primary input from membrane bioreactor plant managers, pharmaceutical procurement leads, fluoropolymer R&D directors, and aftermarket service heads at filtration OEMs and refined through secondary validation against EPA effluent limitation guidelines, ECHA REACH restriction frameworks, SAMR certification databases, and customs trade flow records. Bottom-up membrane area demand estimates from municipal retrofit pipelines and top-down fluoropolymer resin consumption analysis were triangulated to anchor volume projections.
Demand-supply balance modeling across the projection horizon incorporated segmentation by mechanical format, separation precision tier, and regulatory exposure cluster alongside end-use industry-specific capacity expansion timelines. CAGRs were derived from fitted growth curves calibrated to historical membrane substitution program velocities and forward-looking MEE standard implementation schedules. Semiconductor node progression timelines and hydrogen electrolyzer deployment pipelines provided industry-specific demand elasticity inputs.
Practitioners should monitor REACH precursor restriction enforcement intensity and Chinese dual carbon policy redirection for early signals of supply chain reconfiguration. Forecasts reflect assumptions about regulatory divergence persistence and technology substitution thresholds that could shift if PVDF performance gaps narrow or non-fluorinated hybrid coatings achieve commercial scale. Cross-checking against EIA industrial natural gas price benchmarks and semiconductor capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Microfiltration Membranes Market