
 North America Single-Ply Membrane Market | 2026-2036
North America Single-Ply Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
North America Single-Ply Membrane Market Analytics
EPA enforcement of HFC phasedown rules under the AIM Act is broadening the cost-of-entry calculus for new single-ply membrane producers. Carlisle Construction Materials leverages captive TPO formulation capacity to sustain margin stability across volatile polymer feedstock cycles. Johns Manville anchors its position through deep backward integration into EPDM rubber compounding, while GAF competes via an extensive certified-contractor network that controls specification flow in the commercial segment.
Single-ply membrane denotes factory-manufactured roofing sheets comprising synthetic elastomer or thermoplastic compounds, typically installed in 60 mil to 120 mil thicknesses over insulation boards to provide weatherproof building envelopes. The primary industrial purpose centers on delivering cost-effective, long-duration waterproofing for low-slope commercial and institutional structures with service lives exceeding twenty years. TPO formulations now dominate new commercial specification due to heat-weld seam integrity and reflective surface compliance with cool-roof mandates, while EPDM retains structural margin pools in ballasted industrial applications where chemical resistance and dimensional stability outweigh first-cost sensitivity. Mechanically attached installation methods lead volume in hurricane-prone zones, whereas adhered systems command premium positioning in high-wind markets requiring uplift resistance certification.
OSHA workplace exposure limits and FM Global property loss prevention standards jointly shape product testing protocols and contractor certification requirements across the United States and Canada. The EPA's Significant New Alternatives Policy program and California Air Resources Board regulations further constrain blowing-agent selection and volatile organic compound thresholds in membrane manufacturing. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and building-code amendments that could reclassify membrane recyclability and end-of-life disposal obligations.
Market Dynamics
The North America single-ply membrane market is pivoting around EPA enforcement of HFC phasedown mandates under the AIM Act, which is compressing formulation choices while redistributing competitive advantage toward producers with captive polymer supply.
Growth Catalysts
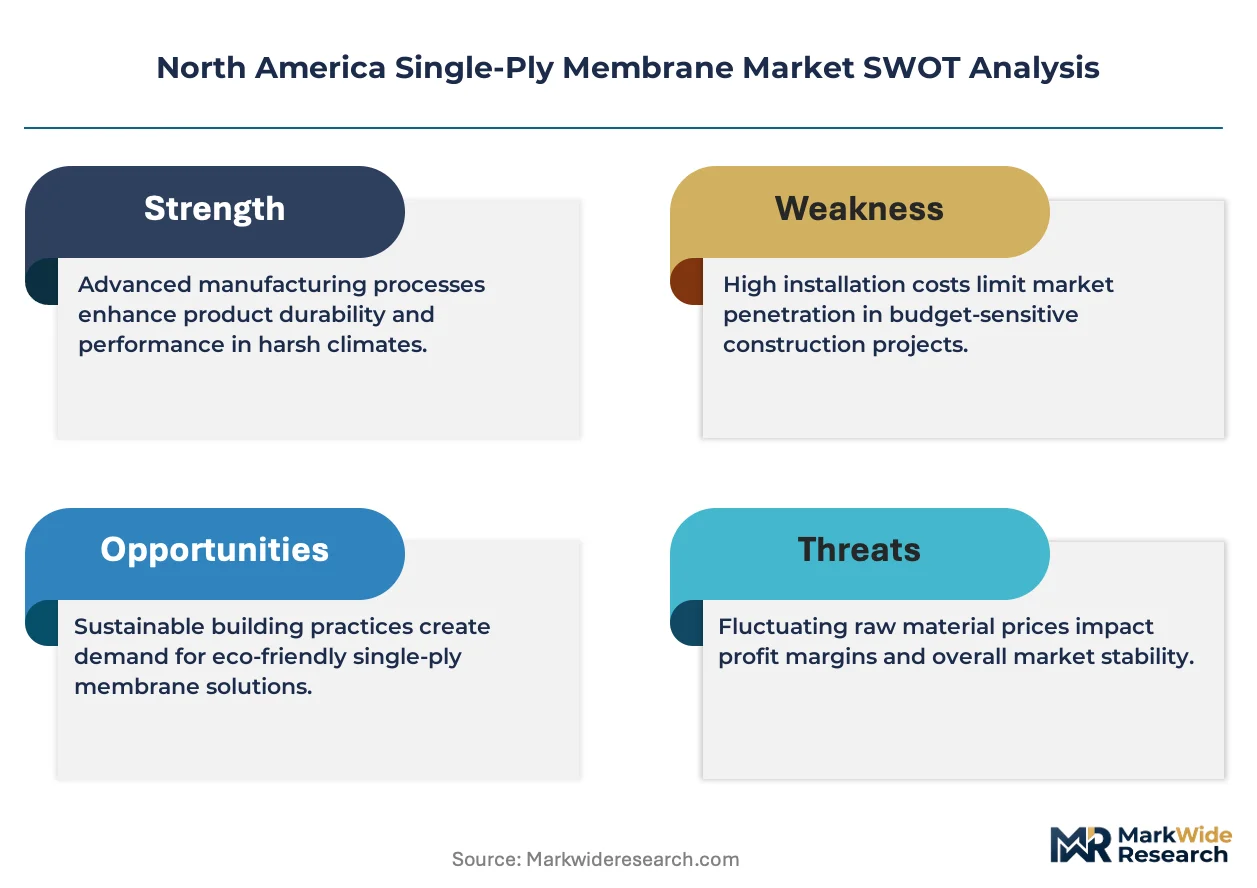
- AIM Act Implementation:EPA phasedown schedules for HFC blowing agents are accelerating R&D investment in lower-GWP formulation chemistry among domestic manufacturers.
- Sun Belt Warehouse Construction:Commercial distribution center and cold-storage building permits in Texas, Florida, and California are outpacing national averages and driving membrane specification volume.
- TPO Heat-Weld Technology:Seam integrity improvements in thermoplastic polyolefin systems are displacing traditional attachment methods in hurricane-prone specification zones.
Market Restraints
- Polymer Feedstock Volatility:Propylene and ethylene price swings compress margin stability for non-integrated membrane producers lacking captive resin supply.
- EPDM Rubber Concentration:Backward-integrated EPDM compounders dominate structural margin pools, creating supply-side concentration risk for specialty grades.
- California CARB Constraints:State-level volatile organic compound thresholds and extended producer responsibility frameworks add compliance friction for cross-border manufacturers.
Strategic Opportunities
- Canadian Cold-Storage Underpenetration:Building code harmonization and Arctic climate adaptation create specification whitespace for high-R-value membrane systems in Alberta and Saskatchewan.
- Cool-Roof Mandate Expansion:Municipal solar reflectance index requirements in Phoenix, Las Vegas, and Miami are creating regulatory tailwinds for white TPO specification.
- Certified-Contractor Networks:Direct-to-installer digital platforms are bypassing traditional distribution and capturing specification flow in the commercial reroofing segment.
Industry Challenges
- FM Global Uplift Certification:Property loss prevention testing protocols require capital-intensive wind-tunnel validation that extends product launch timelines for new entrants.
- Heat-Welder Skill Scarcity:OSHA workplace exposure limits and mechanized seaming equipment operation create certified technician bottlenecks in high-growth construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Single-Ply Membrane Market |
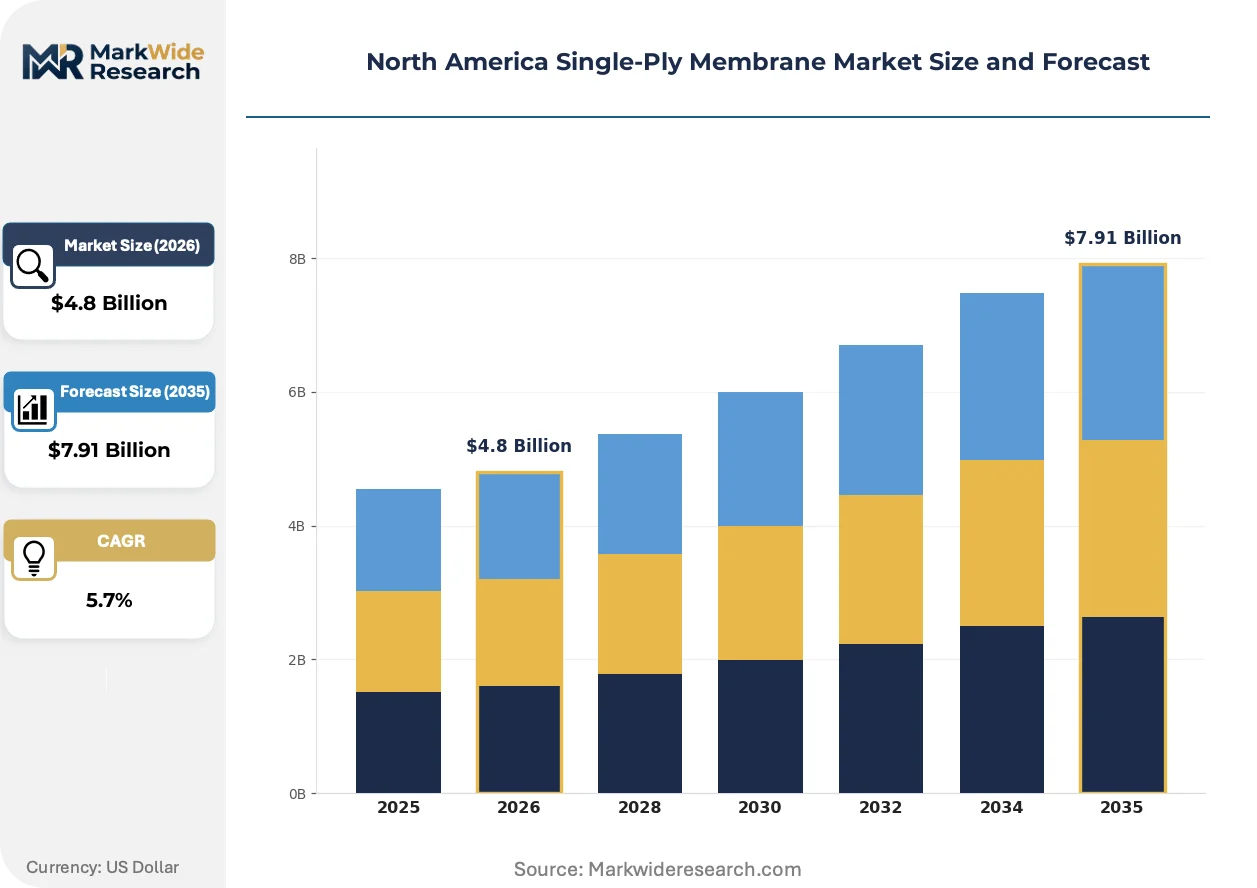
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, TPO, PVC, KEE End User: Residential, Commercial, Industrial, Institutional Installation Type: Adhered, Mechanically Attached, Ballasted, Hybrid Thickness: 60 mil, 80 mil, 100 mil, 120 mil |
| Companies Covered | Carlisle Construction Materials, Kingspan Group, Standard Industries Inc., DOW, IKO Industries Inc., GAF, Johns Manville, Sika AG, CertainTeed, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Single-Ply Membrane Market Evolving Landscape
Formulation chemistry, installation automation, and procurement digitization are converging to compress project timelines and reshape how membrane specification flows through contractor networks.
Robotic pre-programmed welding equipment is automating seam execution on large-format commercial roofs. National roofing contractors in Texas and Florida are deploying these systems to reduce labor dependency and accelerate project closeout. The technology is automating quality consistency while compressing the certified-welder bottleneck that has constrained crew scaling.
EPA's Significant New Alternatives Policy program is constraining blowing-agent selection across domestic manufacturing. Membrane producers are reformulating toward hydrofluoroolefin and hydrocarbon alternatives to maintain product performance under lower-GWP thresholds. TPO lines face the steepest transition curves given their reliance on HFC-driven expansion processes.
Building owners are consolidating procurement through national account structures that bypass regional distributors. Third-party logistics platforms are capturing specification data and directing volume toward pre-qualified membrane brands. This concentration is most visible in the retail and industrial warehouse verticals where portfolio-scale reroofing programs dominate capital planning cycles.
North America Single-Ply Membrane Market Segmentation
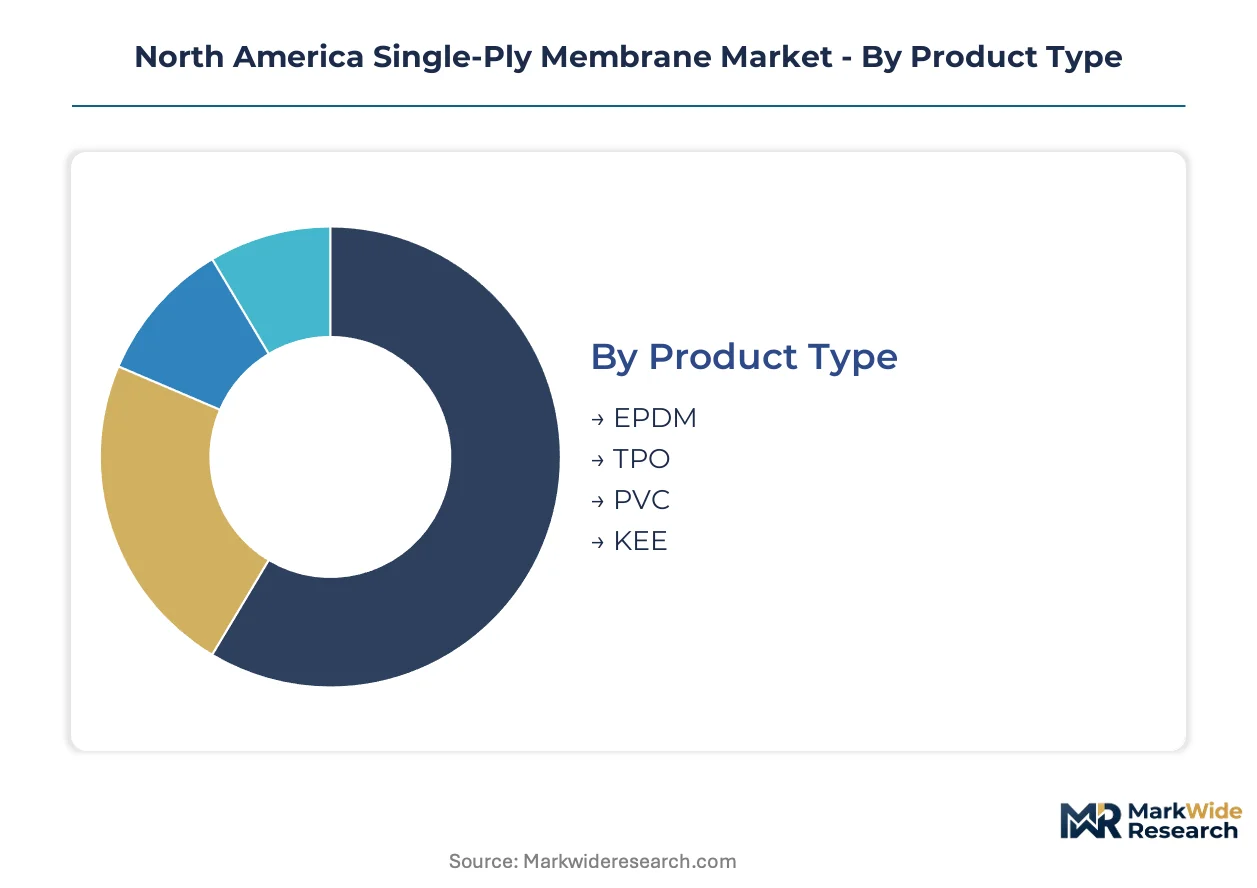
Membrane specification flows through distinct technical and application channels that reshape procurement patterns across the North American roofing industry. Supply concentration in polymer feedstock and installation certification creates divergent margin pools by segment.
Product Type:
Polymer chemistry concentration among integrated compounders determines competitive positioning and formulation flexibility across membrane categories.
- TPO:Thermoplastic polyolefin sheets deliver heat-weld seam integrity and solar reflectance compliance with cool-roof mandates. Demand concentrates in Texas, Florida, and Arizona distribution center construction where white membrane specification dominates new commercial permits.
- EPDM:Ethylene propylene diene terpolymer membranes provide dimensional stability and chemical resistance in ballasted industrial applications. Black-surface EPDM retains structural margin pools across Great Lakes manufacturing corridors and chemical processing facilities where first-cost sensitivity is secondary to longevity.
- PVC:Polyvinyl chloride formulations offer chemical resistance and fire performance for institutional rooftops with stringent code requirements.
- KEE:Ketone ethylene ester compounds deliver premium elongation and puncture resistance for high-traffic mechanical equipment platforms.
TPO absorbs the bulk of installed capacity; KEE is expanding most quickly in specialized mechanical-intensive applications.
End User:
Capital planning cycles and specification authority differ sharply across building ownership structures, redirecting membrane procurement toward national account platforms or regional contractor networks.
- Commercial:Retail, office, and hospitality portfolios drive volume through consolidated national reroofing programs. Third-party logistics platforms in the Sun Belt are capturing specification data and directing volume toward pre-qualified TPO brands for warehouse and distribution center envelopes.
- Industrial:Manufacturing and cold-storage facilities prioritize chemical resistance and thermal performance over reflectivity. EPDM ballasted systems dominate margin pools across petrochemical corridors and food processing plants where roof traffic and equipment density demand puncture tolerance.
- Institutional:Schools, hospitals, and government buildings navigate extended public procurement timelines with heightened fire-code scrutiny.
- Residential:Low-slope multifamily and luxury home construction represents a thin specification channel with price-sensitive contractor selection.
Commercial absorbs the bulk of installed capacity; Industrial is climbing the fastest on cold-storage facility expansion.
Installation Type:
Wind uplift certification requirements and labor availability constrain method selection across hurricane-prone and high-wind geographies.
- Mechanically Attached:Fastener-based systems dominate volume in Florida, Texas, and coastal Carolinas where FM Global uplift ratings govern insurance compliance. Crew scalability depends on certified fastener-pattern technicians, creating bottlenecks in high-growth construction markets.
- Adhered:Full-bond attachment commands premium positioning in Midwest and Northeast markets requiring high-wind certification without mechanical penetration. Cold-storage specification in Minnesota and Wisconsin favors adhered systems for thermal bridge elimination.
- Ballasted:Loose-laid membrane with stone or paver ballast retains cost advantage in large-footprint industrial applications with low wind exposure.
- Hybrid:Combined mechanical and adhered attachment addresses complex roof geometries and equipment-intensive zones.
Mechanically attached absorbs the bulk of installed capacity; Adhered is gaining share fastest on cool-roof mandate expansion.
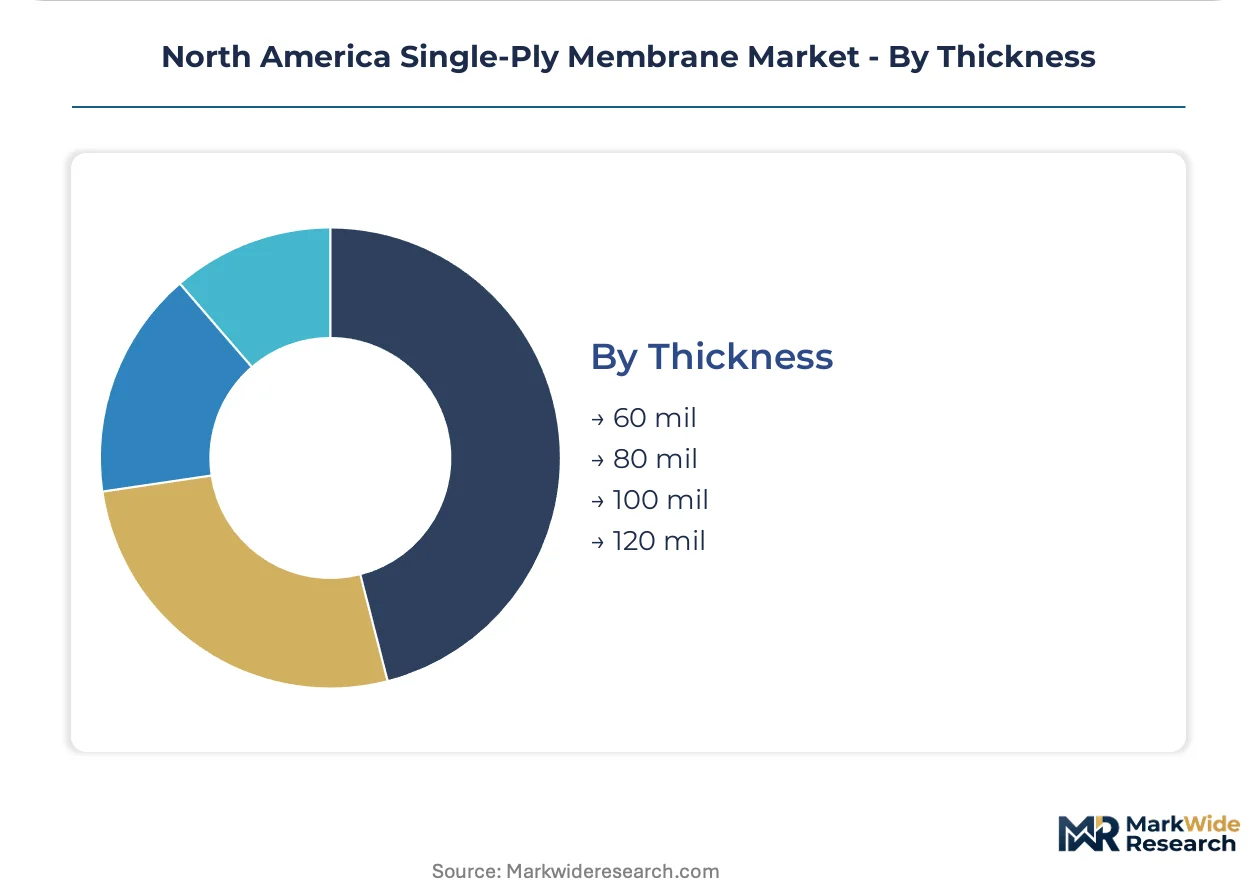
Thickness:
Mil specification directly correlates with warranty duration and capital planning horizons across owner types.
- 60 mil:Entry specification for cost-constrained reroofing and short-hold commercial assets. Standard-grade TPO at this thickness competes on first-cost in Texas and Florida speculative warehouse construction.
- 80 mil:Mid-tier workhorse specification balancing durability and material cost. Dominates institutional and commercial new construction across California and Arizona where 20-year service life is baseline.
- 100 mil:Premium specification for high-traffic industrial roofs and extended-warranty national accounts. Cold-storage operators in Pennsylvania and Ohio specify this grade for puncture resistance under mechanical equipment.
- 120 mil:Maximum durability grade for critical facilities and extreme climate exposure. Limited to specialized applications in Arctic-adjacent Canadian markets and chemical processing corridors.
80 mil absorbs the bulk of installed capacity; 100 mil is expanding most quickly on extended-warranty national account consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones across Sun Belt metropolitan areas are concentrating membrane demand through accelerated warehouse development and tax-advantaged capital deployment.
United States
Texas, Florida, and California dominate permit volume for distribution centers and cold-storage facilities. EPA phasedown schedules under the AIM Act are forcing domestic manufacturers toward lower-GWP formulation chemistry. Dallas-Fort Worth and Houston anchor the nation's largest TPO specification clusters for speculative industrial construction.
Canada
Alberta and Saskatchewan present underpenetrated whitespace for high-R-value membrane systems in Arctic climate adaptation. Health Canada and PMRA coordinate with provincial regulators on building code harmonization. Calgary and Edmonton cold-storage operators are specifying thicker membrane grades for thermal bridge elimination.
Mexico
Nuevo León and the Bajío Region attract nearshoring manufacturing investment requiring industrial roofing envelope solutions. Mexican environmental standards under SEMARNAT are tightening volatile organic compound thresholds for cross-border supply chains. Monterrey's automotive supplier parks are driving adhered-system specification for high-wind uplift certification.
North America Single-Ply Membrane Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and installation certification vectors. Market structure tilts toward consolidated supply given captive polymer requirements and FM Global testing barriers. Three archetypes dominate: integrated compounders controlling resin supply, membrane fabricators with certified-contractor networks, and building-material conglomerates leveraging distribution scale. Competitive moves center on backward integration into polymer feedstock and digital platform deployment to capture specification data.
Among integrated compounders, Carlisle Construction Materials and Johns Manville exemplify the backward-integrated archetype, while GAF occupies a position within the certified-contractor network tier. These three anchors represent distinct pathways to margin stability: captive TPO formulation, deep EPDM rubber compounding, and installer-channel control respectively.
| Leading Market Players |
|---|
| Carlisle Construction Materials |
| Kingspan Group |
| Standard Industries Inc. |
| DOW |
| IKO Industries Inc. |
| GAF |
| Johns Manville |
| Sika AG |
| CertainTeed |
| Others |
Value Network & Pricing Analysis
Propylene and ethylene feedstock volatility propagates through membrane manufacturing into three-tier pricing stratification across premium, standard, and economy levels, with captive resin supply anchoring margin stability for integrated compounders while non-integrated fabricators absorb polymer price swings in their spot-market procurement tiers.
Pricing Analysis
Short lead-time premiums command pricing power in Texas and Florida construction corridors where warehouse completion deadlines compress procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates FM Global-certified membranes from commercial-grade specification and entry-level reroofing stock. Pricing pressure stems from polymer feedstock volatility squeezing non-integrated producers without captive TPO formulation capacity. Speculative warehouse developers in Dallas-Fort Worth exhibit acute price sensitivity, while cold-storage operators in Minnesota prioritize thermal performance over first-cost.
Supply Chain Analysis
Freight costs from Gulf Coast petrochemical corridors to Sun Belt construction markets shape regional pricing spreads for membrane distribution. Manufacturing concentrates in the United States, Canada, and Mexico under USMCA trade frameworks, with polymer compounding anchored in Texas and Louisiana chemical processing zones. Raw material dependencies span propylene monomer, EPDM rubber compound, and hydrocarbon blowing agents subject to EPA phasedown constraints. Single-source vulnerability concentrates in specialized EPDM rubber grades where backward-integrated compounders dominate. Distribution runs through certified-contractor networks that capture specification flow in commercial reroofing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive polymer supply has become the decisive lever in this market, with manufacturers racing to secure upstream resin capacity as EPA formulation mandates compress margin pools for non-integrated competitors.
For Market Incumbents: Deploy certified-contractor network expansion to lock out specification flow from emerging digital procurement platforms. Carlisle and Johns Manville should accelerate captive TPO and EPDM compounding capacity additions in Texas and Ohio corridors before HFC phasedown deadlines tighten further. GAF must defend its installer-channel control against third-party logistics platforms capturing national account procurement data in retail and warehouse verticals. For New Entrants and Emerging Players: Regional roofing distributors in Canadian Prairie provinces represent the most penetrable channel partner type for bypassing established US supply relationships. Alberta and Saskatchewan cold-storage construction presents whitespace for high-R-value membrane systems where building code harmonization lags US adoption curves. New entrants should target digital direct-to-installer platforms for commercial reroofing segments where certified-welder scarcity constrains incumbent crew scaling. For Investors and Strategic Acquirers: EPA enforcement actions against HFC non-compliance are the leading indicator that formulation-capable compounders will command scarcity premiums across the analysis window. Mid-cycle viability favors manufacturers with demonstrated lower-GWP chemistry transitions and FM Global wind-tunnel certification infrastructure. Acquisition targets should screen for captive resin supply or established certified-contractor networks rather than pure fabrication capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive TPO and EPDM resin supply insulates margin stability from Gulf Coast feedstock volatility cycles. |
| FM Global Wind-Tunnel Certification Investment | Uplift rating validation opens specification access in Florida and Texas hurricane-prone insurance markets. |
| Certified-Contractor Network Expansion | Installer-channel control captures specification flow before third-party logistics platforms consolidate procurement. |
| Lower-GWP Formulation Transition | Hydrofluoroolefin and hydrocarbon blowing-agent chemistry maintains EPA compliance under AIM Act phasedown schedules. |
| Robotic Welding Equipment Deployment | Automated seam execution reduces labor dependency and compresses project timelines in high-growth construction corridors. |
Research Methodology
Independent corroboration across membrane manufacturing executives, commercial roofing contractors, and building code officials underwrites the qualitative findings in this study. Primary fieldwork engaged plant managers at integrated compounders, procurement leads at national roofing distributors, technical R&D directors at formulation laboratories, and certified-welder training coordinators. Secondary validation drew from EPA AIM Act regulatory filings, FM Global property loss prevention data, ACC chemical production statistics, and building permit databases across Texas, Florida, and California metropolitan areas. Bottom-up volume estimates triangulated against top-down polymer consumption models.
Rate-of-change decomposition across the analysis window isolates volume drivers by membrane chemistry, installation method, thickness specification, and end-use vertical. Segmentation modeling incorporates product type, end-user category, installation technique, and mil-grade warranty tier. CAGRs derive from polynomial trend fitting against historical permit data and polymer feedstock price elasticity coefficients. Forecast inputs include Sun Belt warehouse construction pipelines, EPA enforcement intensity projections, and certified-technician supply constraints.
Several conditions sit outside the modeled scope, including potential building-code amendments reclassifying membrane recyclability obligations and state-level extended producer responsibility frameworks beyond California CARB constraints. Forecasts reflect documented assumptions regarding HFC phasedown adherence timelines and labor availability in high-growth construction markets. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Polysulfone Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
SBS Modified Bitumen Membrane Market