
 Liquid Roofing Market | 2026-2036
Liquid Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Roofing Market Intelligence
The push for energy-efficient buildings, exemplified by cool roof mandates in cities like Los Angeles and building codes in Australia, is pivoting the market toward reflective liquid roofing solutions. Sika AG leverages its extensive distribution network to serve large-scale commercial projects. BASF SE specializes in advanced polyurethane and acrylic formulations for high-performance applications. Carlisle Companies Incorporated focuses on integrated roofing systems for new construction and reroofing.
Liquid roofing consists of a monolithic, fully-bonded membrane applied in a cold liquid state to a roof surface, curing to form a seamless and waterproof barrier. These systems often incorporate elastomeric polymers to accommodate thermal expansion and contraction. Polyurethane and acrylic formulations lead the product segment due to performance versatility. Application on flat roofs for commercial buildings represents the largest area of consumption.
Product standards are shaped by frameworks like ISO 9001 for quality management and CE marking in Europe, ensuring conformity with safety and performance criteria. In the United States, EPA regulations on Volatile Organic Compounds (VOCs) influence the chemical composition of liquid roofing products. Navigating the diverse regional building codes and environmental certifications will be critical for manufacturers seeking to expand their geographic footprint.
Market Dynamics
The market’s trajectory is defined by the convergence of stringent building energy codes and rapid construction in logistics infrastructure. Demand for high-performance, sustainable roofing solutions is growing in response to both regulatory pressure and the functional needs of modern commercial buildings.
Growth Catalysts
- EU Green Deal:The EU's building renovation policies stimulate demand for energy-efficient liquid roofing to upgrade aging commercial and public buildings.
- Logistics Infrastructure Growth:The build-out of warehouses and data centers for e-commerce creates sustained demand for seamless, waterproof flat roofing systems.
- Cool Roof Regulations:Mandates in jurisdictions like California and Australia create specific demand for solar-reflective formulations to improve building energy efficiency.
Market Restraints
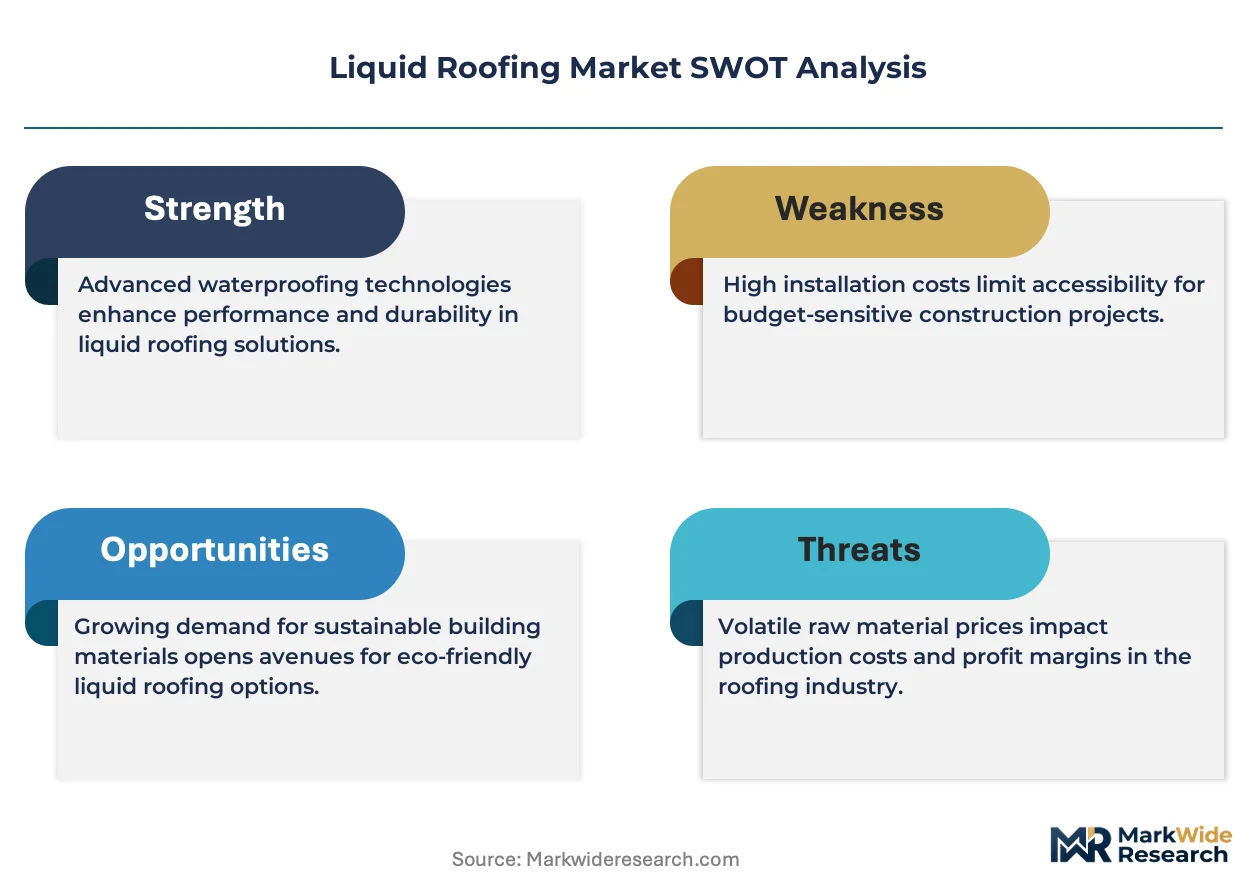
- Raw Material Cost Volatility:The price of key chemical precursors for polyurethane and acrylics, such as isocyanates, is subject to fluctuation, impacting manufacturer margins.
- Application Sensitivity:Product curing is dependent on specific temperature and humidity ranges, constraining installation schedules and increasing weather-related project risk.
- Competition from Sheet Membranes:Lower-cost alternatives like EPDM and TPO membranes present a substitution threat, especially in cost-sensitive new construction projects.
Strategic Opportunities
- Bio-Based Formulations:Developing products with high bio-based content meets rising demand for sustainable materials aligned with circular economy principles.
- Public Infrastructure Renewal:Targeting the refurbishment of aging schools, hospitals, and transit facilities opens a large, stable market beyond commercial real estate.
- Urbanization in New Geographies:Penetrating high-growth urban centers in Southeast Asia and Latin America for new construction offers significant geographic expansion potential.
Industry Challenges
- Skilled Applicator Shortage:A lack of certified installers trained in proper surface preparation and application techniques can lead to premature roof failures and damage brand reputation.
- Fragmented Regulatory Compliance:Manufacturers must navigate a complex and diverse landscape of regional building codes, fire ratings, and environmental certifications like CE marking and local VOC limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Roofing Market |
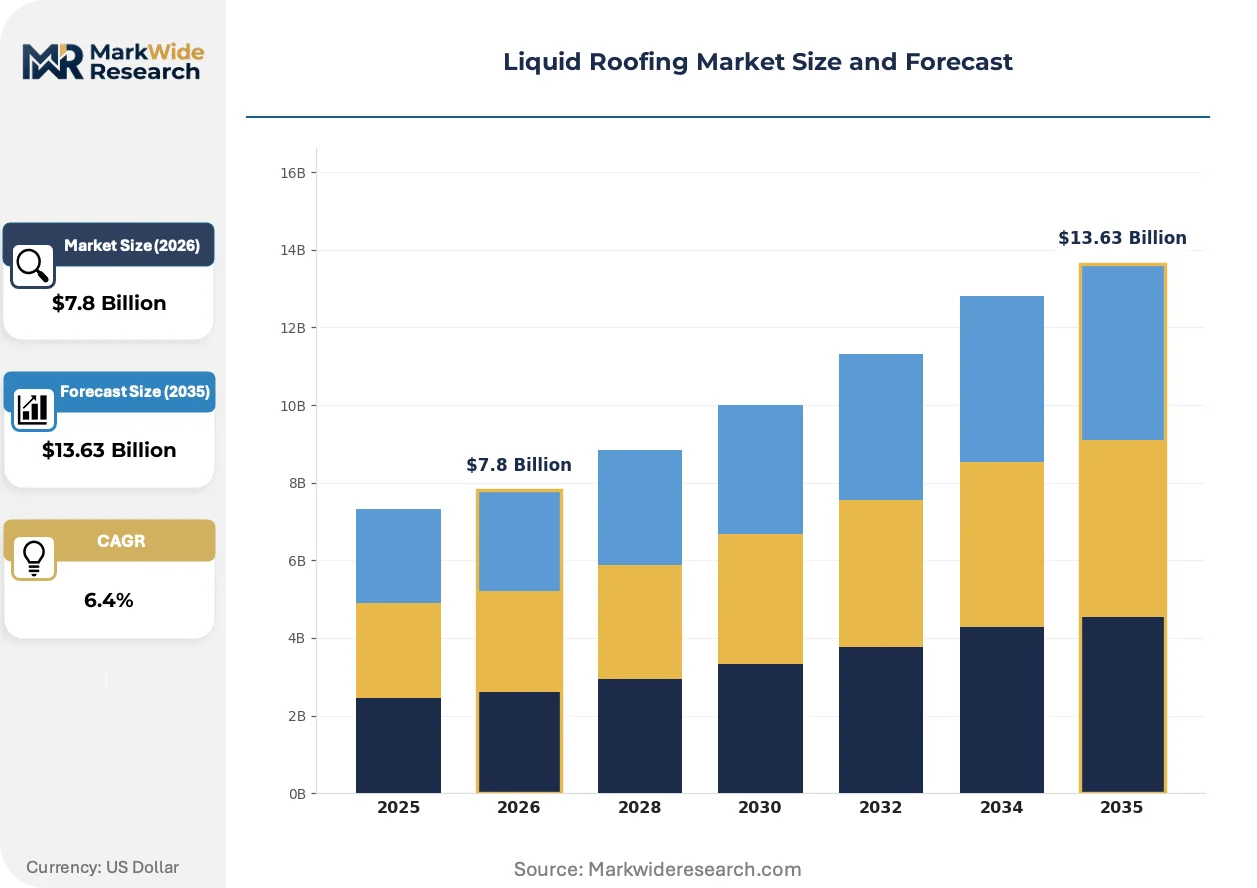
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Bituminous, Silicone, EPDM, Polyurea Application: Flat Roofs, Pitched Roofs, Terraces, Balconies, Basements, Walkways End User Industry: Commercial Buildings, Educational Institutions, Hospitality Venues, Warehousing, Office Complexes, Data Centers Installation Method: Brush Application, Spray Application, Roller Application, Trowel Application, Self-Leveling, Cold Applied |
| Companies Covered | Sika AG, BASF SE, Dow Inc., Saint-Gobain, 3M, Akzo Nobel N.V., GAF Materials, Johns Manville, Carlisle Companies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Roofing Market Strategic Shifts & Innovations
Material science advancements are converging with building lifecycle management priorities, creating roofing systems valued for long-term performance and sustainability. This evolution prioritizes durability and energy efficiency over simple waterproofing, altering product development and specification criteria.
Self-healing polymers incorporate microcapsules that rupture upon damage to fill cracks, autonomously repairing the waterproof membrane. Owners of critical facilities like data centers and hospitals are early adopters, seeking to minimize failure risks. This technology is rewriting lifecycle maintenance models, shifting focus from reactive repairs to passive, built-in resilience.
Stricter regulations on Volatile Organic Compounds (VOCs), such as those enforced by the EPA in the United States and through the REACH framework in Europe, are driving formulation changes. This is forcing a market-wide shift from solvent-based products to water-based, 100% solids, or silicone alternatives. The acrylic and polyurethane segments are most impacted, accelerating R&D into compliant, high-performance chemistries.
Building owners are increasingly specifying roofing systems backed by long-term performance warranties that require installation by manufacturer-certified contractors. This model disrupts the traditional open market for materials and labor, favoring suppliers who offer integrated, warrantied systems. The trend is most prominent in the North American and European commercial reroofing markets.
Liquid Roofing Market Segmentation
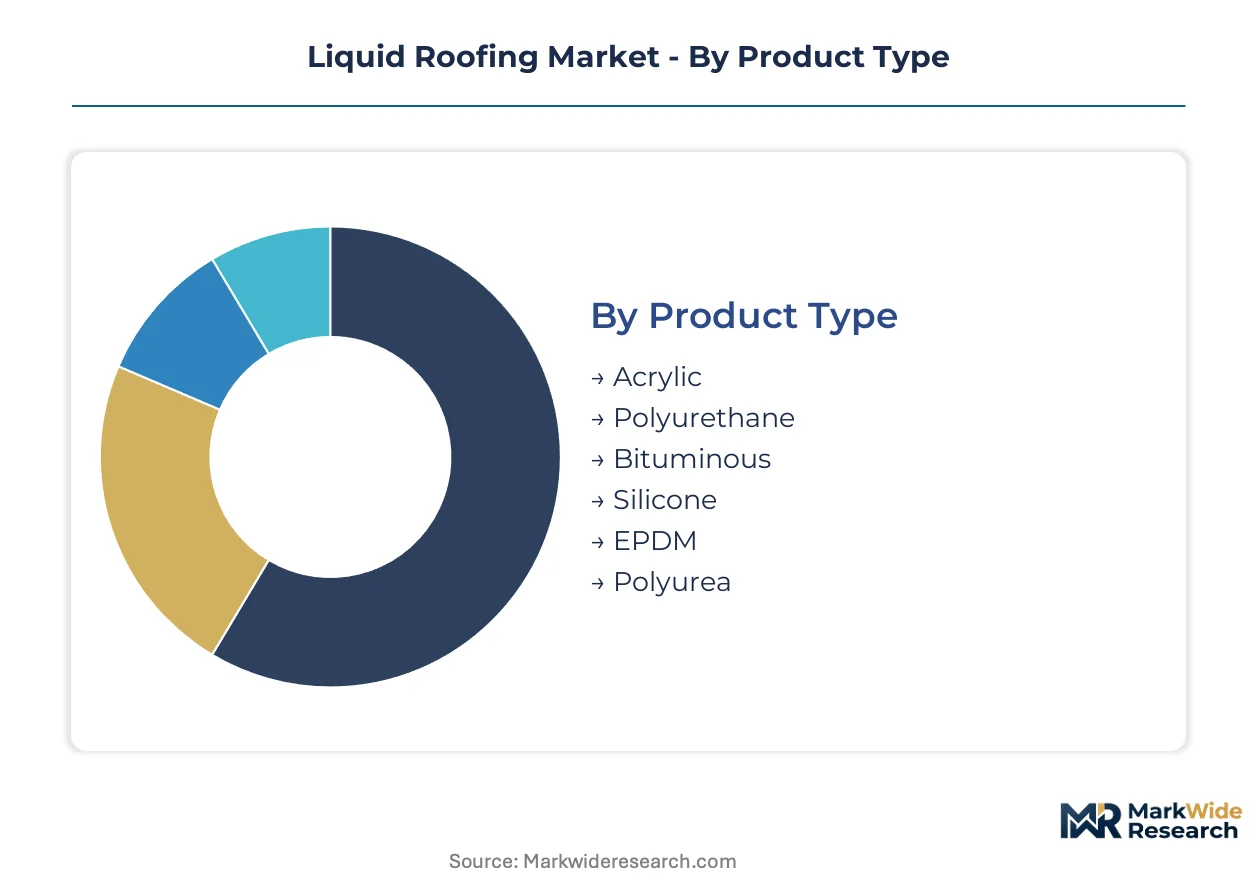
The liquid roofing market segmentation clarifies diverse product attributes and application contexts. Understanding these distinct categories allows manufacturers to tailor formulations and sales strategies to specific performance requirements and end-user demands across various construction projects.
Product Type:
The product type segment spans a spectrum from highly customizable, specialized chemistries to more standardized, general-purpose solutions.
- Polyurethane:These formulations offer exceptional elasticity and abrasion resistance, ideal for high-performance applications on commercial and industrial roofs. Demand concentrates in Europe, driven by stringent energy efficiency standards and long-term durability requirements for data centers.
- Acrylic:Water-based acrylics provide excellent UV stability and reflectivity, making them suitable for cool roof applications in warmer climates. The United States market sees strong demand for acrylics due to cool roof mandates in cities like Los Angeles.
- Bituminous:Modified bitumen liquid systems provide robust waterproofing for existing asphaltic substrates, often used in refurbishment projects.
- Silicone:Silicone coatings offer superior UV resistance and remain flexible across extreme temperature fluctuations, extending roof lifespan.
- EPDM:Liquid EPDM systems provide seamless waterproofing, often used for detailing around penetrations on existing EPDM sheet membranes.
- Polyurea:Polyurea systems cure rapidly and offer high chemical resistance, making them suitable for demanding industrial environments and rapid repairs.
Leading the category by volume: Polyurethane. Growing fastest: Silicone.
Application:
The application segment reflects how liquid roofing solutions adapt to diverse architectural designs and functional needs of building envelopes.
- Flat Roofs:These applications represent the largest consumption area for liquid roofing, providing seamless, monolithic waterproofing for commercial and industrial buildings. Logistics infrastructure development in China significantly drives demand for flat roof solutions.
- Pitched Roofs:Liquid systems offer an effective overlay solution for existing pitched roofs, providing a durable, lightweight, and aesthetically pleasing finish without extensive structural modifications. European building renovation initiatives stimulate demand for pitched roof applications.
- Terraces:Liquid membranes are ideal for waterproofing terraces, offering pedestrian traffic resistance and aesthetic versatility for urban developments.
- Balconies:These systems provide durable and waterproof surfaces for balconies, protecting underlying structures from water ingress.
- Basements:Liquid roofing formulations can be applied as tanking membranes for basement waterproofing, preventing moisture penetration below ground level.
- Walkways:Liquid coatings provide anti-slip and protective layers for pedestrian walkways on roofs and other elevated surfaces.
Flat roofs dominate consumption, while terraces show significant expansion.
End User Industry:
End-user industry segmentation highlights how specific sector requirements influence the choice and specification of liquid roofing products.
- Commercial Buildings:This segment encompasses a broad range of structures, including retail spaces and corporate offices, requiring durable and long-lasting roofing solutions. The commercial construction boom in Southeast Asia fuels demand for liquid roofing systems.
- Warehousing:The rapid expansion of e-commerce drives significant demand for liquid roofing in warehousing and logistics centers, prioritizing seamless, waterproof, and easily maintainable flat roofs. India's growing logistics sector is a key market for these applications.
- Educational Institutions:Schools and universities require robust, low-maintenance roofing systems that ensure building integrity and minimize disruption during installation.
- Hospitality Venues:Hotels and resorts utilize liquid roofing for aesthetic appeal and long-term weather protection on complex roof designs and amenity spaces.
- Office Complexes:Modern office complexes demand energy-efficient and sustainable roofing solutions that contribute to overall building performance and tenant comfort.
- Data Centers:Critical infrastructure like data centers require highly reliable, self-healing, and long-warrantied liquid roofing systems to protect sensitive equipment.
Commercial buildings represent the largest end-user segment, with data centers demonstrating rapid uptake.
Installation Method:
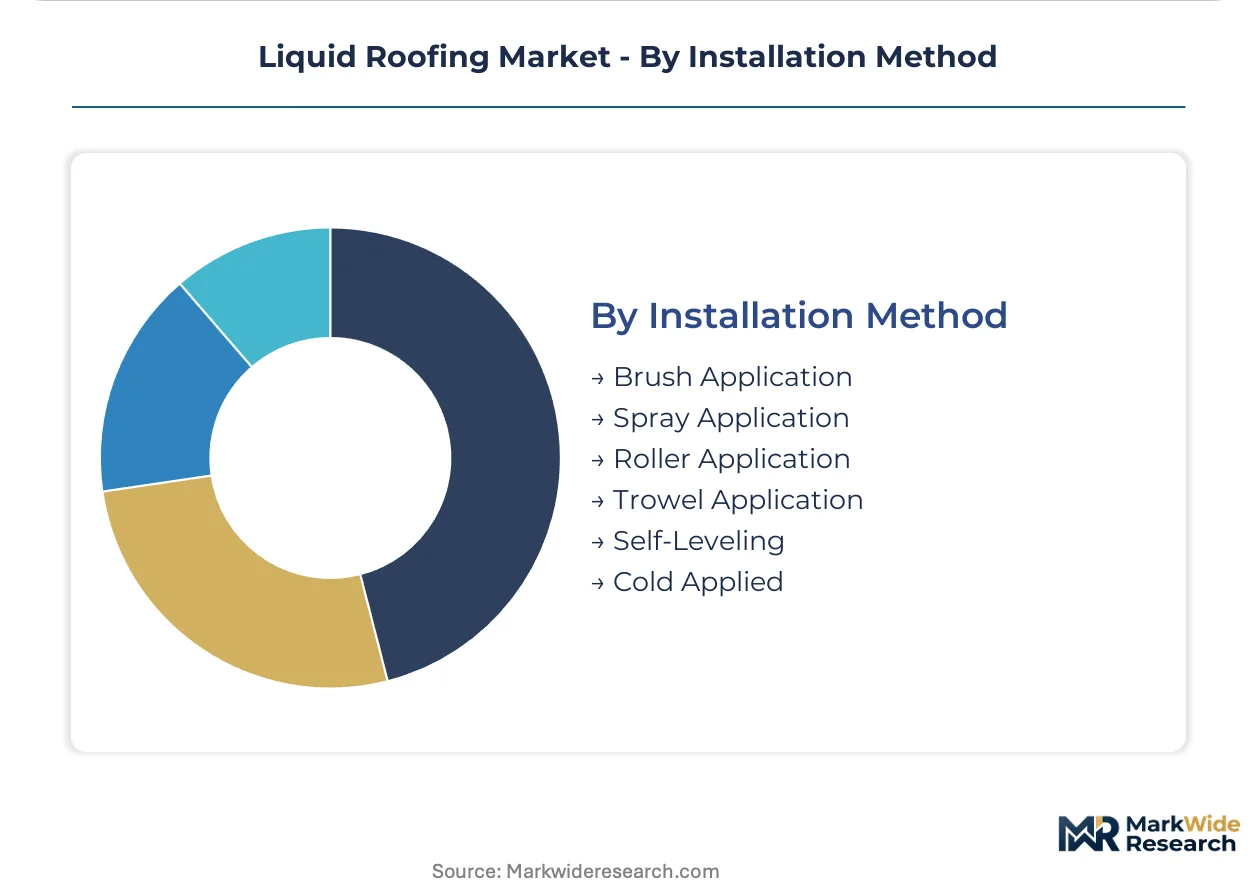
The installation method segment is shaped by project scale, surface complexity, and site-specific environmental conditions.
- Spray Application:This method offers high efficiency and rapid coverage for large, unobstructed roof areas, minimizing labor time on major commercial projects. Large-scale warehouse construction in the United States frequently utilizes spray application.
- Cold Applied:These systems are applied without heat, enhancing safety and reducing fire risk on sites with sensitive equipment or occupied spaces. European regulations, including aspects of the EU Green Deal, favor cold-applied methods for renovation projects.
- Brush Application:Brush application is suitable for intricate detailing, small repairs, and areas with restricted access where precision is critical.
- Roller Application:Rollers provide a balanced approach, offering good coverage for medium-sized areas while maintaining control over material thickness.
- Trowel Application:Trowel application is used for thicker coatings, detailing, or creating specific profiles, often for repairs or specialized membranes.
- Self-Leveling:Self-leveling formulations create smooth, even surfaces on horizontal applications, often used for balconies and walkways before final topcoats.
Spray application offers efficiency for large projects, while cold applied methods gain traction due to safety benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapid urbanization and industrial expansion significantly influence the liquid roofing market across the Asia-Pacific region. Extensive urban renewal and commercial construction projects in the country drive substantial demand for advanced roofing solutions. This growth trajectory underscores the critical role of key national economies in shaping global liquid roofing consumption patterns.
China
Extensive urban renewal and commercial construction projects generate strong demand for liquid roofing systems in China. The country's dual carbon goals, enforced by the Ministry of Ecology and Environment (MEE), encourage energy-efficient building materials. The Yangtze River Delta region, with its dense logistics infrastructure, sees high adoption of seamless flat roofing solutions.
United States
Cool roof mandates in cities like Los Angeles and the expansion of large-scale warehousing facilities drive liquid roofing demand across the United States. EPA regulations on Volatile Organic Compounds (VOCs) influence product formulations toward compliant, low-emission solutions. California's building codes, particularly in major metropolitan areas, promote solar-reflective acrylic coatings.
Germany
Stringent energy efficiency standards and the need for long-term durability in commercial and industrial structures define the German market. CE marking ensures product conformity, while EU Green Deal initiatives stimulate renovation projects. North Rhine-Westphalia, a major industrial hub, prioritizes high-performance polyurethane systems for its diverse building stock.
India
India's growing logistics sector and rapid infrastructure development create substantial demand for liquid roofing, particularly for warehousing and commercial buildings. The Bureau of Indian Standards (BIS) sets quality benchmarks for construction materials. The Delhi-NCR region experiences significant uptake due to its expanding commercial and industrial footprint.
France
EU Green Deal renovation initiatives and public infrastructure renewal projects stimulate liquid roofing demand in France. The REACH framework guides the chemical composition of products, favoring sustainable formulations. The Île-de-France region, encompassing Paris, drives demand for advanced systems in both new construction and refurbishment of public and commercial buildings.
Liquid Roofing Market Key Industry Players
Premium-margin players sit above commodity-margin players across product performance and application complexity in the liquid roofing market. The competitive structure includes integrated systems providers, specialized formulators, and broad material suppliers. Companies pursue portfolio diversification and geographic expansion to solidify their market positions and capture new opportunities.
On the premium-tier vector, Sika AG leverages its extensive distribution network to serve large-scale commercial projects, offering integrated solutions. BASF SE occupies a position as a specialized formulator, providing advanced polyurethane and acrylic formulations for high-performance applications. Carlisle Companies Incorporated exemplifies a focus on integrated roofing systems for new construction and reroofing, particularly within North American and European markets.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Dow Inc. |
| Saint-Gobain |
| 3M |
| Akzo Nobel N.V. |
| GAF Materials |
| Johns Manville |
| Carlisle Companies Incorporated |
| Others |
Cost & Logistics Intelligence
Performance-tier differentiation in liquid roofing solutions drives pricing power for advanced formulations, while commodity-grade products face intense cost competition. This divergence shapes procurement strategies and raw material sourcing across the supply chain.
Pricing Analysis
Long-term performance warranties anchor pricing for premium liquid roofing systems, reflecting their extended lifespan and reduced maintenance costs. Price differentiation stems from formulation complexity, such as self-healing polymers, and manufacturer certification requirements for installation. Cost compression in standard acrylic formulations intensifies due to competition from sheet membranes. Commercial building owners are less price-sensitive for critical infrastructure like data centers, while new construction projects often prioritize initial cost.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of liquid roofing materials, especially for bulky raw chemicals. Supply concentration for key chemical precursors like isocyanates and specialized acrylic monomers centers in China and Germany. The market relies on a globalized chemical supply chain, creating structural risk from commodity price volatility. Downstream distribution runs through a network of specialized distributors and manufacturer-certified applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates with supply constraints, particularly for advanced chemical precursors, which props up pricing for high-performance liquid roofing systems. Raw material cost volatility further accentuates this dynamic.
For Market Incumbents:Anchor market share by expanding geographic presence in high-growth urban centers like Southeast Asia, leveraging existing distribution networks. Consolidate strategic raw material sourcing to mitigate price volatility from chemical precursors, protecting profit margins from external shocks. Invest in R&D for bio-based formulations to counter regulatory threats from VOC limits. Control certified applicator networks to differentiate from lower-cost, less reliable alternatives.
For New Entrants and Emerging Players:Begin with targeting niche applications requiring specialized performance, such as self-healing polymers for critical infrastructure like data centers. Penetrate underserved refurbishment markets in aging public facilities in Europe, offering sustainable, cold-applied solutions. Focus on a direct-to-specifier go-to-market angle, educating architects and engineers on lifecycle cost benefits. The most penetrable segment is public infrastructure renewal due to long-term government investment cycles.
For Investors and Strategic Acquirers:Exit pathways concentrate in vertically integrated specialists offering proprietary formulations and certified installation services. The market demonstrates long-term viability driven by global urbanization and stringent energy efficiency mandates for buildings. Acquisition targets are mid-sized formulators with strong regional distribution and a focus on low-VOC or bio-based chemistries. A signal to watch is the widespread adoption of circular economy principles in building codes, favoring sustainable material innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand in China for flat roof solutions. |
| Bio-based Formulation R&D | Meets EU Green Deal requirements for sustainable building materials. |
| Certified Applicator Training Programs | Mitigates skilled labor shortages in the United States. |
| Strategic Raw Material Sourcing | Stabilizes input costs for polyurethane and acrylics. |
| Digital Specification Tools | Enhances product selection and project management for commercial buildings. |
Research Approach
Document review covered industry reports, company investor presentations, and regulatory filings from EPA and MEE, complemented by interviews with industry executives and certified applicators. Primary research included discussions with R&D directors, procurement managers at commercial building firms, and project managers for data center construction. Data was triangulated using both bottom-up market sizing and top-down validation through expert panel discussions.
Historical market data was cross-referenced against expert panel input to project future market trajectories across the analysis window. The analytical framework modeled segmentation by product type, application method, and end-user industry, alongside regional adoption patterns. Compound Annual Growth Rates were derived from a weighted average of historical trends and anticipated regulatory impacts. Forecast inputs included projected e-commerce growth rates and global construction spending.
Underlying measurement precision varies by segment; established product types like polyurethane and acrylic carry tighter precision than emerging silicone or polyurea. Forecasts reflect assumptions regarding raw material availability and regulatory stability. Geopolitical events or unforeseen technological disruptions represent risk factors that could revise these projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Breather Membranes Market