
 Global Roofing Membranes Market | 2026-2036
Global Roofing Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Roofing Membranes Market Foresight
Building material distribution through specialized roofing contractors is rewriting procurement patterns across developed economies. Carlisle SynTec Systems leverages its captive manufacturing network to control specification-grade product flow. Sika AG anchors European supply through its adhesives and membrane integration strategy. GAF Materials LLC competes on residential-to-commercial brand extension and contractor loyalty programs.
Roofing membranes are synthetic sheet materials—typically thermoplastic polyolefin, EPDM rubber, or modified bitumen composites ranging from 45 to 90 mils in thickness—engineered to create watertight barriers over structural roof decks. These membranes prevent moisture infiltration, reduce thermal transfer, and extend building envelope service life across commercial and institutional structures. Thermoplastic polyolefin dominates specification activity for its heat-weldable seams and reflective surface properties, while modified bitumen sustains share in renovation markets where torch-applied familiarity reduces installer retraining costs. Ethylene propylene diene monomer occupies niche positions in climates with extreme temperature cycling due to its elastomeric recovery.
FDA standards for manufacturing facility roofing indirectly shape membrane selection in pharmaceutical and food processing construction, while EPA stormwater regulations push commercial owners toward reflective, durable roof surfaces that reduce runoff thermal loading. REACH compliance in Europe restricts certain plasticizer chemistries in PVC membrane formulations, forcing reformulation investments. Stakeholders must monitor evolving building code adoptions across municipalities and assess whether material certification investments align with regional enforcement trajectories.
Market Dynamics
The EU Green Deal's building performance mandates are forcing wholesale material substitution across European commercial envelopes, while US and Chinese code tightening on aging stock retrofits concentrates demand in specification-grade thermoplastic systems.
Growth Catalysts
- REACH plasticizer restrictions:European reformulation requirements are accelerating PVC membrane replacement with TPO and EPDM alternatives that command specification premiums.
- Food processing construction:FDA facility roofing standards indirectly mandate membrane systems with validated microbial resistance and thermal stability documentation.
- Stormwater thermal loading rules:EPA regulations on commercial runoff are pushing reflective membrane adoption across US municipal jurisdictions.
Market Restraints
- Petrochemical feedstock volatility:TPO and EPDM production costs track ethylene and propylene price swings that compress manufacturer margins unpredictably.
- Installer certification bottlenecks:Heat-weldable seam technologies require trained technician pools that concentrate in Germany and the United States.
- Modified bitumen substitution resilience:Torch-applied familiarity in renovation markets slows thermoplastic conversion despite performance advantages.
Strategic Opportunities
- India building code modernization:BIS energy efficiency mandates for commercial envelopes create first-mover advantage for reflective membrane specification.
- Green bond financing integration:EU taxonomy alignment allows membrane manufacturers to bundle product sales with sustainability-linked construction finance.
- Drone-enabled inspection services:Automated membrane integrity assessment creates recurring revenue attachment to material sales.
Industry Challenges
- Heat-welding technician scarcity:TPO seam certification programs cannot scale to match installation demand in rapidly retrofitting US metropolitan markets.
- Multi-jurisdictional code fragmentation:Municipal waterproofing standards vary across Chinese provinces, forcing redundant product testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Roofing Membranes Market |
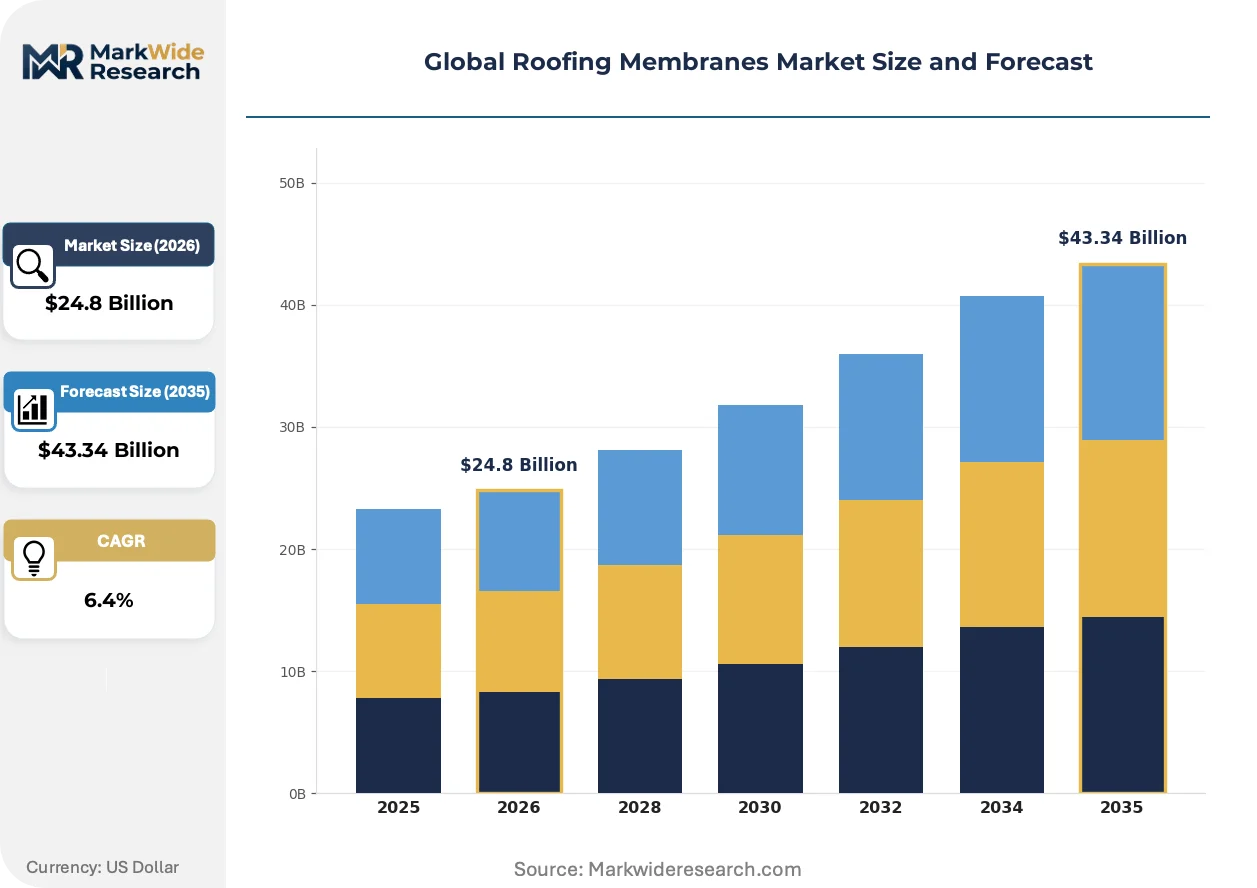
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Polyolefin, Ethylene Propylene Diene Monomer, Polyvinyl Chloride, Modified Bitumen, Spray Polyurethane Foam Application: Commercial Buildings, Institutional Buildings, Industrial Facilities, Public Infrastructure Installation Method: Fully Adhered, Mechanically Attached, Ballasted, Self-Adhered End User: Roofing Contractors, Property Developers, Facility Managers, Building Maintenance |
| Companies Covered | Carlisle SynTec Systems, GAF Materials LLC, Sika AG, Soprema Group, Standard Industries Inc., Firestone Building Products Company LLC, Owens Corning, Johns Manville, Henry Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Roofing Membranes Market Shifts & Advancements
Digital specification tools and automated installation quality systems are compressing the traditional contractor-manufacturer information asymmetry that once governed membrane selection.
Building information modeling integration is virtualizing membrane specification workflows. Architects and envelope engineers now embed TPO performance datasets directly into digital twins during schematic design. Large commercial developers in Germany and the United States are mandating BIM-native product libraries that bypass traditional distributor influence. This is virtualizing the legacy specification chain that relied on contractor-driven material selection.
REACH Annex XVII plasticizer restrictions are eliminating legacy PVC formulations from European pharmaceutical and food processing construction. ECHA enforcement timelines are compressing manufacturer reformulation investments into 18-month windows. German membrane producers are accelerating bio-based plasticizer R&D while TPO suppliers capture displaced specification volume.
Performance-guarantee contracting is displacing transactional material sales in US commercial roofing. Building owners now procure 20-year watertightness outcomes rather than membrane sheets, bundling installation, monitoring, and repair liability. This model concentrates volume with vertically integrated manufacturers capable of underwriting long-term risk.
Global Roofing Membranes Market Segmentation
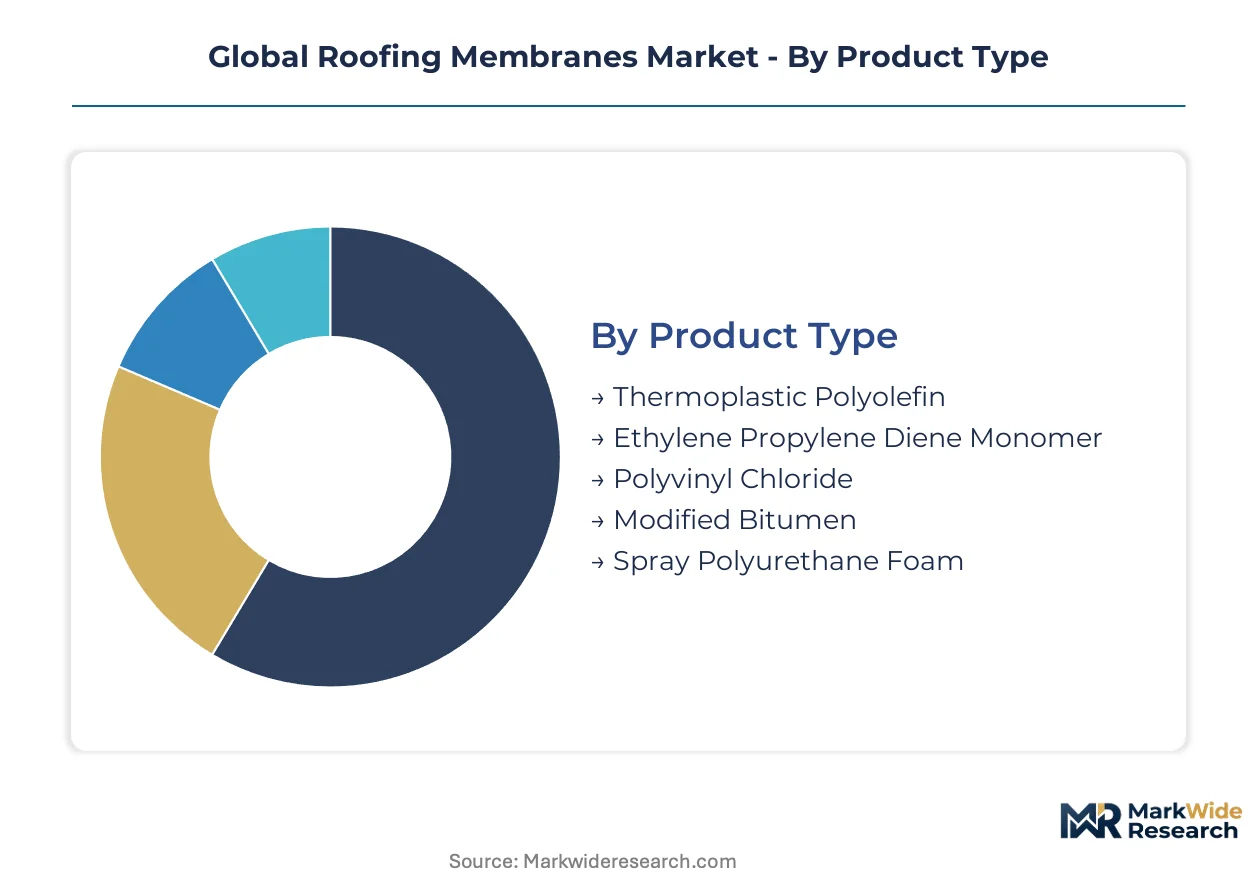
Membrane specification varies sharply across building typologies and installation constraints. Product chemistry, application setting, and procurement channel each reshape margin structures and competitive positioning for manufacturers.
Product Type:
Cost tier differentiation separates specification-grade systems from economy alternatives across commercial bidding.
- Thermoplastic Polyolefin:Heat-weldable polyolefin sheets deliver seam integrity without adhesive dependence. Demand concentrates in United States commercial retrofits where reflective surfaces satisfy EPA stormwater thermal loading rules and reduce cooling loads.
- Ethylene Propylene Diene Monomer:Elastomeric rubber membranes accommodate extreme temperature cycling through molecular recovery. German and Chinese specifications favor EPDM for industrial facilities where chemical resistance and dimensional stability outweigh first-cost premiums.
- Polyvinyl Chloride:Flexible vinyl systems face REACH Annex XVII plasticizer restrictions across European pharmaceutical construction. Reformulation investments compress manufacturer margins while accelerating displacement toward TPO alternatives.
- Modified Bitumen:Asphalt-rubber composites sustain share in renovation markets where torch-applied installation familiarity reduces contractor retraining requirements.
- Spray Polyurethane Foam:Liquid-applied systems create seamless monolithic barriers for complex geometries and irregular substrates.
Thermoplastic polyolefin holds installed capacity. Ethylene propylene diene monomer is rotating up the share rankings.
Application:
Volume concentration tracks building stock age and code enforcement intensity across municipal jurisdictions.
- Commercial Buildings:Office and retail structures drive specification-grade membrane demand through large footprint economies. United States metropolitan markets concentrate retrofit activity as aging stock triggers waterproofing code upgrades and insurance-driven replacement cycles.
- Institutional Buildings:Schools and hospitals require validated microbial resistance documentation under FDA facility roofing standards. German envelope specifications prioritize thermoplastic systems with 20-year performance guarantees in public procurement frameworks.
- Industrial Facilities:Manufacturing plants select membranes based on chemical exposure profiles and process thermal loading.
- Public Infrastructure:Government-owned assets face extended procurement cycles with lifecycle cost evaluation mandates.
Commercial buildings hold installed capacity. Institutional buildings are rotating up the share rankings.
Installation Method:
Customer type determines attachment specification — owner-operated assets favor low-maintenance systems while developer-held properties prioritize speed-to-weather.
- Fully Adhered:Complete substrate bonding eliminates fastener penetrations and maximizes wind uplift resistance. United States coastal specifications mandate adhered systems for hurricane-prone zones where mechanical attachment risks membrane displacement.
- Mechanically Attached:Fastener-based installation accelerates deployment across large flat roofs with accessible structural decks. Chinese commercial construction favors mechanical systems for speed advantages in rapid urban development cycles.
- Ballasted:Gravel or paver weighting avoids adhesive and fastener dependence entirely.
- Self-Adhered:Pressure-sensitive backing reduces labor skill requirements and eliminates open-flame equipment.
Fully adhered holds installed capacity. Mechanically attached is rotating up the share rankings.
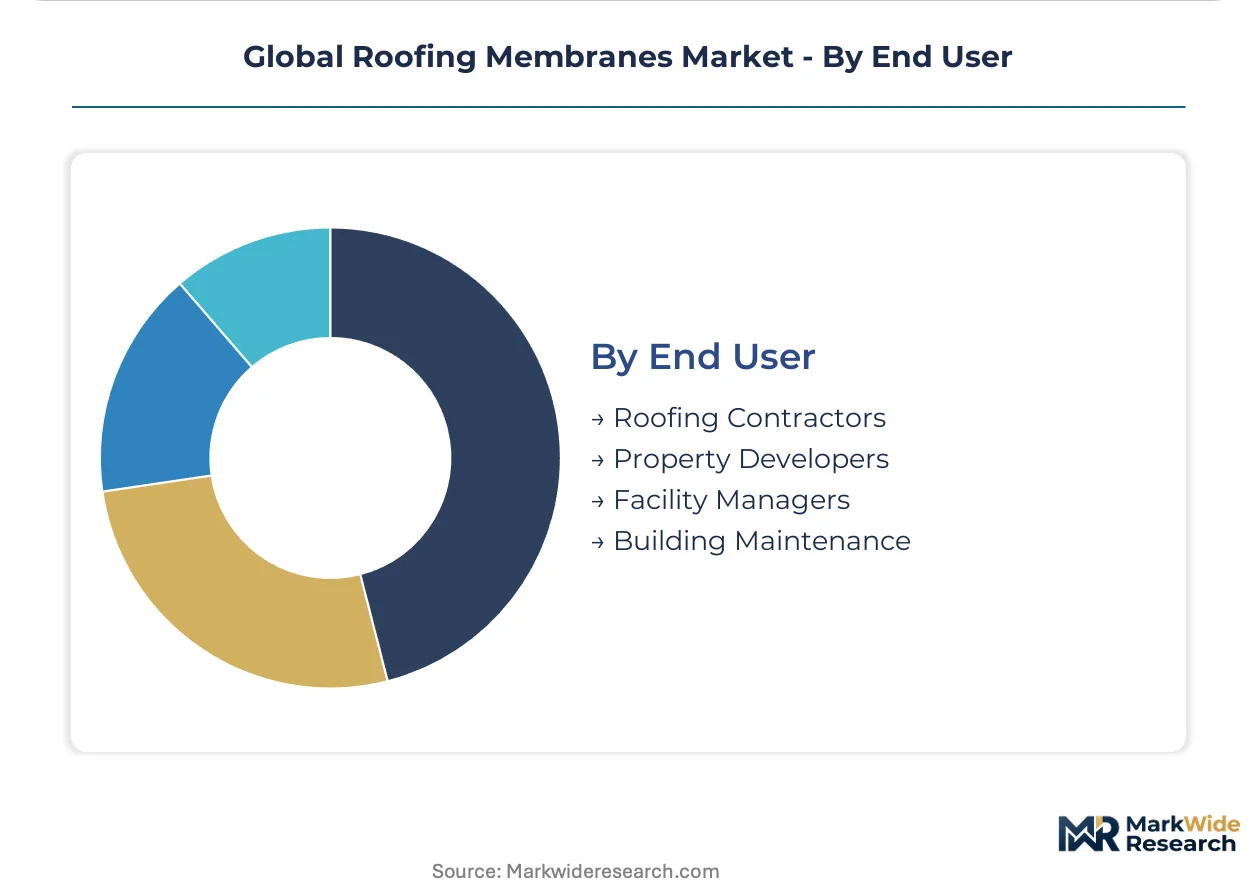
End User:
Supply concentration varies by procurement sophistication and technical evaluation capacity across buyer categories.
- Roofing Contractors:Specialized installers control material specification through distributor relationships and manufacturer certification programs. German and United States markets concentrate trained technician pools for heat-weldable seam technologies that gate TPO adoption.
- Property Developers:Speculative construction prioritizes first-cost minimization and speed-to-occupancy over lifecycle performance. Chinese developers bundle membrane procurement with general contractor packages that obscure material origin.
- Facility Managers:Owner-operated assets prioritize predictive maintenance integration and warranty transferability.
- Building Maintenance:Reactive repair demand sustains modified bitumen and self-adhered alternatives for localized remediation.
Roofing contractors hold installed capacity. Property developers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German specification-grade markets while Chinese volume plays compress margins through rapid urban development cycles. The United States commands retrofit premiums through insurance-driven replacement mandates. India and Brazil emerge as code-modernization frontiers where first-mover positioning determines specification capture.
United States
Commercial building stock aging concentrates demand in metropolitan retrofit corridors across the Northeast and Midwest. EPA stormwater thermal loading rules push reflective membrane adoption in municipal jurisdictions. Miami and Houston clusters drive specification-grade TPO demand through hurricane-prone wind uplift codes.
Germany
EU Green Deal building performance mandates accelerate thermoplastic substitution across commercial envelopes. ECHA REACH Annex XVII enforcement eliminates legacy PVC formulations from pharmaceutical construction. The Rhine-Ruhr industrial corridor anchors specification-grade membrane demand through 20-year performance guarantee procurement frameworks.
China
Rapid urban commercial construction favors mechanically attached systems for speed-to-weather advantages. MEE dual carbon goals tighten building envelope energy efficiency standards in tier-one cities. The Yangtze River Delta cluster concentrates membrane fabrication capacity serving domestic retrofit and new-build demand.
India
BIS energy efficiency mandates for commercial envelopes create specification-grade entry opportunities. CDSCO facility standards indirectly shape membrane selection in pharmaceutical construction through validated microbial resistance requirements. The Delhi-NCR and Mumbai metropolitan regions concentrate retrofit activity as aging stock triggers waterproofing upgrades.
Brazil
ANVISA pharmaceutical facility standards drive validated membrane documentation in food processing construction. Municipal building code modernization across São Paulo and Rio de Janeiro creates reflective membrane specification windows. The Southeast industrial corridor anchors demand through manufacturing facility expansion and export-oriented logistics infrastructure.
Global Roofing Membranes Market Competitive Landscape
Vertically integrated membrane manufacturers and specialty chemical conglomerates split the market through divergent route-to-market strategies. Consolidation concentrates specification-grade volume among captive manufacturing networks while regional fabricators compete on renovation economy tiers. Three archetypes dominate: integrated building envelope specialists, diversified construction chemical platforms, and polymer-focused membrane pure-plays. Competitive dynamics center on specification capture through contractor certification programs and backward integration into polymer compounding operations.
Among North American integrated specialists, Carlisle SynTec Systems and GAF Materials LLC occupy positions defined by captive manufacturing control and contractor loyalty program scale. Sika AG anchors the European diversified chemical platform archetype through adhesives-membrane integration strategies. These three exemplify how geographic manufacturing footprint and specification-channel depth determine competitive positioning across retrofit-driven versus new-build market cycles.
| Leading Market Players |
|---|
| Carlisle SynTec Systems |
| GAF Materials LLC |
| Sika AG |
| Soprema Group |
| Standard Industries Inc. |
| Firestone Building Products Company LLC |
| Owens Corning |
| Johns Manville |
| Henry Company |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese TPO membrane fabrication is compressing global pricing discipline while forcing European and North American producers toward specification-grade differentiation. Utilization rates below nameplate capacity in the Yangtze River Delta cluster are triggering export-oriented volume dumping that reshapes procurement negotiations across developed markets.
Pricing Analysis
The customization-premium spread separates configured-to-order specification systems from standard roll goods by fifteen to twenty-five percentage points. Three-tier pricing structure across premium, standard, and economy levels dominates commercial bidding, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy-tier mechanically attached systems is intensifying because Chinese export volumes are absorbing regional distributor margins. Property developers exhibit highest price sensitivity through bundled general contractor procurement, while institutional facility managers prioritize lifecycle performance over first cost.
Supply Chain Analysis
Export-control regime friction around advanced polymer compounding equipment is fragmenting technology transfer flows between German machinery builders and Asian fabricators. Geographic supply concentrates in China, Germany, and the United States, with ethylene and propylene feedstock dependencies tethering membrane producers to petrochemical complex economics. Single-source vulnerability in specialized heat-welding equipment creates chokepoint exposure for TPO specification-grade output. Distribution runs through specialized roofing contractor networks that control specification influence in developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large commercial developers and facility management platforms that consolidate procurement across multi-site portfolios. This consolidation is compressing distributor margins and forcing manufacturers toward direct specification relationships.
For Market Incumbents: Entrench specification capture through captive heat-welding technician certification programs that gate TPO adoption in retrofit-heavy US metropolitan markets. Deepen backward integration into polymer compounding to defend margin position against ethylene price volatility. Accelerate bio-based plasticizer R&D to preempt ECHA REACH Annex XVII enforcement timelines that threaten legacy PVC formulations.
For New Entrants and Emerging Players: India's underpenetrated specification-grade membrane market offers first-mover positioning as BIS energy efficiency mandates modernize commercial envelope standards. Target CDSCO-compliant pharmaceutical facility construction in Delhi-NCR and Mumbai metropolitan regions where validated microbial resistance documentation commands premium pricing. Pursue drone-enabled inspection service bundling to create recurring revenue attachment alongside material sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers capable of underwriting 20-year performance guarantee contracts. Long-term viability hinges on specification-channel depth rather than volume scale across commodity renovation tiers. Monitor ECHA enforcement acceleration and US municipal stormwater code adoption as inflection indicators for thermoplastic substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Welding Technician Certification Scale-Up | Carlisle SynTec Systems and GAF Materials LLC are expanding training capacity to match TPO retrofit demand in hurricane-prone US coastal zones. |
| Bio-Based Plasticizer Reformulation Investment | German membrane producers are accelerating R&D to capture PVC displacement volume under ECHA REACH Annex XVII enforcement. |
| Drone-Enabled Membrane Integrity Services | Automated inspection platforms create recurring revenue attachment that displaces transactional material-only sales models. |
| Backward Integration into Polymer Compounding | In-house ethylene-propylene control insulates margin structures from petrochemical feedstock volatility. |
| Green Bond Financing Product Bundling | EU taxonomy alignment allows sustainability-linked construction finance packaging with specification-grade membrane sales. |
Research Methodology
Initial hypotheses were tested against primary input from roofing contractor operations managers, commercial facility procurement directors, building envelope specification engineers, and polymer compounding technical leads and refined through secondary validation against customs trade data, ECHA regulatory filings, SEC 10-K disclosures from listed building material groups, and municipal building code adoption records. Bottom-up volume estimates from installation activity were triangulated against top-down capacity assessments from membrane fabrication facilities.
Demand-supply-balance dynamics across the analysis window were modeled through segmentation by product chemistry, installation method, building typology, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, code enforcement intensity trajectories, and material substitution elasticity parameters. Forecast inputs incorporated petrochemical feedstock price correlation coefficients and technician certification program scaling constraints.
Practitioners should monitor ECHA enforcement acceleration, US municipal stormwater thermal loading rule adoption, and Indian BIS code modernization timelines for early signals of specification shift. Material shifts in REACH plasticizer restriction scope or EPA stormwater regulatory stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Microporous Materials Market