
 Reverse Osmosis (RO) Membrane Market | 2026-2036
Reverse Osmosis (RO) Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Osmosis (RO) Membrane Market Intelligence
A shift from single-source membrane procurement to multi-source qualification programs is repositioning how engineering firms manage supply risk for large desalination projects. DuPont leverages its integrated polymer science capabilities to sustain filmtec membrane performance leadership across high-salinity applications. Hydranautics anchors its competitive position through specialized seawater and brackish water product lines with extended operating lifespans. TORAY INDUSTRIES, INC. dominates the Asian project landscape through captive fiber spinning and module assembly operations.
Reverse osmosis membranes are semi-permeable barriers, typically thin-film composite polyamide layers on polysulfone supports, that reject dissolved salts and contaminants when feedwater is pressurized beyond osmotic pressure; they achieve salt rejection rates exceeding 99.5% in standard seawater configurations. Spiral wound modules occupy the largest share of installed capacity due to their favorable balance of packing density and pressure tolerance in municipal and industrial plants. Polyamide thin-film composites represent the fastest-growing material category as operators seek higher flux rates and improved chlorine resistance. Desalination applications command premium pricing positions because of extreme operating pressures and membrane replacement frequency.
The EPA enforces maximum contaminant levels that directly determine membrane selection criteria for US municipal systems, while REACH and the EU Drinking Water Directive shape material compliance requirements across European installations. China's MEE implements discharge standards that compel industrial facilities to adopt advanced membrane-based zero-liquid-discharge configurations. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance regulations constrain membrane chemistries and open substitution opportunities for novel surface modifications.
Market Dynamics
Membrane replacement cycles are compressing as municipal utilities confront tightening potable water standards and industrial operators face zero-liquid-discharge mandates. This regulatory pressure cascade is restructuring procurement patterns toward multi-source qualification programs.
Growth Catalysts
- EPA National Primary Drinking Water Regulations:Maximum contaminant level enforcement compels US municipal systems to upgrade membrane infrastructure, accelerating replacement demand across aging treatment plants.
- Seawater desalination infrastructure:China's coastal provinces are scaling membrane-based capacity to relieve industrial water stress, concentrating project awards in Shandong, Jiangsu, and Zhejiang.
- Thin-film composite polyamide chemistry:Higher flux rates and improved chlorine resistance enable longer operating intervals, reducing lifecycle costs for high-salinity applications.
Market Restraints
- Petrochemical feedstock volatility:Polysulfone support substrate production depends on benzene and bisphenol-A supply chains exposed to crude price swings.
- Asian module assembly concentration:Captive fiber spinning and spiral-wound manufacturing cluster in China, Japan, and South Korea, creating geographic supply risk for non-Asian project developers.
- Per- and polyfluoroalkyl substance constraints:Evolving restrictions on fluorinated chemistries limit surface modification options for fouling-resistant membranes.
Strategic Opportunities
- India's industrial water reuse:Central Pollution Control Board mandates are driving adoption of membrane-based zero-liquid-discharge systems in textile and pharmaceutical clusters around Ahmedabad and Tiruppur.
- Brackish water agricultural irrigation:California's Central Valley and Texas High Plains operators are retrofitting treatment trains for crop-compatible salinity levels.
- Antifouling surface coatings:Graphene oxide and zwitterionic polymer convergences promise extended cleaning intervals in high-organic feedwaters.
Industry Challenges
- Membrane autopsy technician shortage:Specialized failure-analysis capabilities remain concentrated at original equipment manufacturers, delaying root-cause identification for premature fouling or oxidation.
- Legacy SCADA integration:Predictive maintenance algorithms for membrane trains require retrofitting analog-era distributed control systems common in 1990s-era municipal plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Osmosis (RO) Membrane Market |
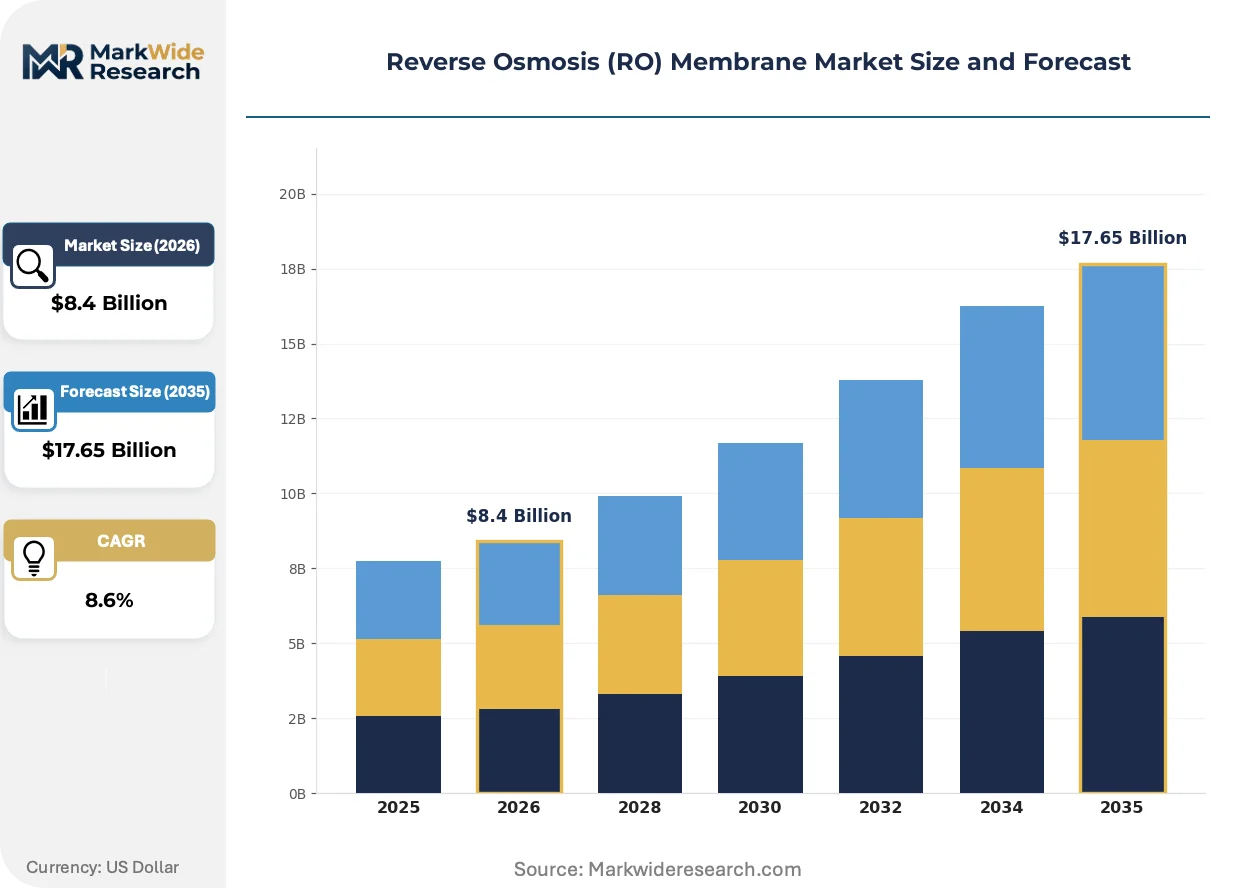
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.65 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiral Wound, Hollow Fiber, Tubular, Flat Sheet Material: Polyamide, Polysulfone, Cellulose Acetate, Others End User: Municipal, Industrial, Commercial, Residential Application: Desalination, Wastewater Treatment, Food & Beverage Processing, Semiconductor Manufacturing |
| Companies Covered | DuPont, Hydranautics, TORAY INDUSTRIES, INC., Veolia Water Technologies, Toyobo Co., Ltd, NITTO DENKO CORPORATION, Koch Membrane Systems, Inc, Pentair, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Osmosis (RO) Membrane Market Strategic Shifts & Innovations
Electrochemical anti-scaling systems are displacing chemical dosing regimes, while graphene-enhanced substrates promise step-change flux improvements. These material and process innovations are compressing operating expenditure structures for high-recovery applications.
Graphene oxide nanocomposite substrates are electrifying membrane performance benchmarks through enhanced hydrophilicity and mechanical strength. Seawater desalination operators in the Middle East and Australia are piloting these materials for 20% flux improvements. The technology is electrifying competitive positioning around energy intensity metrics that dominate levelized cost calculations.
REACH substance restrictions and the EU Drinking Water Directive are tightening material compliance requirements for polyamide chemistries. Membrane manufacturers must reformulate cross-linking agents and additives to maintain CE marking eligibility. European municipal tenders now specify full material disclosure, favoring suppliers with established regulatory dossiers.
Multi-source qualification programs are displacing single-source procurement for large desalination engineering-procurement-construction contracts. Buyers are unbundling membrane supply from system integrator scope to reduce concentration risk. This pattern is most visible in Saudi Arabia's Public Investment Fund-backed giga-projects and Chilean mining sector water agreements.
Reverse Osmosis (RO) Membrane Market Segmentation
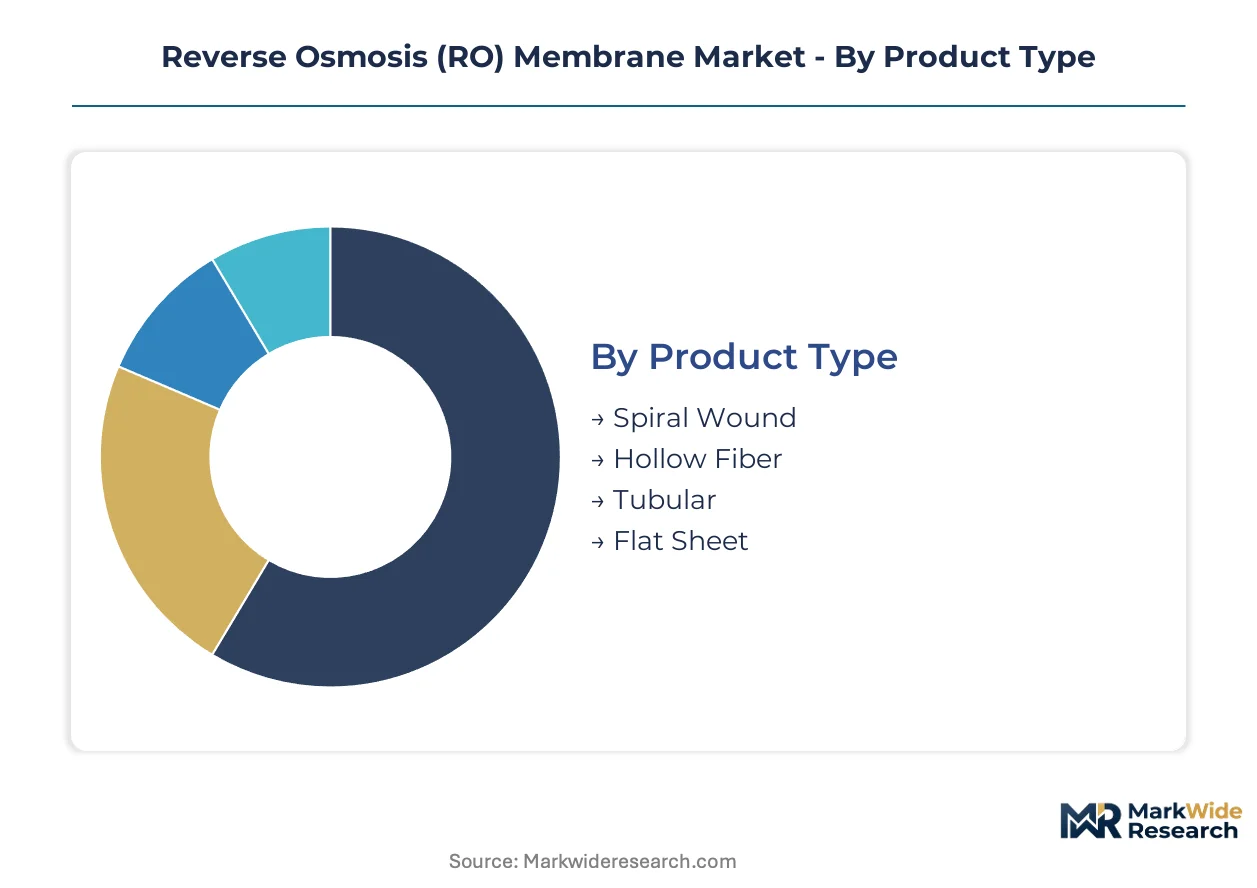
Membrane geometry, polymer chemistry, end-use requirements, and application severity create distinct performance specifications and procurement patterns across the RO membrane landscape. Each segmentation dimension carries unique cost structures and replacement cycles that reshape vendor positioning.
Product Type:
Module configuration determines packing density, pressure tolerance, and cleaning accessibility, with supply concentrating around spiral wound manufacturing lines in China, Japan, and South Korea.
- Spiral Wound:Thin-film composite layers wrapped around a central permeate tube maximize surface area within pressure vessels. Municipal utilities in California, Texas, and Florida specify these modules for their balance of flux performance and operational longevity under EPA discharge compliance.
- Hollow Fiber:Thousands of hair-thin membranes potted at both ends enable outside-in filtration with lower fouling propensity. China's coastal desalination plants in Shandong and Jiangsu deploy these for high-turbidity seawater intake conditions.
- Tubular:Wide-bore membranes tolerate extreme suspended solids and enable mechanical cleaning. Food and beverage processors leverage this geometry for high-viscosity feed streams.
- Flat Sheet:Plate-and-frame configurations suit laboratory-scale and specialized industrial piloting. Research institutions and membrane developers use these for rapid prototype testing.
Today's leader: Spiral Wound. Tomorrow's challenger: Hollow Fiber.
Material:
Polymer selection governs salt rejection, chlorine tolerance, and mechanical durability, with cost tiers separating thin-film composites from legacy chemistries.
- Polyamide:Interfacially polymerized aromatic layers on polysulfone supports achieve industry-leading salt rejection exceeding 99.5%. REACH substance restrictions and EU Drinking Water Directive material disclosure requirements favor suppliers with established regulatory dossiers for this chemistry.
- Polysulfone:Sulfone-based polymers provide structural integrity as support substrates rather than active separation layers. Petrochemical feedstock volatility in benzene and bisphenol-A supply chains exposes this segment to crude price swings.
- Cellulose Acetate:Legacy acetate chemistry offers chlorine tolerance but lower flux and pH sensitivity. Niche applications in developing markets with limited pretreatment infrastructure sustain residual demand.
- Others:Emerging chemistries including graphene oxide nanocomposites and zwitterionic surface modifications address fouling resistance gaps.
Polyamide dominates installed value. Graphene-enhanced variants are gaining share fastest.
End User:
Customer type segments by scale, technical sophistication, and procurement centralization, with municipal tenders unbundling membrane supply from system integrator scope.
- Municipal:City and regional water authorities operate large-scale treatment trains with standardized membrane replacement protocols. EPA National Primary Drinking Water Regulations accelerate upgrade cycles across aging US plants.
- Industrial:Manufacturing facilities face zero-liquid-discharge mandates from China's MEE and India's Central Pollution Control Board. Textile clusters around Ahmedabad and Tiruppur drive membrane-based reuse adoption.
- Commercial:Hotels, hospitals, and office complexes require point-of-entry purification with moderate capacity. Service contracts and leasing models predominate in this segment.
- Residential:Under-sink and whole-house systems serve households in water-stressed regions. California's Central Valley operators retrofit treatment for crop-compatible salinity in agricultural settings.
Industrial buyers currently command premium pricing. Municipal procurement is expanding most quickly.
Application:
Severity of operating conditions and recovery requirements create distinct margin profiles across use cases.
- Desalination:Seawater and brackish water conversion demands extreme pressure tolerance and frequent replacement. Saudi Arabia's Public Investment Fund-backed giga-projects and Chilean mining sector agreements concentrate project awards.
- Wastewater Treatment:Secondary and tertiary polishing for reuse applications requires fouling-resistant surface chemistries. Australia's inland communities pilot graphene-enhanced substrates for high-organic feedwaters.
- Food & Beverage Processing:Product-contact applications impose FDA and EU food-grade material compliance. Dairy and juice concentration processes favor sanitary-design module configurations.
- Semiconductor Manufacturing:Ultrapure water specifications demand sub-ppb contaminant removal with continuous operation. Taiwan and South Korea fabrication clusters sustain specialized membrane procurement.
Desalination anchors revenue concentration. Semiconductor applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors membrane demand expansion through seawater desalination megaprojects serving industrial water stress relief. Municipal utilities across four continents are accelerating membrane replacement cycles under tightening discharge standards. Project awards concentrate in coastal manufacturing belts and mining-intensive interiors.
China
Shandong, Jiangsu, and Zhejiang coastal provinces deploy hollow fiber configurations for high-turbidity seawater intake at scale. The Ministry of Ecology and Environment enforces zero-liquid-discharge mandates that compel textile and chemical facilities toward membrane-based reuse systems. Tianjin's industrial corridor sustains concentrated demand for brackish water conversion capacity.
United States
California's Central Valley agricultural operators retrofit treatment trains for crop-compatible salinity levels amid sustained drought pressure. The EPA's National Primary Drinking Water Regulations drive membrane infrastructure upgrades across aging municipal plants in Texas and Florida. Permian Basin oilfield operators expand produced water reuse through high-pressure desalination configurations.
Saudi Arabia
Public Investment Fund-backed giga-projects unbundle membrane supply from system integrator scope to reduce concentration risk. The Saline Water Conversion Corporation oversees procurement for Red Sea and Arabian Gulf desalination capacity expansions. Jubail Industrial City's petrochemical complexes anchor premium membrane demand for ultrapure process water.
Germany
REACH substance restrictions and the EU Drinking Water Directive tighten material compliance requirements for polyamide chemistries in municipal tenders. The country's chemical manufacturing belt along the Rhine sustains specialized membrane demand for process water purification. Bavarian semiconductor fabrication clusters require sub-ppb contaminant removal specifications.
India
Central Pollution Control Board mandates drive membrane-based zero-liquid-discharge adoption in textile clusters around Ahmedabad and Tiruppur. The country's pharmaceutical manufacturing corridors in Hyderabad and Mumbai expand ultrapure water capacity for API production. Gujarat's industrial zones anchor brackish water reverse osmosis deployment for captive water security.
Reverse Osmosis (RO) Membrane Market Key Industry Players
Global majors compete with regional champions across polymer chemistry specialization and project-scale manufacturing capacity. The vendor base separates into three functional tiers: integrated polymer science conglomerates with captive fiber spinning, specialized membrane fabricators with dedicated seawater product lines, and diversified water technology platforms with system integration capabilities. Dominant competitive moves include backward integration into polysulfone substrate production and multi-source qualification program participation for giga-project awards.
Among integrated polymer science conglomerates, DuPont and TORAY INDUSTRIES, INC. exemplify archetypes with distinct geographic anchoring. DuPont occupies a position representing North American filmtec membrane performance leadership across high-salinity applications. TORAY INDUSTRIES, INC. sits within the Asian project landscape through captive fiber spinning and module assembly operations. Hydranautics represents the specialized fabricator archetype with dedicated seawater and brackish water product configurations. These three companies collectively illustrate how competitive positioning stratifies around material science depth versus geographic manufacturing concentration.
| Leading Market Players |
|---|
| DuPont |
| Hydranautics |
| TORAY INDUSTRIES, INC. |
| Veolia Water Technologies |
| Toyobo Co., Ltd |
| NITTO DENKO CORPORATION |
| Koch Membrane Systems, Inc |
| Pentair |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Benzene and bisphenol-A price volatility cascades through polysulfone substrate costs into three-tier membrane pricing structures across premium seawater, standard brackish, and economy-grade industrial tiers. Municipal utilities in California and Texas absorb these fluctuations through multi-year framework agreements, while Chinese coastal desalination projects negotiate spot-adjusted contracts tied to petrochemical indices.
Pricing Analysis
Input-cost pass-through from aromatic polymer feedstocks governs membrane module pricing, with thin-film composite polyamide configurations commanding premiums based on salt-rejection certification grade and chlorine-tolerance testing. Price differentiation separates EPA-compliant municipal tenders from unbundled industrial procurement in India's textile clusters. Cost compression in standard brackish-water tiers intensifies because Chinese module manufacturers expanded spiral-wound capacity. Industrial zero-liquid-discharge operators show least price sensitivity due to regulatory compliance mandates, while agricultural retrofit buyers in California's Central Valley exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia's Public Investment Fund giga-projects and India's production-linked incentive schemes are reshaping sourcing patterns toward localized module assembly. Manufacturing gravity centers on China, Japan, and South Korea for captive fiber spinning and spiral-wound assembly. Raw material flows draw from benzene derivatives, bisphenol-A, and interfacial polymerization agents. Single-source vulnerability concentrates in polysulfone substrate production. Distribution runs through engineering-procurement-construction contractors and direct municipal tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on graphene oxide nanocomposite adoption reducing energy intensity and extending replacement intervals in high-salinity applications.
For Market Incumbents: Anticipate regulatory tightening on per- and polyfluoroalkyl substance chemistries by accelerating zwitterionic surface modification R&D. Backward integration into polysulfone substrate production defends margin position against petrochemical volatility. Multi-source qualification program participation in Saudi giga-projects preserves volume access as procurement unbundling accelerates. For New Entrants and Emerging Players: Enter via India's Central Pollution Control Board-mandated zero-liquid-discharge retrofit wave in Ahmedabad and Tiruppur textile clusters. Graphene-enhanced substrate pilot programs in Australia's high-organic wastewater treatment facilities offer technology validation pathways. Partner with European system integrators facing REACH compliance disclosure requirements to bypass brand-loyalty barriers in municipal tenders. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane autopsy technical capabilities concentrate at original equipment manufacturers, creating acquisition opportunities for specialized failure-analysis laboratories. Long-term viability favors vertically integrated players with captive polymer science depth over pure-play module assemblers. Watch for inflection signals in EPA enforcement patterns for maximum contaminant level upgrades across aging US municipal plants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysulfone Substrate Production | Captive supply of benzene-derived support layers insulates margins from crude volatility in high-pressure membrane tiers. |
| Graphene Oxide Nanocomposite Commercialization | Pilot programs in Middle East seawater desalination validate 20% flux improvements for energy intensity leadership. |
| Multi-Source Qualification Program Participation | Unbundled procurement in Saudi Public Investment Fund projects reduces customer concentration risk for qualified suppliers. |
| Zwitterionic Surface Modification Development | Antifouling coatings address per- and polyfluoroalkyl substance constraints while extending cleaning intervals. |
| Zero-Liquid-Discharge System Integration Partnership | Textile cluster mandates in India's Ahmedabad and Tiruppur drive bundled membrane-plus-engineering procurement. |
Research Approach
Bottom-up municipal and industrial demand modeling reconciled against top-down module manufacturing capacity tracking forms the analytical core. Primary interviews with desalination project developers, membrane procurement officers at municipal utilities, EPC contractor technical directors, and plant operations managers in textile and pharmaceutical clusters informed demand-side assumptions. Secondary validation drew from EPA enforcement databases, China's Ministry of Ecology and Environment discharge filings, EU REACH substance restriction updates, and customs trade data for polysulfone and polyamide imports. Triangulation across these sources anchored segmentation-level projections.
Input-output matrices mapped feedstock costs through manufacturing value chains into end-use price elasticities across the projection horizon. Segmentation dimensions modeled include module geometry, polymer chemistry tier, application severity, and regional regulatory cluster. CAGRs derived from installed base replacement cycle compression and greenfield capacity announcements. Industry-specific forecast inputs incorporated zero-liquid-discharge mandate implementation timelines and seawater desalination project award pipelines.
Inputs from regulatory filing databases and EPC contractor project trackers were available through the study window; gaps in proprietary membrane autopsy failure rates introduce uncertainty bands around replacement cycle assumptions. Forecasts reflect documented assumptions regarding petrochemical feedstock stability and enforcement continuity for EPA and MEE standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Global Bitumen Membranes Market