
 Asia-Pacific, Middle East and Africa Macrofiltration Market | 2026-2036
Asia-Pacific, Middle East and Africa Macrofiltration Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific, Middle East and Africa Macrofiltration Market Insights
Power generation utilities and desalination operators is unwinding legacy equipment procurement patterns toward continuous-cleaning macrofiltration architectures. Pentair PLC leverages its cross-flow engineering heritage to anchor large-scale municipal contracts across the Gulf Cooperation Council states. Mann+Hummel competes through backward integration into polymer membrane substrates, sustaining margin control across volatile feedstock cycles.
Macrofiltration encompasses mechanical separation processes employing porous media with nominal ratings typically exceeding ten microns, engineered from woven synthetics, sintered metals, or rigid ceramics to remove suspended solids from high-volume fluid streams. Bag filters dominate upfront capital deployment in chemical processing due to standardized housing compatibility and rapid media swap-out protocols, while ceramic filters capture expanding share in food and beverage applications where thermal sterilization cycles degrade polymeric alternatives. Membrane filters command premium positioning in pharmaceutical production, where endotoxin retention and validated integrity testing protocols create defensible margin pools against commoditized gravity filtration offerings.
EMA's F-Gas Regulation and REACH compliance protocols shape material selection for European-destined exports manufactured within Asia-Pacific facilities, while China's MEE effluent standards and India's CPCB zero-liquid-discharge mandates directly stimulate equipment procurement across industrial end users. Australia's TGA-aligned water quality benchmarks and Saudi Arabia's SFDA pharmaceutical manufacturing rules further fragment certification requirements across the regional footprint. Stakeholders must map regulatory convergence trajectories between Gulf state environmental agencies and ASEAN harmonization initiatives to preempt compliance-driven specification changes.
Market Dynamics
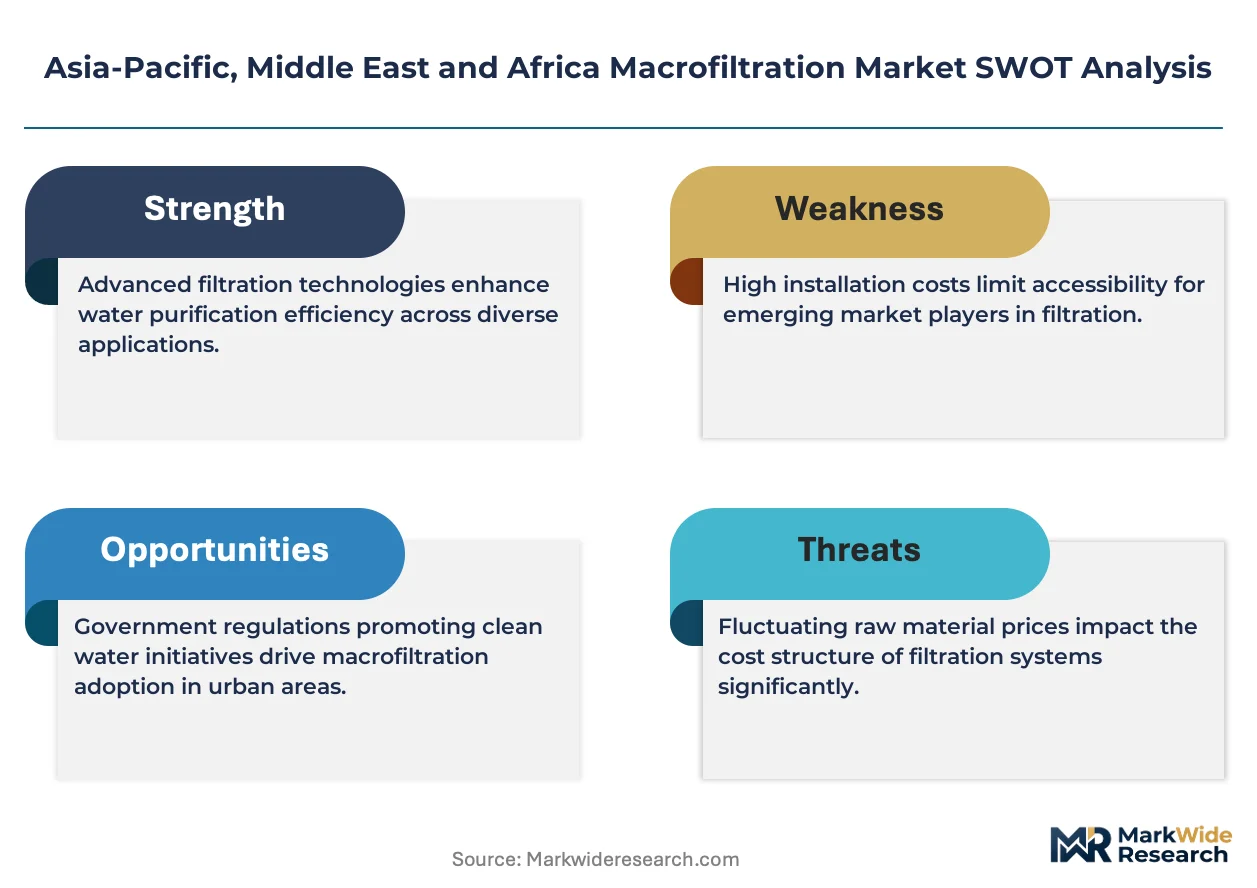
Municipal water utilities across Southeast Asia are unwinding legacy procurement patterns toward continuous-cleaning macrofiltration architectures, driven by tightening effluent standards and membrane-based treatment capacity expansion. This structural shift is compressing equipment replacement cycles and rewiring supplier-buyer relationships across the regional footprint.
Growth Catalysts
- China's dual carbon goals:Beijing's emissions reduction mandates are accelerating equipment replacement cycles in industrial water treatment, pulling demand for energy-efficient ceramic and membrane filtration systems.
- Textile and pharmaceutical clusters:India's industrial corridor states face escalating CPCB zero-liquid-discharge compliance requirements, forcing capital deployment into advanced macrofiltration infrastructure.
- ISO-aligned water quality frameworks:Australia's TGA benchmarks and Saudi Arabia's SFDA pharmaceutical manufacturing rules are fragmenting certification requirements and stimulating premium equipment procurement.
Market Restraints
- Polymer feedstock volatility:Backward integration into membrane substrates remains concentrated among European and Japanese chemical suppliers, exposing margin compression risks during petrochemical price spikes.
- Gulf state procurement concentration:Large-scale municipal contracts across GCC states cluster around a narrow vendor base, creating bid-rotation bottlenecks and elongated sales cycles.
- Thermal sterilization incompatibility:Standard polymeric bag filters face performance degradation in food and beverage applications requiring repeated high-temperature cycles, limiting addressable market scope.
Strategic Opportunities
- Vietnam's emerging industrial zones:Northern manufacturing corridors lack established filtration service infrastructure, creating first-mover advantages for membrane-based zero-liquid-discharge system providers.
- EMA F-Gas Regulation alignment:European-destined exports manufactured in Asia-Pacific facilities must adapt material selection protocols, rewarding early compliance investments with preferential supplier status.
- Cross-flow engineering convergence:Integration of continuous-cleaning architectures with smart monitoring systems opens service-revenue streams beyond equipment sales in desalination and power generation.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous compliance with Australia's TGA, Saudi SFDA, and India's CPCB mandates extends product validation cycles by 18-24 months for pharmaceutical-grade membrane filters.
- Legacy housing incompatibility:Rapid media swap-out protocols for standardized bag filter housings clash with continuous-cleaning system architectures, forcing costly retrofit decisions at industrial end users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific, Middle East and Africa Macrofiltration Market |
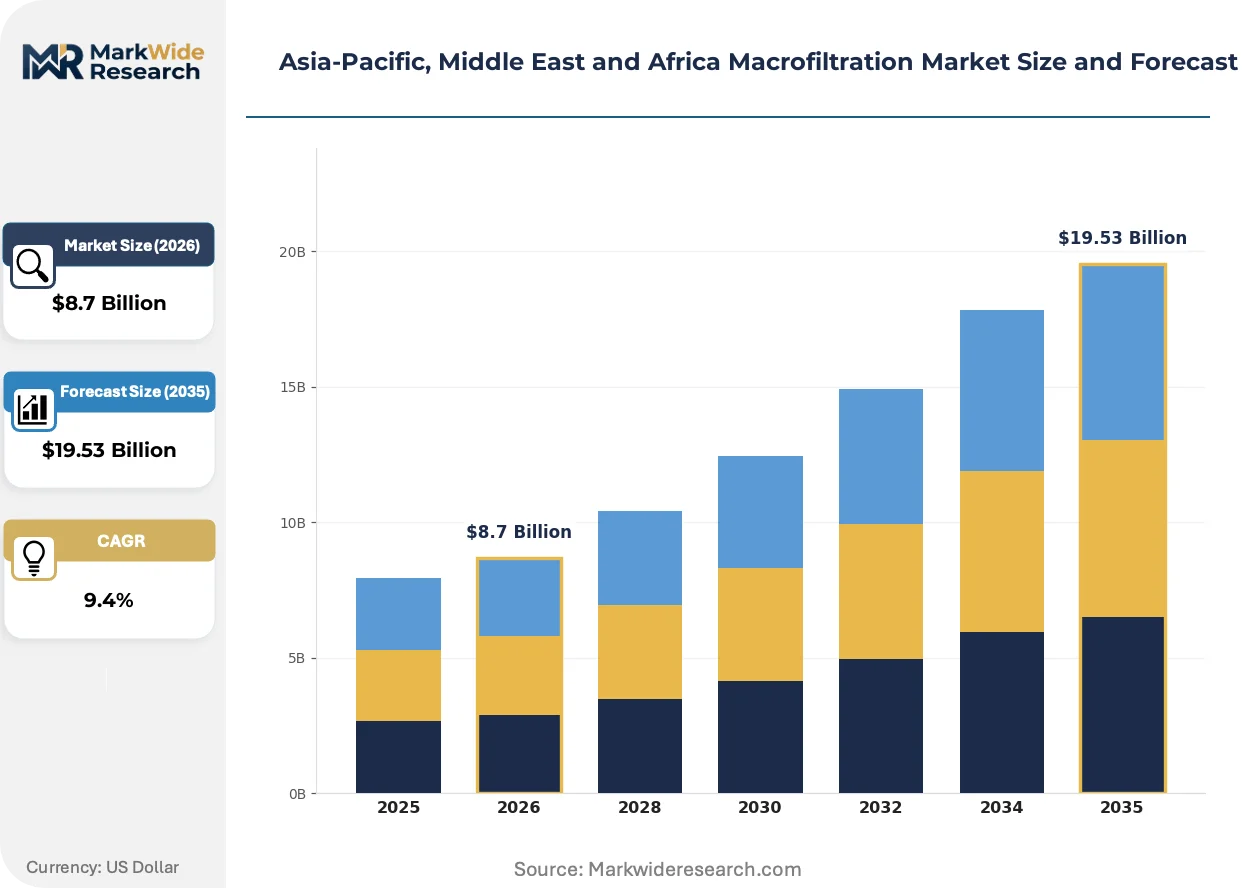
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Ceramic Filters, Cartridge Filters, Bag Filters Application: Water Treatment, Food & Beverage Processing, Pharmaceutical Production, Chemical Processing End User: Municipalities, Industrial Facilities, Laboratories, Commercial Establishments Technology: Microfiltration, Ultrafiltration, Cross-flow Filtration, Gravity Filtration |
| Companies Covered | Filtration Group, MTB Technologies Sp. Z O.O., Amiad Water Systems, Parker Hannifin, Ostwald Filtration Systems GmbH, Ascension Industries, Inc., Mann+Hummel, Pentair PLC, Danaher Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific, Middle East and Africa Macrofiltration Market Trends and Innovations
Equipment architectures are pivoting from batch-cleaning gravity systems toward continuous-operation membrane platforms, rewiring competitive positioning around service intensity and uptime guarantees rather than upfront capital metrics.
Ceramic filtration media is displacing polymeric alternatives in high-temperature food and beverage processing lines. Breweries and dairy processors across Australia and South Korea are adopting alumina and silicon carbide substrates to withstand repeated steam sterilization cycles without pore-structure degradation. This thermal resilience is displacing standardized bag filter deployments in applications above 85 degrees Celsius, compressing addressable volume for conventional synthetic media suppliers.
China's MEE effluent standards are tightening suspended solids and chemical oxygen demand limits for industrial discharge. Textile dyeing facilities in Zhejiang and Guangdong provinces face plant closure risks for non-compliance, triggering membrane filtration retrofits. Pharmaceutical manufacturers exporting to Europe must simultaneously satisfy REACH material restrictions and EMA F-Gas Regulation protocols, forcing dual-track certification investments at Asia-Pacific production facilities.
Desalination operators are unbundling after-sales service contracts from equipment procurement, compressing vendor selection criteria toward lifecycle cost and remote monitoring capabilities. Large-scale reverse osmosis pre-treatment systems in Saudi Arabia and UAE now specify predictive maintenance clauses as mandatory bid elements. This service-model rotation is most visible in Gulf Cooperation Council states, where operator consolidation has concentrated buying power among three national water authorities.
Asia-Pacific, Middle East and Africa Macrofiltration Market Segmentation
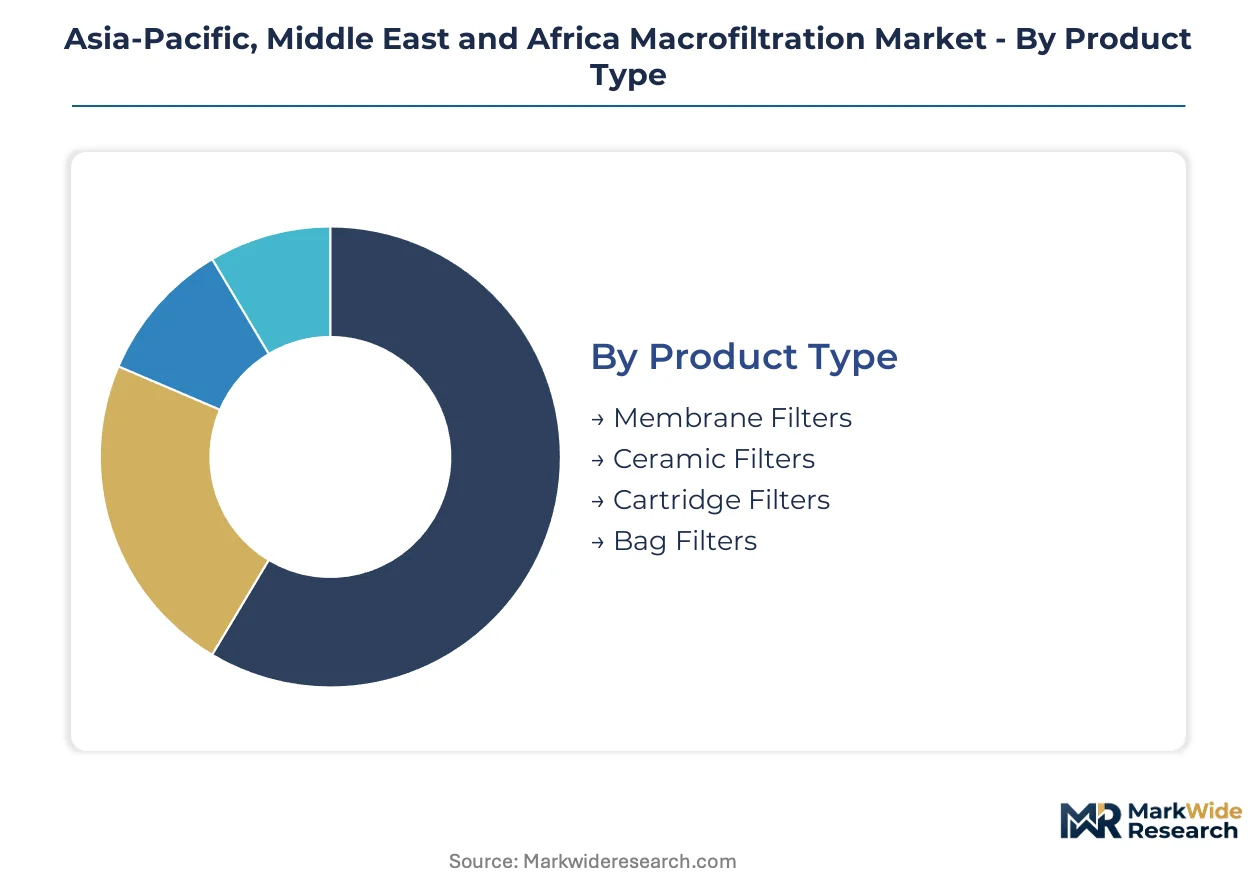
Macrofiltration procurement patterns diverge sharply across product architectures and end-use specifications. Channel configuration—direct municipal contracting versus industrial distributor networks—determines which segments capture volume versus margin.
Product Type:
Membrane and ceramic systems flow primarily through engineered-solutions channels with long sales cycles, while bag and cartridge filters move through industrial distribution with rapid inventory turns.
- Membrane Filters:Polymeric or ceramic porous structures with sub-micron to ten-micron ratings, validated for endotoxin retention in pharmaceutical streams. Demand concentrates in India's pharmaceutical corridors and Saudi Arabia's SFDA-regulated manufacturing zones, where integrity testing protocols create specification lock-in. These systems command premium positioning through validated performance guarantees rather than commodity pricing.
- Ceramic Filters:Sintered alumina or silicon carbide rigid media engineered for thermal sterilization cycles above 85 degrees Celsius. Australian breweries and South Korean dairy processors are displacing polymeric alternatives in food and beverage lines, where repeated steam exposure degrades synthetic substrates. Thermal resilience creates defensible substitution barriers against lower-cost bag filter offerings.
- Cartridge Filters:Pleated or depth-style disposable elements in standardized housings, procured through industrial distribution channels for chemical processing pre-treatment.
- Bag Filters:Woven synthetic media in standardized housings, dominating upfront capital deployment where rapid media swap-out protocols outweigh continuous-cleaning efficiency.
Bag filters dominate installed base across Southeast Asian chemical processing. Membrane filters are where expansion concentrates in pharmaceutical and zero-liquid-discharge applications.
Application:
Cost tier stratification separates premium-validated pharmaceutical systems from standardized municipal and food processing equipment.
- Water Treatment:Municipal utilities across Vietnam and Indonesia are retrofitting membrane-based continuous-cleaning architectures to meet tightening effluent standards. China's MEE suspended solids limits and India's CPCB zero-liquid-discharge mandates are compressing replacement cycles for legacy gravity systems. Desalination pre-treatment in Saudi Arabia and UAE now specifies predictive maintenance clauses as mandatory bid elements.
- Pharmaceutical Production:Endotoxin-retentive membrane systems with validated integrity testing, required for TGA-aligned Australian exports and SFDA-regulated Saudi manufacturing. Dual-track REACH and EMA F-Gas compliance for European-destined products extends certification timelines by 18-24 months, creating specification stickiness for incumbent suppliers.
- Food & Beverage Processing:Ceramic filtration displacing polymeric media in high-temperature Australian and South Korean processing lines.
- Chemical Processing:Standardized bag filter housings for rapid media replacement in continuous production environments.
Water treatment captures the largest equipment volume. Pharmaceutical production holds the steepest expansion trajectory through compliance-driven specification upgrades.
End User:
Customer type determines procurement modality—municipal tender processes versus industrial direct negotiation versus commercial spot purchasing.
- Municipalities:Large-scale desalination and water utility contracts across Gulf Cooperation Council states, concentrated among three national water authorities. Bid-rotation bottlenecks and elongated sales cycles characterize this channel, with predictive maintenance clauses now mandatory in Saudi and UAE tenders.
- Industrial Facilities:Textile dyeing operations in Zhejiang and Guangdong provinces face plant closure risks under China's MEE standards, triggering membrane filtration retrofits. India's industrial corridor states deploy zero-liquid-discharge systems to satisfy CPCB mandates.
- Laboratories:Validated membrane systems for analytical and quality control applications.
- Commercial Establishments:Point-of-use filtration through distributor channels with rapid replacement cycles.
Industrial facilities drive current retrofit demand. Municipalities anchor long-term service-revenue potential through operator consolidation.
Technology:
Maturity gradient separates established gravity systems from emerging cross-flow architectures with integrated smart monitoring.
- Cross-flow Filtration:Continuous-cleaning configurations with tangential flow patterns that minimize membrane fouling. Power generation utilities and desalination operators are unbundling after-sales service from equipment procurement, compressing vendor selection toward lifecycle cost and remote monitoring capabilities. Integration with smart monitoring systems opens recurring revenue streams beyond upfront capital sales.
- Ultrafiltration:Pressure-driven membrane separation for macromolecule retention, specified in pharmaceutical endotoxin control and food protein concentration. Australia's TGA benchmarks and India's pharmaceutical export requirements drive specification intensity in this tier.
- Microfiltration:Particle and bacteria retention in water and beverage applications.
- Gravity Filtration:Legacy batch-cleaning architectures facing replacement pressure from continuous-operation platforms.
Gravity filtration retains legacy installed base. Cross-flow ultrafiltration is gaining share fastest through service-model rotation in desalination and power generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese membrane filtration exports flow primarily to Southeast Asian municipal utilities and Indian pharmaceutical corridors, while Gulf Cooperation Council desalination operators source ceramic and cross-flow systems from European-Japanese joint ventures manufacturing in Singapore and South Korea.
China
Zhejiang and Guangdong textile dyeing clusters face plant closure risks under MEE effluent standards, triggering membrane filtration retrofits. Beijing's dual carbon goals accelerate equipment replacement cycles in industrial water treatment. Shanghai and Jiangsu province chemical parks deploy zero-liquid-discharge systems to satisfy tightening suspended solids limits.
India
Maharashtra and Gujarat pharmaceutical corridors drive endotoxin-retentive membrane demand for CDSCO-regulated exports. Telangana and Andhra Pradesh industrial zones deploy advanced macrofiltration for CPCB zero-liquid-discharge compliance. Karnataka biotechnology parks specify validated integrity testing protocols for European-destined active pharmaceutical ingredients.
Saudi Arabia
SFDA pharmaceutical manufacturing rules fragment certification requirements for membrane filter suppliers. National Water Company consolidation concentrates buying power for desalination pre-treatment systems. Jubail Industrial City petrochemical complexes specify predictive maintenance clauses in macrofiltration tenders.
Australia
TGA-aligned water quality benchmarks stimulate premium equipment procurement in pharmaceutical production. Victoria and New South Wales breweries adopt ceramic filtration for repeated steam sterilization cycles. South Australian dairy processors displace polymeric media with alumina substrates above 85 degrees Celsius.
Vietnam
Northern manufacturing corridors in Bac Ninh and Hai Phong lack established filtration service infrastructure. MEE-equivalent provincial standards emerge for textile discharge in Dong Nai and Binh Duong provinces. First-mover membrane providers capture zero-liquid-discharge system deployments in emerging industrial zones.
Asia-Pacific, Middle East and Africa Macrofiltration Market Competitive Landscape
Player mix skews toward diversified filtration conglomerates with cross-regional manufacturing footprints, creating tiered competition between integrated system providers and specialized membrane substrate fabricators. Market structure concentrates large-scale municipal contracts among three to four vendors with Gulf Cooperation Council track records, while industrial distribution channels fragment across regional distributors. Two strategic archetypes dominate: European-Japanese chemical suppliers with backward integration into polymer membranes, and engineered-solutions providers with cross-flow engineering heritage. Competitive moves center on service contract unbundling and smart monitoring integration rather than pure equipment pricing.
Among diversified conglomerates, Pentair PLC and Danaher Corporation occupy positions anchored by municipal desalination relationships and pharmaceutical validation protocols respectively. Mann+Hummel exemplifies the backward-integrated archetype with captive membrane substrate production. Parker Hannifin and Filtration Group sit within the industrial distribution-focused tier, leveraging standardized housing compatibility across chemical processing accounts. Amiad Water Systems represents Israeli-origin specialization in agricultural and industrial water filtration, while Ostwald Filtration Systems GmbH anchors German-engineered ceramic media positioning for high-temperature applications.
| Leading Market Players |
|---|
| Filtration Group |
| MTB Technologies Sp. Z O.O. |
| Amiad Water Systems |
| Parker Hannifin |
| Ostwald Filtration Systems GmbH |
| Ascension Industries, Inc. |
| Mann+Hummel |
| Pentair PLC |
| Danaher Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term municipal offtake contracts across Gulf Cooperation Council states lock in membrane substrate supply access and compress price visibility for ceramic filtration systems, while spot procurement for standardized bag filter housings exposes industrial buyers to polymer feedstock volatility.
Pricing Analysis
Current-generation cross-flow membrane systems command premium positioning over prior-generation gravity batch systems and emerging next-generation smart-monitored platforms. Three-tier pricing structure across validated pharmaceutical-grade, industrial-standard, and economy municipal tiers separates membrane filters by certification intensity—REACH-compliant substrates for European-destined exports carry material cost premiums. Pricing pressure stems from polymer feedstock volatility concentrated among Japanese and European chemical suppliers, compressing margins for non-integrated fabricators. Municipal water authorities in Saudi Arabia and UAE exhibit lowest price sensitivity due to consolidated buying power, while Vietnamese textile processors in emerging industrial zones face acute cost compression.
Supply Chain Analysis
Inventory lead times for sintered ceramic substrates extend 40-60 days longer than woven synthetic bag filter media, constraining rapid deployment for high-temperature food and beverage retrofits. Manufacturing concentrates in China for polymeric membranes, Germany and Japan for ceramic substrates, and Singapore for European-Japanese joint venture cross-flow system assembly. Raw material dependencies center on polyethersulfone and polyvinylidene fluoride resins, alumina and silicon carbide powders, and stainless-steel housing components. Single-source vulnerability runs through Japanese suppliers for pharmaceutical-grade membrane substrates. Distribution runs through direct municipal contracting for large-scale desalination, industrial distributor networks for chemical processing, and engineered-solution channels for validated pharmaceutical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three national water authorities across Gulf Cooperation Council states, fragmenting vendor access and elongating sales cycles for equipment providers without established track records.
For Market Incumbents: Consolidate service-revenue streams by unbundling predictive maintenance clauses from equipment procurement in Saudi and UAE municipal tenders, countering margin compression from polymer feedstock volatility. Deepen backward integration into membrane substrate production or captive supply partnerships with Japanese chemical suppliers to defend positioning against emerging Chinese membrane exporters.
For New Entrants and Emerging Players: Anchor in Vietnam's northern manufacturing corridors around Bac Ninh and Hai Phong, where filtration service infrastructure remains underdeveloped and first-mover advantages accrue to zero-liquid-discharge system providers. Target textile dyeing facilities in Dong Nai and Binh Duong provinces facing emerging MEE-equivalent discharge standards, leveraging distributor partnerships with established industrial channel partners rather than direct municipal contracting.
For Investors and Strategic Acquirers: Specialized ceramic substrate fabricators with thermal sterilization validation for food and beverage applications represent the most defensible acquisition archetype, given substitution barriers against polymeric alternatives above 85 degrees Celsius. Long-term viability hinges on regulatory convergence between ASEAN harmonization initiatives and Gulf state environmental agencies. Watch for bid-rotation pattern shifts in GCC municipal tenders as an inflection signal for vendor consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrates | Mann+Hummel's captive polymer production insulates margins against petrochemical price spikes. |
| Smart Monitoring Platform Integration | Cross-flow system vendors capture recurring service revenue beyond upfront capital sales in desalination. |
| Ceramic Media Thermal Validation Investment | Australian breweries and South Korean dairy processors lock in alumina substrate specifications. |
| Dual-Track Certification for REACH and EMA F-Gas | Pharmaceutical exporters to Europe extend specification stickiness through 18-24 month validation cycles. |
| Zero-Liquid-Discharge System Deployment | India's CPCB mandates force capital deployment across Maharashtra and Gujarat industrial corridors. |
Research Methodology
A spread of perspectives from municipal water utility procurement officers, industrial plant engineers, membrane substrate R&D directors, and aftermarket service heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, MEE effluent standard filings, and SEC disclosures from listed filtration conglomerates. Bottom-up equipment deployment tallies triangulated against top-down addressable market estimates across the analysis window.
Segmentation dimensions modeled include product architecture, application intensity, end-user procurement modality, and technology maturity gradient. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory mandate timing. Forecast inputs incorporated China's dual carbon goal implementation pace and India's CPCB enforcement intensity across industrial corridor states.
Decision-makers should treat outputs as directional under assumptions of sustained MEE and CPCB enforcement; material deviation in regulatory implementation timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
PTFE Membrane Market