
 Hemodialysis Catheters Market | 2026-2036
Hemodialysis Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialysis Catheters Market Analysis
Recurring catheter maintenance contracts is hardening into a core revenue stream alongside device sales. Medtronic leverages its integrated care networks to bundle replacement schedules with remote monitoring services. BD sustains R&D intensity in antimicrobial polymer research, while Fresenius Medical Care anchors demand through captive consumption across its dialysis clinic network.
Hemodialysis catheters are hollow, flexible tubes inserted into large central veins to enable blood withdrawal and return during renal replacement therapy, typically manufactured from medical-grade polyurethane or silicone with dual-lumen configurations to separate arterial and venous blood flow. Tunneled catheters dominate inpatient settings due to lower infection risk and extended dwell times, while dual-lumen designs capture expanding share in outpatient dialysis clinics where throughput efficiency governs purchasing decisions. Silicone formulations retain preference for long-term implantation despite higher material costs, whereas coated materials represent the fastest-growing segment as antimicrobial surface technologies advance.
FDA enforces stringent biocompatibility and sterility standards under 21 CFR requirements for blood-contacting devices, while ISO 10555 and ISO 80369 govern dimensional and connection integrity to prevent misconnection hazards. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for Class III devices, extending approval timelines for novel catheter coatings. Stakeholders must monitor evolving antimicrobial resistance patterns and their impact on coating efficacy claims.
Market Dynamics
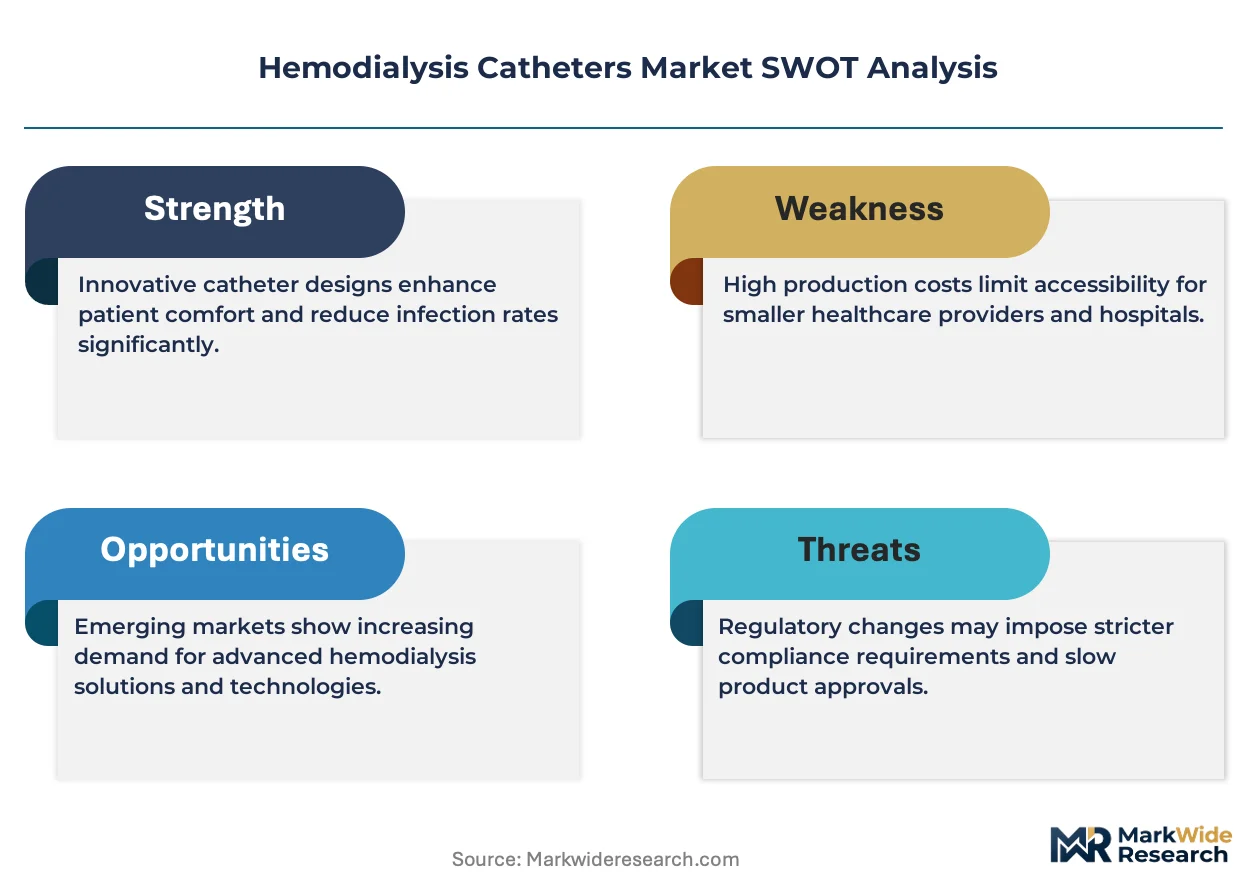
Antimicrobial surface engineering is compressing product lifecycles across the hemodialysis catheter landscape, forcing manufacturers to recertify portfolios under evolving FDA biocompatibility benchmarks while clinic procurement committees rewrite vendor scorecards around infection-rate performance.
Growth Catalysts
- Outpatient dialysis expansion:Medicare reimbursement structures in the United States favor clinic-based treatment, accelerating catheter replacement schedules and consumable pull-through.
- ISO 80369 connection standards:Mandated dimensional integrity for small-bore connectors is eliminating misconnection hazards and driving systematic catheter fleet upgrades.
- Silicone polymer advances:Enhanced biostability formulations are extending tunneled catheter dwell times, reducing total cost of ownership for long-term renal patients.
Market Restraints
- Polyurethane feedstock concentration:Medical-grade polymer supply clusters in German and Chinese chemical manufacturing regions, exposing procurement to input volatility.
- EU MDR clinical evidence requirements:Extended approval timelines for novel antimicrobial coatings delay commercialization by 18-24 months versus predecessor directives.
- Arteriovenous fistula substitution:Surgical vascular access alternatives reduce catheter dependency among eligible patients, capping addressable volume in transplant-eligible cohorts.
Strategic Opportunities
- Home hemodialysis penetration:United States Medicare Advantage plans are expanding reimbursement for residential treatment, creating demand for simplified catheter interfaces.
- Remote monitoring convergence:Integration of pressure-sensing catheters with cloud-based dialysis management platforms enables predictive maintenance contracting.
- Indian dialysis infrastructure buildout:Government-funded renal care centers under the National Health Mission represent untapped procurement volume for dual-lumen devices.
Industry Challenges
- Antimicrobial resistance surveillance:Coating efficacy claims require continuous clinical validation against evolving pathogen profiles, straining post-market study budgets.
- Legacy EMR integration:Catheter utilization tracking systems must interface with heterogeneous hospital information architectures, complicating rollout of smart-device variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialysis Catheters Market |
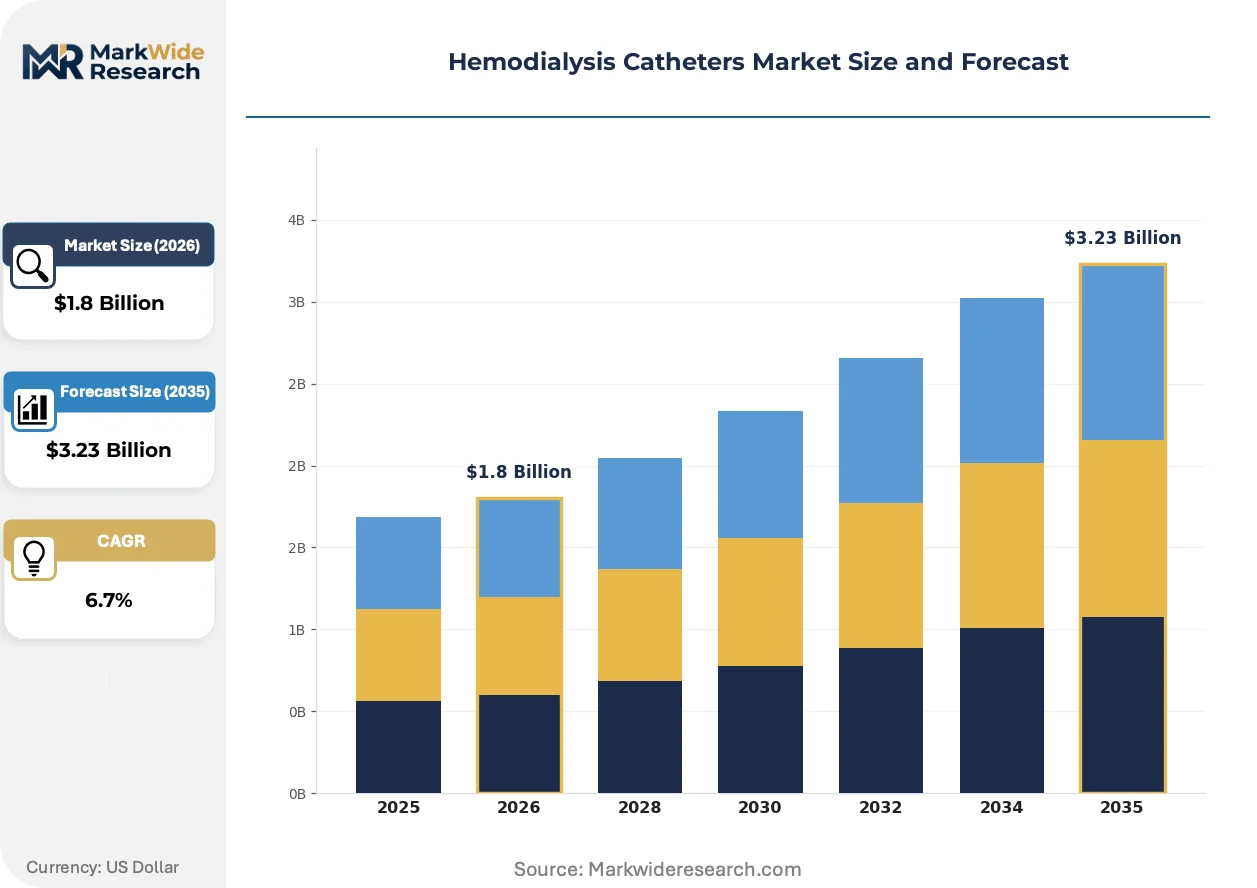
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tunneled Catheters, Non-Tunneled Catheters, Hemodialysis Catheter Sets, Dual-Lumen Catheters End User: Hospitals, Ambulatory Surgical Centers, Dialysis Clinics, Home Care Providers Material: Polyurethane, Silicone, PVC, Coated Materials Deployment: Inpatient, Outpatient, Home-Based, Emergency Settings |
| Companies Covered | Medtronic, BD (Becton, Dickinson and Company), Teleflex Incorporated, Merit Medical Systems, B. Braun SE, AngioDynamics, Mozarc Medical Holding LLC, Medical Components, Inc, Fresenius Medical Care AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialysis Catheters Market Emerging Trajectories
Surface modification chemistry and connected-device architectures are redefining competitive differentiation in hemodialysis access, shifting procurement criteria from unit cost toward total infection-cost accountability and real-time performance telemetry.
Antimicrobial silver-ion release coatings are automating infection prevention protocols by maintaining sub-MIC concentrations at the catheter-skin interface without clinician intervention. Outpatient dialysis chains in the United States are adopting these surfaces at replacement cycle acceleration, compressing competitive advantage timelines for conventional uncoated devices. This automation of prophylactic care is displacing manual antiseptic regimens and bundling catheter selection with liability risk transfer.
EU Medical Device Regulation (MDR) Class III clinical evidence requirements are extending certification pathways for novel catheter coatings, forcing manufacturers to construct prospective registry studies before CE marking. The industrial consequence is a consolidation of development pipelines around proven antimicrobial mechanisms rather than experimental surfaces. Hemodialysis catheter portfolios with legacy CE certificates under the Medical Device Directive face mandatory recertification, favoring incumbents with established clinical datasets.
Clinic procurement committees are unbundling device acquisition from maintenance service contracts, creating separate vendor relationships for catheter supply and insertion site care. Dialysis chains are consolidating purchasing through group purchasing organizations while retaining local autonomy for clinical service agreements. This bifurcation is most visible in United States integrated delivery networks, where supply chain and clinical operations report to separate cost centers.
Hemodialysis Catheters Market Segmentation
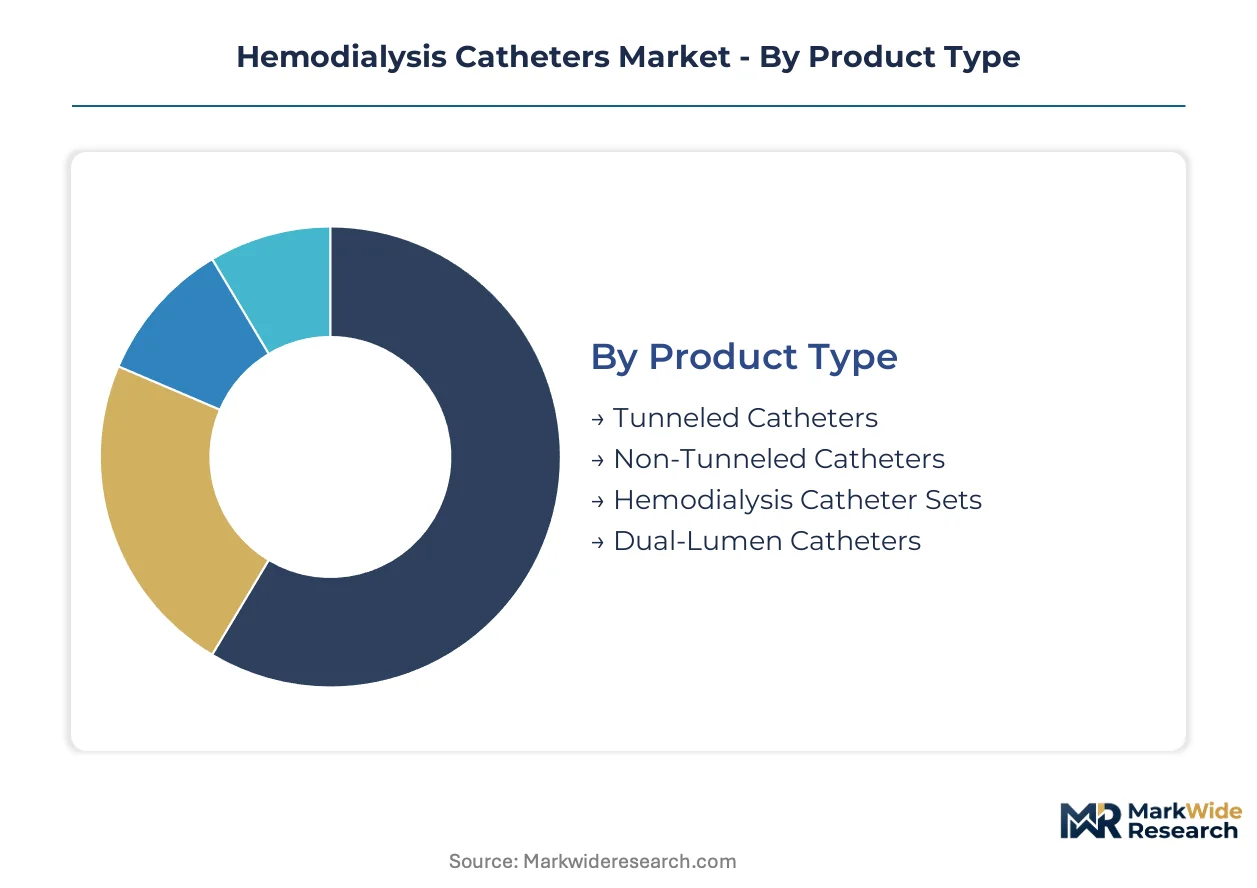
Catheter replacement cycles vary dramatically across clinical settings, with procurement committees weighting infection risk against dwell time economics. Material selection and deployment environment dictate upgrade timing, creating distinct revenue pools for manufacturers.
Product Type:
Replacement schedules diverge sharply by catheter construction, with tunneled designs commanding longer upgrade intervals than acute-care alternatives.
- Tunneled Catheters:These devices incorporate a subcutaneous cuff that anchors the catheter and creates a biological seal against bacterial migration. Demand concentrates in United States hospital systems managing end-stage renal disease patients awaiting fistula maturation, where Medicare reimbursement structures reward reduced infection episodes.
- Dual-Lumen Catheters:Separated arterial and venous channels enable simultaneous blood withdrawal and return without recirculation. Outpatient dialysis chains in the United States specify these configurations for throughput efficiency, with procurement committees prioritizing lumen integrity over unit cost.
- Non-Tunneled Catheters:Acute-care facilities deploy these for emergency dialysis initiation where immediate vascular access outweighs infection risk.
- Hemodialysis Catheter Sets:Pre-packaged insertion kits reduce procedural variability and supply chain complexity for high-volume purchasers.
Tunneled catheters sit at the top of the volume ranking, with dual-lumen designs climbing the fastest.
End User:
Procurement authority fragments across care settings, with dialysis clinics consolidating purchasing power while hospitals retain clinical autonomy.
- Dialysis Clinics:Freestanding renal care centers generate recurring catheter demand through scheduled replacement protocols. United States Medicare reimbursement structures favor clinic-based treatment, accelerating consumable pull-through.
- Hospitals:Inpatient facilities manage acute renal failure cases and catheter insertion for transitioning patients. Academic medical centers maintain vendor diversity to support resident training across multiple device platforms.
- Ambulatory Surgical Centers:These settings handle catheter insertion and removal procedures for stable patients, with procurement governed by case-volume contracts.
- Home Care Providers:Residential dialysis programs require simplified catheter interfaces and remote monitoring compatibility.
Dialysis clinics command the largest procurement volumes, with home care providers expanding most quickly.
Material:
Material selection governs biostability performance and coating efficacy claims, with procurement committees rewriting vendor scorecards around dwell time outcomes.
- Coated Materials:Antimicrobial surface technologies release silver ions or other agents at the catheter-skin interface. FDA clearance pathways for these devices are tightening product standards, forcing manufacturers to recertify portfolios under evolving biocompatibility benchmarks.
- Silicone:Medical-grade formulations offer superior biostability for long-term implantation despite higher material costs. Enhanced polymer variants are extending tunneled catheter dwell times in United States outpatient settings.
- Polyurethane:This material balances mechanical strength with flexibility for acute-care applications.
- PVC:Lower-cost alternative for short-term deployment where extended dwell time is not clinically indicated.
Silicone maintains the highest implantation volumes, with coated materials gaining share fastest.
Deployment:
Care setting migration is restructuring catheter specifications, with outpatient and home environments demanding simplified interfaces.
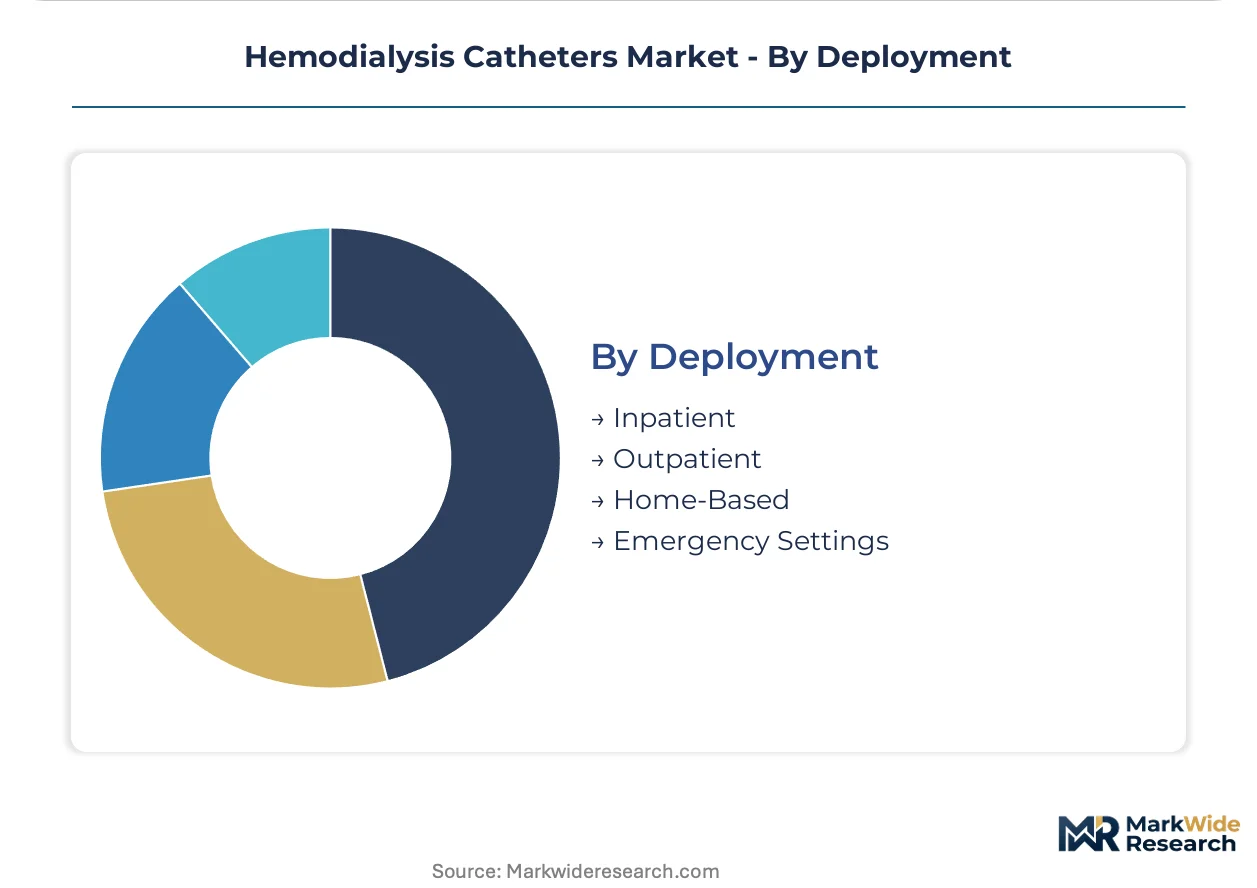
- Outpatient:Freestanding dialysis centers prioritize dual-lumen configurations for throughput efficiency. United States Medicare Advantage plans are expanding reimbursement for clinic-based treatment, reinforcing this segment's procurement weight.
- Inpatient:Hospital-based dialysis services manage acute cases and complex comorbidities, with catheter selection governed by infection control protocols.
- Home-Based:Residential treatment requires patient-friendly catheter interfaces and integration with remote monitoring platforms.
- Emergency Settings:Critical care units deploy non-tunneled designs for immediate vascular access in unstable patients.
Outpatient deployment leads volume rankings, with home-based care showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with streamlined regulatory pathways for antimicrobial-coated devices, exploiting compliance-cost differentials while maintaining quality standards for export markets.
United States
Medicare reimbursement structures favor clinic-based treatment, accelerating catheter replacement schedules across freestanding dialysis centers. FDA enforces stringent biocompatibility standards under 21 CFR requirements for blood-contacting devices. Manufacturing clusters in Minnesota and Massachusetts concentrate on silicone polymer formulations for long-term implantation.
Germany
Medical-grade polyurethane feedstock production anchors supply security for European catheter manufacturers. EU Medical Device Regulation imposes enhanced clinical evidence requirements for Class III devices with antimicrobial coatings. The Rhine-Ruhr industrial corridor hosts specialized polymer research facilities advancing coating chemistry.
China
Government-funded renal care expansion under the National Health Mission equivalent drives procurement volume for dual-lumen devices. NMPA clearance pathways are tightening alignment with international biocompatibility benchmarks. Manufacturing concentrates in Jiangsu and Zhejiang provinces serving domestic and export markets.
India
The National Health Mission is funding dialysis infrastructure buildout across government renal care centers, creating untapped procurement volume. CDSCO regulates medical device imports and domestic manufacturing under strengthened quality frameworks. Industrial clusters in Gujarat and Maharashtra are developing catheter assembly capabilities for regional supply.
Japan
Aging demographics expand the end-stage renal disease patient pool requiring vascular access solutions. PMDA maintains rigorous clinical evidence standards for antimicrobial surface technologies. Manufacturing activity concentrates in the Kansai region around Osaka, with specialized polymer processing for biostable silicone formulations.
Hemodialysis Catheters Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated care networks bundling device supply with service contracts while independent clinics negotiate discrete procurement relationships. Market structure tilts toward consolidation among multinational device corporations with dialysis clinic ownership or exclusive supply agreements. Three archetypes dominate: diversified medtech conglomerates with renal care verticals, specialized vascular access manufacturers, and regional contract fabricators serving private-label distributors. Competitive moves center on antimicrobial coating patent licensing and backward integration into medical-grade polymer compounding.
Among diversified medtech conglomerates, Medtronic and BD exemplify the integrated care network model, leveraging scale to bundle replacement schedules with remote monitoring services. Fresenius Medical Care occupies a distinct position through captive consumption across its owned dialysis clinic network, anchoring demand volume that shapes procurement specifications industry-wide. These three corporations represent the tier where device manufacturing converges with treatment delivery infrastructure.
| Leading Market Players |
|---|
| Medtronic |
| BD (Becton, Dickinson and Company) |
| Teleflex Incorporated |
| Merit Medical Systems |
| B. Braun SE |
| AngioDynamics |
| Mozarc Medical Holding LLC |
| Medical Components, Inc |
| Fresenius Medical Care AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Antimicrobial certification tiers bifurcate procurement economics between FDA-cleared silver-ion coatings and conventional uncoated devices, with premium-tier manufacturers commanding 40-60% unit price premiums while concentrating polymer compounding in Minnesota and Massachusetts clusters. This tier divergence simultaneously shapes distributor margin structures and raw material sourcing strategies, as clinic procurement committees unbundle device acquisition from service contracts.
Pricing Analysis
Distributor markups of 25-35% separate manufacturer net pricing from hospital procurement committees, with group purchasing organizations extracting volume-tiered discounts that compress margins for mid-tier suppliers. Price differentiation rests on FDA 510(k) clearance status and ISO 80369 connection compliance, with antimicrobial-coated devices sustaining premium positioning against commodity polyurethane alternatives. Cost compression in standard-grade segments intensifies as Indian and Chinese domestic manufacturers expand regional supply, while academic medical centers demonstrate lowest price sensitivity due to resident training requirements.
Supply Chain Analysis
Domestic-content mandates in India's National Health Mission and China's NMPA localization push are reshaping sourcing patterns for multinational manufacturers, compelling joint ventures with Gujarat and Maharashtra assembly facilities. Medical-grade polyurethane feedstock concentrates in German Rhine-Ruhr chemical corridors and Chinese Jiangsu-Zhejiang manufacturing zones, drawing from silicone monomer and antimicrobial agent dependencies. Single-source vulnerability pervades silver-ion coating precursor supply, while distribution runs through specialized medical device distributors serving dialysis clinic chains and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where outpatient dialysis expansion and FDA tightening of biocompatibility standards tilt procurement toward antimicrobial-coated premium specifications. Device economics increasingly favor manufacturers with integrated coating chemistry and captive clinic relationships.
For Market Incumbents: To counter arteriovenous fistula substitution and coating commoditization, Medtronic-scale players should deepen backward integration into medical-grade silicone compounding and lock exclusive supply terms with Fresenius-style captive clinic networks. Certification investment in next-generation antimicrobial surfaces preserves pricing power against uncoated challengers. For New Entrants and Emerging Players: Home hemodialysis providers represent the most penetrable buyer archetype, with Medicare Advantage reimbursement expansion creating white-space demand for simplified catheter interfaces and remote-monitoring compatibility. CDSCO-registered Indian domestic manufacturers can capture National Health Mission procurement through cost-optimized dual-lumen designs, bypassing entrenched GPO relationships in saturated US clinic markets. For Investors and Strategic Acquirers: Consolidation pressure builds where antimicrobial coating patent estates fragment across specialized polymer research shops and legacy device manufacturers. Long-term viability favors targets with established clinical datasets under EU MDR and FDA 510(k) pathways, not pure-play contract fabricators. Watch for inflection when CMS issues bundled reimbursement codes for infection-prevention surface technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Patent Licensing | Silver-ion release mechanisms from Rhine-Ruhr research facilities accelerate FDA recertification timelines. |
| Backward Integration into Polymer Compounding | In-house silicone formulation control secures supply against German-Chinese feedstock volatility. |
| Home Hemodialysis Interface Development | Simplified patient-operable designs align with Medicare Advantage residential reimbursement expansion. |
| Remote Monitoring Platform Integration | Pressure-sensing catheter-cloud convergence enables predictive maintenance subscription revenue. |
| Indian Domestic Manufacturing Joint Venture | CDSCO-registered Gujarat facilities capture National Health Mission procurement volume. |
Methodological Framework
Multiple input streams — structured interviews with dialysis clinic procurement managers, biomedical engineers at academic medical centers, and GPO contracts specialists — were reconciled against FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR CE marking registries. Bottom-up catheter unit demand estimates from hospital procurement systems and top-down market sizing from polymer feedstock trade flows were cross-validated to establish dimensional integrity.
Historical infection-rate performance data was cross-referenced against panel input from antimicrobial coating chemists and regulatory affairs directors to inform segment-level assumptions across the projection horizon. The analytical framework modeled product type, material formulation, deployment setting, and regional regulatory cluster dimensions, with CAGRs derived from replacement cycle velocity and outpatient clinic expansion trajectories. Silicone polymer biostability advances and ISO 80369 connector standard compliance served as key forecast inputs.
Underlying measurement precision varies by segment; coated materials and home-based deployment carry tighter precision than commodity PVC acute-care alternatives due to sparse utilization tracking. Forecasts reflect documented assumptions on antimicrobial resistance surveillance costs and EU MDR recertification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transportable Ventilator Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Global Medical Drones Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Global Pathological Microscopes Market