

Surgical Heart Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Heart Valves Market Insights
Hospital procurement for surgical heart valves is tilting toward bundled contract models that consolidate vendor relationships. Edwards Lifesciences leverages its pericardial tissue processing capabilities to command premium positioning in academic medical centers. Medtronic anchors its presence through integrated perfusion and valve product suites that reduce operating room turnover time. Abbott competes on sutureless and rapid-deployment designs that shorten cross-clamp duration.
Surgical heart valves are implantable devices fabricated from pyrolytic carbon, bovine pericardium, or porcine aortic tissue, designed to restore unidirectional blood flow across diseased native valves. Bioprosthetic valves incorporate anti-calcification treatments such as ethanol and surfactant washes to extend durability in younger patients. Mechanical valve demand persists in emerging markets where lifelong anticoagulation access remains unreliable. Aortic valve replacement generates the dominant revenue pool, while mitral valve repair applications are expanding fastest as surgeons adopt valve-sparing techniques.
FDA's premarket approval pathway and EMA's MDR conformity assessment create divergent timelines for new valve introductions across major markets. ISO 5840 standards govern in vitro durability testing, accelerating design iteration cycles for manufacturers seeking multi-regional clearance. Stakeholders must monitor CMS's evolving Transcatheter Aortic Valve Replacement (TAVR) coverage determinations, as surgical valve volumes shift based on procedural reimbursement parity between catheter-based and open surgical approaches.
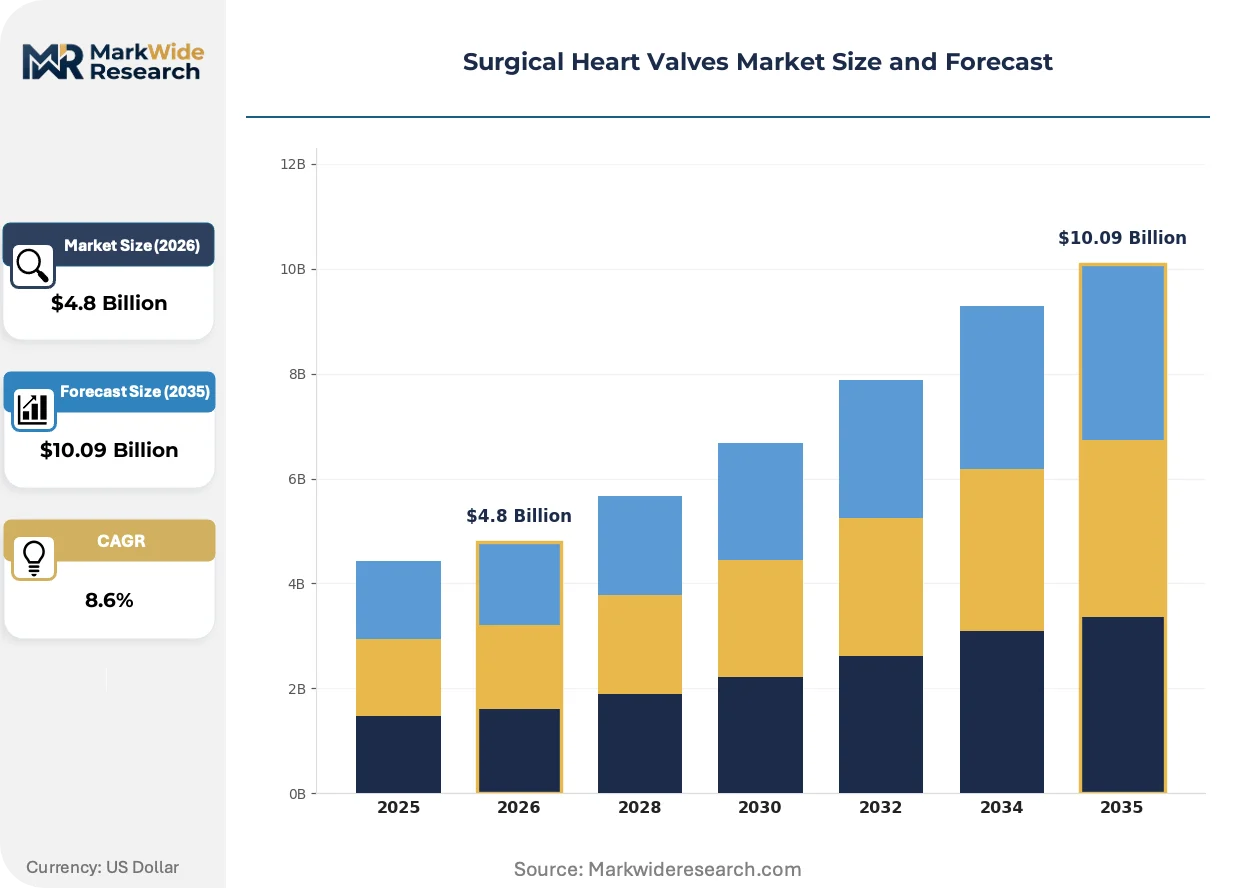
Market Dynamics
Transcatheter delivery systems are compressing surgical valve volumes as interventional cardiologists capture intermediate-risk patients previously routed to cardiac surgeons, forcing manufacturers to defend open-procedure franchises through durability claims and younger-patient positioning.
Growth Catalysts
- Bioprosthetic tissue processing:Anti-calcification treatments including ethanol washes and surfactant soaks extend valve lifespan in patients under sixty-five, expanding the addressable candidate pool beyond elderly populations.
- Medicare reimbursement parity:CMS coverage determinations for tissue valve replacements in the United States reduce out-of-pocket exposure, accelerating hospital procurement of premium bioprosthetic models over mechanical alternatives.
- EMA Medical Device Regulation:MDR conformity assessment pathways in Germany and neighboring markets legitimize next-generation pericardial valves through enhanced clinical evidence requirements, building physician confidence in newer designs.
Market Restraints
- Bovine pericardium supply concentration:Tissue sourcing depends on a limited network of abattoir suppliers in Australia and New Zealand, creating vulnerability to herd health disruptions and export quota fluctuations.
- Lifelong anticoagulation infrastructure:Mechanical valve demand in emerging markets faces constraint from unreliable warfarin monitoring networks and clinic access gaps in rural India and Southeast Asia.
- ISO 5840 durability testing:Accelerated wear protocols require eighteen-to-twenty-four month validation cycles, delaying design iterations and compressing competitive response windows for mid-tier manufacturers.
Strategic Opportunities
- Mitral valve repair expansion:Valve-sparing techniques and annuloplasty band adoption in academic medical centers create adjacency revenue as surgeons preserve native tissue rather than replacing entire valves.
- Sutureless rapid-deployment designs:Cross-clamp time reduction appeals to high-volume surgical centers managing throughput pressure, opening premium positioning for novel deployment mechanisms.
- Integrated perfusion suites:Bundled contracts combining oxygenators, cannulae, and valves reduce operating room turnover time, locking in multi-year hospital commitments through workflow optimization.
Industry Challenges
- Premarket approval timeline compression:FDA PMA pathways for novel valve designs demand extensive clinical follow-up, stretching R&D cycles and requiring sustained capital commitment before revenue realization.
- Transcatheter skill migration:Cardiac surgery fellowship programs face declining open-procedure case volumes as trainees gravitate toward catheter-based interventions, narrowing the specialist pipeline for complex reoperations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Heart Valves Market Trends and Innovations
Device architecture and clinical workflow are converging around durability verification, regulatory harmonization, and procurement consolidation as manufacturers navigate reimbursement compression and procedural volume shifts.
Pyrolytic carbon mechanical valves are migrating from standard tilting-disc configurations toward bileaflet designs with enhanced thromboresistance coatings. High-volume cardiac surgery centers in India and Brazil continue specifying mechanical options for patients under fifty where tissue valve degeneration risks outweigh anticoagulation burdens. This material evolution preserves manufacturer relevance in price-sensitive segments while transcatheter platforms capture premium bioprosthetic growth.
EMA's Medical Device Regulation now mandates systematic post-market clinical follow-up for all Class III implantable devices, including surgical heart valves. Manufacturers must submit periodic safety updates and real-world performance data, increasing compliance overhead but creating competitive moats against undercapitalized entrants. German notified bodies have extended conformity assessment timelines by eight to fourteen months, delaying new product introductions and favoring incumbents with established technical documentation.
Hospital valve purchasing is consolidating under value-analysis committees that bundle cardiac surgery consumables across multiple vendor relationships. Academic medical centers in the United States now negotiate eighteen-to-thirty-six month sole-source agreements covering valves, perfusion circuits, and monitoring accessories. This committee-driven selection process privileges integrated suppliers capable of standardizing equipment interfaces and reducing nursing training burden across catheterization and operating room environments.
Surgical Heart Valves Market Segmentation
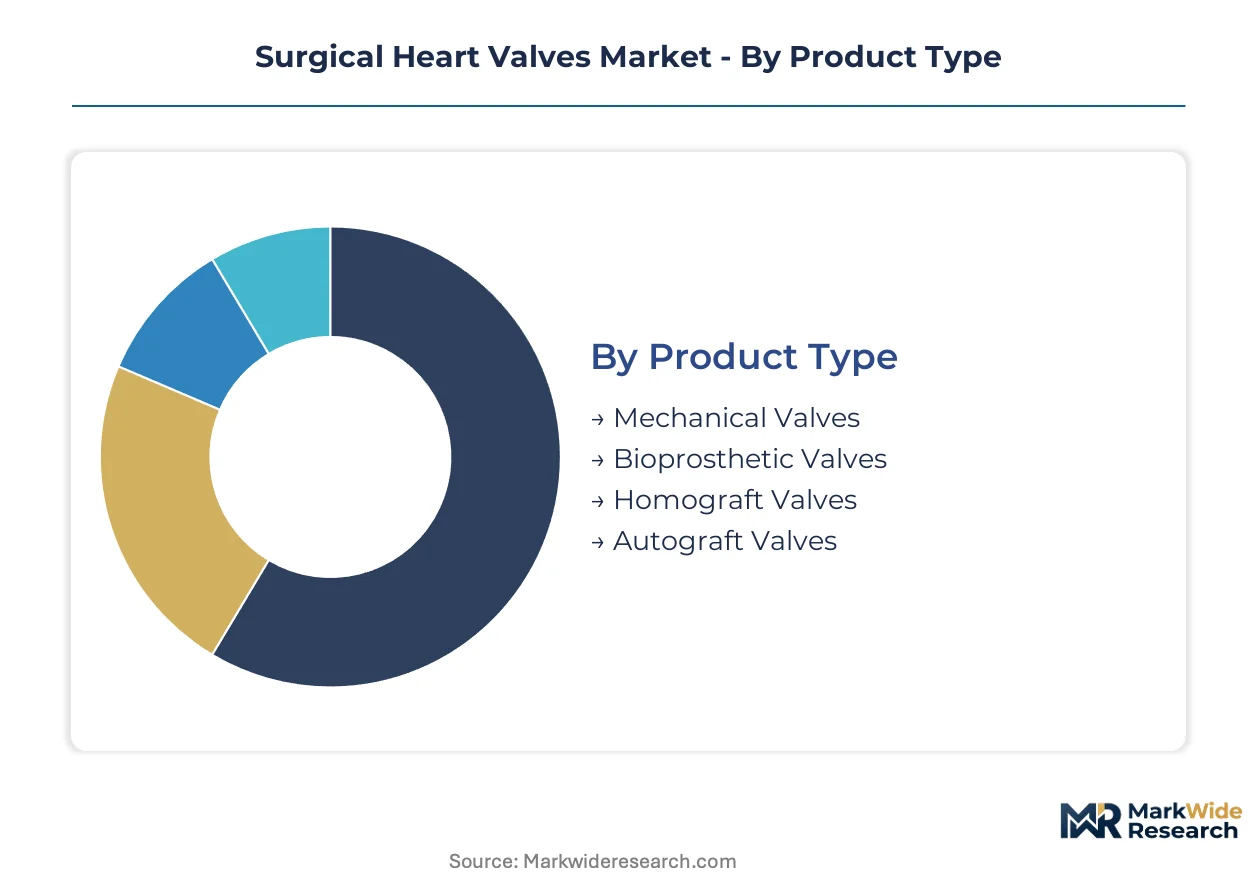
Surgical heart valve segmentation reveals divergent technology trajectories across material science, anatomical positioning, and care delivery settings. Manufacturers calibrate R&D portfolios against procedure volume shifts between open surgical and transcatheter pathways. Hospital procurement committees weight durability claims differently across patient age cohorts and comorbidity profiles.
Product Type:
Material composition and tissue sourcing define cost tiers, reimbursement pathways, and competitive positioning across manufacturer portfolios.
- Mechanical Valves:Pyrolytic carbon bileaflet designs incorporate thromboresistant surface treatments to reduce anticoagulation intensity. Demand persists in India and Brazil where patients under fifty face tissue valve degeneration risks exceeding warfarin monitoring burdens.
- Bioprosthetic Valves:Pericardial and porcine tissue constructs undergo ethanol and surfactant anti-calcification washes to extend functional lifespan. Medicare reimbursement parity in the United States accelerates hospital procurement of premium tissue models over mechanical alternatives in patients over sixty-five.
- Homograft Valves:Cryopreserved human cadaveric tissue eliminates xenogeneic immune response for complex reoperations and endocarditis reconstruction.
- Autograft Valves:Patient-derived pulmonary root transposition enables growth-appropriate pediatric reconstruction with superior hemodynamics.
Mechanical valves hold installed capacity in emerging markets. Bioprosthetic valves are rotating up the share rankings in OECD healthcare systems.
Application:
Anatomical positioning determines surgical complexity, cross-clamp duration requirements, and the competitive threat from transcatheter alternatives.
- Aortic Valve Replacement:Transcatheter platforms have captured intermediate-risk candidates, forcing surgical manufacturers to defend open-procedure franchises through durability claims in younger patients and complex anatomies. Academic medical centers in Germany retain surgical volume for bicuspid valve reconstruction and concomitant root replacement.
- Mitral Valve Replacement:Valve-sparing repair techniques and annuloplasty band adoption expand fastest as surgeons preserve native tissue rather than excising entire valves. EMA MDR post-market surveillance requirements in Germany build physician confidence in newer repair device iterations.
- Tricuspid Valve Repair:Functional regurgitation correction accompanies left-sided procedures, creating secondary device demand.
- Pulmonary Valve Replacement:Congenital heart disease follow-on procedures sustain specialized pediatric and adult congenital service lines.
Aortic valve replacement anchors revenue concentration. Mitral valve repair is climbing the fastest as structural heart programs expand surgical conservation techniques.
End User:
Customer type stratifies procurement authority, case volume thresholds, and bundled contracting sophistication.
- Cardiac Surgery Centers:High-volume institutions negotiate eighteen-to-thirty-six month sole-source agreements covering valves, perfusion circuits, and monitoring accessories. Value-analysis committees in the United States standardize equipment interfaces to reduce nursing training burden across operating room environments.
- Specialty Clinics:Focused valve programs concentrate expertise for complex reoperations and multi-valve procedures.
- Medical Institutes:Training hospitals balance resident education requirements against declining open-procedure case volumes.
- Research Hospitals:Academic centers generate clinical evidence for regulatory submissions and post-market surveillance under EMA MDR mandates.
Cardiac surgery centers concentrate procurement leverage. Specialty clinics are gaining share fastest as regional referral networks consolidate complex case routing.
Deployment:
Care setting determines capital equipment requirements, staffing models, and reimbursement coding complexity.
- Inpatient Surgery:Traditional open-heart procedures require cardiopulmonary bypass infrastructure and intensive care step-down capacity. Medicare diagnosis-related group reimbursement in the United States covers multi-day stays for complex multi-valve reconstruction.
- Outpatient Surgery:Selective low-risk isolated valve procedures migrate to short-stay protocols.
- Ambulatory Care:Diagnostic and surveillance services support longitudinal valve function monitoring.
- Hybrid Operating Rooms:Integrated imaging and catheterization capability enables concomitant surgical and interventional approaches for complex anatomies.
Inpatient surgery retains case volume concentration. Hybrid operating rooms are expanding most quickly as structural heart programs invest in convergent procedure platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German cardiac surgery centers where EMA MDR compliance commands premium valve procurement, while Indian institutions absorb cost compression from mechanical valve demand in younger patient cohorts.
United States
Medicare reimbursement parity for tissue valve replacements drives hospital procurement of premium bioprosthetic models. FDA premarket approval pathways stretch eighteen-to-twenty-four month validation cycles for novel designs. The Cleveland Clinic and Mayo Clinic anchor academic medical center networks that negotiate sole-source agreements covering valves, perfusion circuits, and monitoring accessories.
Germany
Cardiac surgery centers in Munich and Berlin expand bioprosthetic valve adoption under EMA Medical Device Regulation conformity assessments. Notified bodies have extended technical documentation review timelines by eight to fourteen months. The German Heart Center Berlin generates clinical evidence for post-market surveillance mandates, building physician confidence in newer pericardial valve iterations.
India
Mechanical valve demand persists for patients under fifty where tissue valve degeneration risks exceed warfarin monitoring burdens. The country's national pharmaceutical regulator oversees device import licensing amid unreliable anticoagulation infrastructure in rural regions. Chennai and Bangalore host high-volume cardiac surgery centers that specify pyrolytic carbon bileaflet designs for price-sensitive segments.
China
Domestic manufacturers advance pericardial tissue processing capabilities to capture share from imported premium models. The National Medical Products Administration harmonizes in vitro durability testing with ISO 5840 standards. Shanghai and Beijing academic medical centers pilot valve-sparing repair techniques as structural heart programs expand surgical conservation volumes.
Brazil
Mechanical valve specifications dominate public hospital procurement for patients under fifty-five facing lifelong anticoagulation access constraints. ANVISA regulates device registration through risk-based classification pathways. São Paulo cardiac surgery centers concentrate expertise for complex reoperations while regional referral networks consolidate case routing from interior states.
Surgical Heart Valves Market Competitive Landscape
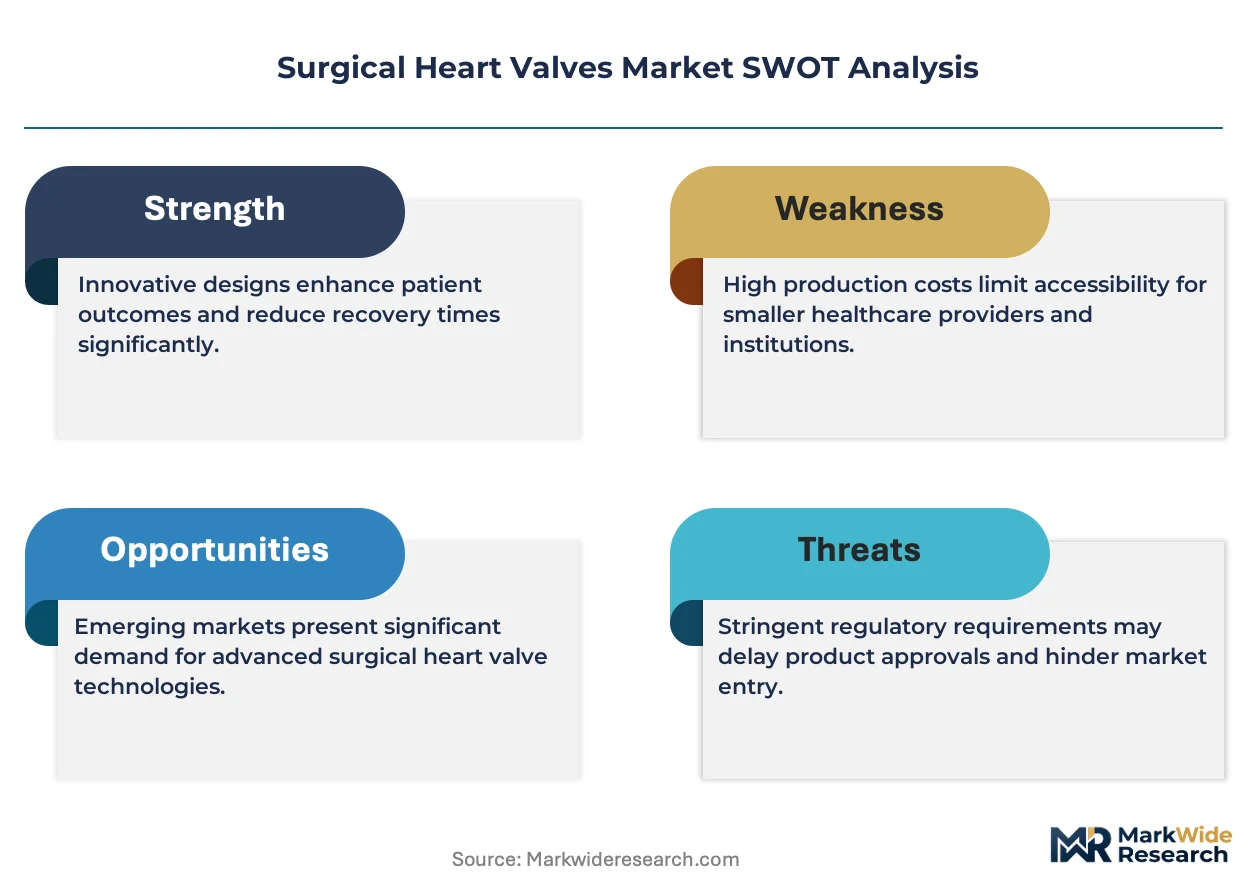
Platform integrators command the system tier; component specialists sit upstream. The surgical heart valve market structures around consolidated incumbents with integrated perfusion portfolios and mid-tier challengers competing on deployment mechanism innovation. Three archetypes dominate: tissue processing specialists leveraging anti-calcification intellectual property, rapid-deployment engineers compressing cross-clamp intervals, and bundled contract orchestrators standardizing operating room workflows. Competitive moves concentrate on strategic partnerships for annuloplasty band adjacencies and vertical integration into bovine pericardium supply security.
Within the integrated platform tier, Edwards Lifesciences and Medtronic anchor multi-regional presence through divergent strategic postures. Edwards Lifesciences occupies a position exemplifying tissue processing premiumization in academic medical centers. Medtronic represents the perfusion-suite bundling archetype that reduces operating room turnover time through consolidated vendor relationships. Abbott sits within the rapid-deployment engineering cluster, competing on sutureless designs that shorten cross-clamp duration for high-volume surgical centers managing throughput pressure.
| Leading Market Players |
|---|
| Edwards Lifesciences |
| Medtronic |
| Abbott |
| Boston Scientific |
| LivaNova |
| Artivion |
| Meril Life Sciences |
| Venus Medtech |
| Braile Biomedica |
| Others |
Pricing and Supply Chain Analysis
Queensland and New South Wales abattoir clusters in Australia concentrate bovine pericardium supply, translating tissue sourcing scarcity into premium pricing power for anti-calcification processed valves sold to German cardiac surgery centers under EMA MDR compliance requirements.
Pricing Analysis
Configured-to-order pricing for patient-specific annuloplasty bands and rapid-deployment mechanisms commands spreads of forty-to-sixty percent above standard mechanical valve catalog pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 5840 durability certification tier and anti-calcification treatment intensity. Pricing pressure stems from transcatheter platform capture of intermediate-risk aortic procedures, compressing open-surgical valve margins. Public hospital procurement in Brazil and India exhibits highest price sensitivity, while academic medical centers in the United States absorb premium positioning for sutureless designs.
Supply Chain Analysis
Contract manufacturing concentration for pyrolytic carbon leaflets centers on specialized foundries in the United States and Germany, with Singapore emerging for precision machining of deployment frames. Raw material flows draw from Australian and New Zealand bovine tissue networks, pyrolytic carbon feedstock from aerospace-grade suppliers, and titanium alloy sources from Japanese and Chinese mills. Single-source vulnerability concentrates in bovine pericardium traceability chains subject to herd health export disruptions. Distribution runs through hospital value-analysis committees and group purchasing organizations consolidating multi-year vendor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as integrated perfusion-valve suites displace standalone component purchasing, with interoperability between oxygenators, cannulae, and valve deployment systems determining hospital procurement decisions.
For Market Incumbents: Insulate open-procedure franchises by deepening backward integration into bovine pericardium supply security and accelerating ISO 5840 durability certification for next-generation anti-calcification treatments. Transcatheter platform expansion into intermediate-risk patients threatens surgical valve volumes; defend positioning through younger-patient durability claims and complex anatomy specialization. For New Entrants and Emerging Players: Pursue mitral valve repair adjacencies including annuloplasty bands and valve-sparing instrumentation where transcatheter alternatives remain technically constrained. Sutureless rapid-deployment mechanisms for high-volume cardiac surgery centers offer the most penetrable entry vector; partner with perfusion equipment distributors for bundled contract access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tissue processing specialists with captive anti-calcification intellectual property and established EMA MDR technical documentation. Long-term viability hinges on navigating reimbursement parity between catheter-based and surgical approaches. Watch CMS TAVR coverage determinations and German notified body conformity assessment timelines as inflection indicators for surgical valve volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bovine Pericardium Supply | Captive tissue sourcing from Queensland abattoirs insulates against export quota volatility and herd health disruptions. |
| EMA MDR Conformity Assessment Acceleration | Compressed notified body timelines in Germany unlock premium positioning for next-generation pericardial valve iterations. |
| Sutureless Rapid-Deployment Platform Launch | Cross-clamp time reduction appeals to high-volume cardiac surgery centers managing throughput pressure. |
| Hospital System Partnership for Bundled Contracts | Eighteen-to-thirty-six month sole-source agreements lock in multi-year commitments through perfusion suite standardization. |
| Mitral Valve Repair Device Reimbursement Strategy | CMS coverage parity for annuloplasty bands accelerates adoption of valve-sparing techniques over replacement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers; and secondary validation against FDA PMA filings, EMA MDR technical documentation, ISO 5840 durability testing protocols, and CMS Medicare reimbursement databases. Bottom-up triangulation of hospital procurement volumes and top-down manufacturer revenue reconciliation anchored segmentation sizing.
Forecast inputs span product type, application anatomy, end-user institution tier, and deployment setting across the projection horizon. CAGRs derive from procedure volume elasticity to reimbursement parity, transcatheter platform penetration curves, and tissue valve durability improvement trajectories. Modeled variables include anti-calcification treatment adoption rates and mechanical valve demand persistence in emerging markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic Chinese manufacturers or transcatheter platform specialists would shift outcomes beyond modeled ranges. Quarterly review of German notified body assessment timelines, CMS TAVR coverage determinations, and Australian bovine tissue export quotas is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.