
 Cardiovascular Ultrasound Imaging Systems Market | 2026-2036
Cardiovascular Ultrasound Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Ultrasound Imaging Systems Market Outlook
Software-defined workflow subscriptions is expanding how cardiovascular ultrasound vendors monetize hardware placements, shifting revenue toward recurring diagnostic service agreements. GE Healthcare leverages its Edison AI platform to sustain predictive maintenance contracts across installed base fleets. Koninklijke Philips N.V. anchors its cardiovascular ultrasound business through integrated enterprise imaging networks that span cath labs to outpatient clinics. Siemens Healthineers AG differentiates via advanced signal processing algorithms embedded in subscription-tier feature unlocks.
Cardiovascular ultrasound imaging systems employ piezoelectric transducers operating at 2-15 MHz to generate real-time anatomical and hemodynamic visualizations of cardiac structures, with Doppler modes measuring blood flow velocity and turbulence for functional assessment. The technology serves primarily non-invasive diagnosis of valvular disorders, cardiomyopathies, and congenital defects across acute and ambulatory settings. Portable ultrasound systems now represent the fastest-expanding product category as point-of-care cardiology decentralizes from centralized radiology departments, while 3D ultrasound captures disproportionate margin pools due to complex probe manufacturing and specialized clinical training requirements. Doppler ultrasound maintains mature volume leadership in routine stress echo and hemodynamic monitoring protocols.
The FDA governs 510(k) clearance pathways for cardiovascular ultrasound devices including AI-assisted measurement tools, while the EU Medical Device Regulation mandates updated clinical evidence standards for echocardiography systems sold in European markets. ISO 13485 quality management certification shapes supplier qualification for transducer manufacturing and final system assembly. Stakeholders must monitor evolving software-as-medical-device classifications that determine whether algorithm updates trigger new regulatory submissions or qualify as managed service enhancements.
Market Dynamics
Point-of-care decentralization is compressing traditional radiology department workflows, with portable ultrasound systems displacing fixed-console installations in acute cardiac settings and ambulatory clinics.
Growth Catalysts
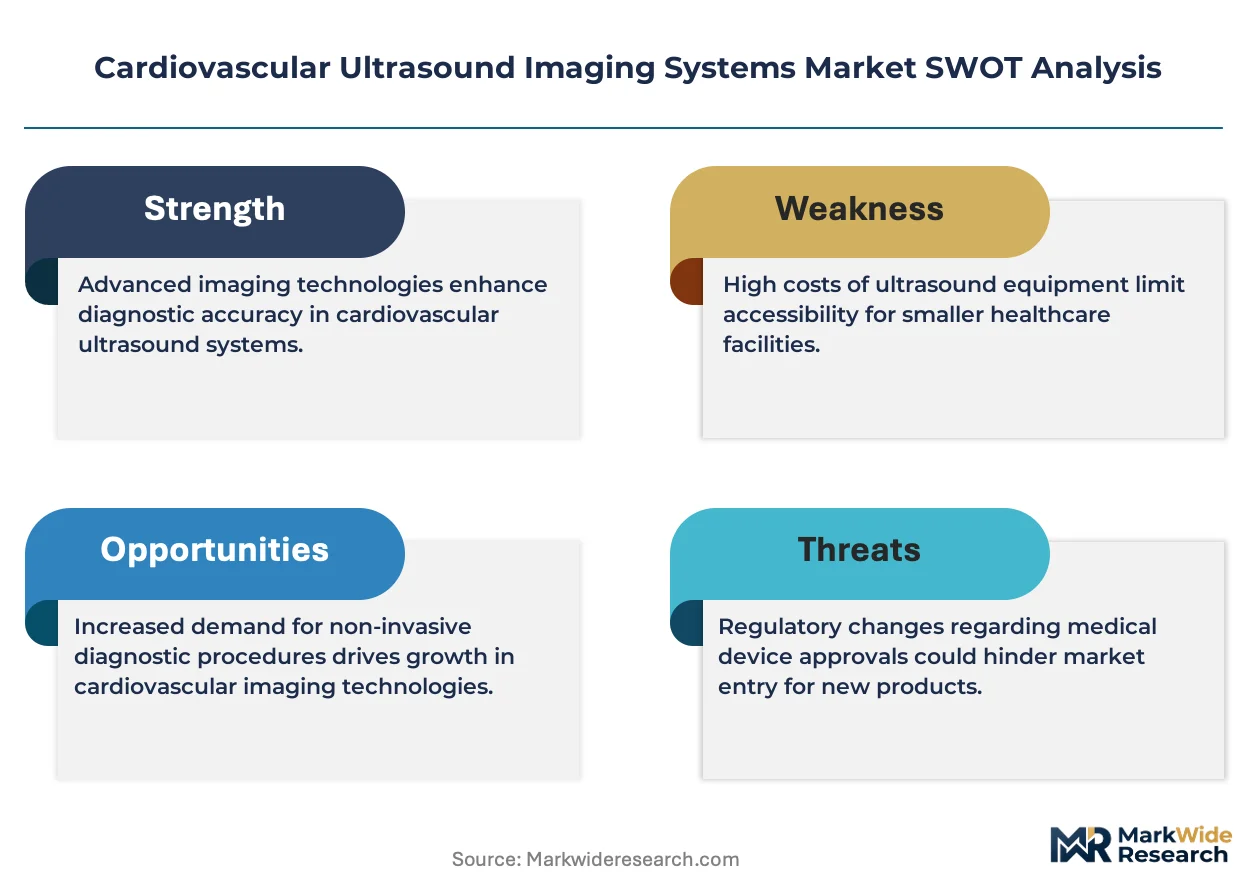
- EU Medical Device Regulation (MDR) harmonization:Updated clinical evidence standards for echocardiography systems are streamlining cross-border market access and reducing redundant certification burdens for manufacturers.
- AI-enhanced measurement tools:FDA 510(k) clearance pathways for software-as-medical-device features are accelerating algorithm integration into diagnostic workflows.
- Aging demographics in Japan, Germany, and the United States:Structural investment in non-invasive cardiac assessment infrastructure is expanding installed base replacement cycles.
Market Restraints
- Piezoelectric crystal supply concentration:Transducer manufacturing depends on specialized ceramic suppliers concentrated in East Asian production clusters, creating input vulnerability.
- 3D probe manufacturing complexity:Precision assembly requirements for matrix array transducers limit supplier qualification and extend lead times for premium system configurations.
- CT coronary angiography substitution:Non-invasive CT-based functional assessment is capturing intermediate-risk chest pain referrals from stress echocardiography protocols.
Strategic Opportunities
- Rural and community hospital penetration in the United States:Underserved regions lack on-site cardiologist coverage, creating demand for telemedicine-integrated portable systems with remote interpretation support.
- Subscription-tier feature unlocks:Siemens Healthineers' advanced signal processing algorithms demonstrate recurring revenue potential through software-defined capability expansion.
- Integrated enterprise imaging networks:Koninklijke Philips N.V. spans cath labs to outpatient clinics, showing how vendor-neutral archive connectivity creates platform stickiness.
Industry Challenges
- Specialized sonographer training gaps:3D echocardiography and strain imaging require advanced certification pathways that outpace clinical education program expansion.
- Legacy PACS integration friction:New AI-enhanced systems must interface with decade-old hospital IT infrastructure, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Ultrasound Imaging Systems Market |
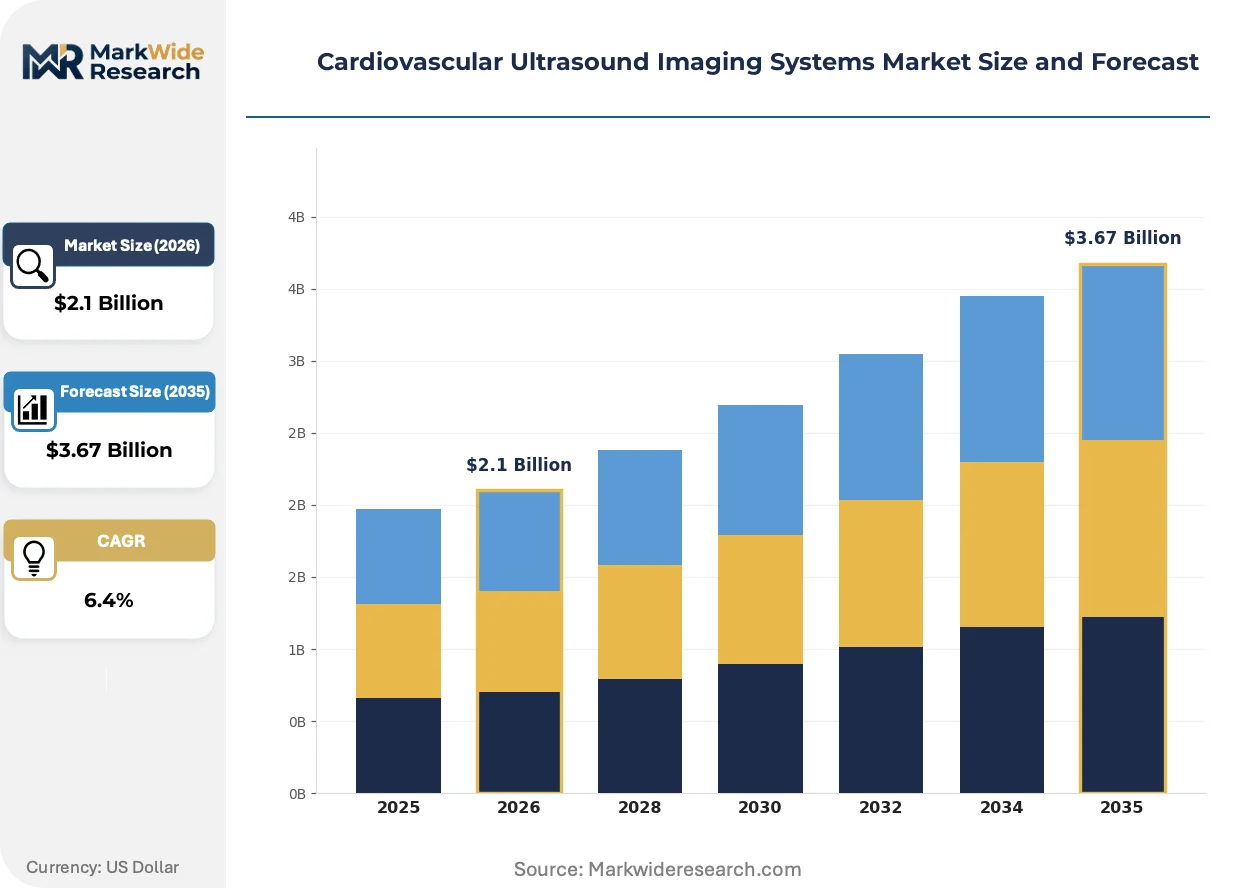
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Ultrasound, 3D Ultrasound, Doppler Ultrasound, Portable Ultrasound Technology: Printable Sensors, Contrast Echo, Mobile Imaging, Advanced Signal Processing End User: Cardiology Clinics, Diagnostic Centers, Hospitals, Research Laboratories Application: Cardiac Cycle Assessment, Atrial Septal Defect Detection, Valve Stenosis Evaluation, Congenital Heart Disease Screening |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers AG, Canon Medical Systems, Mindray Medical International Limited, Samsung Medison Co., Ltd., FUJIFILM SonoSite, Inc., Esaote, Hitachi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Ultrasound Imaging Systems Market Strategic Shifts
Workflow automation and algorithmic decision support are displacing manual measurement protocols, while regulatory frameworks evolve to classify software updates as managed service enhancements rather than new device submissions.
Machine learning-based left ventricular ejection fraction calculation is automating quantitative assessment that previously required manual tracing by experienced sonographers. Community hospitals and urgent care centers are adopting these tools to reduce inter-operator variability and expand diagnostic capacity without specialist staffing. The technology is automating routine measurements and compressing examination duration, enabling higher patient throughput in resource-constrained settings.
The FDA's updated premarket notification pathways for software-as-medical-device features are reshaping how cardiovascular ultrasound vendors release algorithmic enhancements. Manufacturers can now deploy predictive maintenance and automated quality assurance tools through cloud-based subscription models without triggering full 510(k) resubmission. Hospital cardiology departments in the United States are responding by accelerating procurement of AI-integrated systems that promise reduced downtime and standardized output.
Diagnostic service unbundling is fragmenting traditional capital equipment sales into recurring revenue relationships. Health systems now negotiate software-defined workflow subscriptions separately from hardware acquisition, with predictive maintenance contracts and enterprise imaging network access sold as ongoing services. This pattern is most visible in Germany and Japan, where aging installed bases create aftermarket monetization opportunities for vendors with platform-integrated AI architectures.
Cardiovascular Ultrasound Imaging Systems Market Segmentation
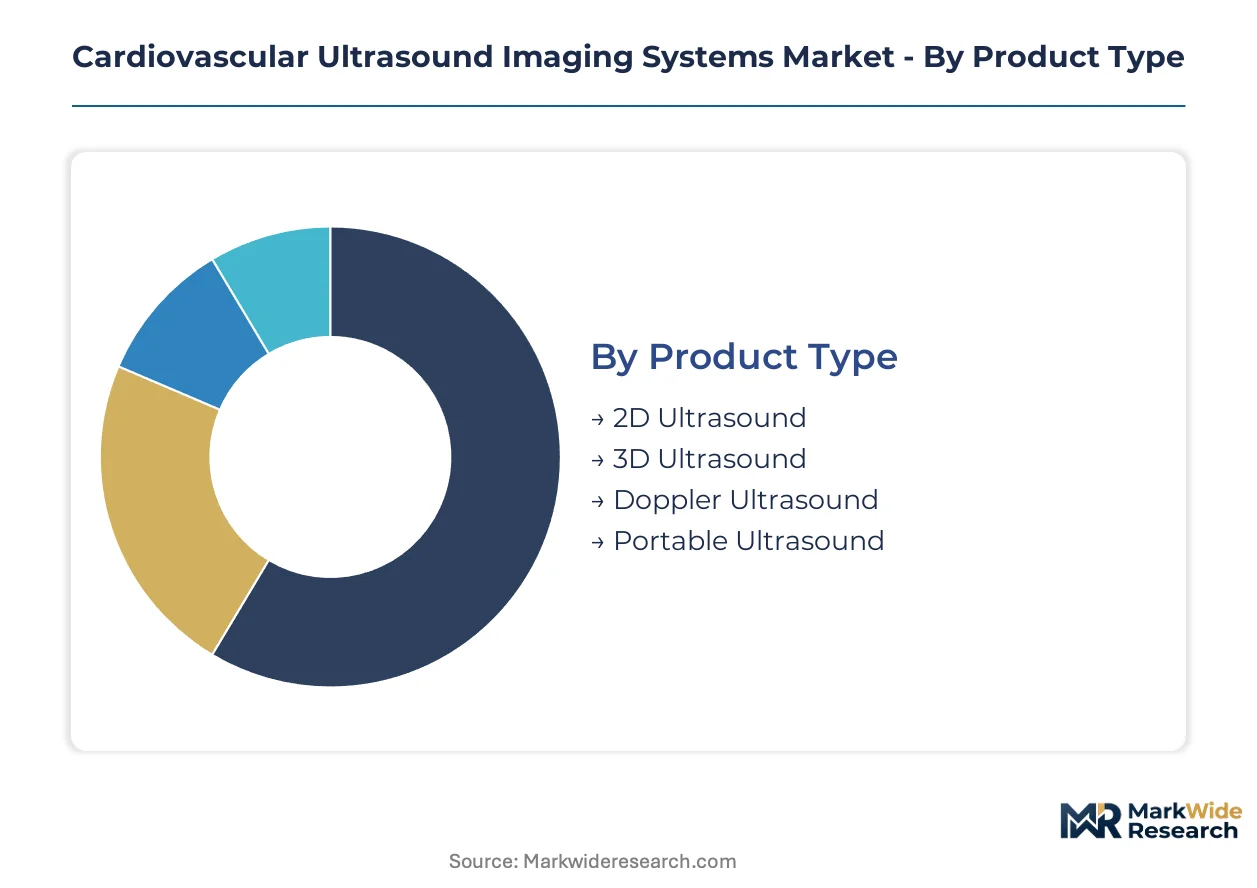
Segmentation in cardiovascular ultrasound imaging reveals distinct procurement patterns across clinical settings. Product configuration, technology integration depth, and end-user infrastructure determine pricing tiers and replacement cycles.
Product Type:
Standalone console systems serve centralized radiology departments, while portable configurations embed into point-of-care workflows across dispersed clinical sites.
- 2D Ultrasound:Conventional sector-array transducers generate real-time grayscale anatomical visualizations at 2-5 MHz for routine structural assessment. Hospital cardiology departments in the United States and Germany rely on these systems for high-volume screening protocols where throughput outweighs advanced functionality.
- 3D Ultrasound:Matrix-array probes with 3000-4000 active elements reconstruct volumetric cardiac datasets through beam steering electronics. Premium installations concentrate in Japanese quaternary centers where complex congenital interventions demand precise spatial orientation; probe manufacturing complexity limits supplier qualification and extends lead times.
- Doppler Ultrasound:Pulsed-wave and continuous-wave modes quantify blood flow velocity gradients across valves and septal defects. Mature installed bases in diagnostic centers drive replacement demand for systems with integrated strain imaging.
- Portable Ultrasound:Battery-powered cart-based and handheld devices operating at 1.5-3 kg deploy to bedside and ambulatory settings. Community hospitals in underserved US regions adopt these for telemedicine-integrated remote interpretation.
Volume placements concentrate in Doppler and 2D systems; the steepest expansion trajectory belongs to portable configurations.
Technology:
Cost tiers separate mature imaging modalities from emerging sensor architectures and algorithmic enhancements.
- Printable Sensors:Flexible polymer-based transducer arrays fabricated through microelectromechanical processes enable disposable probe economics. Research laboratories in Germany pilot these for infection control in interventional settings where sterilization costs dominate lifecycle economics.
- Contrast Echo:Microbubble-enhanced perfusion imaging using sulfur hexafluoride or perfluoropropane agents visualizes myocardial blood flow at capillary level. Cardiology clinics in Japan leverage this for viability assessment in ischemic cardiomyopathy where perfusion defects guide revascularization decisions.
- Mobile Imaging:Tablet-controlled systems with cloud-archived DICOM connectivity extend diagnostic capacity beyond fixed infrastructure. Diagnostic centers in rural United States deploy these for outreach screening programs.
- Advanced Signal Processing:Synthetic aperture beamforming and adaptive noise reduction algorithms extract diagnostic data from suboptimal acoustic windows. Siemens Healthineers embeds these as subscription-tier unlocks in premium system configurations.
Standard deployments cluster around mobile imaging and contrast echo; printable sensors are gaining share fastest as manufacturing scales.
End User:
Customer type determines integration requirements from enterprise PACS connectivity to standalone operation.
- Cardiology Clinics:Outpatient-focused practices prioritize workflow efficiency and rapid report generation for fee-for-service reimbursement. US-based multispecialty groups consolidate purchasing through group purchasing organizations.
- Diagnostic Centers:High-throughput facilities serving multiple referring specialties demand vendor-neutral archive compatibility and automated measurement protocols. German diagnostic chains negotiate enterprise imaging network subscriptions.
- Hospitals:Acute care settings require 24/7 reliability, predictive maintenance contracts, and cath lab integration. Japanese hospital systems emphasize AI-enhanced measurement tools for sonographer workforce constraints.
- Research Laboratories:Academic medical centers drive early adoption of experimental modalities including shear wave elastography and 4D flow quantification. Funding cycles determine procurement timing independent of clinical replacement schedules.
Installed base concentration sits with hospitals; diagnostic centers are expanding most quickly through consolidation and capital partnerships.
Application:
Clinical indication specificity shapes transducer frequency selection and examination protocol complexity.
- Cardiac Cycle Assessment:Left ventricular ejection fraction and diastolic function quantification using Simpson's biplane method or automated border detection. Routine volume leader across all end-user settings.
- Atrial Septal Defect Detection:Subcostal and transesophageal imaging with color Doppler shunt characterization. Pediatric cardiology centers in the United States specialize in these protocols.
- Valve Stenosis Evaluation:Continuity equation and pressure half-time calculations for aortic and mitral valve gradients. German heart valve centers integrate these measurements into multidisciplinary heart team decisions.
- Congenital Heart Disease Screening:Segmental sequential analysis for complex anatomy including transposition and single-ventricle physiology. Japanese referral centers maintain specialized sonographer certification pathways.
Examination volume concentrates in cardiac cycle assessment; congenital screening protocols are climbing fastest as fetal echocardiography expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of piezoelectric transducers and ultrasound console assemblies concentrates in East Asian production clusters, while demand for cardiovascular imaging systems concentrates in aging Western markets and advanced Asian healthcare systems.
United States
Hospital cardiology departments are expanding point-of-care deployments of portable ultrasound systems for bedside diagnostics and emergency department triage. The FDA's updated 510(k) premarket notification pathways for software-as-medical-device features are accelerating AI-enhanced workflow integration into clinical practice. Boston and Minneapolis medical device clusters host engineering centers developing advanced signal processing algorithms for next-generation systems.
Germany
Diagnostic centers and university hospitals are driving replacement demand for 3D echocardiography systems with integrated strain imaging capabilities. The EU Medical Device Regulation mandates updated clinical evidence standards that streamline cross-border certification while raising documentation requirements for echocardiography manufacturers. The Baden-Württemberg region around Stuttgart maintains specialized supplier networks for precision transducer manufacturing and final system assembly.
Japan
Quaternary cardiac centers are adopting premium 3D ultrasound configurations for complex congenital interventions and structural heart procedures. The Pharmaceuticals and Medical Devices Agency maintains rigorous premarket approval processes that favor established manufacturers with extensive clinical validation datasets. Tokyo and Osaka metropolitan areas concentrate installed base replacement cycles and specialized sonographer training programs.
China
Domestic manufacturers are expanding production capacity for mid-tier portable ultrasound systems serving county-level hospitals and community health centers. The National Medical Products Administration harmonizes technical review standards with international norms while prioritizing local innovation in probe miniaturization and wireless connectivity. Shenzhen and Shanghai industrial zones host assembly operations for both indigenous brands and multinational joint ventures.
India
Private diagnostic chains and corporate hospital networks are importing portable cardiovascular ultrasound systems to address cardiologist shortages in tier-2 and tier-3 cities. The Central Drugs Standard Control Organization regulates device import and distribution through notified body partnerships that streamline registration for established global manufacturers. Bangalore and Hyderabad medical technology corridors are emerging as service hubs for AI-enhanced diagnostic software development and remote interpretation platforms.
Cardiovascular Ultrasound Imaging Systems Market Competitive Environment
Top-tier vendors anchor the premium console and 3D imaging segment, while mid-tier specialists and regional manufacturers compete on portable system cost and local service responsiveness. Market structure reflects a bifurcated pattern where integrated healthcare conglomerates with enterprise imaging platforms coexist with focused ultrasound pure-plays. Strategic archetypes include AI-platform integrators leveraging predictive maintenance contracts, enterprise network orchestrators spanning cath lab to outpatient workflows, and hardware-centric suppliers emphasizing probe manufacturing precision. Dominant competitive moves encompass subscription-tier feature unlocks for recurring revenue conversion and telemedicine-integrated portable system partnerships for rural market penetration.
Among diversified healthcare technology conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify platform-integrated positioning that extends beyond hardware into software-defined service relationships. Siemens Healthineers AG occupies a comparable tier with emphasis on algorithmic differentiation through subscription-accessible capabilities. These three entities represent the consolidation vector where enterprise imaging network scale and AI architecture investment create defensive positioning against specialized competitors.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Canon Medical Systems |
| Mindray Medical International Limited |
| Samsung Medison Co., Ltd. |
| FUJIFILM SonoSite, Inc. |
| Esaote |
| Hitachi Ltd |
| Others |
Value Chain & Pricing Dynamics
Specialized sonographer certification programs concentrated in Japanese quaternary centers and German university hospitals create labor-cost differentials that widen pricing-tier spreads between premium 3D systems and portable economy configurations. This workforce scarcity in advanced imaging protocols forces vendors to bundle training subsidies into premium console pricing while stripping service components from mid-tier portable offerings.
Pricing Analysis
Margin tightening in economy-tier portable systems reflects aggressive penetration pricing by Chinese and Korean manufacturers seeking installed base footholds. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced enterprise platforms from basic Doppler configurations and handheld devices, with price differentiation driven by algorithmic capability depth and ISO 13485 certification tier. Cost-down pressure on mid-range cart-based systems accelerates as hospital purchasing committees consolidate vendor relationships. Diagnostic centers in Germany exhibit lowest price sensitivity due to reimbursement stability, while Indian private hospital networks negotiate hardest on upfront capital outlay.
Supply Chain Analysis
ISO 13485 quality certification gates supplier qualification for piezoelectric crystal fabrication and final transducer assembly, concentrating qualified component sourcing in Japan, Germany, and select East Asian production clusters. Raw material dependencies include lead zirconate titanate ceramics, precision-machined lens housings, and application-specific integrated circuits for beamforming electronics. Single-source vulnerability concentrates in specialized ceramic suppliers serving matrix-array probe manufacturing. Distribution runs through direct hospital system contracts in developed markets and distributor networks with local service capabilities in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable AI-enhanced systems are displacing fixed-console installations as the dominant procurement pattern, with algorithmic workflow automation replacing manual measurement protocols across acute and ambulatory settings.
For Market Incumbents: Lock in enterprise imaging network stickiness through predictive maintenance contracts spanning cath lab to outpatient clinic workflows. Deepen backward integration into transducer manufacturing to reduce exposure to East Asian ceramic supply concentration. Defend against CT coronary angiography substitution by embedding strain imaging and 3D quantification as standard rather than premium-tier features. For New Entrants and Emerging Players: Capture rural United States community hospital demand through telemedicine-integrated portable systems with remote interpretation support. Target Indian tier-2 and tier-3 cities where cardiologist shortages create whitespace for AI-automated diagnostic tools. Pursue software-as-medical-device regulatory pathways that enable subscription revenue without full hardware certification cycles. For Investors and Strategic Acquirers: Re-rating potential sits with AI-platform integrators possessing FDA-cleared algorithm portfolios and established hospital system relationships given reimbursement tailwinds for automated measurement protocols. Long-term viability favors vendors with enterprise archive connectivity and recurring service revenue exceeding fifty percent of total mix. Monitor FDA software-as-medical-device guidance evolution as inflection signal for capital-light business model viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Workflow Integration | FDA 510(k) clearance for automated ejection fraction calculation accelerates hospital procurement decisions. |
| Subscription-Tier Feature Unlocks | Siemens Healthineers' signal processing algorithms demonstrate recurring revenue conversion from hardware placements. |
| Telemedicine-Integrated Portable Systems | Remote interpretation partnerships address cardiologist shortages in underserved United States regions. |
| Enterprise Imaging Network Expansion | Koninklijke Philips N.V. spans cath labs to outpatient clinics creating platform switching costs. |
| Backward Integration into Transducer Manufacturing | GE Healthcare's Edison AI platform leverages captive probe supply for predictive maintenance contracts. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital procurement database records, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sonographer training program directors. Secondary validation drew from SEC 10-K disclosures, ISO 13485 certification registries, and clinical society guideline publications. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates.
Cross-referencing historical replacement cycle patterns with panel input from cardiology department heads informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, technology integration depth, end-user infrastructure tier, and regional regulatory cluster. CAGRs were derived from installed base growth projections and average selling price trajectory assumptions, with specific inputs for AI software attachment rates and portable system penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device reclassification decisions and CT coronary angiography reimbursement parity shifts. Forecasts reflect documented assumptions regarding sonographer workforce expansion and hospital capital budget allocation priorities. A model refresh is warranted upon material change in EU MDR enforcement stringency or major health system consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Vascular Prostheses Market