
 UAE Cardiovascular Devices Market | 2026-2036
UAE Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Cardiovascular Devices Market Analytics
Project finance for cath lab infrastructure is narrowing the competitive field to operators with balance-sheet capacity or sovereign-linked backing. Siemens Healthineers AG leverages its imaging-therapy integration to anchor premium tender positions across UAE Ministry of Health facilities. Abbott Laboratories sustains catheter and structural heart portfolios through deep inventory partnerships with private hospital groups. Medtronic dominates cardiac rhythm management with localized technical service teams that reduce equipment downtime.
Cardiovascular devices encompass implantable and interventional instruments—stents, pacemakers, catheters, and valves—typically manufactured from nitinol, cobalt-chromium alloys, or bioresorbable polymers, designed to restore hemodynamic function through percutaneous or surgical delivery. Coronary stent deployment represents the most mature revenue pool, while transcatheter valve segments capture expanding margin as procedural volume shifts from open surgery to minimally invasive approaches. Robotic surgery technology is gaining fastest adoption among specialty heart institutes seeking differentiated patient outcomes and reduced length-of-stay metrics.
MOHAP, the Dubai Health Authority, and the UAE's mandatory health insurance framework jointly shape device reimbursement pathways and facility accreditation standards that determine market access. SFDA-aligned import controls and MOHAP post-market surveillance requirements enforce traceability and clinical evidence thresholds for new device registrations. Stakeholders must monitor how Dubai's mandatory health insurance expansion into Northern Emirates reshapes patient referral patterns and procurement concentration.
Market Dynamics
Catheterization lab infrastructure expansion across Dubai and Abu Dhabi is concentrating procurement power among sovereign-backed hospital networks, squeezing mid-tier distributors and favoring device manufacturers with localized technical service capabilities and inventory partnerships.
Growth Catalysts
- MOHAP Mandatory Insurance Framework:The UAE's compulsory health coverage expansion under MOHAP and Dubai Health Authority is accelerating patient access to interventional cardiology procedures across Northern Emirates.
- Transcatheter Valve Replacement:Minimally invasive structural heart procedures are displacing open surgical volumes at tertiary cardiac centers in Dubai Healthcare City and Cleveland Clinic Abu Dhabi.
- Robotic Surgery Adoption:Specialty heart institutes are deploying robotic-assisted platforms to differentiate on patient outcomes and reduce length-of-stay metrics.
Market Restraints
- Nitinol and Cobalt-Chromium Supply Concentration:Specialty alloy feedstock for stent and valve manufacturing concentrates among a limited supplier base, exposing device makers to input cost volatility.
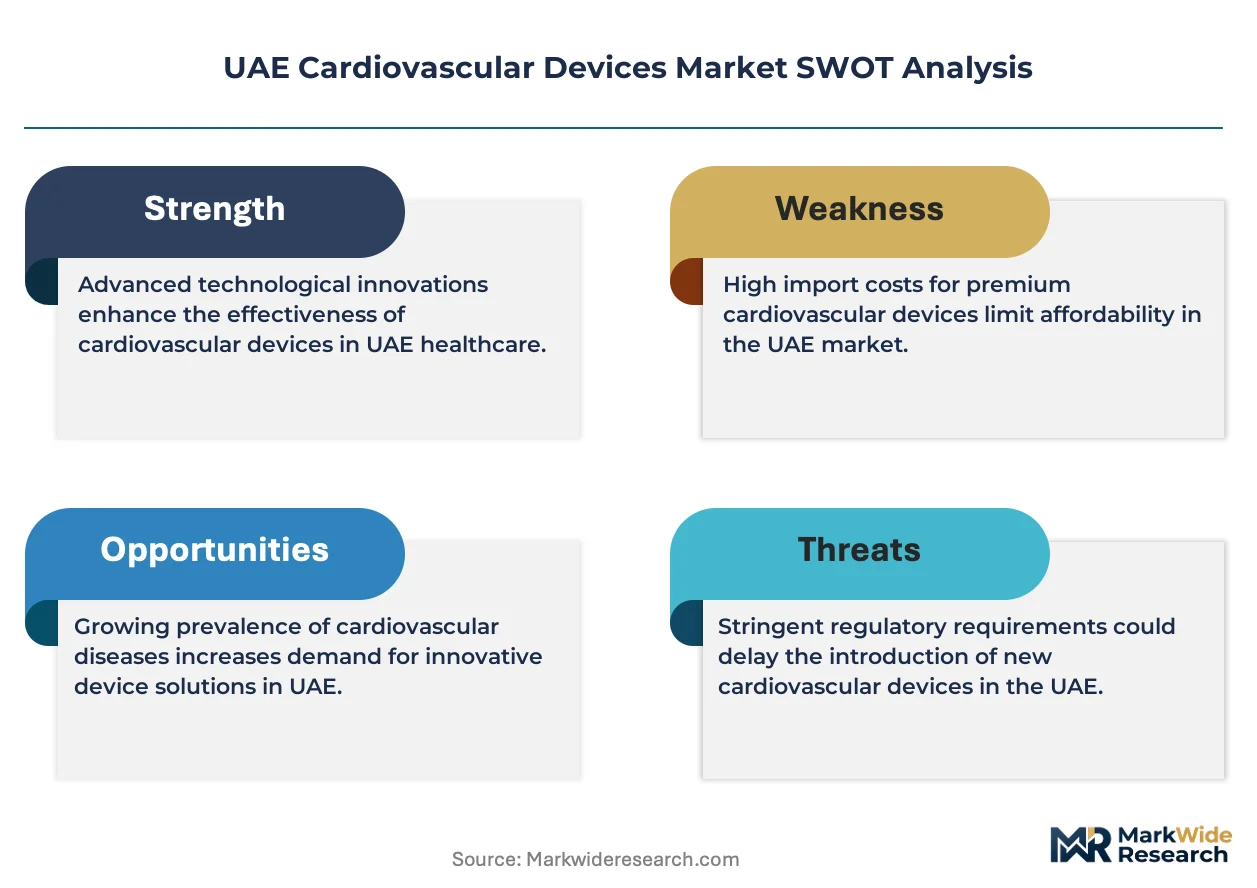
- SFDA-Aligned Import Controls:Post-market surveillance and traceability requirements for new device registrations create extended approval timelines for novel bioresorbable polymer platforms.
- Open Surgical Substitution:Conventional coronary artery bypass grafting retains preference among certain patient cohorts, limiting transcatheter valve penetration in complex anatomies.
Strategic Opportunities
- Northern Emirates Coverage Expansion:Dubai's mandatory health insurance extension into Ras Al Khaimah, Fujairah, and Umm Al Quwain is creating referral pattern shifts and procurement concentration opportunities.
- Imaging-Therapy Integration:Convergence of intravascular imaging with interventional platforms enables real-time procedural guidance and premium tender positioning.
- Local Technical Service Teams:On-site cardiac rhythm management support capabilities reduce equipment downtime and anchor long-term service contracts with private hospital groups.
Industry Challenges
- Interventional Cardiologist Training Pipeline:Complex transcatheter procedures require specialized fellowship pathways that remain underdeveloped relative to procedural volume growth.
- Catheterization Lab Capex Intensity:Each new cath lab installation demands multimillion-dirham imaging, hemodynamic monitoring, and sterilization infrastructure commitments.
- Legacy System Integration:Robotic surgery platforms must interface with existing PACS and EMR architectures, creating interoperability friction during deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Cardiovascular Devices Market |
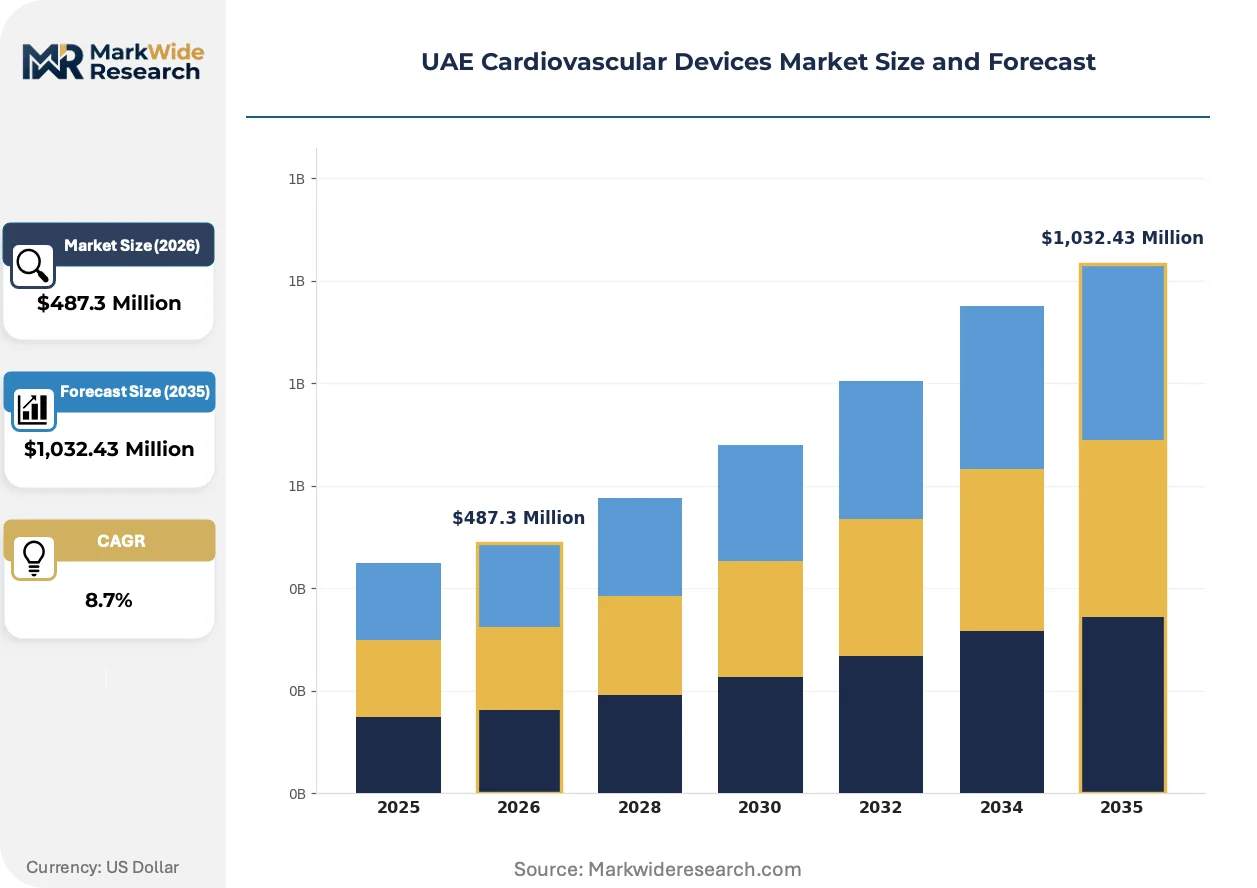
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves Technology: Bioresorbable, Minimally Invasive, Robotic Surgery, Telemedicine End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Heart Institutes Application: Coronary Artery Disease, Heart Rhythm Disorders, Heart Failure, Peripheral Artery Disease |
| Companies Covered | Siemens Healthineers AG, Edwards Lifesciences Corporation, Abbott Laboratories, Biotronik, Cardinal Health, Medtronic, Boston Scientific Corporation, Advanced Healthcare LLC, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Cardiovascular Devices Market Evolving Landscape
Device manufacturers are converging imaging, robotics, and bioresorbable materials into integrated procedural ecosystems that redefine competitive differentiation beyond standalone product performance.
Bioresorbable vascular scaffolds are hybridizing coronary intervention by combining temporary mechanical support with drug-eluting functionality that dissolves after vessel healing. Cleveland Clinic Abu Dhabi and Dubai Healthcare City cardiac centers are piloting these platforms for selected lesion subsets. This convergence is compressing the traditional stent-to-surgery decision pathway and enabling earlier intervention in diffuse disease.
MOHAP post-market surveillance requirements are tightening traceability mandates for implantable cardiovascular devices across UAE Ministry of Health facilities. Manufacturers must now maintain device-level tracking from import through explant, increasing compliance infrastructure costs. High-volume stent and pacemaker suppliers are responding by deploying serialized inventory management systems aligned with SFDA data standards.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracting models that bundle devices, imaging, and technical support. This disintermediates traditional distributor networks and transfers inventory risk to manufacturers. The shift is most visible among Dubai's private hospital groups, where cath lab operators now negotiate annual spend commitments across entire device portfolios rather than per-procedure purchasing.
UAE Cardiovascular Devices Market Segmentation
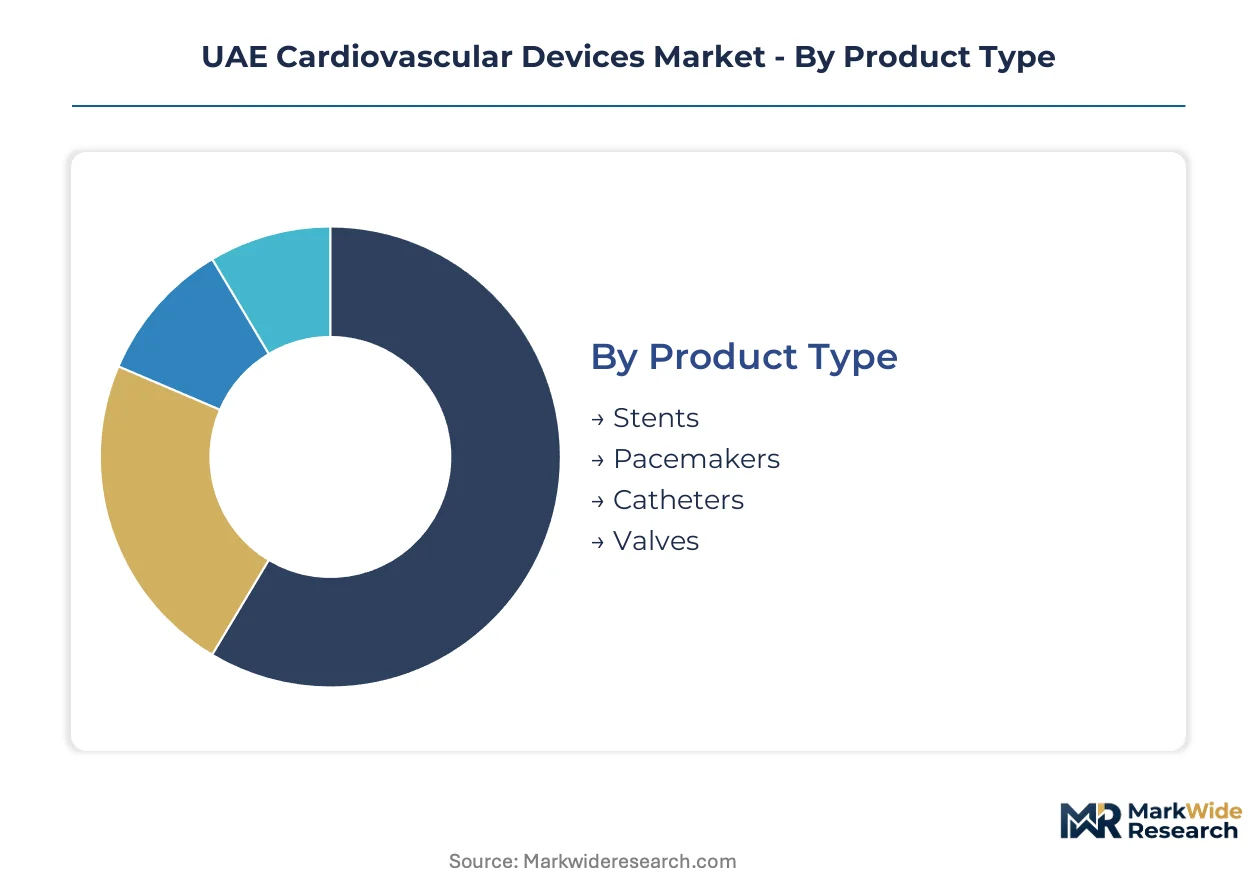
Device segmentation in the UAE cardiovascular market reveals how procurement power concentrates around specific clinical applications and facility tiers. Understanding these splits exposes where manufacturers must anchor technical service capabilities and inventory partnerships to secure long-term contracts.
Product Type:
Cost tier differentiation separates commodity devices from premium implantable platforms requiring specialized alloy feedstocks and localized support infrastructure.
- Stents:Drug-eluting and bare-metal platforms manufactured from cobalt-chromium alloys or nitinol dominate coronary intervention volumes. Demand concentrates in Dubai Healthcare City and Cleveland Clinic Abu Dhabi cath labs where bundled procurement contracts favor suppliers with serialized inventory tracking aligned to MOHAP traceability mandates.
- Pacemakers:Implantable cardiac rhythm management devices featuring lithium-iodine power cells and telemetry connectivity. Medtronic's localized technical service teams in Dubai anchor maintenance contracts with private hospital groups, reducing equipment downtime to under four hours.
- Catheters:Diagnostic and interventional delivery systems for angiography and structural heart procedures.
- Valves:Mechanical and tissue prostheses including transcatheter aortic and mitral replacement platforms.
Stents command the established base. The steepest expansion runs through transcatheter valve platforms displacing open surgical volumes.
Technology:
Application maturity varies sharply across these four technology platforms, with established minimally invasive techniques giving way to robotic and bioresorbable innovations.
- Bioresorbable:Polymer-based vascular scaffolds providing temporary mechanical support before dissolving post-healing. Cleveland Clinic Abu Dhabi pilots these for selected lesion subsets, compressing traditional stent-to-surgery decision pathways in diffuse coronary disease.
- Minimally Invasive:Transcatheter delivery systems for valve replacement and coronary intervention. Tertiary cardiac centers in Dubai Healthcare City drive procedural volume as SFDA-aligned import controls extend approval timelines for novel platforms.
- Robotic Surgery:Computer-assisted surgical platforms for precision cardiac procedures. Specialty heart institutes deploy these systems to differentiate on patient outcomes and reduce length-of-stay metrics.
- Telemedicine:Remote cardiac monitoring and consultation infrastructure connecting Northern Emirates patients to Abu Dhabi and Dubai specialists.
Minimally invasive platforms command the established base. The steepest expansion runs through robotic surgery adoption gaining fastest traction among premium-tier facilities.
End User:
Customer type determines procurement scale, with sovereign-backed networks consolidating vendor relationships around full-procedure contracting models that disintermediate traditional distributors.
- Hospitals:General acute care facilities with cardiac catheterization capabilities. MOHAP facilities and Dubai Health Authority hospitals anchor volume, though procurement committees increasingly bundle devices, imaging, and technical support into annual spend commitments.
- Specialty Heart Institutes:Dedicated cardiac centers with concentrated interventional volume. Dubai Healthcare City and Cleveland Clinic Abu Dhabi expand cath lab capacity, narrowing the competitive field to manufacturers with balance-sheet capacity or sovereign-linked backing.
- Clinics:Outpatient diagnostic and follow-up facilities referring complex cases to tertiary centers.
- Ambulatory Surgical Centers:Same-day procedure facilities handling lower-acuity cardiac interventions.
Hospitals command the established base. The steepest expansion runs through specialty heart institutes capturing complex structural heart referrals.
Application:
Volume concentration in coronary artery disease creates margin pressure, while heart rhythm and structural heart segments capture premium positioning through technical differentiation.
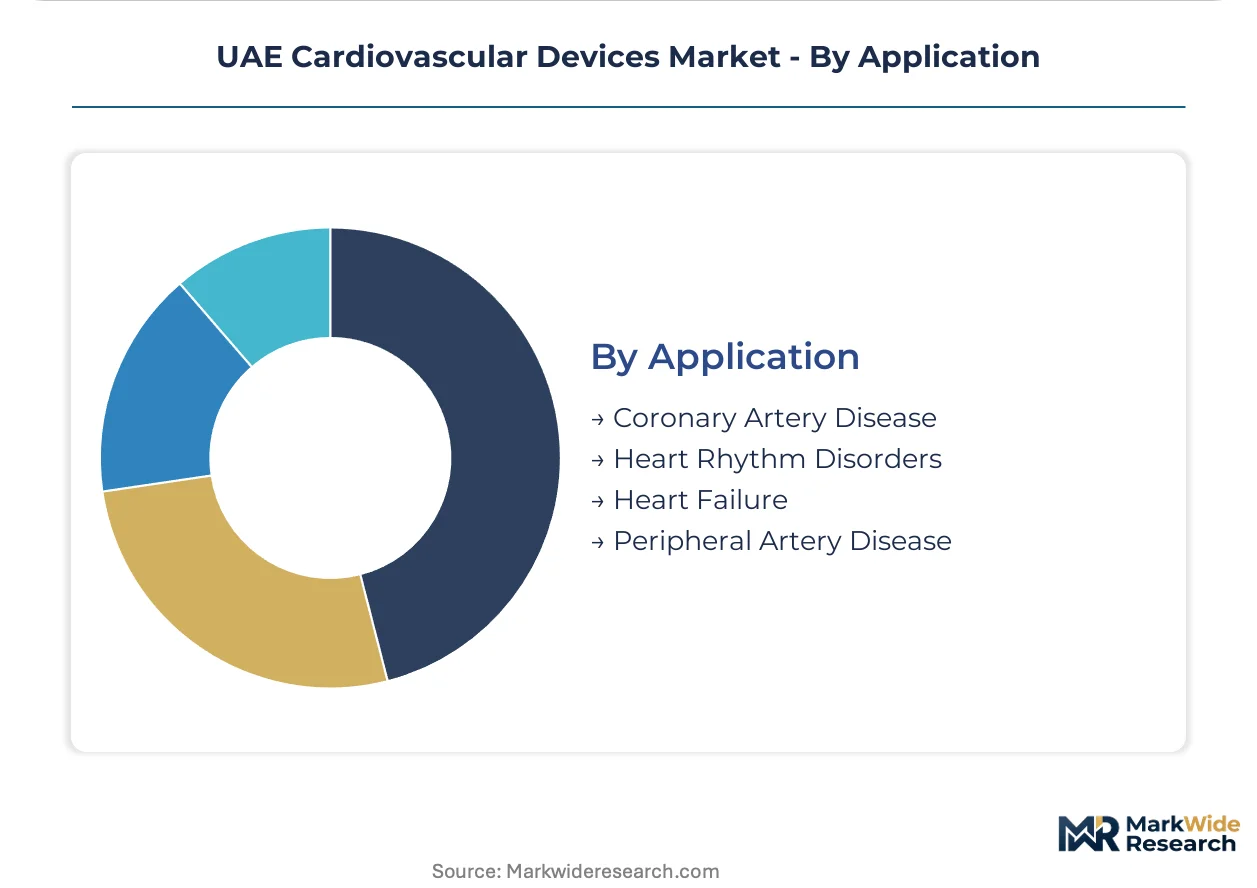
- Coronary Artery Disease:Stent deployment and bypass procedures addressing atherosclerotic vessel narrowing. The most mature revenue pool concentrates procedural volume across Dubai and Abu Dhabi, though open surgical substitution limits transcatheter penetration in complex anatomies.
- Heart Rhythm Disorders:Arrhythmia management through pacemaker implantation and catheter ablation. Localized technical service capabilities reduce equipment downtime and anchor long-term contracts with private hospital groups.
- Heart Failure:Device therapy including cardiac resynchronization and ventricular assist platforms.
- Peripheral Artery Disease:Lower-extremity revascularization using drug-coated balloons and stents.
Coronary artery disease commands the established base. The steepest expansion runs through heart rhythm disorder management as aging demographics and mandatory insurance coverage extend patient access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular device trade flows into the UAE reflect heavy import dependence with limited domestic manufacturing, positioning Dubai and Abu Dhabi as regional distribution hubs serving Gulf Cooperation Council markets through re-export channels.
Dubai
Transcatheter valve replacement procedures concentrate at Dubai Healthcare City cardiac centers where Cleveland Clinic Abu Dhabi affiliates drive structural heart volumes. MOHAP mandatory insurance expansion into Northern Emirates channels patient referrals through Dubai-based tertiary facilities. The Dubai Health Authority accredits catheterization labs under unified procurement frameworks that favor suppliers with localized technical service teams.
Abu Dhabi
Cleveland Clinic Abu Dhabi anchors complex coronary intervention volumes with sovereign-backed capacity expansion across multiple cath lab installations. The Department of Health Abu Dhabi enforces facility licensing standards that determine device reimbursement eligibility. Specialty heart institutes on Al Maryah Island and Al Ain are consolidating vendor relationships around full-procedure contracting models.
Sharjah
General acute care hospitals with cardiac catheterization capabilities serve as referral intermediaries to Dubai and Abu Dhabi tertiary centers. University Hospital Sharjah and private hospital groups are upgrading hemodynamic monitoring infrastructure to capture intermediate-complexity cases. The Sharjah Health Authority coordinates with Dubai Health Authority on cross-emirate patient transfer protocols.
Northern Emirates
Ras Al Khaimah, Fujairah, and Umm Al Quwain facilities represent underpenetrated demand as Dubai's mandatory health insurance framework extends coverage northward. Saqr Hospital and Fujairah Hospital are building diagnostic cardiology capacity with government-funded equipment procurement. Patient referral patterns are shifting as insured populations gain access to interventional procedures previously concentrated in Dubai.
UAE Cardiovascular Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying catheters, stents, and implantable materials to cath lab operators. The vendor base concentrates among multinational manufacturers with UAE technical service infrastructure and inventory partnerships with sovereign-backed hospital networks. Three archetypes dominate: imaging-therapy integrators anchoring premium tenders, cardiac rhythm management specialists with localized maintenance teams, and structural heart platform providers capturing transcatheter valve volumes. Competitive moves center on full-procedure contracting bundles and cath lab infrastructure project finance partnerships.
Among the named manufacturers, Siemens Healthineers AG exemplifies the imaging-therapy integration archetype, Abbott Laboratories occupies a position within catheter and structural heart supply tiers, and Medtronic anchors the cardiac rhythm management segment with technical service localization. These three represent distinct competitive vectors without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Edwards Lifesciences Corporation |
| Abbott Laboratories |
| Biotronik |
| Cardinal Health |
| Medtronic |
| Boston Scientific Corporation |
| Advanced Healthcare LLC |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Cath lab undercapacity across Northern Emirates concentrates procurement leverage with Dubai and Abu Dhabi sovereign-backed hospital networks, compressing margins for mid-tier distributors while amplifying pricing power for manufacturers with localized technical service infrastructure and inventory partnerships.
Pricing Analysis
Sovereign-backed hospital networks anchor a contract-based long-term offtake pricing structure across the UAE cardiovascular devices market. Price differentiation separates premium-tier suppliers with MOHAP-aligned traceability systems and localized service teams from standard-tier distributors lacking inventory partnerships. Cost compression in the stent segment is intensifying because bundled procurement contracts transfer inventory risk to manufacturers. Private hospital groups exhibit the highest price sensitivity, while specialty heart institutes prioritize outcome metrics over unit economics.
Supply Chain Analysis
Extended payment terms from sovereign-backed hospital networks are forcing manufacturers to deploy supply-chain finance facilities or absorb working capital strain. Device manufacturing draws from nitinol and cobalt-chromium alloy feedstock concentrated in the United States, Germany, and Japan, with bioresorbable polymer platforms sourced from specialized European chemical suppliers. Single-source vulnerability in specialty alloy supply exposes device makers to input cost volatility. Distribution runs through Dubai's re-export hubs serving Gulf Cooperation Council markets, with customs clearance aligned to SFDA import control protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE cardiovascular devices market functions as a defensive-moat environment where regulatory entrenchment through MOHAP facility accreditation and SFDA-aligned traceability mandates creates substantial switching costs for hospital procurement committees.
For Market Incumbents: Entrench market position by deepening technical service localization in Dubai and Abu Dhabi to capture cath lab infrastructure expansion contracts. Anchor long-term vendor relationships through full-procedure bundling that disintermediates traditional distributor networks. The emerging threat of robotic surgery platform entrants demands preemptive imaging-therapy integration investments. Backward integration into serialized inventory management systems represents the critical defensive lever against compliance cost escalation.
For New Entrants and Emerging Players: Establish a beachhead in Northern Emirates diagnostic cardiology capacity buildout as Dubai's mandatory insurance expansion channels patient referrals northward. Target Saqr Hospital and Fujairah Hospital procurement committees with government-funded equipment financing partnerships. The most penetrable segment lies in telemedicine infrastructure connecting Northern Emirates patients to Dubai and Abu Dhabi specialists. A direct hospital system partnership go-to-market model bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across transcatheter valve platform development as SFDA-aligned approval timelines extend R&D investment horizons. The five-to-ten year viability window favors manufacturers with sovereign-linked balance sheet capacity or project finance partnerships for cath lab infrastructure. Acquisition targets should display localized technical service teams and MOHAP-aligned compliance infrastructure. The signal to monitor is Dubai Health Authority procurement committee consolidation around annual spend commitment models.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Traceability Compliance Investment | Serialized inventory systems satisfy post-market surveillance mandates across Ministry of Health facilities. |
| Cath Lab Infrastructure Partnership | Project finance alignment with sovereign-backed networks secures multi-year device procurement commitments. |
| Imaging-Therapy Platform Integration | Convergence of intravascular imaging with interventional systems enables premium tender positioning. |
| Technical Service Team Localization | On-site cardiac rhythm management support reduces equipment downtime below four-hour thresholds. |
| Northern Emirates Coverage Expansion | Mandatory insurance extension into Ras Al Khaimah and Fujairah redirects patient referral patterns. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, hospital procurement committee members, biomedical engineers, and cath lab operations directors. Secondary validation drew from MOHAP facility accreditation databases, Dubai Health Authority procurement records, SFDA import registration filings, and Cleveland Clinic Abu Dhabi procedural volume disclosures. Bottom-up device shipment analysis was triangulated against top-down healthcare expenditure tracking across the projection horizon.
Calibration against historical procedural volume trends and mandatory insurance enrollment data anchored the analytical framework. Segmentation dimensions modeled included product type, technology platform, end-user facility tier, and clinical application severity across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating aging demographic projections and cath lab capacity expansion schedules. Forecast inputs incorporated SFDA approval timeline assumptions and alloy feedstock price volatility indices.
Stress conditions across SFDA regulatory stringency, nitinol supply disruption, and Northern Emirates insurance penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MOHAP facility accreditation pace and sovereign-backed hospital network consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Blood Fluid Warming System Market